
 Isophorone Market | 2026-2036
Isophorone Market Size, Share, and Industry Trends Forecast 2026-2036
Isophorone Market Intelligence
The unbundling of isophorone from pre-formulated solvent packages is broadening access for specialized formulators in the coatings industry. This shift allows for greater customization in end-products. Evonik Industries leverages its significant manufacturing scale to serve high-volume accounts. In contrast, Arkema Group competes by offering a portfolio of specialty chemical solutions, including isophorone derivatives for niche applications.
Isophorone is a cyclic ketone, chemically known as 3,5,5-trimethyl-2-cyclohexen-1-one, characterized by its high boiling point and slow evaporation rate. It primarily functions as a powerful solvent for resins, polymers, and other organic materials. Its application as a solvent in paints and coatings represents the largest consumption segment. The use of isophorone as a chemical intermediate for producing derivatives like isophorone diamine (IPDA) is a critical, high-value application in the chemical industry.
The market operates under strict environmental and safety regulations. The European Union's REACH legislation governs the registration and use of chemical substances, while the EPA in the United States sets limits on volatile organic compounds (VOCs) in coatings. These frameworks compel manufacturers to develop compliant formulations. Stakeholders must therefore navigate the challenge of maintaining product performance while adhering to increasingly stringent global environmental standards.
Market Dynamics
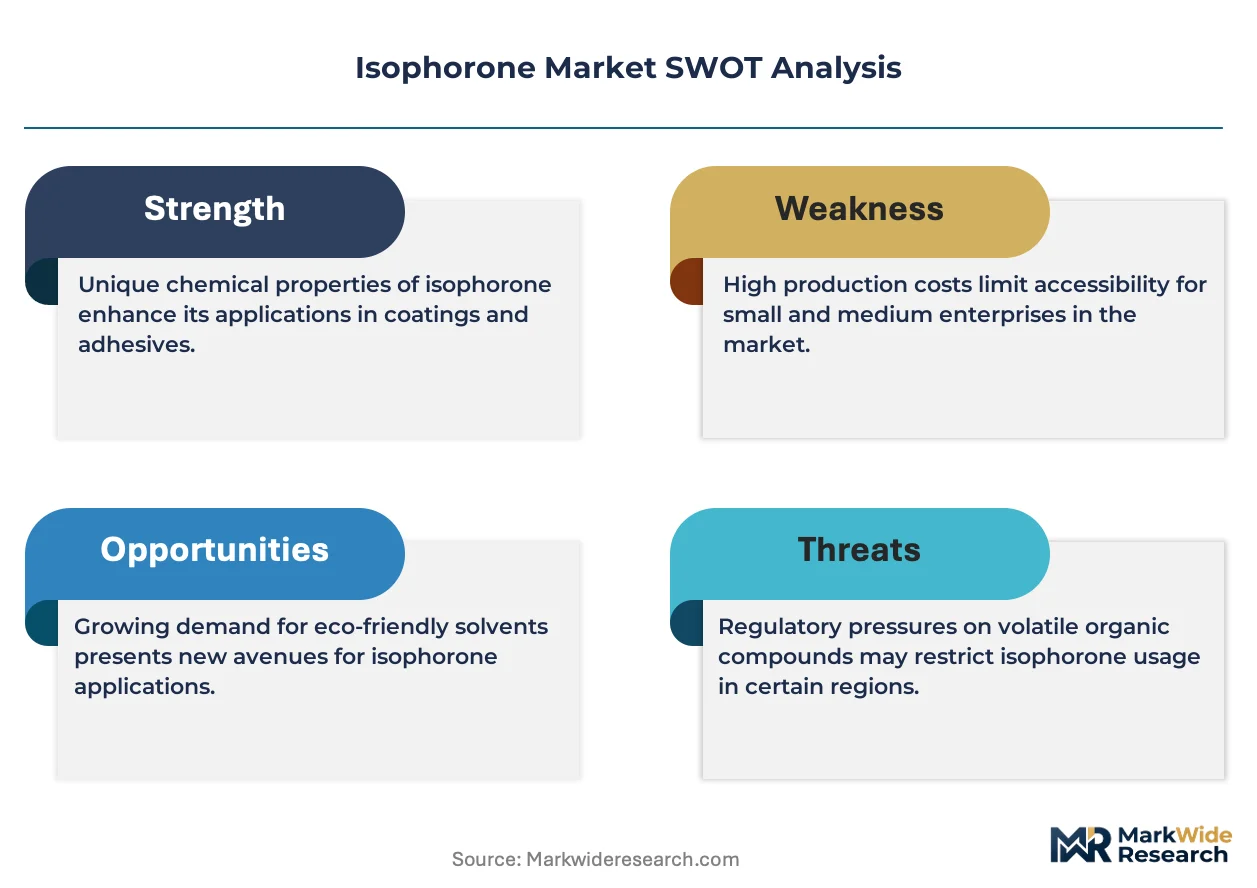
The isophorone market is fundamentally shaped by the tension between stringent global environmental regulations and the unyielding performance requirements of advanced industrial applications. This dynamic forces a continuous cycle of reformulation and innovation, particularly within the high-value coatings and composites sectors where isophorone's unique solvent properties are critical.
Growth Catalysts
- Automotive Coatings Demand:The automotive industry's need for high-performance, durable, and weather-resistant coatings for OEM and refinish applications directly propels isophorone consumption. Its slow evaporation rate is essential for achieving flawless, high-gloss finishes.
- Chinese Industrial Expansion:China's large-scale chemical manufacturing base and extensive construction projects create sustained, high-volume demand. Isophorone and its derivatives are integral inputs for paints, adhesives, and composite materials used in this expansion.
- Isophorone Derivative Growth:The expanding use of isophorone diamine (IPDA) and isophorone diisocyanate (IPDI) as chemical intermediates is a significant catalyst. These derivatives are crucial for producing high-performance epoxy curing agents and polyurethane coatings.
Market Restraints
- Regulatory Pressure on VOCs:Regulations such as the European Union's REACH framework and the EPA's limits on volatile organic compounds (VOCs) in the United States create compliance hurdles. This pressure compels formulators to seek lower-VOC alternatives, constraining market expansion.
- Threat from Substitute Solvents:The development of alternative, bio-based, or less toxic solvents presents a persistent substitution risk. While these alternatives may not match isophorone's performance, they gain traction in less demanding applications or where environmental branding is key.
- Raw Material Price Volatility:Isophorone production is dependent on acetone, a petrochemical derivative. Fluctuations in crude oil and propylene prices translate directly into cost volatility for isophorone manufacturers, impacting pricing stability and margins.
Strategic Opportunities
- Renewable Energy Sector:The use of isophorone diamine (IPDA) in epoxy resins for manufacturing large, durable wind turbine blades represents a significant opportunity. This aligns production with the global expansion of renewable energy infrastructure.
- High-Solids and Waterborne Formulations:Stricter VOC regulations create an opportunity for isophorone as a coalescing agent in advanced waterborne coatings or as a reactive diluent in high-solids systems, enabling compliance without sacrificing performance.
- Industrialization in Southeast Asia:Growing manufacturing and construction activities in countries like Vietnam and Indonesia offer new geographic markets for isophorone. These regions require the high-performance materials for which isophorone is a key ingredient.
Industry Challenges
- High Capital Investment:The construction of new isophorone production plants requires substantial capital expenditure and long lead times. This high barrier to entry concentrates production among a few major players and can lead to supply tightness.
- Complex Reformulation Cycles:Adapting coatings and resin formulations to meet evolving environmental standards across multiple jurisdictions is a complex and resource-intensive process. Manufacturers face the challenge of maintaining product performance while ensuring compliance.
- Logistical and Supply Chain Complexity:The geographic concentration of isophorone production facilities creates significant logistical challenges. End-users are vulnerable to supply chain disruptions, requiring sophisticated inventory management and risk mitigation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isophorone Market |
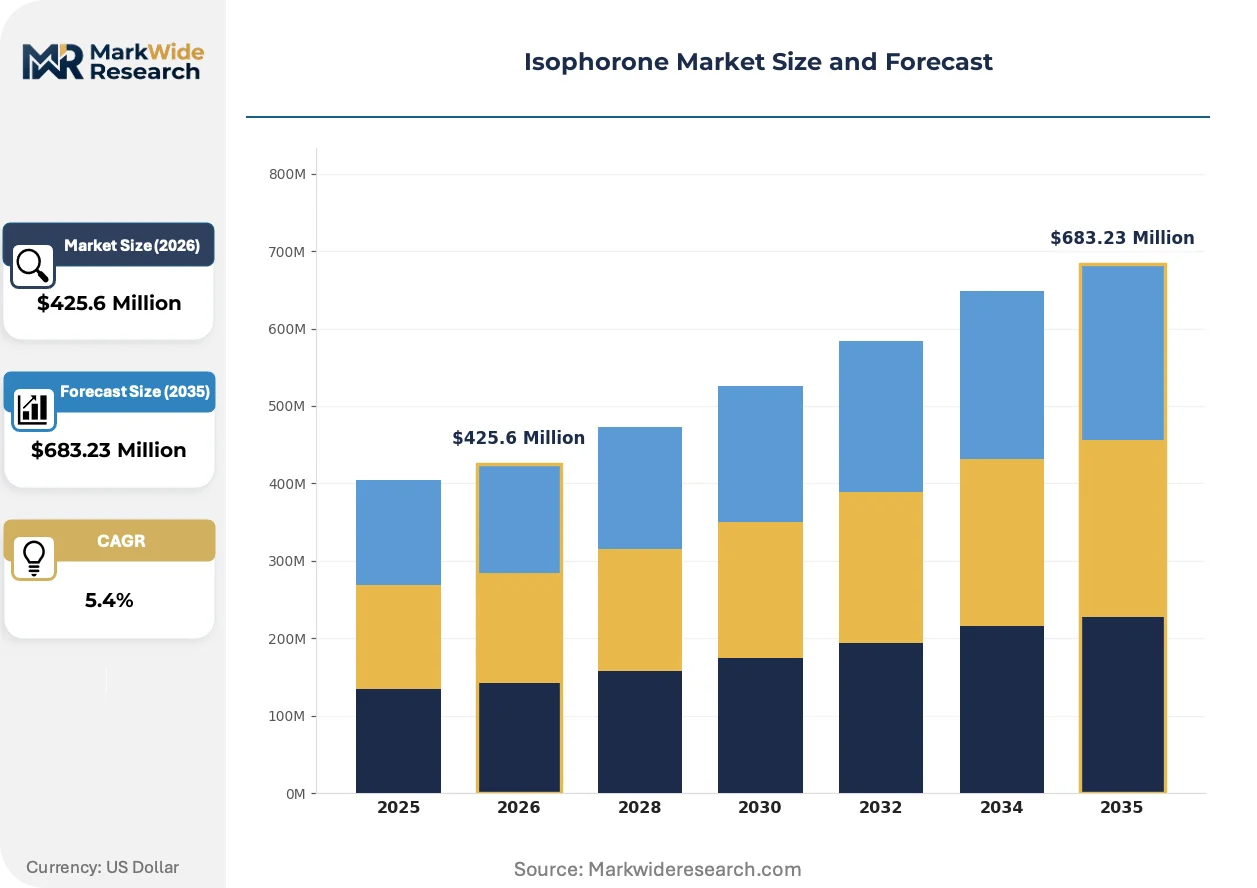
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $683.23 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Coating Agent, Adhesive Application: Paints, Inks, Coatings, Plastics End User: Chemical Industry, Automotive, Construction, Electronics Form: Liquid, Solid, Powder, Paste |
| Companies Covered | Merck KGaA, Covestro AG, Evonik Industries, Jiangsu Huanxin High Tech Materials Co. Ltd, CHAIN FONG, Arkema Group, SI Group Inc., Prasol Chemicals Pvt Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isophorone Market Strategic Shifts & Innovations
A dual focus on process efficiency and sustainable chemistry is defining the next phase of the isophorone market. Innovations are geared towards reducing environmental footprints, optimizing resource utilization, and developing higher-value derivative applications that meet stringent performance and regulatory criteria.
Advanced process control (APC) systems represent a critical technological evolution in isophorone synthesis. Chemical manufacturers are increasingly adopting these systems to precisely manage reaction conditions like temperature and pressure in real time. This technology is automating the continuous adjustment of process parameters, which optimizes feedstock conversion, minimizes byproduct formation, and ensures consistent product quality.
China's national environmental policies, including its "dual carbon" targets and stricter MEE standards on industrial emissions, are impacting production. This regulatory push compels manufacturers to invest in cleaner production methods and more efficient solvent recovery technologies. The coatings industry is most affected, which is accelerating the development of compliant high-solids formulations where isophorone's properties are highly valued.
A notable behavioral shift involves formulators moving away from pre-blended solvent packages to directly sourcing individual chemical components. This change allows sophisticated buyers in the coatings and adhesives industries to gain precise control over their product formulations and intellectual property. The trend is most visible within the automotive OEM coatings sector in Europe, where customization and performance optimization are paramount.
Isophorone Market Segmentation
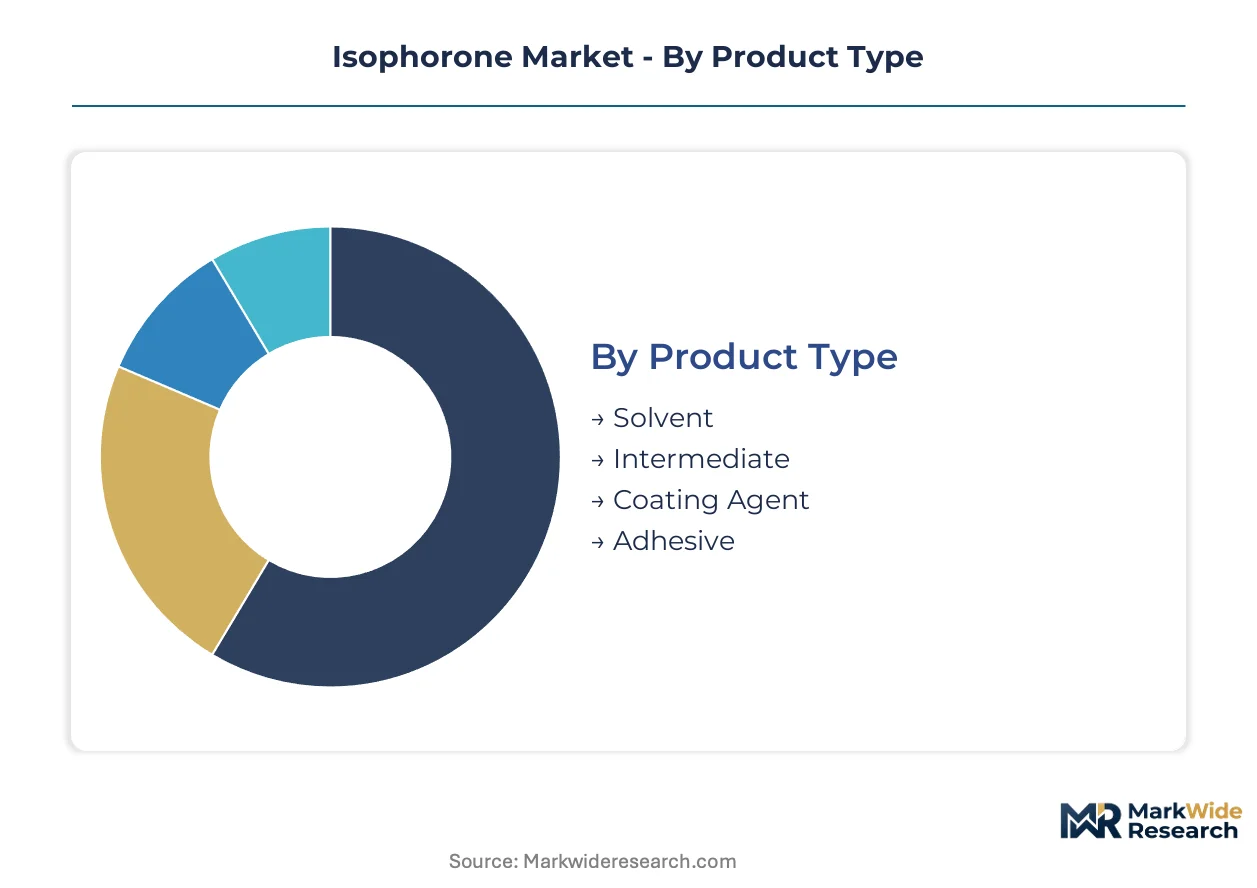
The Isophorone market segmentation reflects the diverse end-use requirements and technical specifications demanded by various industries. Understanding these distinct segments helps manufacturers tailor product offerings and optimize distribution channels for specific applications.
Product Type:
Buyers in this category differentiate based on whether they require isophorone for its solvent properties or as a chemical building block for further synthesis.
- Solvent:This form of isophorone is widely used for its high boiling point and slow evaporation rate, making it an excellent solvent for resins and polymers. Demand concentrates in the automotive industry for high-performance coatings, ensuring flawless, high-gloss finishes.
- Intermediate:Isophorone serves as a critical chemical intermediate for producing high-value derivatives such as isophorone diamine (IPDA) and isophorone diisocyanate (IPDI). This application is crucial for manufacturing high-performance epoxy curing agents and advanced polyurethane coatings in the chemical industry.
- Coating Agent:This segment utilizes isophorone to enhance film formation, flow, and leveling properties in various coating formulations.
- Adhesive:Isophorone improves the performance characteristics of adhesives, contributing to better bond strength and flexibility in specialized formulations.
Volume sits with Solvent; growth tilts toward Intermediate.
Application:
Specific performance requirements and end-product characteristics drive the selection within application segments.
- Coatings:Isophorone is essential for formulating high-performance, durable, and weather-resistant coatings, particularly for industrial and automotive OEM and refinish applications. Its slow evaporation rate is critical for achieving superior surface aesthetics.
- Paints:Functions primarily as a powerful solvent for resins and binders in various paint formulations, contributing to improved film properties and application characteristics. This segment supports both decorative and protective paint systems.
- Inks:Isophorone aids in pigment dispersion and controls drying times in specialized printing ink formulations.
- Plastics:It serves as a processing aid or a component in certain plastic formulations, influencing material properties.
The automotive sector drives demand for Coatings; Plastics applications show expanding potential.
End User:
End-user segments differentiate by their specific material performance demands and scale of consumption.
- Automotive:This industry requires isophorone for its role in high-performance, durable, and aesthetic coatings for vehicle bodies and components. OEM and refinish applications demand its unique solvent properties.
- Chemical Industry:This segment consumes isophorone primarily as a feedstock for synthesizing high-value derivatives like IPDA and IPDI, which are crucial for advanced polymer production.
- Construction:Isophorone finds use in paints, adhesives, and sealants applied in building and infrastructure projects.
- Electronics:Specialized coatings and resins containing isophorone protect sensitive electronic components.
Automotive applications dictate premium formulations; the Chemical Industry drives derivative innovation.
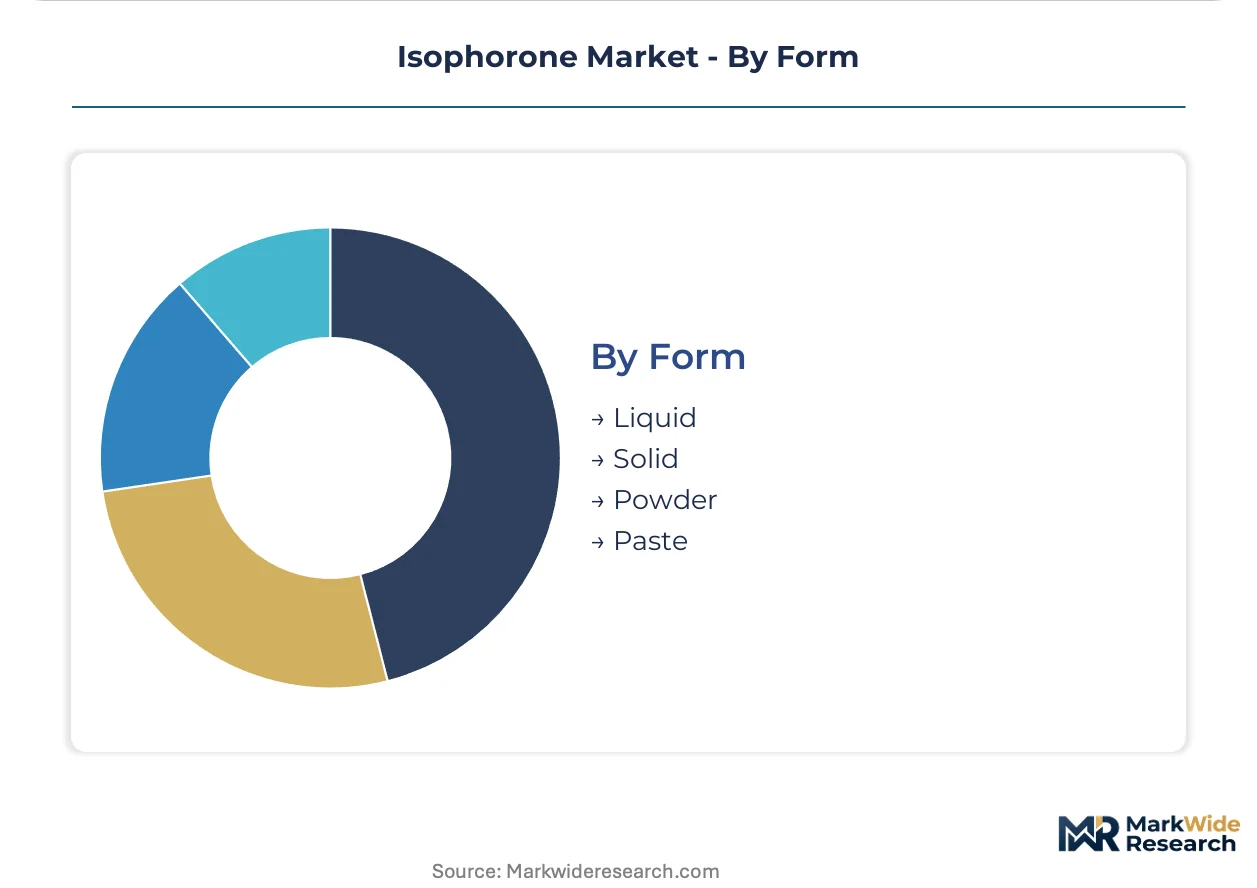
Form:
The physical state of isophorone dictates its handling, storage, and integration into manufacturing processes.
- Liquid:This is the predominant physical form of isophorone, offering ease of handling, blending, and dispersion in solvent-based and high-solids formulations. It is critical for many coating and adhesive applications.
- Solid:Isophorone in solid form is utilized in niche applications or as a precursor for specific chemical reactions where a solid reactant is preferred. This form offers specific handling and storage benefits.
- Powder:This form is employed in specialized applications requiring dry blending or specific dispersion characteristics.
- Paste:Used in formulations that demand a semi-solid consistency for controlled application and specific rheological properties.
Liquid remains the dominant form; specialized Paste formulations are gaining traction for specific uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global isophorone market exhibits a clear divide between established production hubs and rapidly industrializing consumption regions. While manufacturing capacity concentrates in specific chemical-intensive geographies, demand centers are increasingly dispersed, particularly across Asia.
China
China's extensive chemical manufacturing base and vast construction sector drive significant isophorone consumption. The country's MEE standards and "dual carbon" targets compel manufacturers to adopt cleaner production methods. Industrial clusters in the Yangtze River Delta continue to expand, increasing demand for high-performance coatings and adhesives.
Germany
German automotive and chemical industries rely on isophorone for high-performance coatings and derivative production. The European Union's REACH framework heavily influences solvent choices, pushing for compliant formulations. Chemical parks in the Rhine-Main region remain central to the development and production of specialized isophorone derivatives.
United States
United States demand stems from its automotive OEM and refinish sectors, alongside a robust chemical industry producing isophorone derivatives. EPA limits on volatile organic compounds (VOCs) steer formulation trends toward high-solids and waterborne systems. The US Gulf Coast region serves as a major hub for petrochemical production and chemical synthesis.
India
India's expanding industrialization and construction activities generate sustained demand for paints, coatings, and adhesives containing isophorone. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical products, impacting market entry. Gujarat's chemical industrial zones are witnessing increased investment in materials for infrastructure development.
Isophorone Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for isophorone. Major chemical producers leverage their integrated value chains, while smaller firms often target niche applications with specialized derivatives. Strategic partnerships and capacity expansions are common competitive moves.
Large chemical corporations such as Evonik Industries and BASF SE anchor the market, commanding significant production scale and broad product portfolios. Arkema Group, a French multinational, occupies a position among specialty chemical providers, offering isophorone derivatives that cater to specific performance requirements in advanced materials. These companies represent the established players with extensive global distribution networks.
| Leading Market Players |
|---|
| Merck KGaA |
| Covestro AG |
| Evonik Industries |
| Jiangsu Huanxin High Tech Materials Co. Ltd |
| CHAIN FONG |
| Arkema Group |
| SI Group Inc. |
| Prasol Chemicals Pvt Ltd |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Large, integrated chemical conglomerates like Evonik and BASF dictate isophorone supply behavior and pricing discipline. Their substantial capital investments in new production plants reinforce market control.
Pricing Analysis
Cost-down pressure on general industrial and construction applications accelerates because of persistent raw material price volatility. The market primarily operates on a hybrid pricing model, combining long-term contracts for large-volume buyers with spot pricing for smaller or immediate needs. Price differentiation stems from product purity, regulatory compliance (REACH/EPA), and volume scale. Automotive OEM buyers exhibit the least price sensitivity due to stringent performance requirements for coatings.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model manage the flow of isophorone from concentrated production sites to diverse end-users. Global supply concentrates in China, Germany, and the United States, creating significant logistical complexity. Production heavily relies on acetone, a petrochemical derivative, exposing the supply chain to commodity price volatility. This geographic concentration also creates single-source vulnerability for end-users, requiring sophisticated inventory management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Isophorone market presents a supply-constrained narrative, primarily driven by the substantial capital expenditure and long lead times required for new production capacity. This bottleneck effectively props up current pricing levels.
For Market Incumbents:To counter escalating regulatory pressure on volatile organic compounds, incumbents must prioritize investment in R&D for high-solids and waterborne formulations. Expanding production capacity in strategic regions like Southeast Asia can mitigate supply chain risks and capture new demand. Securing long-term supply agreements for acetone can buffer against raw material price volatility. This dual strategy reinforces market leadership and compliance.
For New Entrants and Emerging Players:Advanced process control systems offer a technology-first wedge for new entrants to optimize synthesis and reduce environmental footprints. Targeting niche applications for isophorone derivatives, such as IPDA in renewable energy sectors, provides higher-value market entry. Focusing on industrializing Southeast Asian markets, like Vietnam and Indonesia, offers significant underpenetrated geographic opportunities. Customized formulations for specific performance requirements can differentiate offerings.
For Investors and Strategic Acquirers:New capacity announcements from major producers is the leading indicator that supply-demand dynamics are shifting, signaling potential M&A opportunities. The market exhibits long-term viability over the next 5-10 years due to sustained demand for high-performance coatings and derivatives. Acquisition targets should prioritize specialty chemical firms with proprietary compliant formulations or strong positions in high-growth derivative markets like IPDA. Watch for increased investment in bio-based alternatives as a disruptive signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | This initiative addresses supply constraints and meets the growing demand from China and Southeast Asian industrialization. |
| Green Manufacturing Process Adoption | This shift enables compliance with stringent environmental policies like China's MEE standards and EU REACH regulations. |
| Long-term Acetone Supply Agreements | These agreements mitigate raw material price volatility, ensuring stable production costs for isophorone manufacturers. |
| Joint Venture for IPDA Production | This move allows for shared R&D costs and market access for high-value isophorone diamine derivatives in new applications. |
| Investment in High-Solids Formulations | This R&D focuses on developing compliant coatings that meet EPA VOC limits without sacrificing performance. |
Research Approach
Multi-period observation of isophorone production volumes, regulatory shifts, and patent filings anchored the trend analysis, supplemented by interviews. Primary discussions involved plant managers, OEM procurement leads, R&D directors, and environmental compliance officers. Secondary validation drew from chemical industry reports, customs trade data, and EU REACH and EPA filings. A bottom-up and top-down triangulation ensured data consistency.
Segment-weighting across product type, application, end user, form, and regional production hubs informed the analytical framework over the projection horizon. Isophorone market CAGRs were derived by integrating historical growth trends with forward-looking projections. Key industry-specific forecast inputs included automotive production forecasts and construction spending projections in major consuming regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or geopolitical instability. Projections reflect assumptions regarding raw material supply stability and sustained industrialization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Zinc L-Pidolate Market