
 Lauramide DEA Market | 2026-2036
Lauramide DEA Market Size, Share, and Industry Trends Forecast 2026-2036
Lauramide DEA Market Analytics
The Lauramide DEA market is recalibrating around a widening split between premium cosmetic-grade specifications with low free-amine certification and commodity industrial grades competing on bulk pricing. BASF leverages its integrated ethylene oxide chain to control input costs for high-purity output. Stepan anchors North American supply through dedicated amides capacity at its Winder facility. Colonial Chemical differentiates via custom ester-amide blends for sulfate-free personal care lines.
Lauramide DEA is a fatty acid diethanolamide condensate derived from lauric acid, typically exhibiting 80-95% amide content with controlled free diethanolamine below regulatory thresholds, functioning primarily as a viscosity builder, foam stabilizer, and emulsifier in aqueous surfactant systems. Liquid grades dominate volume flows into industrial cleaning and chemical manufacturing channels where handling efficiency outweighs concentrate premiums. Powder and gel formats capture margin pools in cosmetics and pharmaceuticals where formulation precision and preservative-free claims command price premiums. Emulsion variants represent the fastest-growing format as cold-process personal care manufacturing expands.
EU REACH restrictions on free diethanolamine content and California Proposition 65 listing requirements are reshaping product specifications and testing protocols across export-oriented producers. FDA cosmetic ingredient review processes and EPA industrial chemical reporting obligations add compliance layers for US-market suppliers. Stakeholders must monitor evolving state-level chemical disclosure mandates and surfactant biodegradability certifications to preserve market access.
Market Dynamics
EU REACH restrictions on free diethanolamine content are forcing a bifurcation between certified cosmetic-grade and uncertified industrial-grade Lauramide DEA supply chains, compressing margins for producers lacking purification capabilities while rewarding integrated manufacturers with captive ethylene oxide supply.
Growth Catalysts
- Sulfate-free personal care formulations:Formulators in Germany and France specify low-amine Lauramide DEA as a foam stabilizer in mild surfactant systems, pulling volume from traditional SLES-dependent products.
- REACH-compliant certification pipelines:ECHA registration deadlines for diethanolamide derivatives are accelerating replacement of non-compliant imports with EU-manufactured certified grades.
- Cold-process emulsion manufacturing:Personal care producers in South Korea and Japan are adopting ambient-temperature production methods that favor pre-dispersed Lauramide DEA emulsions over conventional solid grades.
Market Restraints
- Ethylene oxide feedstock volatility:Integrated producers with captive ethylene oxide supply command cost advantages that non-integrated amide specialists cannot replicate.
- Substitution by cocamidopropyl betaines:Mild amphoteric surfactants are displacing Lauramide DEA in premium baby care and sensitive-skin segments where amine-free claims carry marketing weight.
- REACH authorization bottlenecks:ECHA scrutiny of diethanolamine impurities is extending lead times for new supplier qualification beyond 18 months.
Strategic Opportunities
- Pharmaceutical-grade certification:USP-grade Lauramide DEA for topical drug delivery remains underpenetrated, with only two European suppliers holding current Drug Master Files.
- Biodegradable industrial cleaners:EU Ecolabel criteria for surfactant biodegradability are creating specification pull for high-purity Lauramide DEA in professional cleaning concentrates.
- Direct-to-compounder distribution:Specialty chemical distributors are building cold-chain logistics for temperature-sensitive emulsion grades, bypassing traditional bulk tanker economics.
Industry Challenges
- Analytical chemistry talent scarcity:Free-amine testing to REACH thresholds below 0.5% requires GC-MS expertise that contract laboratories struggle to staff.
- Multi-jurisdiction registration costs:Simultaneous FDA cosmetic ingredient filing, EPA TSCA notification, and REACH registration is consuming 12-15% of R&D budgets for mid-sized producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauramide DEA Market |
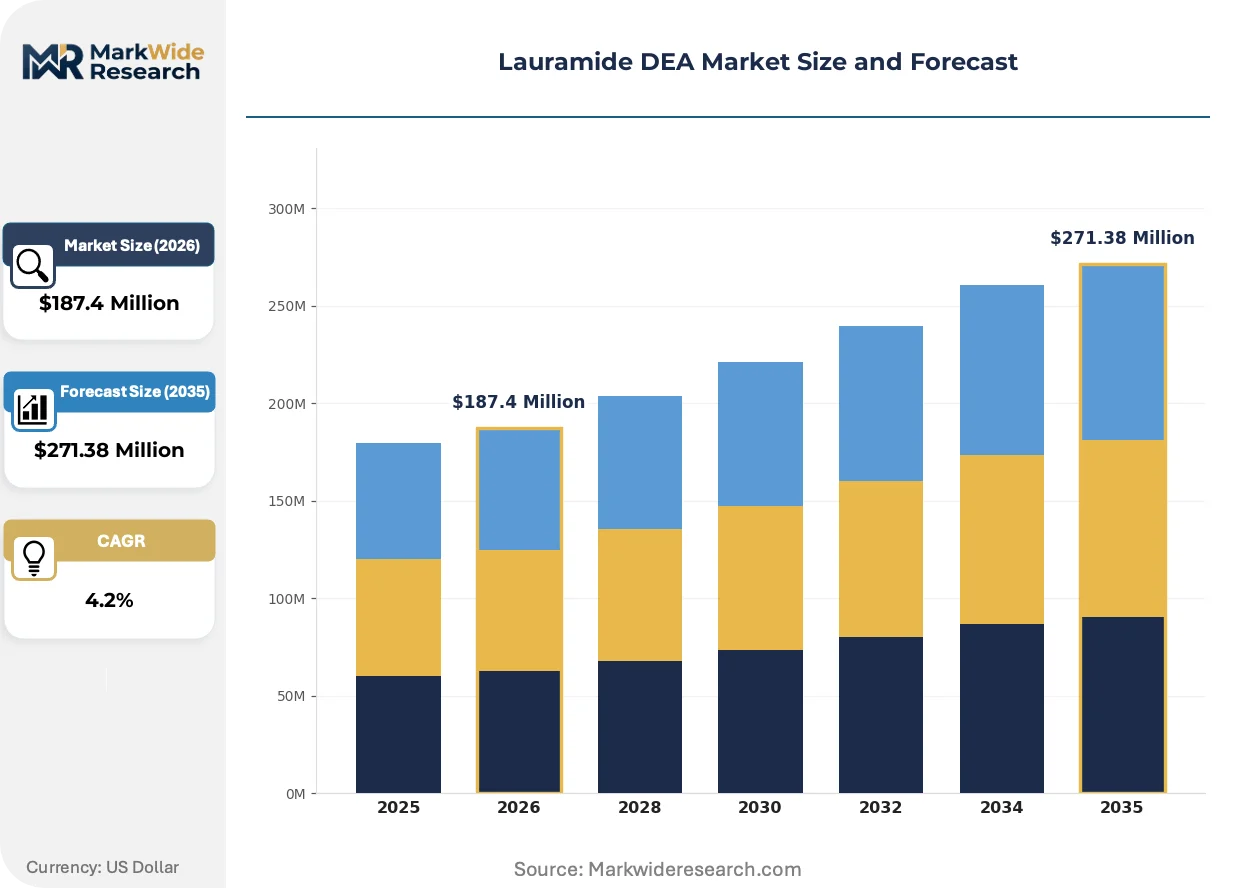
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Powder, Emulsion Application: Cosmetics, Pharmaceuticals, Industrial Cleaning, Agricultural Chemicals End User: Personal Care, Healthcare, Chemical Manufacturing, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | McKinley Resources, Jeen International, Fine Organics, Stepan, Solvay, BASF, Colonial Chemical, Protameen Chemicals, Hydrior, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauramide DEA Market Evolving Landscape
Cold-process manufacturing methods and tightening contaminant thresholds are rewriting formulation protocols across personal care and industrial cleaning segments. Producers must now integrate precision analytical capabilities with flexible emulsion delivery systems.
Enzymatic amidation catalysts are rewriting process economics for high-purity Lauramide DEA production. Specialty chemical manufacturers in Germany and the Netherlands are piloting lipase-catalyzed routes that operate at 40-60°C versus conventional 160-180°C thermal condensation. The lower-temperature pathway is enabling cosmetic-grade output from smaller batch vessels, compressing capital requirements for regional producers.
ECHA's 2023 update to REACH Annex XVII restrictions on diethanolamine content in cosmetic products is forcing reformulation across rinse-off personal care. The regulation mandates free amine levels below 0.5% in finished formulations, requiring suppliers to implement additional distillation steps or molecular sieving. German and French formulators are responding by consolidating supplier bases around integrated producers with certified low-amine output.
Specification-driven procurement is consolidating buyer-seller relationships in European personal care. Compounders are shifting from spot purchasing of commodity amide grades toward multi-year supply agreements with embedded quality certification and audit rights. This behavioral shift is most visible in Germany's specialty chemical corridor, where BASF and Solvay have captured preferred-supplier status with major cosmetic houses through integrated REACH compliance packages.
Lauramide DEA Market Segmentation
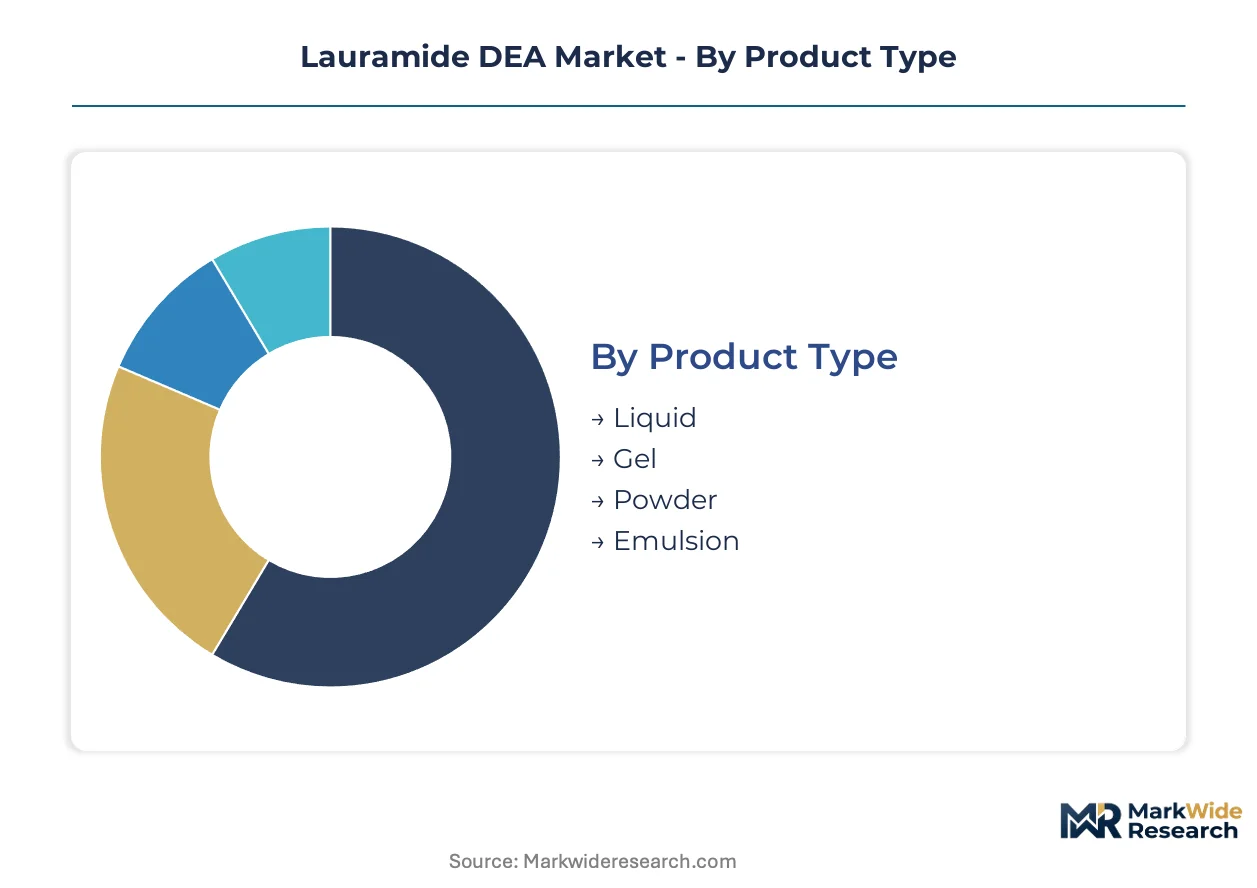
Lauramide DEA's physical form, regulatory certification grade, and delivery logistics create distinct margin pools that suppliers must navigate. Each segment carries unique handling requirements, purity thresholds, and customer consolidation patterns that reshape competitive positioning.
Product Type:
Supply concentration favors formats with established cold-chain infrastructure and batch certification capabilities.
- Liquid:Standard 80-95% amide content solutions dominate industrial cleaning and bulk chemical manufacturing channels in Germany and the Netherlands. Tanker-scale logistics and minimal handling costs preserve margins in commodity applications where REACH certification is not mandatory.
- Emulsion:Pre-dispersed aqueous systems enable cold-process personal care manufacturing in South Korea and Japan, bypassing traditional heating steps. Ambient-temperature stability requirements favor regional producers with short distribution radius.
- Gel:Thickened concentrates serve sulfate-free shampoo formulators seeking precise viscosity control without heating equipment. Compact shipping volumes offset higher unit costs for mid-scale compounders.
- Powder:Spray-dried grades with sub-0.5% free diethanolamine certification command premium positioning in pharmaceutical and cosmetic applications. Moisture-sensitive handling limits supplier base to integrated producers with inert-atmosphere packaging lines.
Today's leader: Liquid. Tomorrow's challenger: Emulsion.
Application:
Margin tiering separates certification-intensive segments from price-driven bulk categories.
- Cosmetics:Rinse-off and leave-on personal care formulations in France and Germany specify low-amine certification under ECHA Annex XVII. Ecolabel and preservative-free claims pull volume toward emulsion and powder grades with documented purity chains.
- Industrial Cleaning:Professional concentrates and institutional detergents in the United States prioritize foam stabilization and viscosity building over contaminant thresholds. Bulk liquid procurement through distributors dominates this cost-sensitive tier.
- Pharmaceuticals:Topical drug delivery systems require USP-grade certification with Drug Master File documentation. Only two European suppliers currently serve this underpenetrated segment.
- Agricultural Chemicals:Pesticide emulsifiers and adjuvants utilize standard-grade liquid Lauramide DEA for dispersion stability. Seasonal demand patterns and tank-mix compatibility drive specification rather than purity certification.
Cosmetics anchors current value capture. Pharmaceuticals offers the steepest expansion trajectory for certified suppliers.
End User:
Customer type determines procurement rhythm, contract structure, and technical service intensity.
- Personal Care:Cosmetic houses and contract manufacturers in Germany's specialty chemical corridor consolidate supply bases around integrated producers offering REACH compliance packages and audit rights. Multi-year agreements with embedded certification replace spot purchasing.
- Chemical Manufacturing:Surfactant blenders and industrial compounders prioritize feedstock cost stability and tanker-scale delivery reliability. Captive ethylene oxide supply at supplier level translates to pricing leverage in negotiations.
- Healthcare:Hospital formulary and topical drug manufacturers demand pharmaceutical-grade documentation with batch-specific CoA chains. Regulatory filing support consumes disproportionate supplier resources relative to volume.
- Agriculture:Pesticide formulators and adjuvant suppliers operate on growing-season procurement cycles with limited inventory carry. Specification flexibility and rapid sample turnaround outweigh long-term contract structures.
Personal Care commands supplier attention today. Healthcare represents the certification-intensive frontier.
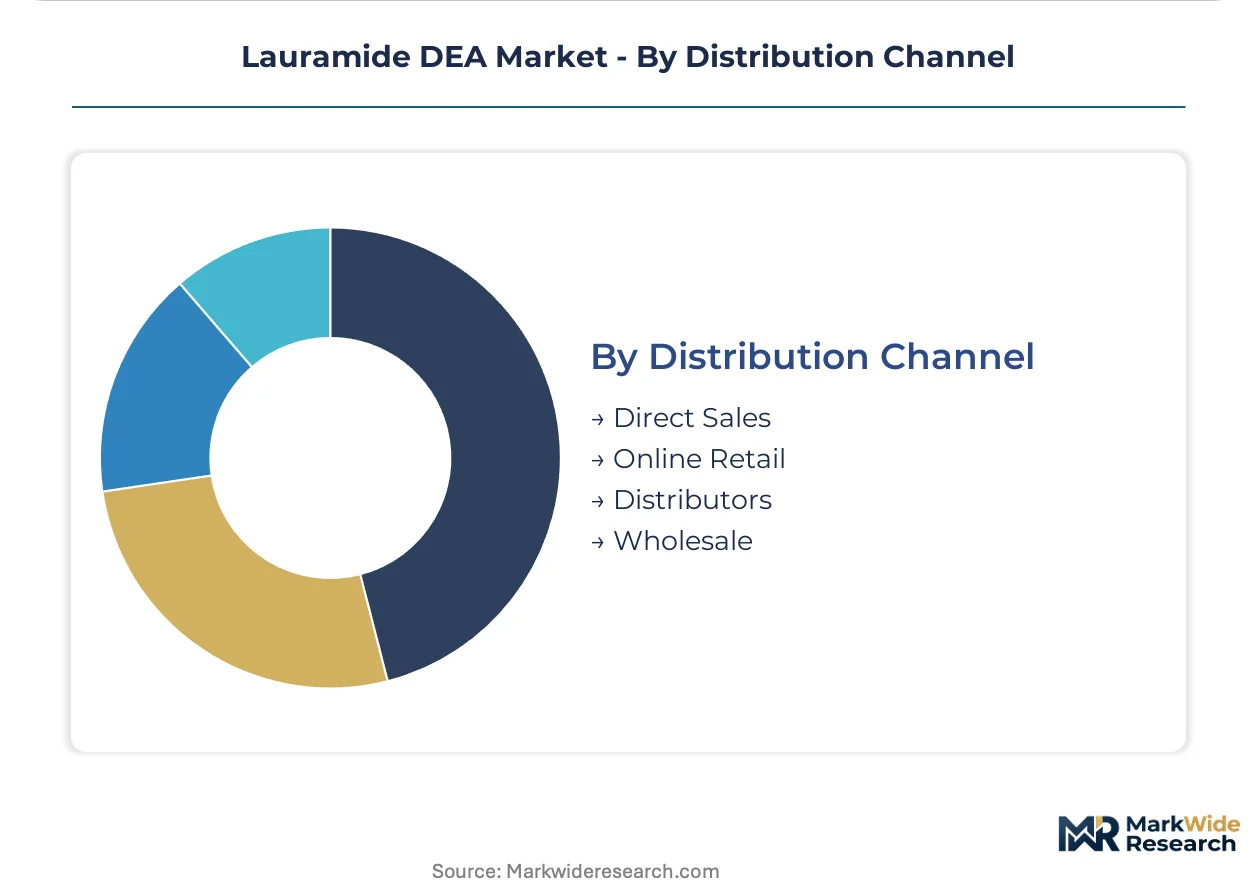
Distribution Channel:
Channel selection reflects order scale, temperature sensitivity, and geographic reach requirements.
- Direct Sales:Large cosmetic houses and pharmaceutical manufacturers in France and Germany negotiate directly with BASF and Solvay for certified grades. Embedded technical service and regulatory documentation justify relationship density.
- Distributors:Specialty chemical distributors build cold-chain logistics for temperature-sensitive emulsion grades, serving mid-scale personal care compounders without tanker-scale demand. Regional warehousing compresses lead times versus direct import.
- Wholesale:Bulk liquid grades for industrial cleaning flow through chemical wholesalers with established tank storage and blending capabilities. Price transparency and immediate availability dominate procurement criteria.
- Online Retail:Small-batch powder and gel formats reach independent formulators and research laboratories through B2B platforms. Sample-scale orders and rapid fulfillment serve product development pipelines.
Distributors are gaining share fastest as cold-chain infrastructure spreads. Direct sales retains the premium certification tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and GC-MS technicians concentrate in Germany's Rhine-Ruhr corridor, anchoring the quality certification infrastructure that underpins premium Lauramide DEA supply chains. This talent base shapes where low-amine production capacity clusters and which export markets gain preferential access.
Germany
Personal care formulators in Düsseldorf and Cologne specify REACH-certified low-amine grades for sulfate-free shampoo lines. ECHA Annex XVII enforcement tightens free diethanolamine thresholds to 0.5% in finished cosmetics. BASF's Ludwigshafen complex operates integrated ethylene oxide-to-amide production with captive analytical laboratories.
United States
Industrial cleaning compounders in Texas and Louisiana prioritize bulk liquid procurement for institutional detergent formulations. California Proposition 65 disclosure requirements extend to diethanolamine content in consumer products. Stepan's Winder, Georgia facility anchors North American amide capacity with dedicated tanker logistics.
France
Cosmetic houses in Paris and Lyon consolidate supplier bases around multi-year agreements with embedded audit rights. ANSM monitors cosmetic ingredient safety alongside EU REACH obligations. The Normandy chemical corridor hosts specialty distributors building cold-chain infrastructure for temperature-sensitive emulsion grades.
South Korea
Personal care manufacturers in Seoul and Incheon adopt cold-process manufacturing methods favoring pre-dispersed Lauramide DEA emulsions. MFDS cosmetic ingredient regulations align with tightening global amine standards. Regional producers with short distribution radius capture ambient-temperature stability requirements.
Japan
Pharmaceutical formulators in Osaka and Tokyo seek USP-grade Lauramide DEA for topical drug delivery systems. PMDA Drug Master File requirements limit qualified suppliers to integrated producers with batch-specific CoA chains. The Kansai region's precision chemical sector drives specification pull for sub-0.5% free-amine certification.
Lauramide DEA Market Competitive Landscape
Top-tier vendors anchor integrated petrochemical-to-surfactant production, while mid-scale specialists compete on custom formulation capabilities and regional cold-chain logistics. The vendor base stratifies across three archetypes: integrated majors with captive ethylene oxide supply, dedicated amide producers with purification expertise, and regional compounders with emulsion processing flexibility. Dominant competitive moves include backward integration into ethylene oxide production and strategic partnerships with specialty distributors for temperature-controlled last-mile delivery.
Within the integrated petrochemical tier, BASF and Solvay exemplify the archetype of producers controlling upstream feedstock through captive ethylene oxide operations. Stepan occupies a position bridging scale-driven commodity supply and specialty amide purification. Colonial Chemical represents the custom formulation specialist archetype, differentiating through ester-amide blend capabilities for sulfate-free personal care lines.
| Leading Market Players |
|---|
| McKinley Resources |
| Jeen International |
| Fine Organics |
| Stepan |
| Solvay |
| BASF |
| Colonial Chemical |
| Protameen Chemicals |
| Hydrior |
| Others |
Value Network & Pricing Analysis
Specialized analytical chemists and GC-MS technicians concentrate in Germany's Rhine-Ruhr corridor, anchoring quality certification infrastructure that widens pricing spreads between premium cosmetic-grade and commodity industrial-grade Lauramide DEA. Labor-cost differentials between certified low-amine production hubs and standard-grade manufacturing regions create three distinct pricing tiers that buyers navigate based on end-use regulatory exposure.
Pricing Analysis
Bundled certification-and-audit services versus unbundled commodity supply splits the Lauramide DEA market into distinct procurement modes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and REACH compliance depth rather than volume scale alone. Price differentiation stems from ECHA Annex XVII testing protocols and captive ethylene oxide supply economics. Pricing pressure stems from cocamidopropyl betaine substitution in premium personal care segments. Industrial cleaning compounders exhibit highest price sensitivity; pharmaceutical formulators show least.
Supply Chain Analysis
Warehouse-distribution layers in Germany, France, and the Netherlands maintain cold-chain infrastructure for temperature-sensitive emulsion grades. Raw material flows draw from lauric acid sources in Southeast Asia and ethylene oxide production in the Rhine-Ruhr chemical corridor. Single-source vulnerability concentrates in certified low-amine purification capacity. Distribution runs through specialty chemical distributors with regional stocking points for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
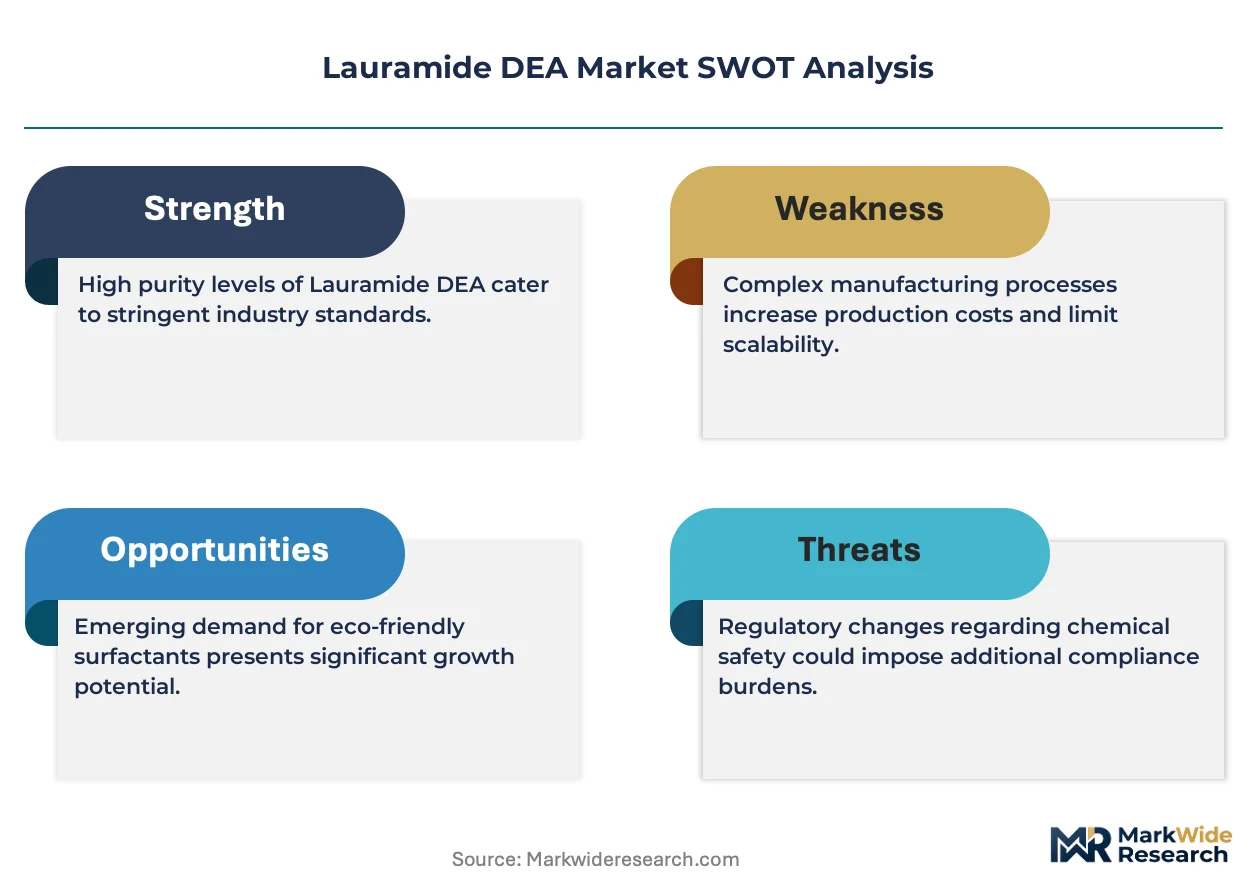
Lauramide DEA offers margin-expansion potential as enzymatic amidation catalysts compress production costs for cosmetic-grade output while REACH certification requirements sustain premium-tier pricing power.
For Market Incumbents: Cement preferred-supplier status with major cosmetic houses through integrated REACH compliance packages and embedded audit rights. Deepen backward integration into ethylene oxide production to neutralize feedstock volatility. Cocamidopropyl betaine displacement in sensitive-skin segments demands defensive certification investment in amine-free process variants. For New Entrants and Emerging Players: Enzymatic amidation technology offers a technology-first wedge for regional producers seeking cosmetic-grade entry without thermal condensation capital requirements. Pharmaceutical-grade USP certification remains underpenetrated with only two European suppliers holding Drug Master Files. Direct-to-compounder distribution through cold-chain logistics partnerships bypasses incumbent tanker-scale economics. For Investors and Strategic Acquirers: Specialty chemical distributors with temperature-controlled last-mile capabilities are the most active acquirer in this space, consolidating regional emulsion-grade suppliers. Long-term viability hinges on certification-capable production assets rather than commodity scale. Watch ECHA authorization bottleneck resolution as inflection indicator for new supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply neutralizes cost volatility for BASF and Solvay in Ludwigshafen. |
| Enzymatic Amidation Scale-Up | Lipase-catalyzed routes at 40-60°C enable cosmetic-grade output from smaller regional batch vessels. |
| Pharmaceutical-Grade Certification | USP-grade Drug Master File documentation opens topical drug delivery segment with limited qualified suppliers. |
| Cold-Chain Distribution Partnership | Temperature-controlled logistics bypass traditional bulk tanker economics for mid-scale personal care compounders. |
| REACH Compliance Package Bundling | Embedded certification and audit rights secure multi-year agreements with German cosmetic houses. |
Research Methodology
Bottom-up personal care and industrial cleaning modeling reconciled against top-down ethylene oxide-to-amide production tracking forms the analytical core of this study. Primary interviews with plant managers at integrated surfactant facilities, procurement leads at downstream cosmetic houses, distribution channel partners in specialty chemicals, and technical R&D directors at amide specialists combined with secondary validation from ECHA registration databases, customs and trade flow data, Cefic surfactant reports, and SEC filings from listed chemical producers. Triangulation between demand-side formulation trends and supply-side capacity announcements anchored volume and value estimates.
Historical trendline analysis of lauric acid diethanolamide pricing and volume flows established baseline growth patterns across the projection horizon. Segmentation modeling incorporated physical form, regulatory certification grade, end-use application, and geographic production hub dimensions. CAGRs derived from slope analysis of normalized demand curves adjusted for REACH regulatory phase-in effects. Industry-specific forecast inputs included ECHA Annex XVII enforcement timelines and cold-process personal care manufacturing adoption rates in South Korea and Japan.
The model holds under stable REACH enforcement intensity and continued ethylene oxide supply availability; deviation in ECHA authorization timelines or feedstock disruption would shift volume and value trajectories. Forecasts reflect documented assumptions about regulatory compliance costs and substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Global Surfactants Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Micellar Water Market
Surfactants
Global Methyl Soyate Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Cationic Surfactants Market
Surfactants
Global Rhamnolipid Market
Surfactants
Emulsifying Wax Market
Surfactants
Zeolite for Detergents Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market