
 Linear Alkylbenzene Sulfonate (LAS) Market | 2026-2036
Linear Alkylbenzene Sulfonate (LAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Alkylbenzene Sulfonate (LAS) Market Analysis
The capital-intensity gap between integrated petrochemical giants and regional surfactant specialists is collapsing as bio-based feedstock investments level the playing field. BASF SE leverages its backward integration into linear alkylbenzene feedstock to sustain margin stability across European supply chains. Stepan Company anchors its competitive position through dedicated sulfonation infrastructure in North America. Galaxy Surfactants Ltd. competes by occupying cost-advantaged manufacturing positions in India and the Middle East.
Linear Alkylbenzene Sulfonate is an anionic surfactant synthesized through sulfonation of linear alkylbenzene with sulfur trioxide, yielding a sodium salt with a hydrophobic alkyl chain (typically C10-C14) and a hydrophilic sulfonate headgroup that reduces surface tension in aqueous systems. Its primary commercial purpose centers on formulation of synthetic detergents where foaming, wetting, and emulsification performance prove critical. Household cleaners constitute the dominant application segment as private-label brands and concentrated formats reshape volume-demand relationships. Industrial cleaning applications represent the fastest-expanding category as food processing and institutional sanitation standards tighten across multiple jurisdictions. Oilfield chemicals remain a specialized niche where technical-grade specifications command premium positioning.
EPA registration requirements under the Toxic Substances Control Act and REACH substance evaluation in Europe constrain non-biodegradable surfactant alternatives, directly advantaging LAS formulations with established environmental fate data. FDA oversight of food-contact sanitizers and FSSAI cleaning-agent standards in India further delineate permissible active-ingredient concentrations and residue limits. Stakeholders must monitor evolving bio-based content mandates and carbon-border adjustment mechanisms as these frameworks increasingly determine feedstock sourcing economics and regional manufacturing competitiveness.
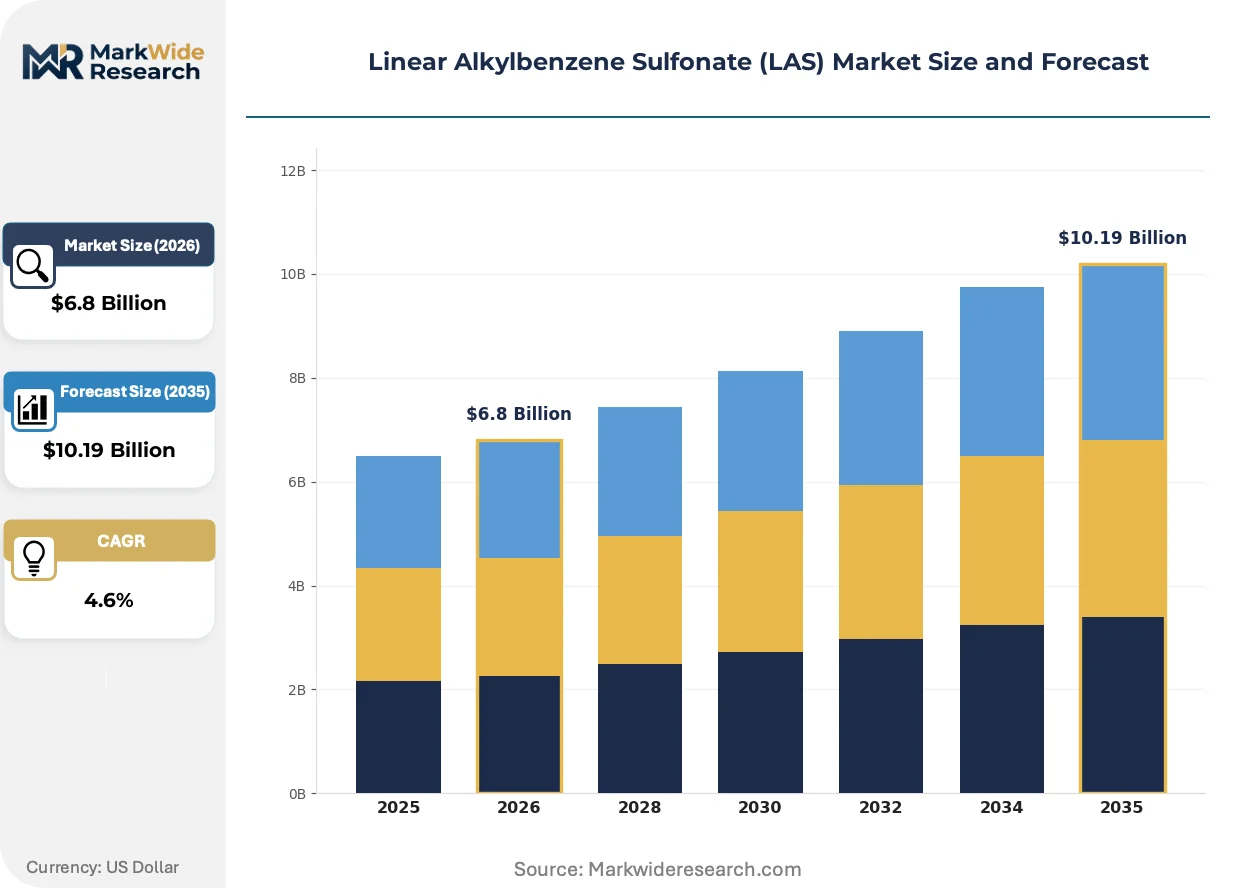
Market Dynamics
REACH substance evaluation and EPA registration requirements are redirecting formulation chemistry toward biodegradable surfactant architectures, collapsing the capital-intensity gap between integrated petrochemical giants and regional specialists as bio-based feedstock investments level competitive positioning.
Growth Catalysts
- Household Cleaner Demand:Consumers prioritize effective sanitation formulations, strengthening volume pull from packaged detergent consumption as middle-class expansion accelerates in emerging economies.
- REACH Compliance:The European regulation constrains non-biodegradable surfactant alternatives, directly advantaging LAS formulations with established environmental fate data and biodegradability credentials.
- Industrial Sanitation Standards:Food processing and institutional cleaning mandates tighten across multiple jurisdictions, expanding technical-grade specifications in oilfield chemicals and specialized industrial applications.
Market Restraints
- Linear Alkylbenzene Feedstock Volatility:Crude oil price fluctuations transmit directly to LAB production economics, compressing margin stability for non-integrated sulfonation operators.
- China Supply Concentration:Bulk volume growth concentrates in Chinese manufacturing clusters, creating geographic dependency risk for downstream formulators in other regions.
- Alcohol Ether Sulfate Substitution:AES surfactants compete in premium detergent segments where mildness and foam aesthetics override cost considerations, limiting LAS penetration in high-end formulations.
Strategic Opportunities
- Brazil Market Underpenetration:Middle-class detergent consumption in Brazilian urban centers lags per-capita benchmarks, offering volume expansion potential for cost-optimized LAS supply.
- EU Green Deal Bio-Based Mandates:Carbon-border adjustment mechanisms and renewable content requirements create sourcing advantages for producers with integrated bio-alkylbenzene capabilities.
- E-Commerce Channel Expansion:Direct-to-consumer concentrated detergent formats bypass traditional retail distribution, enabling private-label brands to capture margin previously allocated to intermediaries.
Industry Challenges
- Sulfonation Process Engineering Talent:Specialized expertise in continuous SO3 sulfonation reactor design and emission control remains scarce, constraining capacity expansion timelines.
- Multi-Jurisdiction Certification Complexity:FDA food-contact sanitizer approvals, FSSAI cleaning-agent standards in India, and divergent residue limit definitions create compliance fragmentation for global formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Alkylbenzene Sulfonate (LAS) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Household Cleaners, Industrial Detergents, Personal Care Products, Food Processing Agents Grade: Technical Grade, Laboratory Grade, Food Grade, Pharmaceutical Grade Application: Synthetic Detergents, Household Cleaning, Industrial Cleaning, Oilfield Chemicals End User: Households, Manufacturing, Food Industry, Oil & Gas |
| Companies Covered | BASF SE, Stepan Company, Clariant Corporation, Hansa Group AG, Croda International Plc, Huntsman Corporation, Galaxy Surfactants Ltd., Evonik Industries AG, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Alkylbenzene Sulfonate (LAS) Market Emerging Trajectories
Bio-based feedstock integration and sulfonation process intensification are actively reshaping competitive economics, while regulatory frameworks accelerate environmental fate transparency requirements across detergent value chains.
Continuous membrane sulfonation technology is fragmenting traditional batch reactor economics by enabling higher throughput with reduced sulfur trioxide excess. Specialty chemical producers in India and the Middle East adopt these systems to offset labor cost advantages with capital efficiency gains. The technology is fragmenting regional supply patterns by allowing smaller-scale producers to achieve unit economics previously reserved for integrated petrochemical complexes.
REACH substance evaluation under ECHA jurisdiction now mandates comprehensive environmental fate dossiers for surfactant registrations, extending compliance timelines and documentation burdens. Industrial cleaning formulators face reformulation costs to maintain authorized substance status. The household detergent segment in Germany and France responds by consolidating supplier relationships toward established LAS producers with existing biodegradability datasets.
Concentrated detergent formats now command preference among European and North American private-label buyers, compressing shipping volumes and packaging material intensity. Traditional dilute liquid detergent supply chains face disintermediation as retailers direct-sourced concentrated tablets and pods. This pattern concentrates demand pull in Benelux and Nordic markets where sustainability scoring influences procurement decisions.
Linear Alkylbenzene Sulfonate (LAS) Market Segmentation
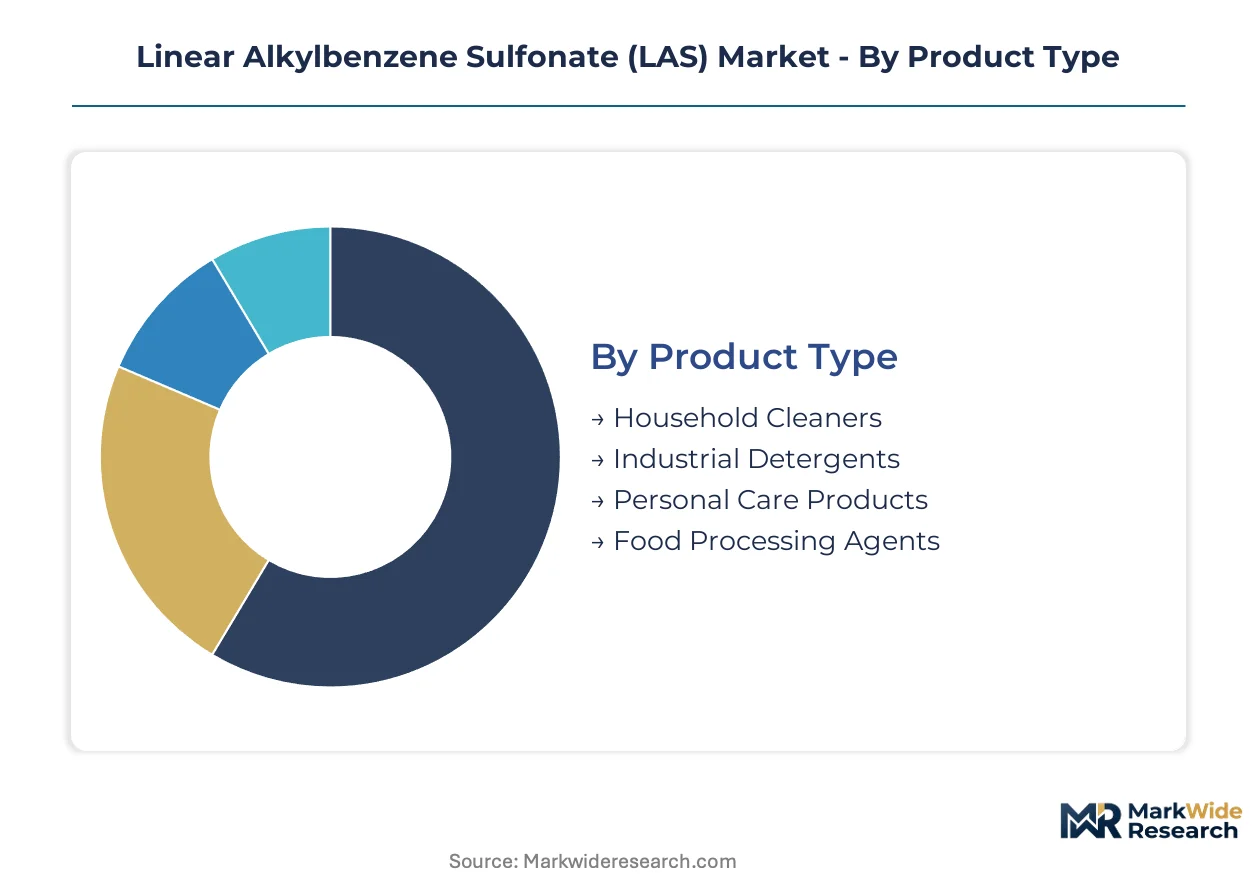
Segmentation in the Linear Alkylbenzene Sulfonate market reveals how formulation chemistry and regulatory compliance create distinct competitive arenas. Each dimension—product type, grade, application, and end user—carries different margin profiles and geographic concentration patterns that determine supplier positioning.
Product Type:
Export-led demand dominates industrial and food processing segments, while household formulations concentrate in domestic manufacturing clusters serving regional consumer bases.
- Household Cleaners:Comprising liquid detergents, dishwashing liquids, and laundry formulations with C10-C14 alkyl chain distributions optimized for hard water tolerance. Demand concentrates in Brazilian and Indian urban centers where middle-class expansion accelerates packaged detergent consumption; REACH compliance in Europe favors established LAS producers with biodegradability datasets over import-dependent formulators.
- Industrial Detergents:Heavy-duty formulations with higher active surfactant concentrations for machinery, vehicle, and facility cleaning. Food processing plants in Germany and France drive specification tightening as ECHA environmental fate requirements extend compliance timelines; sulfonation operators with integrated LAB supply capture margin stability.
- Personal Care Products:Milder LAS derivatives with refined purity specifications for shampoos and body washes.
- Food Processing Agents:Sanitizer formulations meeting FDA food-contact residue limits and FSSAI cleaning-agent standards.
Household Cleaners holds the largest share; momentum sits with Food Processing Agents as multi-jurisdiction sanitation mandates tighten.
Grade:
Cost tier stratification separates commodity sulfonation outputs from certified grades commanding premium positioning in regulated end-uses.
- Technical Grade:Standard LAS with 90-96% active content for industrial cleaning and oilfield applications where functional performance outweighs purity premiums. Oil & Gas operations in Texas and Alberta specify technical grades for emulsion breaking and drilling mud formulations; crude oil price volatility transmits directly to production economics for non-integrated operators.
- Laboratory Grade:Higher purity specifications with controlled trace metal content for analytical and research applications.
- Food Grade:LAS meeting FDA 21 CFR clearance and EFSA food-contact material standards for equipment sanitization in meat, dairy, and beverage processing.
- Pharmaceutical Grade:USP-compliant surfactant with comprehensive impurity profiling for topical and cleaning applications in drug manufacturing.
Technical Grade commands volume leadership; Food Grade climbs the fastest as global food safety authorities harmonize residue limit definitions.
Application:
Customer type differentiation separates mass-market detergent manufacturers from specialized industrial formulators with technical service requirements.
- Synthetic Detergents:Primary LAS incorporation into powder and liquid laundry products with builders, bleaches, and enzymes. Private-label brands in Benelux and Nordic markets direct-source concentrated formats, compressing traditional distributor margins; sustainability scoring influences procurement decisions toward suppliers with carbon-border documentation.
- Household Cleaning:Surface cleaners, toilet bowl formulations, and multi-purpose sprays with fragrance and dye compatibilization.
- Industrial Cleaning:High-alkaline and solvent-based formulations for manufacturing equipment, vehicle fleets, and institutional facilities.
- Oilfield Chemicals:Specialized emulsifiers and wetting agents for enhanced oil recovery and drilling operations.
Synthetic Detergents retains dominant position; Industrial Cleaning shows steepest expansion trajectory as food processing and institutional sanitation standards tighten across multiple jurisdictions.
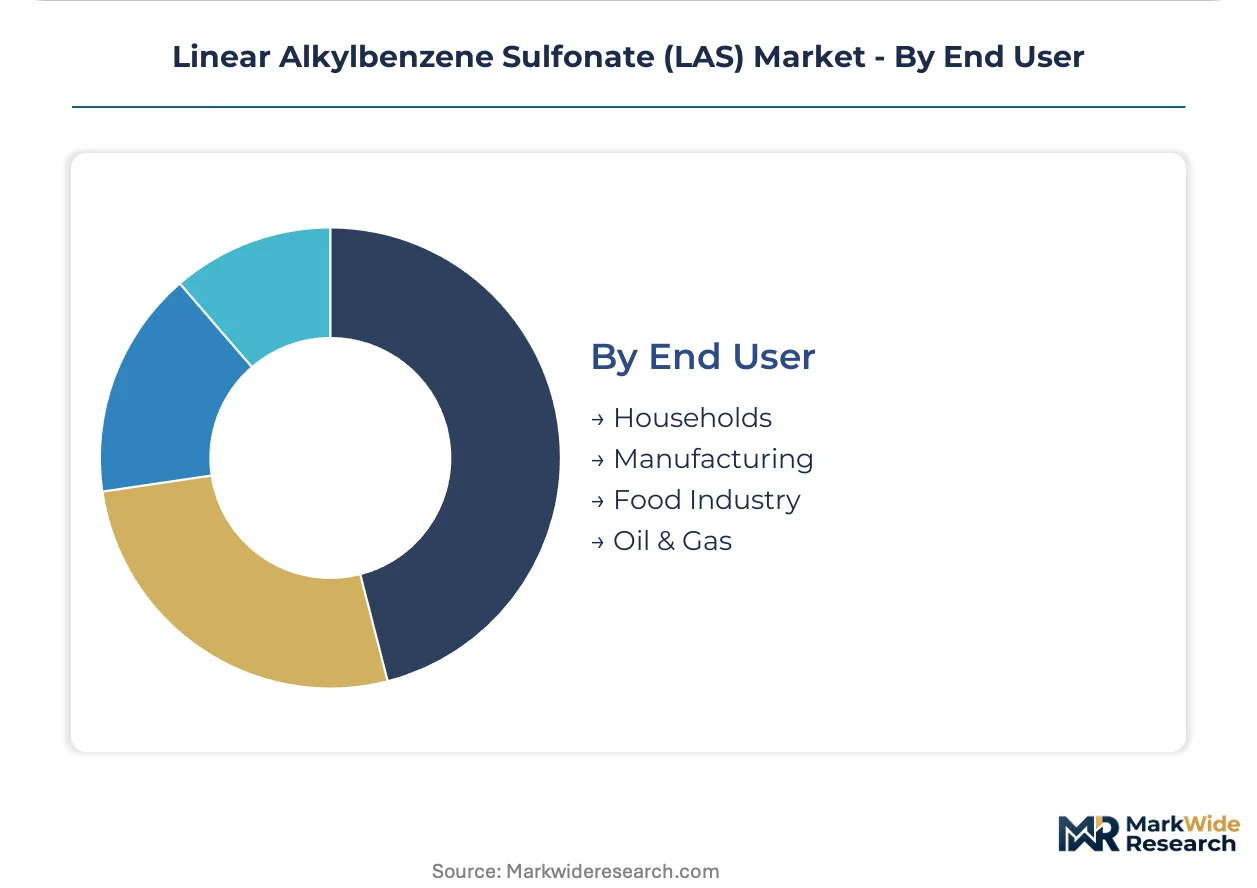
End User:
Volume concentration varies dramatically between fragmented consumer bases and concentrated industrial procurement with long-term supply agreements.
- Households:Individual consumers purchasing retail-packaged detergents through supermarkets, hypermarkets, and e-commerce channels. E-commerce expansion enables direct-to-consumer concentrated tablets and pods, disintermediating traditional retail distribution; urban centers in São Paulo and Mumbai concentrate volume growth as per-capita detergent consumption rises toward developed-market benchmarks.
- Manufacturing:Industrial facilities procuring bulk surfactant for in-house cleaning operations and process applications.
- Food Industry:Processing plants, dairies, and beverage manufacturers with stringent sanitizer residue requirements.
- Oil & Gas:Upstream and midstream operators specifying technical-grade surfactants for production chemistry.
Households represents the largest addressable base; Food Industry gains share fastest as FSSAI, FDA, and EFSA standards converge on stricter cleaning-agent specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates European sulfonation operators from Indian cost-optimized producers, with carbon-border adjustment mechanisms widening this gap. German and French formulators absorb premium-grade LAS at elevated contract terms. Chinese manufacturers export technical-grade volumes at compressed margins.
United States
Household detergent consumption concentrates in suburban retail corridors and e-commerce fulfillment networks. EPA registration requirements under the Toxic Substances Control Act constrain non-biodegradable surfactant alternatives. Gulf Coast petrochemical clusters in Texas and Louisiana anchor LAB feedstock production and downstream sulfonation capacity.
Germany
Industrial sanitation demand from food processing plants drives specification tightening for technical-grade LAS. REACH substance evaluation under ECHA jurisdiction mandates comprehensive environmental fate dossiers. The Ruhr industrial basin concentrates sulfonation infrastructure serving Benelux detergent formulators.
China
Packaged detergent volume expansion in tier-two and tier-three cities accelerates consumption of standard-grade LAS. MIIT industrial standards and dual carbon goals pressure manufacturers toward process intensification. Yangtze River Delta manufacturing clusters dominate export-oriented sulfonation capacity.
India
Middle-class urbanization in Mumbai and Delhi-NCR reshapes per-capita detergent consumption toward developed-market benchmarks. FSSAI cleaning-agent standards delineate permissible active-ingredient concentrations for food-contact applications. Gujarat and Maharashtra host cost-advantaged sulfonation facilities serving Middle East export markets.
Brazil
Urban detergent consumption in São Paulo lags per-capita benchmarks, offering volume expansion potential. ANVISA regulates sanitizer residue limits for food processing equipment. Southeastern manufacturing corridors concentrate import-dependent formulators seeking cost-optimized LAS supply.
Linear Alkylbenzene Sulfonate (LAS) Market Vendor Landscape
Concentration sits with integrated petrochemical conglomerates and regional sulfonation specialists competing on feedstock access and regulatory compliance speed. The vendor base fragments across three tiers: backward-integrated LAB producers, dedicated sulfonation operators, and import-dependent formulators. Two strategic archetypes dominate: European majors leveraging REACH-compliant biodegradability datasets, and Asian cost-optimized producers exploiting labor and energy arbitrage. Competitive moves center on continuous membrane sulfonation technology licensing and bio-based feedstock partnerships.
Among European-integrated majors, BASF SE exemplifies the backward-integrated archetype with captive LAB supply. Stepan Company anchors North American positioning through dedicated sulfonation infrastructure. Galaxy Surfactants Ltd. occupies the cost-optimized tier with India and Middle East manufacturing positions.
| Leading Market Players |
|---|
| BASF SE |
| Stepan Company |
| Clariant Corporation |
| Hansa Group AG |
| Croda International Plc |
| Huntsman Corporation |
| Galaxy Surfactants Ltd. |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
REACH substance evaluation under ECHA jurisdiction gates both supply qualification timelines and price differentiation across European detergent value chains, compressing margins for import-dependent formulators while rewarding integrated producers with existing biodegradability datasets. Certification burdens fragment procurement into premium-compliant and economy-non-compliant tiers.
Pricing Analysis
Configured-to-order pricing for food-grade LAS with FDA 21 CFR clearance commands substantial premiums over standard technical-grade spot transactions. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade USP specifications from industrial cleaning grades, with customization depth and certification tier as primary price differentiation drivers. Cost compression in standard-grade segments is intensifying because Chinese export volumes expand at compressed margins. Household detergent manufacturers in Brazil and India exhibit highest price sensitivity, while pharmaceutical and food-processing formulators demonstrate lowest elasticity due to residue-limit compliance requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites Middle East LAB feedstock flows to Indian sulfonation clusters, creating geographic chokepoint exposure for cost-optimized supply chains. Manufacturing concentrates in China, India, and Germany, with raw material dependencies on linear alkylbenzene feedstock, sulfur trioxide, and sodium hydroxide. Single-source vulnerability runs through Yangtze River Delta export capacity, where environmental compliance inspections periodically constrain output. Distribution feeds from integrated petrochemical complexes through bulk tanker shipments to downstream formulators, with e-commerce channels disintermediating traditional distributor networks for concentrated detergent formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for sulfonation process optimization and regulatory dossier maintenance expand faster than commodity LAS volume, creating attach-rate opportunities for integrated producers. Recurring compliance documentation revenue layers compound annually as REACH evaluation timelines extend.
For Market Incumbents: Shield margin stability through captive linear alkylbenzene production and continuous membrane sulfonation licensing to regional specialists. AES surfactant substitution in premium detergent segments threatens volume retention; backward integration into bio-alkylbenzene feedstock secures EU Green Deal positioning against carbon-border adjustment exposure. For New Entrants and Emerging Players: Lead with Brazil's underpenetrated urban detergent markets, where São Paulo per-capita consumption lags developed-market benchmarks and import-dependent formulators seek cost-optimized supply. Target food-grade certification for meat and dairy processing applications, where FSSAI, FDA, and EFSA standards converge on stricter residue limits. Pursue direct-to-consumer concentrated tablet formats through e-commerce channels to bypass retail distribution margin capture. For Investors and Strategic Acquirers: EU carbon-border adjustment mechanism implementation reshapes the acquisition landscape toward producers with integrated bio-based feedstock capabilities and established REACH biodegradability datasets. Long-term viability centers on sulfonation operators with captive LAB supply and multi-jurisdiction certification infrastructure. Monitor ECHA substance evaluation timeline extensions as inflection indicator for compliance cost escalation and supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Alkylbenzene | EU Green Deal mandates position bio-based feedstock producers for carbon-border adjustment advantages. |
| Continuous Membrane Sulfonation Licensing | Technology transfer to Indian and Middle East operators fragments regional supply concentration patterns. |
| Food-Grade Certification Investment | FDA 21 CFR and EFSA compliance unlocks premium positioning in meat and dairy processing sanitation. |
| E-Commerce Concentrated Format Launch | Direct-to-consumer tablets and pods disintermediate traditional retail distribution margin capture. |
| Multi-Jurisdiction Dossier Expansion | REACH, FSSAI, and EPA registration coverage consolidates supplier relationships with global formulators. |
Methodological Framework
Initial hypotheses were tested against primary input from sulfonation plant managers, detergent procurement leads at consumer goods OEMs, distribution channel partners, and technical R&D directors, then refined through secondary validation. Customs and trade data, Cefic surfactant reports, SEC 10-K filings, and ECHA registration dossiers anchored quantitative baselines. Bottom-up capacity modeling and top-down demand triangulation converged on volume estimates across the analysis window.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub informed segmentation-level projections. CAGRs derived from elasticity-adjusted demand curves incorporating crude oil feedstock volatility and regulatory compliance cost trajectories. Forecast inputs included LAB production capacity utilization rates and REACH evaluation timeline assumptions.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and FSSAI regimes; material policy shifts would require re-modeling of compliance cost pass-through and supplier qualification timelines. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanism implementation schedules and bio-based content mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Isopropyl Myristate Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Waxing Sponge Market
Surfactants
Polymer Surfactants Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Cationic Surfactants Market
Surfactants
Global Demulsifiers Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Sodium Methyl Cocoyl Taurate Market