
 Asia Pacific Surfactants Market | 2026-2036
Asia Pacific Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Surfactants Market Outlook
Specialized chemical engineering talent is rotating toward surfactant process optimization across the Asia Pacific, tightening labor availability for conventional alkoxylate production while expanding capacity in specialty ester chemistry. BASF SE leverages its integrated Ludwigshafen-derived technology platform to sustain large-scale anionic output in the region. Kao Corporation anchors Japanese personal care demand through captive surfactant supply chains. Galaxy Surfactants Ltd. specializes in India-centric alkylbenzene sulfonate and fatty alcohol ethoxylate grades for domestic detergent makers.
Surfactants are surface-active compounds with amphiphilic molecular structures containing hydrophilic head groups and hydrophobic tail chains, typically synthesized through sulfonation, ethoxylation, or amidation reactions to reduce interfacial tension between immiscible phases. Their primary industrial purpose spans detergency, emulsification, wetting, and foaming across formulated consumer and industrial products. Nonionic surfactants dominate margin pools in personal care and institutional cleaning owing to mildness and cold-water solubility advantages. Anionic surfactants lead volume in household cleaning applications where cost-efficient grease removal remains paramount. Cationic variants occupy niche but high-value positions in textile softening and antimicrobial formulations.
Japan's METI enforces chemical manufacturing efficiency standards that elevate energy and yield requirements for surfactant producers operating within its jurisdiction. India's BIS mandates purity specifications for linear alkylbenzene sulfonate used in detergent formulations, directly conditioning import and domestic production compliance costs. China's MEE implements wastewater discharge regulations that constrain sulfonation plant siting and effluent treatment capital deployment. Stakeholders must monitor evolving bio-based content thresholds across these regulatory regimes to align product portfolios with compliance trajectories and procurement specifications from multinational brand owners.
Market Dynamics
Formulation chemistry specialization is fragmenting procurement patterns across the Asia Pacific surfactants market, as multinational personal care brands impose bio-based content mandates that favor ester-based and cold-process surfactant systems over conventional alkoxylates.
Growth Catalysts
- India's BIS purity standards:Domestic detergent manufacturers must source compliant linear alkylbenzene sulfonate, accelerating certified domestic production capacity and import substitution.
- Southeast Asian personal care clusters:Formulation demand for mild surfactant systems in Indonesia, Thailand, and Vietnam is pulling specialty nonionic capacity into the region.
- Japan's METI efficiency mandates:Energy-yield requirements for chemical manufacturing are steering investment toward low-temperature sulfonation and bio-based feedstock processing.
Market Restraints
- Palm kernel oil price volatility:Fatty alcohol feedstock costs fluctuate with Malaysian and Indonesian commodity markets, compressing margin predictability for ethoxylate producers.
- China's eastern corridor concentration:Sulfonation capacity clusters near Shanghai and Guangzhou create geographic supply risk and wastewater discharge bottlenecks under MEE regulations.
- Technical limitations in cold-water solubility:Anionic surfactants struggle to match nonionic performance in low-temperature laundry applications without formulation complexity.
Strategic Opportunities
- Underpenetrated Indian institutional cleaning:Hospital and food-service sanitation standards are tightening, creating demand for quaternary ammonium and amphoteric disinfectant surfactants.
- Technology convergence of enzymatic and surfactant systems:Detergent formulators in South Korea are blending lipase enzymes with mild nonionics to reduce chemical load per wash cycle.
- Australia's green procurement mandates:Federal sustainable purchasing policies are creating preferential channels for bio-based and readily biodegradable surfactant grades.
Industry Challenges
- Specialized chemical engineering scarcity:Process optimization talent is rotating toward surfactant R&D, tightening availability for conventional alkoxylate plant operations.
- MEE wastewater compliance timelines:Sulfonation producers in China's manufacturing corridor face compressed capital deployment schedules for effluent treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Surfactants Market |
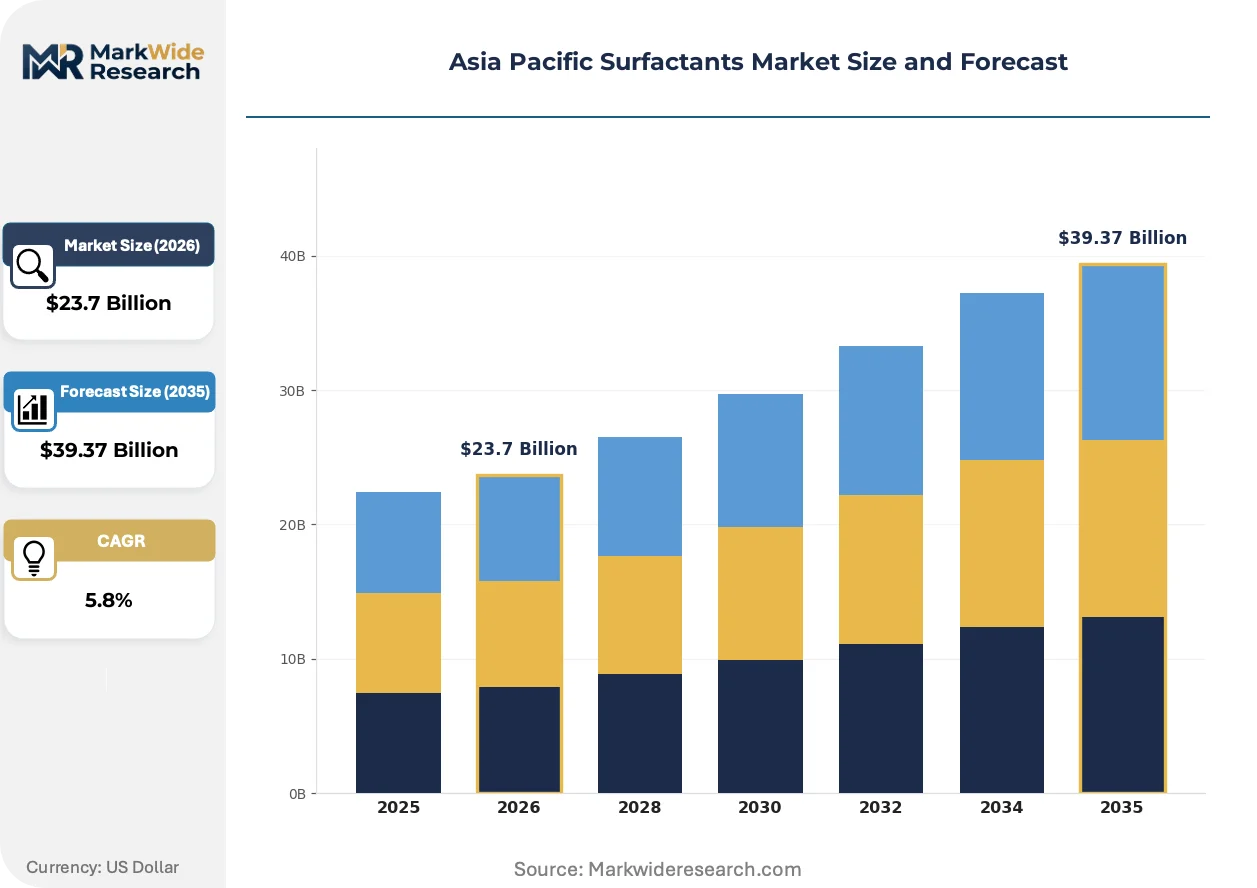
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Surfactants, Cationic Surfactants, Nonionic Surfactants, Amphoteric Surfactants Application: Household Cleaning, Personal Care, Industrial Cleaning, Agricultural Chemicals End User: Food & Beverage, Healthcare, Automotive, Textile Distribution Channel: Online Retail, Supermarkets, Direct Sales, Distributors |
| Companies Covered | BASF SE, Henkel AG & Co. KGaA, Evonik Industries AG, Croda International Plc, Clariant, Kao Corporation, Galaxy Surfactants Ltd., Dow Inc., Solvay S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Surfactants Market Strategic Shifts
Enzymatic pre-treatment systems are actively reshaping detergent formulation architectures across the Asia Pacific, compressing the functional role of traditional surfactants while elevating demand for mild, compatible co-surfactant systems.
Bio-catalytic surfactant synthesis is decomposing the conventional ethoxylation-sulfonation process hierarchy. Japanese and South Korean detergent manufacturers are adopting lipase-assisted production for cold-water applications. This biotechnology is decomposing capital barriers for mid-scale producers seeking to bypass large-scale alkoxylate infrastructure.
China's MEE wastewater discharge regulations are tightening siting constraints for sulfonation plants. Industrial consequence includes elevated effluent treatment capital requirements and geographic relocation of new capacity. Household cleaning surfactant producers in the Yangtze River Delta are responding with closed-loop water recycling investments and third-party treatment partnerships.
Direct procurement from specialty surfactant makers is displacing distributor intermediaries among Southeast Asian personal care formulators. Brand technical teams in Thailand and Indonesia now negotiate directly with ester chemistry specialists for custom mild surfactant systems. This channel compression is most visible in premium skincare and baby care product verticals where formulation differentiation commands priority.
Asia Pacific Surfactants Market Segmentation
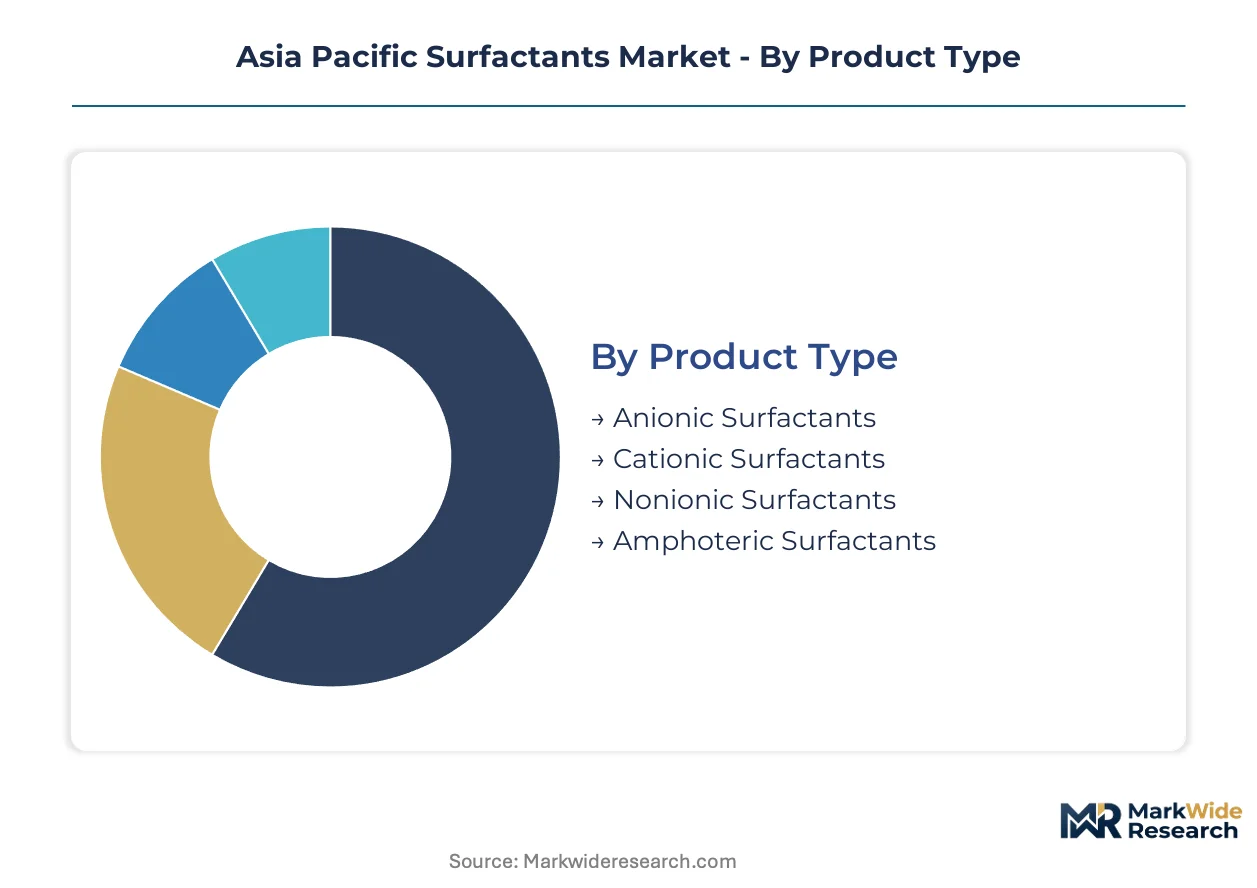
Surfactant procurement patterns across the Asia Pacific diverge sharply by product chemistry and end-use sophistication. Formulation requirements from Japanese personal care brands differ fundamentally from Indian detergent manufacturers, creating parallel demand tracks that suppliers must navigate simultaneously.
Product Type:
Domestic consumption in India and China anchors anionic production, while export-oriented specialty grades from Japan and South Korea feed Southeast Asian personal care formulators.
- Anionic Surfactants:Linear alkylbenzene sulfonate and alcohol ether sulfate dominate household detergent formulations across China and India. India's BIS purity mandates are accelerating certified domestic sulfonation capacity near Mumbai and Gujarat.
- Nonionic Surfactants:Fatty alcohol ethoxylates offer superior cold-water solubility and mildness profiles. Demand concentrates in Thai and Indonesian personal care clusters where multinational brands specify low-irritant surfactant systems.
- Cationic Surfactants:Quaternary ammonium compounds serve textile softening and antimicrobial applications in South Korean and Taiwanese manufacturing.
- Amphoteric Surfactants:Betaine derivatives balance mildness with foaming performance in premium baby care formulations across Southeast Asia.
Anionic surfactants hold the largest share; momentum sits with nonionic grades as cold-process personal care formulations expand.
Application:
Cost tier stratification separates commodity detergent actives from premium personal care specialties, with margin structures diverging threefold between segments.
- Household Cleaning:Powder and liquid laundry detergents consume sulfonate and ethoxylate volumes at scale. China's eastern manufacturing corridor clusters sulfonation plants to serve Unilever and Procter & Gamble formulation facilities near Shanghai.
- Personal Care:Shampoo, body wash, and facial cleanser formulations demand milder, lower-irritation surfactant systems. Indonesian and Thai brands are pulling specialty ester chemistry capacity into ASEAN free trade zones.
- Industrial Cleaning:Metal degreasing and hard surface sanitation applications favor high-alkaline compatible surfactants in Australian and South Korean manufacturing.
- Agricultural Chemicals:Pesticide emulsifiers and adjuvants require tailored hydrophobic-lipophilic balance specifications for tropical crop applications across Malaysia and Indonesia.
Household cleaning commands the greatest volume; personal care applications are climbing the fastest as Southeast Asian disposable incomes rise.
End User:
Customer type determines specification intensity, with healthcare and food processing sectors imposing the strictest purity and documentation requirements.
- Food & Beverage:Processing equipment cleaners and bottle wash formulations demand food-grade surfactant certifications. Australia's dairy and meat processing sectors specify readily biodegradable grades under federal sustainable procurement policies.
- Healthcare:Hospital-grade disinfectants and surgical instrument cleaners require quaternary ammonium and amphoteric surfactants with validated antimicrobial efficacy. India's tightening sanitation standards in private hospital chains are expanding institutional demand.
- Automotive:Car wash formulations and metal pre-treatment chemicals utilize anionic and nonionic blends for soil removal and corrosion inhibition.
- Textile:Fiber processing, dyeing auxiliaries, and finishing softeners drive cationic surfactant consumption in Bangladeshi and Vietnamese garment manufacturing.
Food & beverage represents the most mature demand base; healthcare applications show the steepest expansion trajectory as hospital sanitation standards tighten across the region.
Distribution Channel:
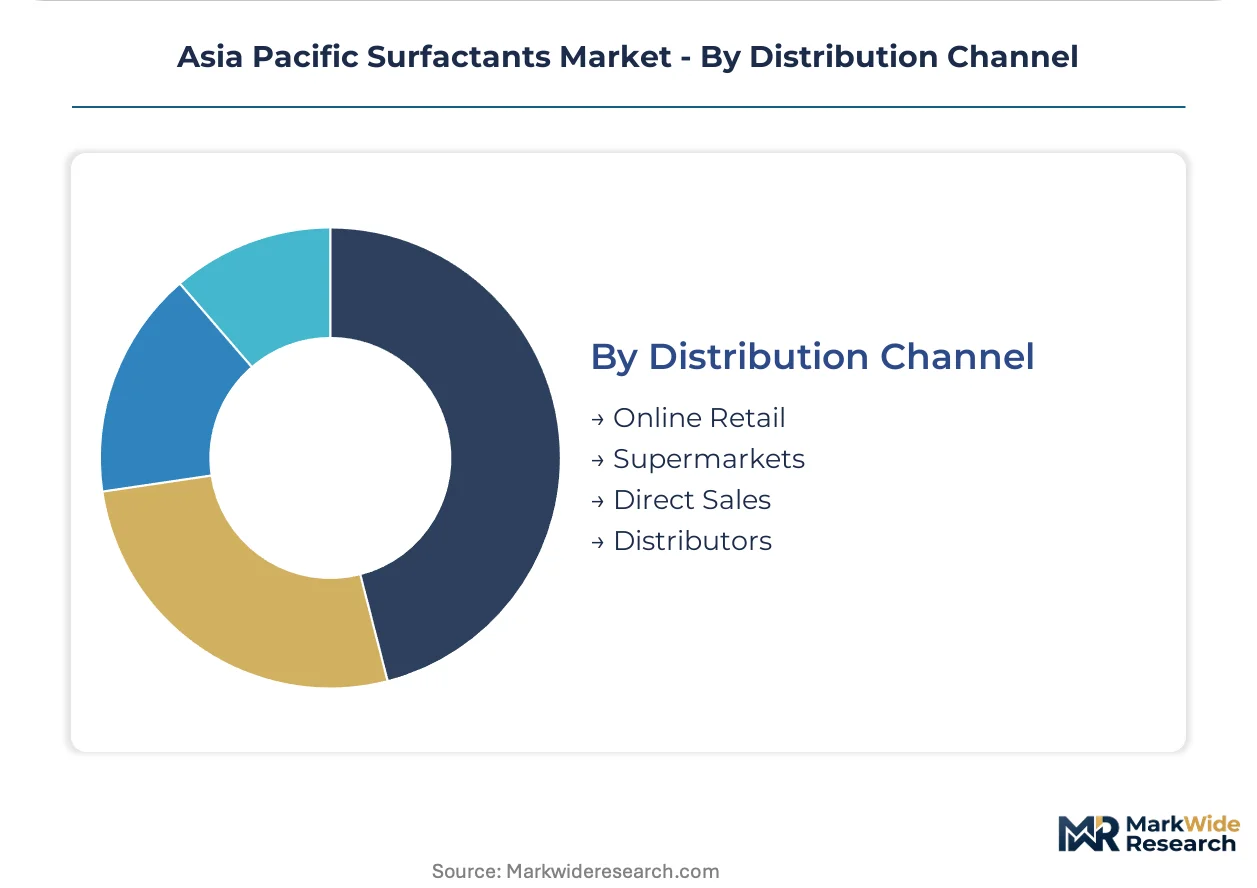
Supply concentration in China's manufacturing belt favors direct procurement relationships over distributor intermediaries for volume detergent producers.
- Direct Sales:Large detergent and personal care manufacturers negotiate annual contracts with surfactant producers for guaranteed alkylbenzene sulfonate and fatty alcohol ethoxylate supply. BASF and Kao leverage captive supply chains to serve their own formulation facilities.
- Distributors:Regional chemical distributors stock standard surfactant grades for mid-tier Indian and Southeast Asian formulators lacking direct supplier relationships.
- Online Retail:Specialty surfactant samples and small-batch orders flow through Alibaba and IndiaMART platforms for cosmetic startups and contract manufacturers.
- Supermarkets:Consumer-facing surfactant products reach end-users through modern trade channels in urban Thailand, Malaysia, and Australia.
Direct sales channels handle the largest volume share; online platforms are gaining share fastest among specialty surfactant procurement for small-batch formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the regulatory environment across the Asia Pacific surfactants market, with wastewater discharge standards reshaping production geography and investment patterns throughout the region.
China
Detergent and cosmetics manufacturers cluster along the eastern manufacturing corridor near Shanghai and Guangzhou, driving concentrated demand for anionic surfactants. MEE regulations constrain sulfonation plant siting and mandate effluent treatment capital deployment. Producers in the Yangtze River Delta are responding with closed-loop water recycling investments and third-party treatment partnerships.
India
Domestic detergent makers anchor consumption of linear alkylbenzene sulfonate and fatty alcohol ethoxylate grades. BIS purity standards mandate certified production, accelerating import substitution and certified domestic sulfonation capacity near Mumbai and Gujarat. Hospital and food-service sanitation standards are tightening institutional demand for quaternary ammonium disinfectant surfactants.
Japan
Personal care brands drive formulation demand for milder, lower-irritation surfactant systems. METI energy-efficiency mandates steer product development toward bio-based feedstock processing and low-temperature active ingredients. Kao Corporation anchors domestic demand through captive surfactant supply chains serving formulation facilities.
Southeast Asia
Indonesia, Thailand, and Vietnam pull specialty nonionic capacity into ASEAN free trade zones as multinational personal care brands specify mild surfactant systems. Formulation technical teams negotiate directly with ester chemistry specialists for custom grades. Premium skincare and baby care verticals command priority in procurement channel compression.
South Korea
Detergent formulators blend lipase enzymes with mild nonionics to reduce chemical load per wash cycle, compressing traditional surfactant functional roles. Technology convergence between enzymatic and surfactant systems elevates demand for compatible co-surfactant architectures. Bio-catalytic synthesis adoption decomposes capital barriers for mid-scale producers.
Asia Pacific Surfactants Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific surfactants market. Integrated multinational chemical conglomerates leverage proprietary process platforms for large-scale anionic output, while regional specialists concentrate on ester chemistry and formulation-specific grades. Three strategic archetypes dominate: captive supply chain operators serving internal formulation networks, independent specialty surfactant makers targeting personal care differentiation, and diversified chemical majors optimizing commodity scale. Competitive moves concentrate on backward integration into fatty alcohol feedstocks and technology licensing for bio-catalytic production systems.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. represent scale-driven positions anchored by technology platforms transferred from European and North American headquarters. Among Asia-headquartered specialists, Kao Corporation exemplifies captive supply chain architecture, while Galaxy Surfactants Ltd. occupies a position serving India-centric detergent demand. These three companies illustrate the geographic and strategic segmentation that defines competitive positioning across the region.
| Leading Market Players |
|---|
| BASF SE |
| Henkel AG & Co. KGaA |
| Evonik Industries AG |
| Croda International Plc |
| Clariant |
| Kao Corporation |
| Galaxy Surfactants Ltd. |
| Dow Inc. |
| Solvay S.A. |
| Others |
Value Chain & Pricing Dynamics
Bio-based feedstock substitution for palm-derived fatty alcohols is redrawing procurement geography across the Asia Pacific surfactants market, compressing Malaysian and Indonesian supply dominance while elevating price volatility for ethoxylate producers locked into traditional feedstock contracts.
Pricing Analysis
Price spreads between Indian domestic sulfonate grades and Japanese specialty ester surfactants span three performance tiers based on BIS certification status and cold-process compatibility. Contract-based long-term offtake dominates volume detergent procurement, while spot purchases govern small-batch personal care sampling. Cost compression in standard anionic grades intensifies as Chinese producers expand sulfonation capacity under MEE compliance timelines. Mass-market detergent manufacturers exhibit highest price sensitivity; premium skincare formulators prioritize mildness specifications over unit economics.
Supply Chain Analysis
China and India anchor sulfonation capacity for commodity anionic surfactants, while Japan and South Korea concentrate specialty nonionic and bio-catalytic production. Fatty alcohol feedstocks draw from Malaysian palm kernel oil, Indonesian coconut derivatives, and emerging Indian castor-based alternatives. Single-source vulnerability concentrates in the Strait of Malacca logistics corridor connecting feedstock origins to Chinese manufacturing clusters. Distribution runs through direct annual contracts for multinational detergent producers, with regional distributors serving mid-tier Southeast Asian formulators lacking captive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational personal care brands imposing bio-based content mandates, fragmenting procurement leverage for smaller Southeast Asian formulators unable to negotiate direct supplier relationships.
For Market Incumbents: Compound technical differentiation through backward integration into certified bio-based feedstock streams and low-temperature sulfonation capacity additions in Gujarat and Vietnam. Lipase-assisted production technologies from South Korean detergent innovators threaten conventional ethoxylate margins; preemptive licensing agreements with enzymatic technology developers secure transition pathways. For New Entrants and Emerging Players: Lead with institutional cleaning specialization targeting Indian hospital and food-service sanitation standards tightening quaternary ammonium demand. Australia's federal sustainable procurement policies create preferential channels for biodegradable surfactant grades with validated environmental certifications. Direct technical sales teams bypass distributor intermediaries serving premium skincare and baby care verticals in Thai and Indonesian free trade zones. For Investors and Strategic Acquirers: The market sits at a feedstock-transition phase that favors specialty ester chemistry capabilities over commodity sulfonation scale. Long-term viability centers on bio-catalytic production platforms and captive supply relationships with multinational brand owners. Watch BIS enforcement intensity and MEE wastewater compliance timelines as inflection indicators for domestic Indian and Chinese producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Castor and sugarcane-derived alternatives reduce Malaysian palm kernel oil dependency for ethoxylate producers. |
| Low-temperature Sulfonation Capacity Expansion | METI efficiency mandates in Japan and BIS compliance in India favor energy-yield optimized production systems. |
| Enzymatic Technology Licensing Partnerships | South Korean lipase-assisted production adoption decomposes capital barriers for mid-scale regional competitors. |
| Direct Procurement Channel Development | Southeast Asian personal care formulators in Thailand and Indonesia bypass distributors for custom mild surfactant systems. |
| Closed-loop Water Recycling Investment | China's MEE regulations in the Yangtze River Delta elevate effluent treatment capital deployment requirements. |
Study Parameters
Operator-level perspectives from sulfonation plant managers, procurement leads at Unilever and Procter & Gamble formulation facilities, distribution channel partners in Mumbai and Bangkok, and technical R&D directors at Japanese personal care brands anchored the qualitative base. Primary interview insights triangulated against customs and trade data from China's General Administration of Customs, ACC and Cefic surfactant production reports, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up capacity and consumption estimates reconciled with top-down market sizing across product chemistry, application vertical, and regional production hub segmentation.
Sensitivity analysis tested forecast outputs against feedstock price volatility scenarios and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled include surfactant chemistry class, end-use application tier, certification grade, and regional manufacturing cluster concentration. CAGRs derived from trend extrapolation of historical consumption patterns adjusted for capacity addition announcements and technology substitution rates. Industry-specific inputs incorporated BIS enforcement timelines, MEE wastewater discharge standard phase-ins, and METI energy-efficiency mandate adoption curves.
Forecasts assume regulatory continuity in India's BIS purity regimes, China's MEE discharge standards, and Japan's METI efficiency mandates; material policy shifts would require re-modeling. Palm kernel oil price volatility, enzymatic technology adoption acceleration, and multinational brand bio-based procurement threshold revisions constitute primary forecast revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cyclotetrasiloxane Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Global Surfactants Market
Surfactants
Sulfosuccinate Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Zeolite for Detergents Market
Surfactants
Trisiloxane Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Microemulsions Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Soap Salts Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Pharmaceutical Surfactants Market