
 Sodium Methyl Cocoyl Taurate Market | 2026-2036
Sodium Methyl Cocoyl Taurate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Methyl Cocoyl Taurate Market Analytics
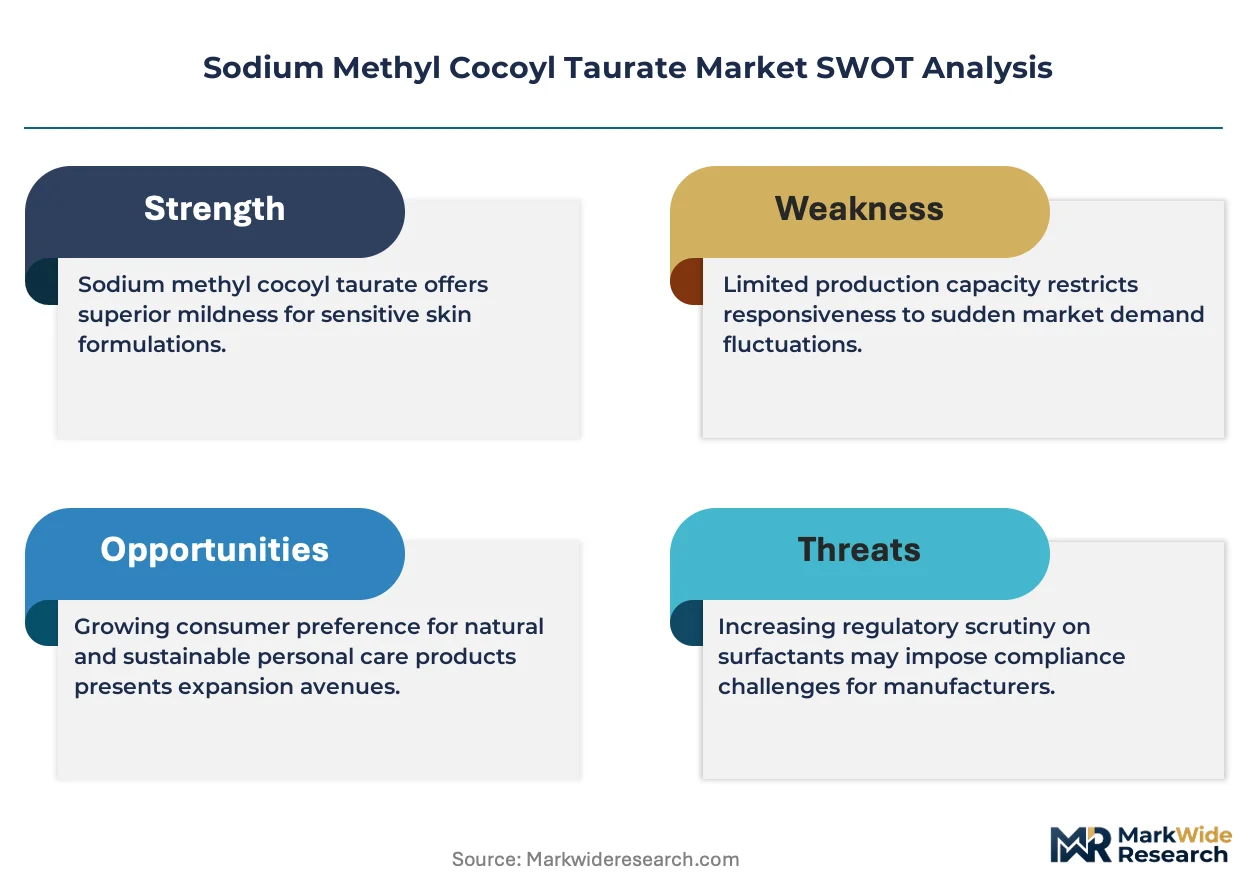
Project finance for dedicated oleochemical processing facilities is fragmenting competitive entry barriers across the Sodium Methyl Cocoyl Taurate landscape. Galaxy Surfactants leverages backward integration into coconut oil fractionation to secure feedstock margins. Stepan Company anchors North American supply through ethoxylation and sulfonation infrastructure. Croda International differentiates via RSPO-certified supply chains and taurine derivatization expertise.
Sodium methyl cocoyl taurate is a sodium salt of the coconut fatty acid amide of N-methyltaurine, typically manufactured through condensation of cocoyl chloride with methyl taurine followed by neutralization, yielding a mild anionic surfactant with pH compatibility from 5.0 to 8.5 and excellent foam stability in hard water. Personal care applications command the dominant value share as sulfate-free and sensitive-skin formulations drive premium positioning for liquid and gel forms. Powder grades are maturing in industrial cleaning where cost-sensitive buyers prioritize bulk handling over solubility performance.
REACH registration requirements and the EU F-Gas Regulation indirectly shape surfactant selection by pressuring formulators toward lower-ecotoxicity chemistries, while China's SAMR enforces GB standards for cosmetic ingredient safety that elevate testing burdens for imported taurates. FDA oversight of cosmetic labeling under the Modernization of Cosmetics Regulation Act adds compliance layers for US market participants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply chain disruptions.
Market Dynamics
Formulators' procurement of sulfate-free surfactants is concentrating demand among coconut-derived taurates, while REACH compliance and China's dual carbon goals force feedstock traceability investments that reshape competitive economics.
Growth Catalysts
- EU Green Deal chemistry mandates:REACH registration burdens for conventional sulfates accelerate substitution toward bio-based taurates in German and French cosmetic manufacturing.
- Sensitive-skin formulation proliferation:Dermatologist-recommended cleansers for eczema-prone populations expand addressable demand for pH-neutral anionic surfactants.
- China cosmetics production clustering:Guangdong and Jiangsu province formulators scale domestic taurate procurement to serve emerging local beauty brands.
Market Restraints
- Coconut oil price volatility:Philippine and Indonesian crude coconut oil supply disruptions transmit directly to taurate manufacturing cost structures.
- Taurine feedstock concentration:Petrochemical-derived taurine supply chains remain concentrated among Japanese and Chinese specialty chemical producers.
- Amide bond hydrolysis limitations:Thermal stability constraints above 40°C restrict high-temperature processing applications in industrial cleaning formulations.
Strategic Opportunities
- India personal care penetration:Underdeveloped sulfate-free shampoo adoption in tier-2 and tier-3 cities creates whitespace for mild surfactant education and sampling.
- SAMR cosmetic ingredient transparency:China's GB standard enforcement elevates testing documentation requirements that favor established taurate suppliers with existing dossiers.
- Spray-drying equipment convergence:Integration of continuous crystallization with fluidized bed drying reduces powder grade production costs for industrial buyers.
Industry Challenges
- Process analytical chemistry expertise:Real-time monitoring of condensation reaction endpoints requires skilled technicians scarce in emerging manufacturing regions.
- RSPO certification timeline:Mass balance chain-of-custody documentation for sustainable palm kernel oil alternatives extends supplier qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Methyl Cocoyl Taurate Market |
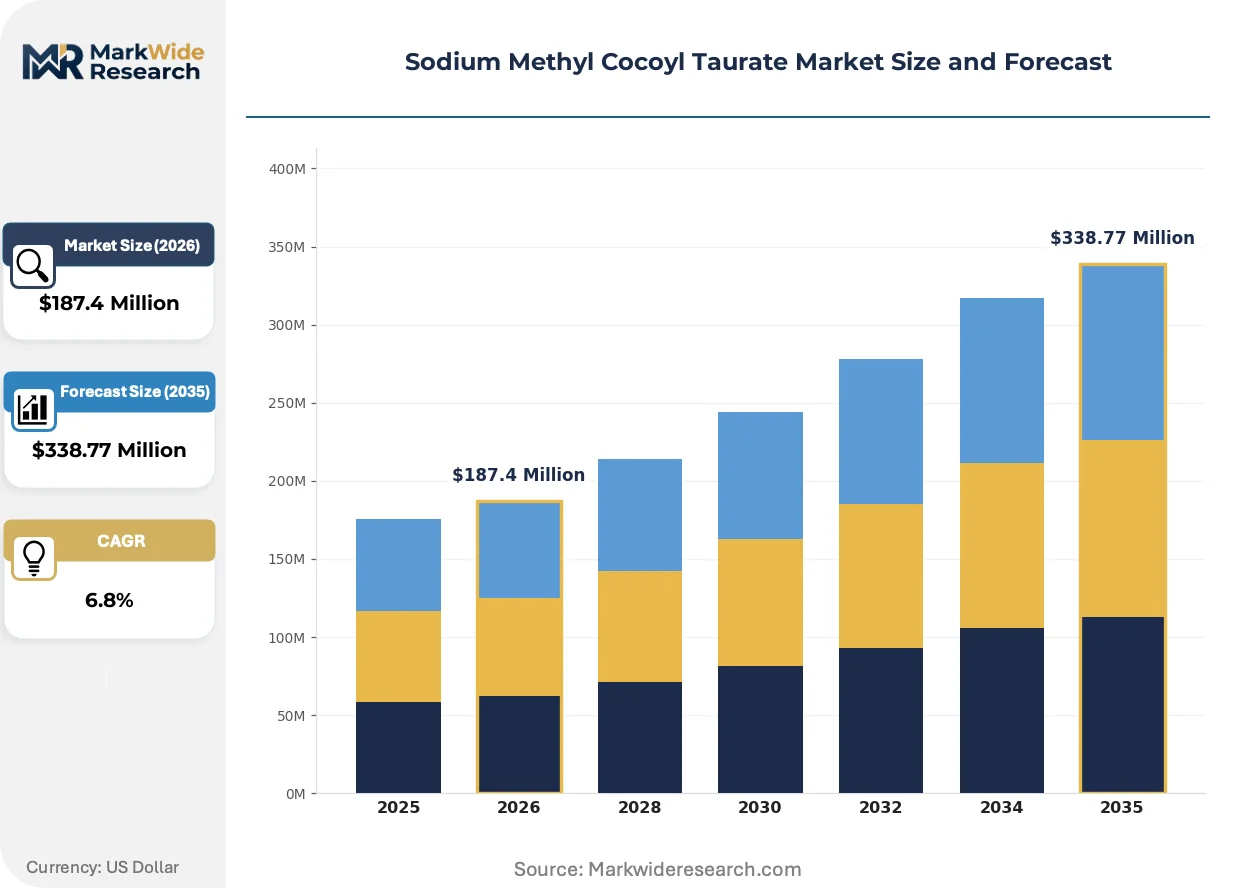
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Cleansers, Foaming Agents, Emulsifiers Application: Personal Care, Household Cleaning, Industrial Cleaning, Cosmetics Form: Powder, Liquid, Cream, Gel End User: Consumers, Manufacturers, Estheticians, Chemists |
| Companies Covered | Croda International, BASF, Galaxy Surfactants, Clariant, Evonik Industries, Stepan Company, Innospec, Foshan Hytop New Material, Puji Biology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Methyl Cocoyl Taurate Market Evolving Landscape
Digital process control and regulatory chemistry disclosure are converging to transform how taurate surfactants are manufactured, certified, and procured across personal care value chains.
Continuous flow reactor technology is digitizing sodium methyl cocoyl taurate synthesis by replacing batch condensation with real-time pH and temperature monitoring systems. Korean and Chinese contract manufacturers are retrofitting pilot plants with distributed control architectures. This digitization compresses batch-to-batch variability and reduces neutralization stage waste by enabling precise stoichiometric endpoint detection.
REACH's SCIP database requirements for Substances of Very High Concern are forcing EU-based formulators to document full taurate supply chain composition down to 0.1% w/w thresholds. German cosmetic brands now require suppliers to submit extended safety data sheets with exposure scenario annexes. The compliance burden falls heaviest on small and mid-sized personal care brands lacking dedicated regulatory affairs functions.
Direct raw material purchasing by personal care brands is displacing traditional distributor intermediaries for sodium methyl cocoyl taurate procurement. North American clean beauty startups now contract directly with Indian and Chinese taurate manufacturers, bypassing regional chemical distributors. This disintermediation is most visible in California and New York where vertically integrated indie brands prioritize supply chain transparency over working capital flexibility.
Sodium Methyl Cocoyl Taurate Market Segmentation
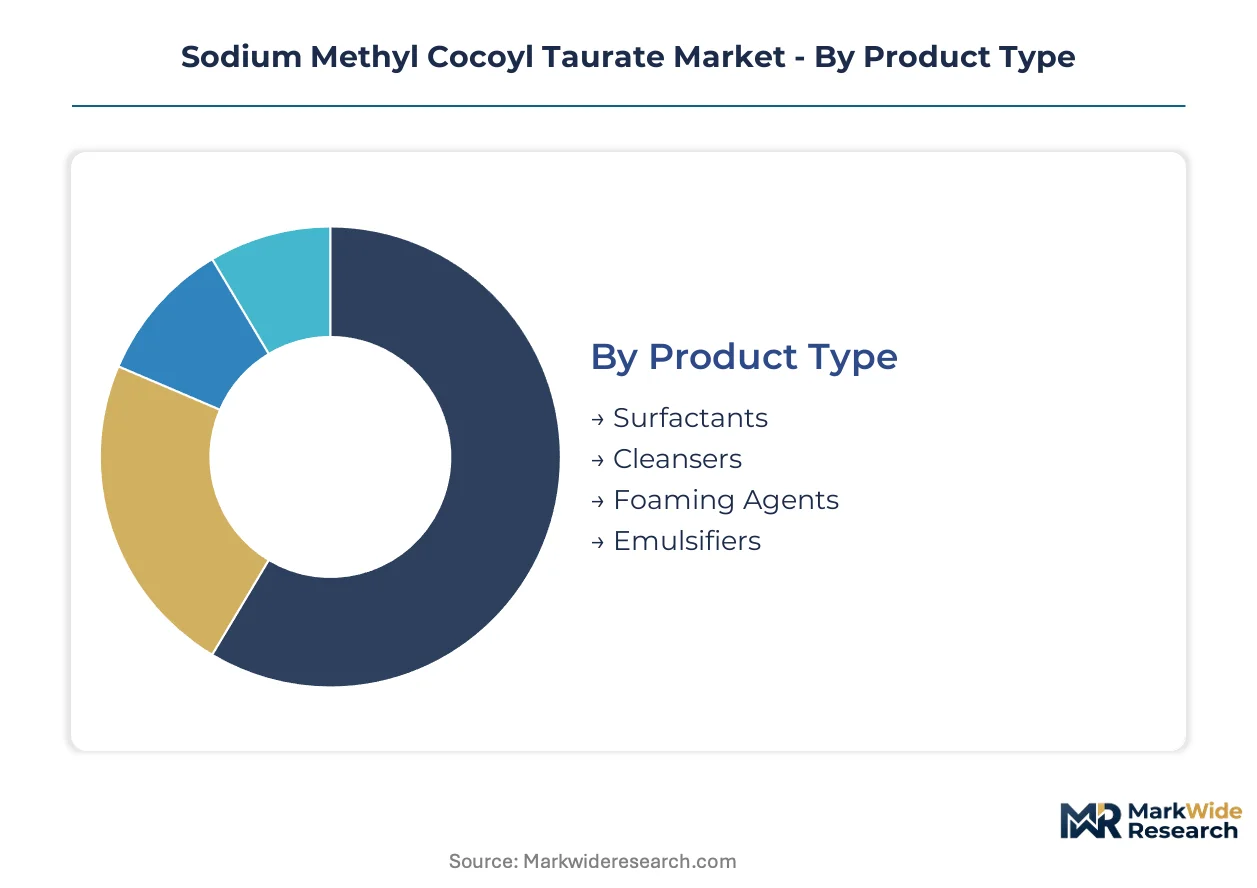
Segmentation in sodium methyl cocoyl taurate procurement reveals how formulation requirements, regulatory compliance burdens, and supply chain transparency demands fragment demand across distinct customer profiles. Understanding these divisions enables suppliers to align crystallization capacity, certification investments, and technical service resources with profit pools.
Product Type:
After-sales service intensity varies sharply across product categories, with surfactant grades requiring ongoing regulatory dossier maintenance and technical troubleshooting support.
- Surfactants:Primary anionic surfactant grades with 30-40% active matter content dominate sulfate-free shampoo and facial cleanser formulations. Demand concentrates among Guangdong and Jiangsu province cosmetic manufacturers seeking REACH-compliant alternatives to sodium lauryl sulfate.
- Cleansers:Mild cleansing bases with pH 5.5-6.5 compatibility serve dermatologist-recommended sensitive-skin product lines. German and French formulators lead procurement as EU Green Deal chemistry mandates accelerate substitution from conventional sulfates.
- Foaming Agents:High-foam stability variants for hard water conditions.
- Emulsifiers:Secondary surfactant functions in cream and lotion systems.
Surfactants hold the largest share; momentum sits with cleansers as sensitive-skin positioning expands.
Application:
Cost tier differentiation separates premium cosmetic grades from commodity industrial formulations, with certification and documentation burdens driving price stratification.
- Personal Care:Premium-grade taurates for shampoo, body wash, and facial cleansing applications requiring full REACH registration and RSPO mass balance documentation. North American clean beauty brands in California and New York bypass distributors to contract directly with manufacturers for supply chain transparency.
- Cosmetics:Refined grades for color cosmetics and skincare with stringent heavy metal and microbiological specifications. SAMR's GB standard enforcement in China elevates testing documentation requirements that favor established suppliers with existing dossiers.
- Household Cleaning:Cost-optimized powder grades for laundry and surface cleaners.
- Industrial Cleaning:Bulk liquid concentrates where thermal stability constraints above 40°C limit high-temperature processing applications.
Personal care commands premium pricing; cosmetics is expanding most quickly as ingredient transparency regulations tighten.
Form:
Volume concentration in liquid grades reflects personal care formulation preferences, while powder investments target industrial scale economies.
- Liquid:Ready-to-use aqueous solutions with 25-35% active content preferred by cosmetic contract manufacturers for direct formulation integration. Korean and Chinese producers retrofit continuous flow reactor systems to compress batch-to-batch variability in liquid grade output.
- Powder:Spray-dried crystalline forms for cost-sensitive industrial buyers prioritizing bulk handling and extended shelf stability. Integration of continuous crystallization with fluidized bed drying reduces production costs for cleaning compound manufacturers.
- Gel:Pre-thickened bases for premium facial cleanser positioning.
- Cream:Specialized emulsion concentrates for skincare applications.
Liquid holds the largest share; powder gains share fastest as spray-drying equipment convergence lowers unit costs.
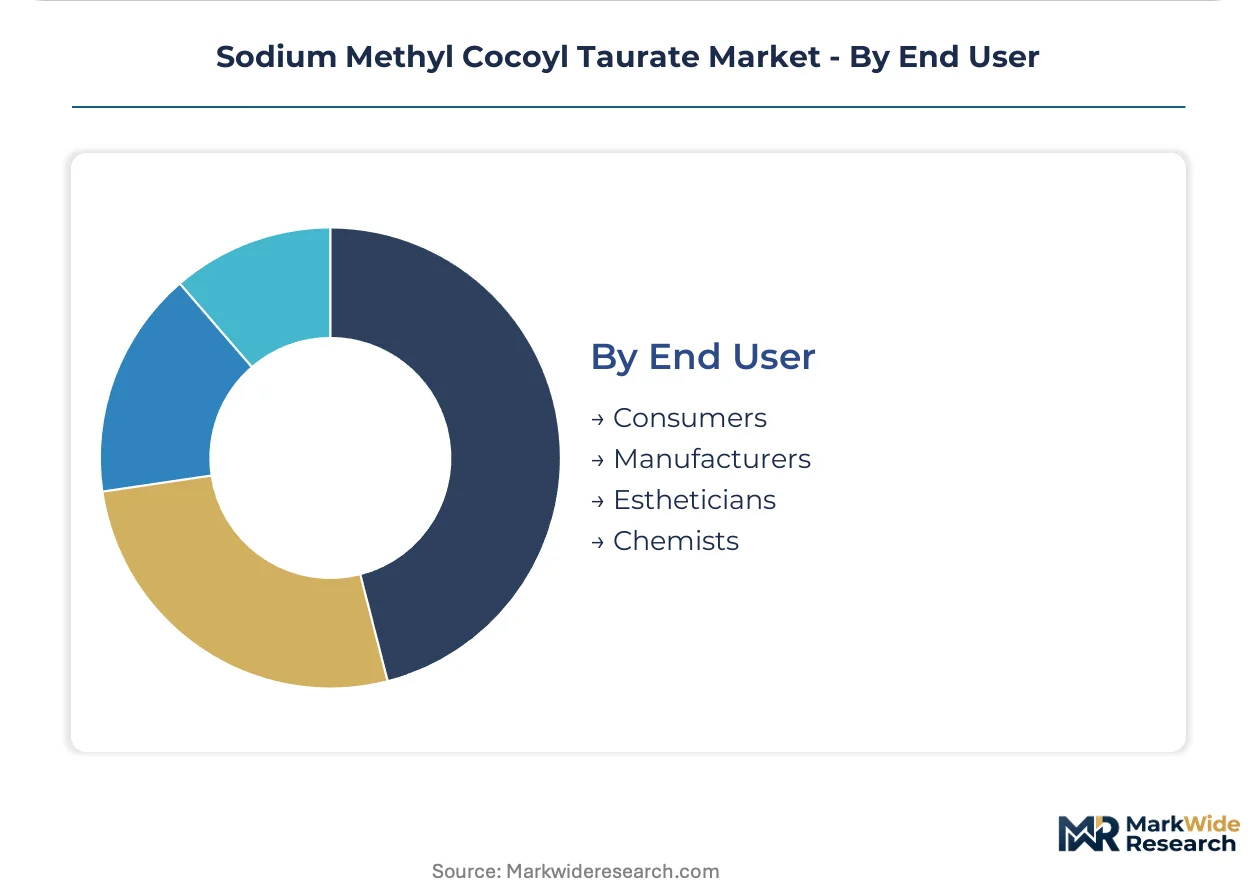
End User:
Customer type determines procurement sophistication, with manufacturers demanding full technical documentation and consumers prioritizing finished-product performance claims.
- Manufacturers:Cosmetic and cleaning compound producers requiring batch-specific certificates of analysis, stability data, and REACH SCIP database compliance documentation. German brands now mandate extended safety data sheets with exposure scenario annexes.
- Consumers:Individual purchasers of finished personal care products where sulfate-free and sensitive-skin labeling drives brand selection. Underpenetrated tier-2 and tier-3 Indian cities create education and sampling whitespace for mild surfactant positioning.
- Estheticians:Professional skincare service providers seeking pH-neutral formulations for treatment protocols.
- Chemists:R&D laboratories evaluating taurate performance in prototype formulations.
Manufacturers hold the largest share; consumers show the steepest expansion trajectory as direct-to-indie-brand disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration burdens and the EU Green Deal chemistry mandates are redirecting procurement toward bio-based taurate surfactants across multiple jurisdictions. China's SAMR enforcement of GB cosmetic standards elevates documentation requirements for imported ingredients. India personal care penetration in secondary cities creates whitespace for sulfate-free surfactant education.
China
Guangdong and Jiangsu province formulators scale domestic taurate procurement to serve emerging local beauty brands. SAMR's GB standard enforcement elevates testing documentation requirements that favor established suppliers with existing dossiers. Foshan Hytop New Material and Puji Biology are expanding crystallization and spray-drying capacity to serve regional cosmetics manufacturers.
Germany
German cosmetic brands now mandate extended safety data sheets with exposure scenario annexes under REACH SCIP database requirements. The EU F-Gas Regulation indirectly pressures formulators toward lower-ecotoxicity chemistries. Cologne and Düsseldorf industrial clusters concentrate dermatologist-recommended cleanser production for eczema-prone populations.
United States
FDA oversight of cosmetic labeling under the Modernization of Cosmetics Regulation Act adds compliance layers for market participants. North American clean beauty startups in California and New York contract directly with manufacturers, bypassing regional chemical distributors. This disintermediation prioritizes supply chain transparency over working capital flexibility.
India
Underdeveloped sulfate-free shampoo adoption in tier-2 and tier-3 cities creates whitespace for mild surfactant education and sampling. BIS standards for cosmetic ingredient safety are elevating testing burdens for imported taurates. Mumbai and Ahmedabad industrial corridors concentrate contract manufacturing for domestic personal care brands.
France
ANSM cosmetic safety assessments align with ECHA REACH registration timelines for surfactant suppliers. Paris-based formulators lead procurement of pH-neutral anionic surfactants for sensitive-skin positioning. The Île-de-France region anchors premium facial cleanser R&D for export-oriented beauty brands.
Sodium Methyl Cocoyl Taurate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated procurement relationships. The vendor base organizes into three tiers: multinational chemical conglomerates with ethoxylation infrastructure, regional oleochemical processors with coconut oil fractionation capabilities, and domestic Chinese manufacturers scaling crystallization capacity. Competitive moves center on backward integration into feedstock supply and RSPO mass balance certification investments.
Among multinational chemical conglomerates, Croda International and BASF occupy positions emphasizing sustainable supply chain documentation. Galaxy Surfactants and Stepan Company exemplify regional processors with captive oleochemical infrastructure. Foshan Hytop New Material and Puji Biology represent the domestic Chinese tier scaling spray-dried powder capacity for cost-sensitive industrial buyers.
| Leading Market Players |
|---|
| Croda International |
| BASF |
| Galaxy Surfactants |
| Clariant |
| Evonik Industries |
| Stepan Company |
| Innospec |
| Foshan Hytop New Material |
| Puji Biology |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into taurate surfactant landed costs, compressing margins for European formulators while amplifying price differentiation between RSPO-certified and conventional grades. Coconut oil procurement concentration in Southeast Asian trading hubs creates asymmetric bargaining power that downstream buyers absorb through tiered pricing structures.
Pricing Analysis
Certification level creates the primary spread between premium and commodity grades, with REACH-registered and RSPO-mass-balance-certified taurates commanding substantial premia over standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects documentation intensity, with German cosmetic manufacturers least price-sensitive due to regulatory compliance requirements and industrial cleaning compounders most sensitive to unit economics. Pricing pressure stems from Philippine and Indonesian crude coconut oil supply disruptions that transmit volatility directly into feedstock costs. Powder grades for industrial applications face the steepest cost compression as Chinese spray-drying capacity expansion intensifies competition.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for established taurate suppliers serving multinational personal care brands, straining working capital for smaller manufacturers. Supply concentrates in China, India, and Germany, with Guangdong province crystallization capacity and North American ethoxylation infrastructure anchoring regional supply. Raw material dependencies center on coconut oil fractionation, petrochemical-derived taurine from Japanese and Chinese producers, and methylating agents. Single-source vulnerability in taurine feedstock creates structural risk if specialty chemical producers consolidate. Distribution runs through direct manufacturer relationships for clean beauty brands and regional chemical distributors for industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor digitization and REACH SCIP database compliance are converging to disrupt competitive positioning in sodium methyl cocoyl taurate manufacturing, favoring suppliers with capital-intensive process control investments and regulatory dossier depth.
For Market Incumbents: Build regulatory dossier moats by accelerating REACH registration completion and RSPO mass balance certification ahead of EU Green Deal enforcement timelines. Deepen backward integration into coconut oil fractionation to secure feedstock margins against Philippine supply volatility. Expand crystallization capacity in Jiangsu province to serve Chinese domestic brand procurement growth. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 personal care markets where sulfate-free surfactant education creates whitespace before multinational incumbents scale distribution. Target spray-dried powder grades for Southeast Asian industrial cleaning compounders seeking cost-optimized alternatives to liquid concentrates. Leverage supply chain finance facilities to match incumbent payment terms. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates divesting non-core surfactant divisions to refocus on specialty pharmaceutical or agrochemical verticals. Mid-term viability hinges on regulatory chemistry expertise and captive oleochemical infrastructure. Watch for SAMR enforcement acceleration in China as the signal indicating consolidation pressure on import-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Oil Fractionation | Galaxy Surfactants and Stepan Company secure feedstock margins against Philippine supply disruptions. |
| Continuous Flow Reactor Retrofit | Korean and Chinese manufacturers compress batch-to-batch variability through real-time pH monitoring systems. |
| RSPO Mass Balance Certification Investment | Croda International differentiates supply chains for EU Green Deal compliance in German cosmetic manufacturing. |
| Direct-to-Brand Distribution Bypass | California clean beauty startups contract with Indian and Chinese taurate manufacturers for transparency. |
| Spray-Drying Capacity Expansion | Foshan Hytop New Material and Puji Biology target cost-sensitive industrial cleaning compounders. |
Research Methodology
Cross-validation between primary interviews with surfactant procurement managers, regulatory affairs directors at cosmetic formulators, plant engineers at oleochemical facilities, and secondary validation through ECHA REACH registration databases, SAMR GB standard filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation across product grade, application end-use, and regional production hub segmentation dimensions integrates with top-down macroeconomic calibration.
Calibration against historical capacity utilization rates and feedstock cost trajectories informs the analytical framework across the projection horizon. Modeled segmentation spans surfactant grade tier, personal care versus industrial end-use, liquid versus powder form factor, and regional regulatory cluster. CAGRs derive from slope analysis of segment-level demand curves and supply-side capacity additions. Coconut oil price volatility indices and REACH compliance cost burdens serve as industry-specific forecast inputs.
Stress conditions across Philippine crude coconut oil supply disruptions, EU F-Gas Regulation enforcement intensity, and Chinese domestic brand procurement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and feedstock cost transmission. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Isopropyl Myristate Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Global Surfactants Market
Surfactants
Wetting Agents Market
Surfactants
Waxing Sponge Market
Surfactants
Global Biosurfactant Market
Surfactants
Lauramide DEA Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Calcium Stearoyl-2 Lactylate Market