
 Global Calcium Sulfonate Market | 2026-2036
Global Calcium Sulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Calcium Sulfonate Market Foresight
North American petrochemical producers is consolidating calcium sulfonate supply capacity around integrated lubricant additive complexes. ExxonMobil Corporation leverages its Gulf Coast refining footprint to sustain backward integration into sulfonate precursor streams. Lanxess AG competes through specialized corrosion inhibitor grades for marine applications. Chevron Corporation anchors its position via controlled distribution to North American heavy machinery OEMs.
Calcium sulfonate denotes a family of overbased alkaline-earth soaps synthesized through carbonation of calcium hydroxide in mineral oil, yielding total base numbers typically exceeding 300 mg KOH/g for marine and industrial lubricant formulations. These compounds function primarily as rust-preventive detergents and extreme-pressure grease thickeners in high-load bearing environments. The lubricant segment dominates value capture due to OEM specification lock-in across construction and agriculture equipment. Metalworking fluids represent the fastest-growing application category as precision machining intensifies in India and Vietnam. Paste formulations command premium positioning in marine grease applications where water washout resistance determines procurement decisions.
EPA registration requirements govern environmental release profiles for calcium sulfonate additives deployed in US marine and agricultural equipment, while REACH restricts certain phenate co-additives in European formulations. China's MEE enforces discharge standards on metalworking fluid waste streams containing sulfonate residues, redirecting demand toward biodegradable alternatives. Stakeholders must monitor evolving OEM factory-fill specifications and regional chemical registration timelines to align capacity investments with compliant formulation portfolios.
Market Dynamics
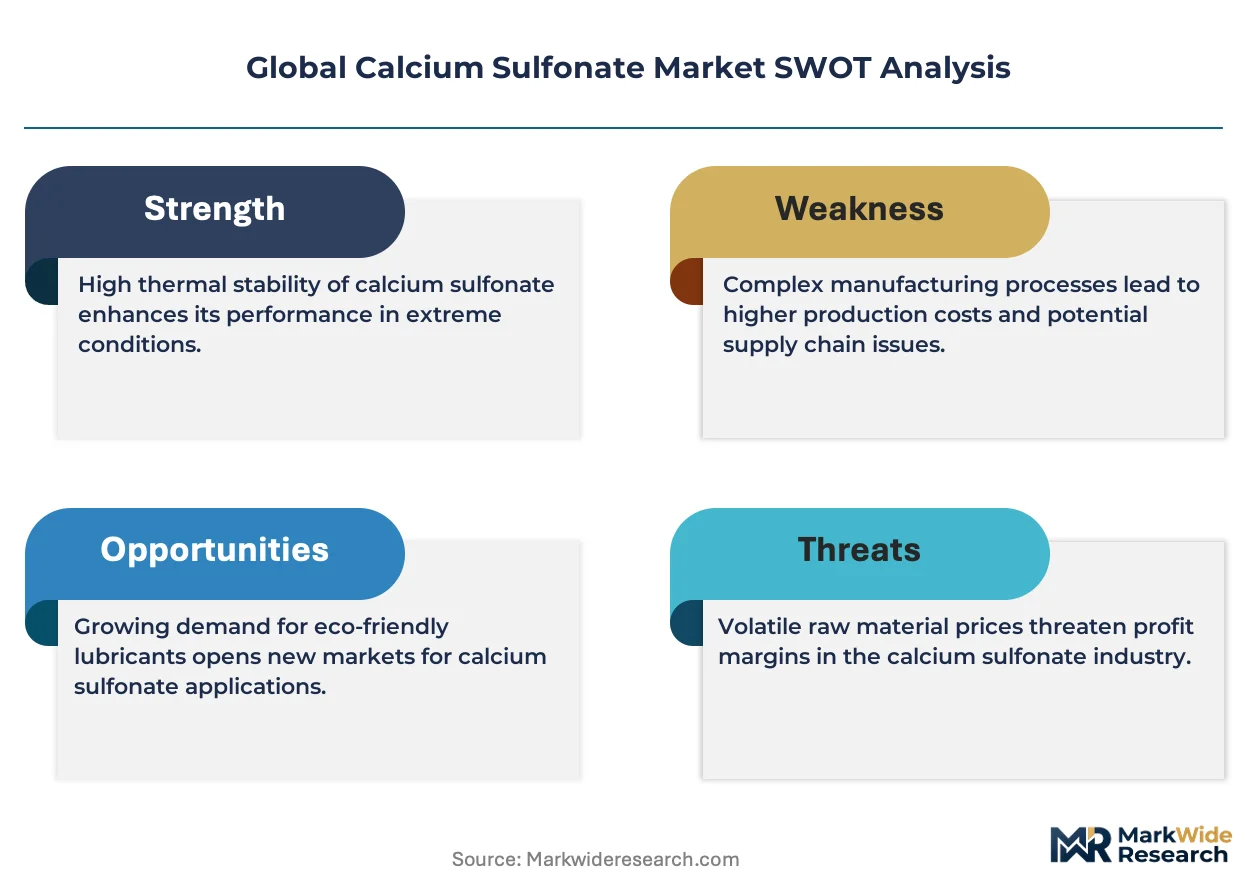
Equipment manufacturers are compressing lubricant service intervals to extend machinery uptime, forcing additive suppliers to reformulate calcium sulfonate greases for higher thermal stability and longer drain periods. This operational pressure is restructuring procurement relationships between lubricant blenders and sulfonate producers.
Growth Catalysts
- REACH additive restrictions:ECHA's tightening limits on phenate co-additives are compelling European formulators to upgrade calcium sulfonate grades, creating specification-driven replacement cycles across marine and industrial lubricant portfolios.
- Construction equipment OEMs:Manufacturers of excavators and wheel loaders in Germany and Japan are mandating factory-fill greases with 400+ TBN ratings, locking in sulfonate demand for high-load bearing applications.
- Carbonation process advances:Continuous reactor technologies are improving overbasing efficiency, enabling producers to achieve higher total base numbers without escalating calcium hydroxide feedstock consumption.
Market Restraints
- Laboratory-grade calcium hydroxide supply:Purified feedstock availability concentrates among Chinese and German chemical processors, exposing sulfonate manufacturers to input cost volatility and qualification delays.
- Polyurea grease substitution:Synthetic thickener technologies are displacing calcium sulfonate in certain high-temperature automotive bearing applications where water resistance is secondary.
- EPA marine discharge scrutiny:Registration requirements for lubricant additives used in US commercial vessels are extending formulation approval timelines and elevating compliance expenditures.
Strategic Opportunities
- Vietnam precision machining expansion:Metalworking fluid demand from electronics and aerospace component manufacturers is outpacing local sulfonate blending capacity, creating import substitution openings.
- Biodegradable marine grease segment:China's MEE discharge standards on sulfonate-containing waste streams are redirecting procurement toward ester-modified calcium sulfonate pastes with enhanced biodegradation profiles.
- Direct OEM contracting models:Heavy machinery manufacturers in India are bypassing traditional distributor networks to negotiate multi-year sulfonate supply agreements with guaranteed volume commitments.
Industry Challenges
- Carbonation reactor scale-up expertise:Engineering talent capable of designing continuous overbasing systems for 300+ TBN production remains concentrated among a limited pool of specialized process designers.
- OEM specification harmonization delays:Divergent factory-fill grease standards across construction, agriculture, and marine equipment segments are fragmenting R&D investment and extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Calcium Sulfonate Market |
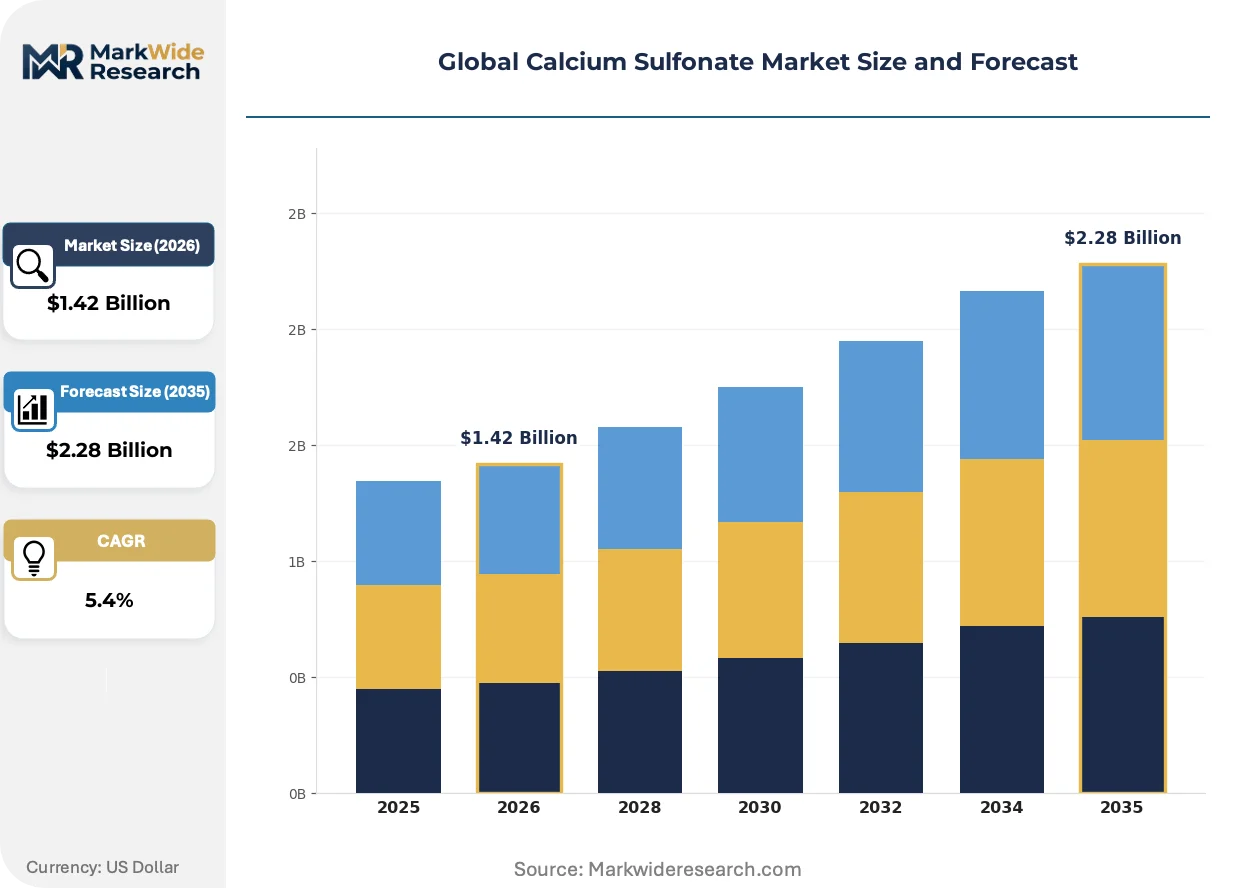
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickener, Base Oil, Additive, Detergent, Corrosion Inhibitor, Lubricant Application: Engine Oil, Gear Oil, Hydraulic Fluid, Compressor Oil, Grease, Metalworking Fluids End User Industry: Marine Equipment, Heavy Machinery, Automotive Manufacturers, Aerospace Equipment, Construction Equipment, Agriculture Equipment Form: Powder, Paste, Liquid, Solid |
| Companies Covered | King Industries, ExxonMobil Corporation, Lanxess AG, Chevron Corporation, Shell plc, The Lubrizol Corporation, Dover Chemical Corporation, Baker Hughes, Afton Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Calcium Sulfonate Market Shifts & Advancements
Digital process control and predictive maintenance integration are transforming how calcium sulfonate formulations are validated and deployed. These shifts are compressing development timelines while elevating performance verification standards.
Continuous carbonation reactor systems with real-time pH monitoring are automating overbasing consistency. European lubricant blenders are adopting these platforms to reduce batch-to-batch TBN variation. This automation is compressing quality assurance overhead and enabling just-in-time sulfonate paste production.
REACH authorization requirements for certain phenolic antioxidants are forcing reformulation of marine lubricant packages. The regulation is accelerating R&D investment in phenate-free calcium sulfonate complexes. Marine OEMs in Germany and the Netherlands are responding by pre-qualifying alternative additive systems ahead of sunset dates.
Buyer consolidation among North American heavy machinery rental fleets is consolidating lubricant procurement decisions. Equipment lessors are unbundling maintenance service contracts from original supply agreements, creating direct purchasing relationships with sulfonate producers. This behavioral shift is most visible in Texas and Alberta oilfield service equipment markets.
Global Calcium Sulfonate Market Segmentation
Calcium sulfonate producers configure their manufacturing assets around distinct specification tiers. Each segment demands unique carbonation reactor setups and feedstock purification levels, fragmenting supply capacity across incompatible production lines.
Product Type:
Supply concentration for high-TBN intermediates sits with integrated lubricant additive complexes in the US Gulf Coast and Germany's Rhine corridor.
- Thickener:Overbased calcium sulfonate pastes with 300-400 mg KOH/g ratings form the structural matrix for extreme-pressure greases. Demand concentrates in German and Japanese construction equipment OEM factory-fill specifications.
- Lubricant:Fully formulated calcium sulfonate greases capture premium positioning through specification lock-in with heavy machinery manufacturers. Procurement from Indian and Chinese mining equipment operators is accelerating as service interval extension becomes a competitive priority.
- Base Oil:Sulfonate-modified mineral oil carriers serve as formulation intermediates for marine lubricant blenders.
- Additive:Concentrated detergent packages integrate with phenate-free antioxidant systems for REACH-compliant European formulations.
- Detergent:High-alkalinity sulfonates neutralize acidic combustion byproducts in marine engine oils.
- Corrosion Inhibitor:Specialized grades protect offshore platform equipment in North Sea and Gulf of Mexico environments.
Lubricant absorbs the bulk of installed capacity; thickener is expanding most quickly.
Application:
Cost tier differentiation separates specification-grade formulations from commodity blending stocks, with marine and aerospace applications commanding 40-60% premia over industrial grades.
- Grease:Calcium sulfonate complex greases deliver water washout resistance and thermal stability for high-load bearings. German excavator manufacturers mandate 400+ TBN factory-fill grades, locking in sulfonate demand through multi-year supply agreements.
- Metalworking Fluids:Soluble oil formulations with sulfonate emulsifiers serve precision machining operations. Vietnam's electronics component manufacturers are outpacing local blending capacity, creating import substitution openings for regional suppliers.
- Engine Oil:Marine diesel formulations rely on overbased sulfonates for acid neutralization during extended voyages.
- Gear Oil:Hypoid gear lubricants incorporate sulfonate detergents for extreme-pressure protection.
- Hydraulic Fluid:Anti-wear packages with sulfonate rust inhibitors protect construction equipment in humid climates.
- Compressor Oil:Rotary screw formulations use sulfonate dispersants to manage varnish deposition.
Grease captures the dominant share of formulation R&D investment; metalworking fluids are climbing the fastest.
End User Industry:
Customer type fragmentation forces producers to maintain parallel qualification tracks for OEM factory-fill, aftermarket service-fill, and MRO distributor channels.
- Heavy Machinery:Mining trucks, excavators, and wheel loaders specify calcium sulfonate greases for 500-hour plus service intervals. Procurement consolidation among North American rental fleets is unbundling maintenance contracts from equipment supply agreements.
- Construction Equipment:OEM factory-fill specifications in Germany and Japan require 400+ TBN ratings with documented thermal stability testing. These standards are extending qualification timelines for new sulfonate entrants.
- Marine Equipment:Commercial vessel operators face EPA registration requirements for lubricant additives, elevating compliance expenditures and extending formulation approval timelines.
- Automotive Manufacturers:Polyurea grease substitution is displacing calcium sulfonate in high-temperature bearing applications where water resistance is secondary.
- Aerospace Equipment:Precision bearing greases demand laboratory-grade feedstock consistency with batch-to-batch TBN variation below 5%.
- Agriculture Equipment:Seasonal operating patterns favor cost-optimized sulfonate grades with standard 300 TBN ratings.
Heavy machinery commands the largest volume commitments; construction equipment is gaining share fastest.
Form:
Geographic variation in handling infrastructure favors paste and liquid formats in mature markets, with powder gaining traction in emerging manufacturing clusters.
- Paste:Concentrated calcium sulfonate pastes with 50-70% active content enable just-in-time grease manufacturing at blender facilities. European lubricant compounders are adopting continuous carbonation reactor systems to reduce batch-to-batch variation.
- Liquid:Pre-diluted sulfonate solutions simplify metalworking fluid formulation for precision machining operations in India and Vietnam.
- Powder:Spray-dried sulfonate powders serve regional grease manufacturers lacking paste handling infrastructure.
- Solid:Flaked and extruded formats support specialty corrosion inhibitor applications with controlled dissolution rates.
Paste dominates value capture through specification-grade positioning; liquid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory-grade calcium hydroxide feedstock availability concentrates among Chinese and German chemical processors, anchoring regional production advantages and exposing sulfonate manufacturers to input cost volatility across manufacturing clusters.
United States
Gulf Coast petrochemical complexes sustain backward integration into sulfonate precursor streams for marine and industrial lubricant formulations. EPA registration requirements govern environmental release profiles for additives deployed in commercial vessels and agricultural equipment. Houston-area refining corridors concentrate integrated lubricant additive manufacturing capacity serving North American heavy machinery OEMs.
Germany
Rhine corridor chemical processors dominate high-TBN intermediate supply for construction equipment factory-fill specifications. ECHA's REACH restrictions on phenate co-additives compel formulators to upgrade calcium sulfonate grades across marine lubricant portfolios. Marine OEMs in Hamburg and the Netherlands are pre-qualifying alternative additive systems ahead of regulatory sunset dates.
China
Purified calcium hydroxide feedstock production concentrates among domestic chemical processors serving integrated sulfonate manufacturing. MEE discharge standards on metalworking fluid waste streams redirect demand toward biodegradable ester-modified calcium sulfonate pastes. Yangtze River Delta electronics manufacturers are outpacing local sulfonate blending capacity for precision machining applications.
India
Mining equipment operators are accelerating procurement of calcium sulfonate greases as service interval extension becomes competitive priority. Central Pollution Control Board enforcement on industrial effluent discharge elevates compliance requirements for metalworking fluid formulations. Heavy machinery manufacturers in Maharashtra and Gujarat are negotiating multi-year sulfonate supply agreements with guaranteed volume commitments.
Vietnam
Electronics and aerospace component manufacturers are expanding precision machining operations faster than local sulfonate blending capacity can accommodate. Provincial environmental regulations on industrial wastewater discharge are tightening formulation standards for metalworking fluid emulsifiers. Northern manufacturing zones around Hanoi and Hai Phong are creating import substitution openings for regional sulfonate suppliers.
Global Calcium Sulfonate Market Competitive Landscape
Global majors compete with regional champions across integrated additive manufacturing and specialized corrosion inhibitor formulations. Market structure tilts toward consolidation around Gulf Coast and Rhine corridor refining complexes, with mid-tier blenders occupying specification-grade niches. Three archetypes dominate: integrated petrochemical majors with captive sulfonate streams, specialized additive houses focusing on REACH-compliant marine grades, and regional blenders serving OEM factory-fill contracts. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure qualified feedstock supply.
Within the integrated petrochemical tier, ExxonMobil Corporation and Chevron Corporation exemplify backward integration strategies leveraging Gulf Coast refining footprints. Lanxess AG occupies a specialist position among European additive houses, while The Lubrizol Corporation and Afton Chemical represent the formulation technology tier serving diversified industrial applications. King Industries anchors the corrosion inhibitor specialist segment. These companies collectively illustrate how geographic proximity to feedstock and regulatory compliance capabilities determine competitive positioning across specification-driven procurement cycles.
| Leading Market Players |
|---|
| King Industries |
| ExxonMobil Corporation |
| Lanxess AG |
| Chevron Corporation |
| Shell plc |
| The Lubrizol Corporation |
| Dover Chemical Corporation |
| Baker Hughes |
| Afton Chemical |
| Others |
Supply & Pricing Matrix
Family-owned German chemical processors anchor laboratory-grade calcium hydroxide production, concentrating feedstock ownership among a tight circle of Rhine corridor specialists and Rhine-Ruhr family enterprises. This ownership pattern tightens pricing discipline across sulfonate tiers, as procurement managers at lubricant blenders face limited alternative sources for purified inputs meeting 400+ TBN specifications.
Pricing Analysis
Warranty and service-bundling unbundling is restructuring how calcium sulfonate greases transact, with North American heavy machinery rental fleets separating maintenance contracts from equipment supply agreements. Three-tier pricing structure across premium, standard, and economy levels reflects total base number ratings, REACH compliance certification, and documented thermal stability testing. Pricing pressure stems from polyurea grease substitution in automotive bearing applications where water resistance carries less weight. Construction equipment OEMs show least price sensitivity due to factory-fill specification lock-in, while agriculture equipment operators favor cost-optimized 300 TBN grades.
Supply Chain Analysis
Laboratory-grade calcium hydroxide supply rests on Chinese and German chemical processors, with purified feedstock production concentrating among Yangtze River Delta and Rhine corridor specialists. Carbonation reactor systems, mineral oil carrier streams, and phenate-free antioxidant packages constitute critical input dependencies. Single-source vulnerability in qualified feedstock supply exposes sulfonate manufacturers to qualification delays and input cost volatility. Distribution runs through integrated lubricant additive complexes serving OEM factory-fill channels, with direct contracting models emerging among Indian heavy machinery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sulfonate precursor streams defines competitive positioning, as Gulf Coast refining footprints and captive calcium hydroxide supply determine margin sustainability across specification tiers.
For Market Incumbents: Acquire continuous carbonation reactor engineering talent to secure 300+ TBN production capability. Lock in multi-year laboratory-grade calcium hydroxide offtake agreements with Chinese and German processors before qualification queues lengthen. Polyurea grease substitution in high-temperature automotive bearings demands defensive R&D investment in ester-modified biodegradable formulations. For New Entrants and Emerging Players: The 40-60% premium gap between marine specification grades and industrial commodity sulfonates offers entry traction. Target Vietnam's precision machining metalworking fluid segment, where electronics component manufacturers outpace local blending capacity. Pursue import substitution positioning with liquid sulfonate solutions for soluble oil formulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier REACH-compliant additive houses in Germany's Rhine corridor with pre-qualified marine OEM relationships. Five-to-ten-year viability hinges on carbonation process automation capabilities and regulatory compliance infrastructure. Watch EPA marine discharge registration timelines as inflection signals for US commercial vessel additive demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Gulf Coast refiners securing captive calcium hydroxide streams reduce qualification dependency on Chinese processors. |
| Continuous Carbonation Reactor Deployment | Real-time pH monitoring systems compress batch-to-batch TBN variation for European marine lubricant blenders. |
| REACH-Compliant Formulation Upgrade | Phenate-free antioxidant packages preempt ECHA sunset dates for Hamburg marine OEM factory-fill contracts. |
| Direct OEM Contracting Model | Maharashtra heavy machinery manufacturers bypass distributor networks for guaranteed volume sulfonate commitments. |
| Biodegradable Marine Grease Development | Ester-modified calcium sulfonate pastes align with China's MEE discharge standards for Yangtze River Delta metalworking operations. |
Research Methodology
Document review covered customs and trade flow databases, chemical industry association reports, and regulatory filing repositories, complemented by interviews with lubricant additive R&D directors, heavy machinery OEM procurement leads, marine equipment maintenance supervisors, and calcium sulfonate plant managers. Secondary validation drew from EPA registration databases, ECHA authorization timelines, and SEC disclosures by integrated petrochemical majors. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Segment-level projections incorporated product type tiers, end-use industry fragmentation, and regional regulatory cluster variations. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Key inputs included construction equipment OEM factory-fill specification timelines, marine diesel engine fleet renewal rates, and precision machining intensity indices for Vietnam electronics manufacturing.
Underlying measurement precision varies by segment; lubricant and thickener product categories carry tighter precision than corrosion inhibitor specialties given specification standardization. Forecasts embed assumptions around REACH authorization sunset adherence and EPA marine discharge registration progression. A small set of triggers—carbonation reactor scale-up delays, laboratory-grade calcium hydroxide supply disruptions, and polyurea substitution acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Amino Silicone Oil Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Natural Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Global Methyl Soyate Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Surfactant EOR Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Polymer Surfactants Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Procream Market
Surfactants
Soap Salts Market
Surfactants
Defoamers Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Wetting Agents Market