
 Cetanol Market | 2026-2036
Cetanol Market Size, Share, and Industry Trends Forecast 2026-2036
Cetanol Market Analysis
Cosmetics formulation is recalibrating toward heavier cetanol loading in skin creams and hair conditioners as brands phase out petrochemical emollients. Croda International Plc leverages its oleochemical heritage to dominate premium cosmetic-grade supply across Europe and North America. Emery Oleochemicals Group anchors its position through backward integration into palm kernel and coconut feedstocks, securing cost-advantaged raw material access. Kao Corporation differentiates via proprietary high-purity distillation technology that meets Japan's stringent cosmetic ingredient standards.
Cetanol, or hexadecan-1-ol, is a saturated fatty alcohol with a sixteen-carbon straight-chain structure, typically produced through hydrogenation of palm or coconut oil-derived methyl esters or through the Ziegler process using ethylene oligomerization; it functions primarily as a consistency agent, emulsion stabilizer, and viscosity modifier across personal care and industrial formulations. The liquid product type occupies the largest volume share due to ease of handling in continuous cosmetic manufacturing, while solid and granular grades command margin premiums in pharmaceutical tablet coating applications where flow properties are critical. Surfactant applications lead absolute demand, though emulsifier use in clean-label cosmetics represents the fastest-expanding segment as formulators replace synthetic alternatives with plant-derived fatty alcohols.
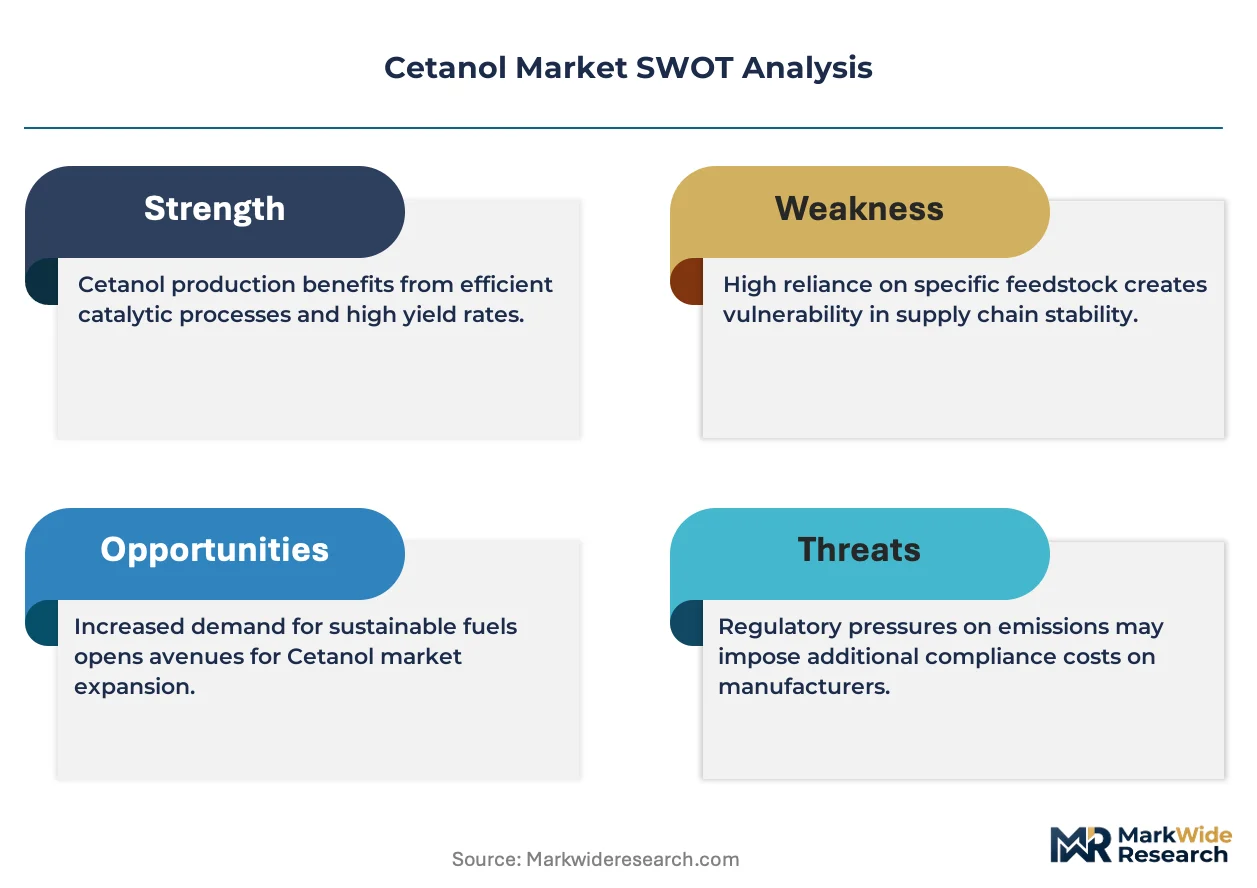
REACH registration requirements in Europe mandate full toxicological dossiers for cetanol imports above one tonne annually, elevating compliance costs for non-European suppliers while creating preferential access for ECHA-registered producers. The EPA's TSCA Section 5 premanufacture notification framework governs novel cetanol derivatives in the United States, slowing innovation cycles but ensuring environmental safety validation. India's BIS certification for cosmetic raw materials adds another layer of testing for exporters targeting the country's expanding personal care sector. Stakeholders must monitor feedstock volatility in palm and coconut oil markets alongside regulatory divergence across major economies to optimize supply chain positioning.
Market Dynamics
Cosmetic formulators are recalibrating emulsion architectures toward plant-derived consistency agents as clean-label mandates intensify across North America and Europe, compressing synthetic emollient demand while elevating cetanol procurement specifications.
Growth Catalysts
- REACH Registration Thresholds:ECHA's full toxicological dossier requirements above one tonne annually create preferential market access for registered European producers, consolidating compliant supply.
- Surfactant Manufacturing Scale-Up:China's domestic surfactant producers are expanding cetanol procurement volumes to serve personal care formulators across Asia-Pacific.
- Ziegler Process Refinement:Ethylene oligomerization advances are yielding higher-purity hexadecan-1-ol streams suitable for pharmaceutical-grade applications.
Market Restraints
- Palm Kernel Oil Volatility:Feedstock price swings in Malaysian and Indonesian palm derivatives compress margin predictability for hydrogenation-based producers.
- Import Compliance Burden:India's BIS certification for cosmetic raw materials adds testing layers that delay market entry for exporters.
- Synthetic Emollient Substitution:Petrochemical-derived alternatives maintain cost advantages in mass-market personal care despite clean-label headwinds.
Strategic Opportunities
- Pharmaceutical Tablet Coating:Solid and granular cetanol grades command margin premiums in drug delivery applications where flow properties determine formulation performance.
- EPA TSCA Section 5 Tailwinds:Pre-manufacture notification frameworks for novel derivatives create first-mover advantages for validated environmental safety dossiers.
- Japanese Cosmetic Standards:METI-aligned high-purity distillation capabilities open access to premium personal care markets with stringent ingredient specifications.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Staggered approval sequences across ECHA, EPA, and BIS systems delay product launches and strain working capital.
- Legacy Hydrogenation Asset Reconfiguration:Converting methyl ester hydrogenation capacity between feedstock types requires substantial capex and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetanol Market |
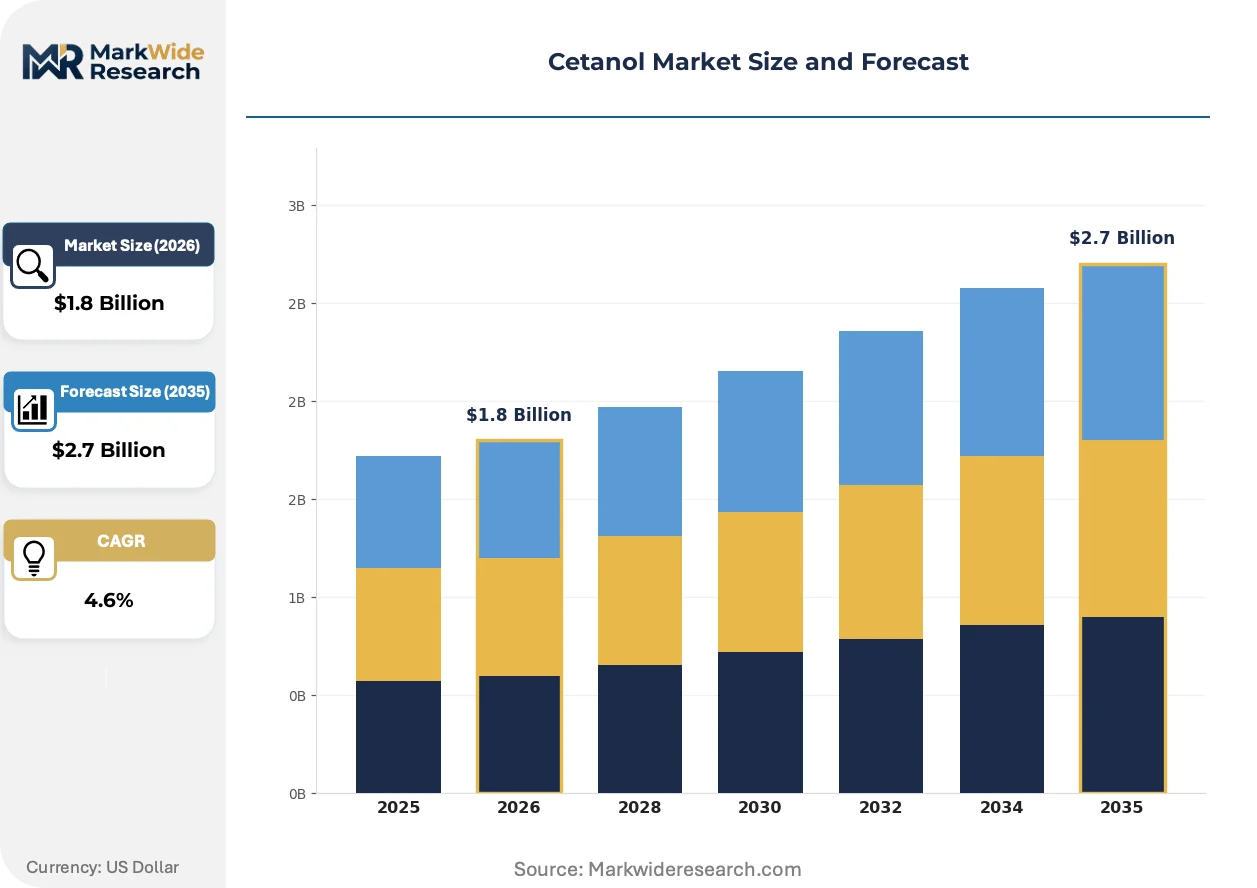
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Granular, Powder End Use Industry: Pharmaceuticals, Cosmetics, Food, Coatings Packaging Type: Drums, Bags, Bottles, Bulk Application: Surfactants, Emulsifiers, Solvents, Lubricants |
| Companies Covered | Croda International Plc, Emery Oleochemicals Group, BASF SE, VVF L.L.C., Stepan Company, Sasol Limited, Godrej Industries Limited, KOKYU ALCOHOL KOGYO CO., LTD, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetanol Market Emerging Trajectories
Formulation science is pivoting toward bio-based emulsion stabilizers as regulatory thresholds harden and consumer ingredient literacy deepens, reshaping raw material specification protocols across personal care value chains.
Membrane filtration technology is integrating into high-purity cetanol finishing trains, stripping residual impurities below parts-per-million thresholds required for ophthalmic and infant care formulations. Korean and Japanese cosmetic houses are adopting these systems fastest, compressing traditional distillation equipment replacement cycles and elevating capital intensity barriers for mid-scale producers.
REACH's 2024 substance evaluation work program is tightening impurity limits for fatty alcohols used in leave-on cosmetic products, forcing reformulation of legacy emulsion bases. European contract manufacturers are responding by dual-sourcing cetanol grades—pharmaceutical purity for sensitive-skin lines, technical grade for rinse-off applications—to maintain formulation flexibility without full portfolio re-registration.
Direct procurement relationships between cosmetic brand houses and oleochemical refiners are displacing traditional distributor intermediaries in North America and Western Europe. Large personal care conglomerates now mandate supplier sustainability certifications and feedstock traceability documentation that regional distributors cannot aggregate, compressing channel margins while securing supply continuity for volume buyers.
Cetanol Market Segmentation
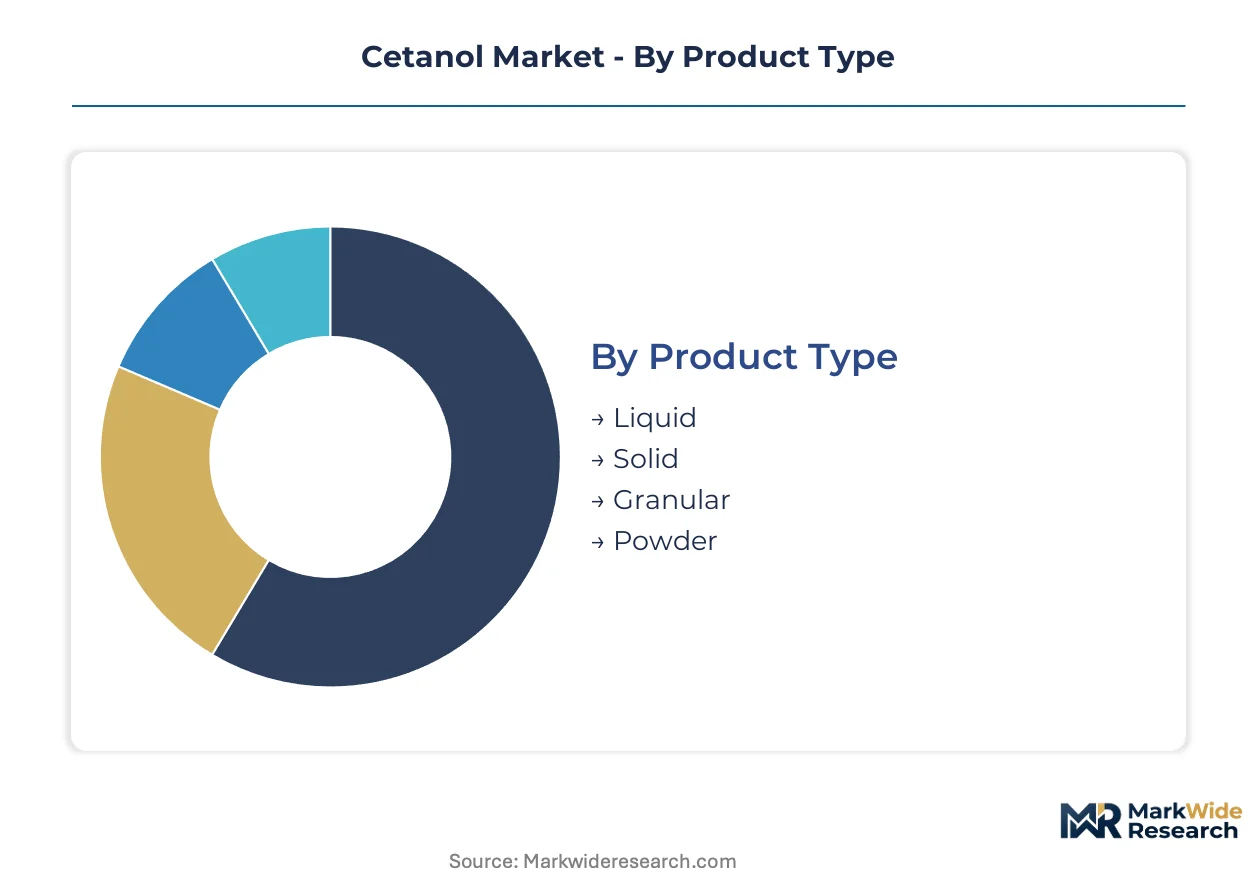
Cetanol procurement patterns diverge sharply across physical forms and end-use specifications, with pharmaceutical and cosmetic buyers imposing purity thresholds that industrial surfactant customers rarely match. Segmentation discipline separates margin-accretive specialty grades from commodity volumes, determining which producers capture premium positioning.
Product Type:
Handling economics and formulation integration costs dominate buyer selection between physical states.
- Liquid:Low-viscosity hexadecan-1-ol flows directly into continuous cosmetic manufacturing lines without melting infrastructure. Cosmetic formulators in Germany and the United States specify liquid grades for high-throughput emulsion production where temperature-controlled processing adds unacceptable overhead.
- Solid:Cast or flaked cetanol offers precise portion control in batch pharmaceutical compounding. Japanese drug manufacturers prefer solid formats for tablet coating operations where melt-point consistency determines batch uniformity.
- Granular:Free-flowing particulate morphology suits automated powder handling systems in food-grade applications. European food additive producers specify granular cetanol for anti-caking formulations where dust generation must stay below occupational exposure limits.
- Powder:Micronized particle size distribution enables rapid dissolution in solvent-based coating systems. Industrial coatings manufacturers in China source powder grades for metalworking fluid applications.
Liquid leads on scale; granular leads on momentum.
End Use Industry:
Regulatory stringency and formulation complexity create tiered margin structures across customer verticals.
- Cosmetics:Clean-label emulsion stabilizers command specification premiums as brands eliminate petrochemical emollients. REACH's tightening impurity limits for leave-on products are compressing technical-grade supply access for European formulators.
- Pharmaceuticals:USP-NF compliance and endotoxin testing add certification layers that exclude non-cGMP producers. Ophthalmic and parenteral applications demand membrane-filtration finishing that only specialized refiners provide.
- Food:EFSA and FDA food additive approvals limit supplier pools for direct-contact applications. Anti-foam and coating uses in confectionery drive procurement from oleochemical specialists with kosher and halal certifications.
- Coatings:Industrial metalworking and wood finish applications prioritize cost position over traceability. Mass-market lubricant blenders source technical-grade cetanol through distributor channels with minimal documentation requirements.
Cosmetics leads on scale; pharmaceuticals leads on momentum.
Packaging Type:
Supply chain configuration and consumption velocity determine packaging economics for different buyer profiles.
- Drums:Standard 200-liter steel drums serve mid-scale cosmetic compounders with monthly consumption rates below bulk tank thresholds. German and French contract manufacturers prefer drum delivery for formulation flexibility across multiple product lines.
- Bulk:Tank truck and ISO tank deliveries capture cost advantages for surfactant producers with dedicated storage infrastructure. Chinese and Indian surfactant manufacturers are expanding bulk procurement to match domestic personal care market expansion.
- Bags:Multi-wall paper or PE bags suit powder and granular grades where moisture protection is critical. Food additive distributors specify bagged formats for warehouse stacking efficiency and lot traceability.
- Bottles:Laboratory and pilot-scale quantities in amber glass or HDPE serve R&D formulation work. Cosmetic innovation labs in Japan and South Korea source bottle formats for preservative-free sampling protocols.
Bulk leads on scale; drums leads on momentum.
Application:
Functional performance requirements and substitution elasticity vary dramatically across use cases.
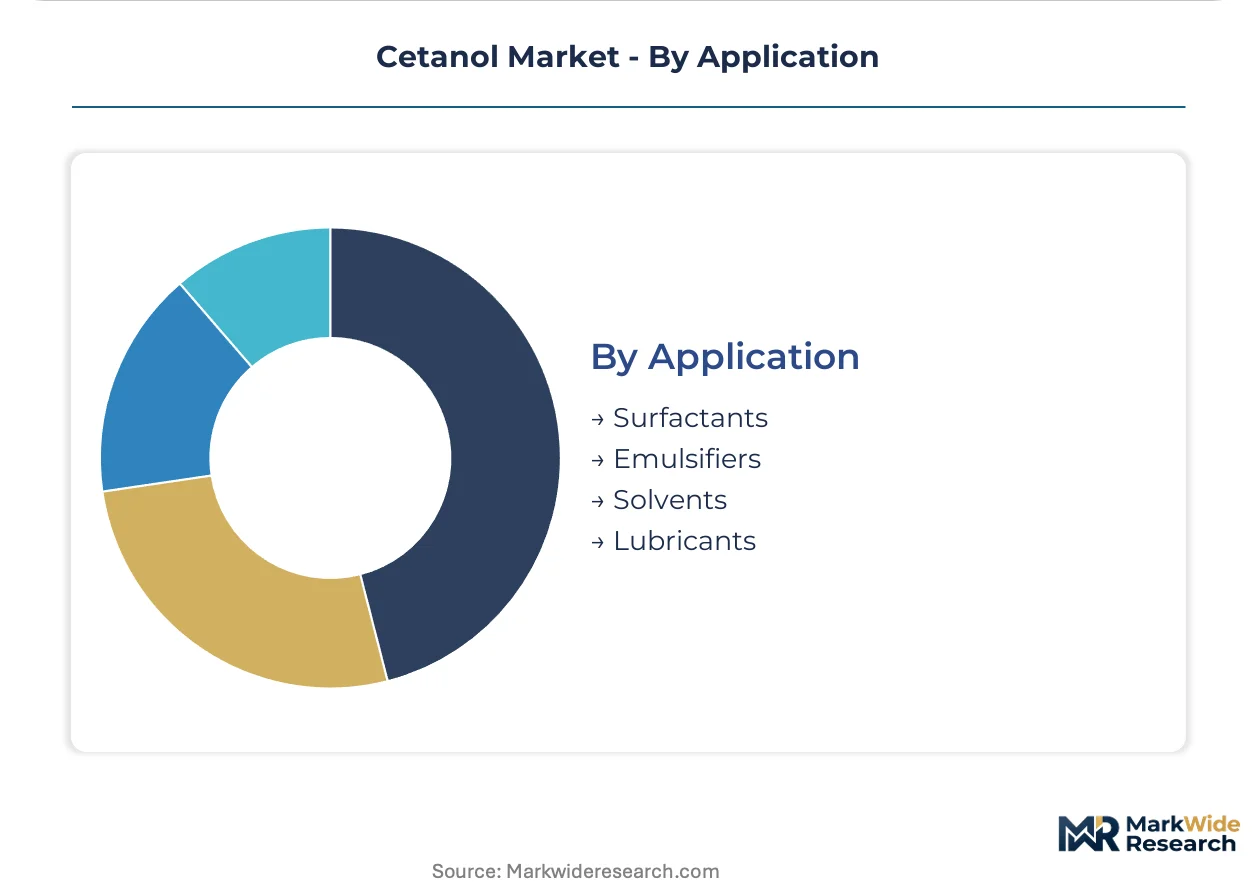
- Surfactants:Cetanol serves as a hydrophobic tail in non-ionic and cationic surfactant synthesis, with ethoxylation degrees tailored to HLB requirements. Asia-Pacific detergent and personal care surfactant production concentrates demand in China and Indonesia.
- Emulsifiers:O/W emulsion stabilization in skin creams and hair conditioners represents the steepest expansion trajectory as clean-label mandates intensify. European cosmetic houses are reformulating legacy bases to elevate plant-derived fatty alcohol loading.
- Solvents:Pharmaceutical extraction and coating solvent applications leverage cetanol's low toxicity profile relative to petrochemical alternatives. USP-grade solvent specifications restrict supply to cGMP-certified producers.
- Lubricants:Metalworking and textile processing applications exploit boundary lubrication properties at moderate temperatures. Southeast Asian textile manufacturers source technical-grade cetanol for fiber processing where biodegradability requirements are emerging.
Surfactants leads on scale; emulsifiers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping cetanol production geography as compliance cost gaps between jurisdictions widen. Manufacturers are relocating hydrogenation capacity toward jurisdictions with streamlined chemical registration frameworks while maintaining sales presence in high-specification markets.
United States
Personal care conglomerates in New Jersey and California are expanding cetanol loading in clean-label emulsion reformulations. EPA's TSCA Section 5 premanufacture notification framework governs novel derivative introductions, slowing innovation cycles but ensuring environmental validation. The Gulf Coast petrochemical corridor hosts ethylene oligomerization refiners supplying pharmaceutical-grade hexadecan-1-ol streams to domestic drug manufacturers.
Germany
REACH registration thresholds above one tonne annually elevate compliance costs for non-European suppliers, consolidating market access for ECHA-registered producers. The country's national chemical regulator maintains stringent toxicological dossier requirements that favor established oleochemical specialists. North Rhine-Westphalia's Ruhr industrial cluster anchors hydrogenation capacity serving cosmetic compounders across the Benelux region.
China
Domestic surfactant manufacturers in Jiangsu and Zhejiang provinces are scaling cetanol procurement to serve Asia-Pacific personal care markets. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for fatty alcohol hydrogenation facilities. The Yangtze River Delta concentration of oleochemical refiners is expanding membrane filtration finishing capacity for high-purity cosmetic grades.
Japan
METI-aligned high-purity distillation capabilities open access to premium personal care markets with stringent ingredient specifications. The country's national pharmaceutical regulator maintains exacting cosmetic ingredient standards that exclude non-specialized importers. Osaka-based cosmetic innovation labs are adopting pharmaceutical-grade cetanol for preservative-free sensitive-skin formulations.
India
BIS certification for cosmetic raw materials adds testing layers that delay market entry for exporters while creating protected domestic supply opportunities. The Bureau of Indian Standards mandates additional purity verification for fatty alcohols used in leave-on personal care products. Maharashtra's Mumbai-Pune industrial corridor hosts emerging surfactant manufacturers scaling cetanol consumption for domestic detergent and shampoo production.
Cetanol Market Vendor Landscape
Capacity expansion dominates the current landscape as producers race to capture pharmaceutical-grade certification tiers. The vendor base stratifies between integrated oleochemical majors with captive feedstock supply and specialized refiners competing on purity specifications. Three archetypes occupy distinct competitive terrain: palm kernel backward integrators controlling Malaysian and Indonesian supply chains, ethylene-based synthetic producers leveraging Ziegler process scale, and regional specialists with localized regulatory registrations. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players securing multi-jurisdictional chemical registrations to preempt competitor market access.
Among European-registered specialists, Croda International Plc exemplifies the premium cosmetic-grade archetype through its oleochemical heritage positioning. Emery Oleochemicals Group represents the backward-integrated feedstock controller archetype with its structural linkage to palm kernel and coconut derivatives. Kao Corporation occupies the high-purity distillation specialist tier, leveraging Japanese regulatory alignment for METI-compliant pharmaceutical and cosmetic ingredient supply.
| Leading Market Players |
|---|
| Croda International Plc |
| Emery Oleochemicals Group |
| BASF SE |
| VVF L.L.C. |
| Stepan Company |
| Sasol Limited |
| Godrej Industries Limited |
| KOKYU ALCOHOL KOGYO CO., LTD |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into Malaysian and Indonesian palm kernel estates anchors supply positioning for hydrogenation-based producers while simultaneously insulating their pricing power from feedstock volatility swings. This captive sourcing strategy compresses input cost variance and enables contract pricing that undercuts non-integrated competitors serving pharmaceutical and cosmetic grade markets.
Pricing Analysis
Distributor margins in European and North American channels are compressing as direct procurement relationships between cosmetic brand houses and oleochemical refiners displace traditional intermediaries. Three-tier pricing structure across pharmaceutical, cosmetic, and technical grades separates USP-NF certified supply from REACH-registered cosmetic grades and industrial surfactant volumes. Pricing pressure stems from palm kernel oil volatility in Southeast Asian feedstock markets. Mass-market surfactant manufacturers exhibit highest price sensitivity, while ophthalmic pharmaceutical formulators show minimal elasticity due to endotoxin testing requirements.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker shipments and packaged drum deliveries determine procurement economics for mid-scale compounders lacking dedicated storage infrastructure. Hydrogenation capacity concentrates in Malaysia, Indonesia, and Germany, with ethylene oligomerization streams anchored in the United States Gulf Coast and Chinese petrochemical corridors. Production draws from palm kernel oil, coconut oil methyl esters, and ethylene feedstocks. Single-source vulnerability persists for pharmaceutical-grade membrane filtration finishing, which only specialized refiners in Japan and Western Europe provide. Distribution runs through direct refiner-to-brand relationships for volume buyers, with regional distributors serving technical-grade industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers where endotoxin testing and membrane filtration capabilities exclude commodity competitors. Feedstock backward integration and REACH registration dossiers represent the primary cost-down and premium-shift levers respectively.
For Market Incumbents: Deploy membrane filtration capacity additions in Japan and Western Europe to capture ophthalmic and infant care formulation demand. Consolidate position by acquiring regional distributors with BIS certification capabilities in India. Synthetic emollient substitution in mass-market personal care threatens technical-grade volumes, requiring capacity reconfiguration toward cosmetic and pharmaceutical grades. For New Entrants and Emerging Players: EPA TSCA Section 5 premanufacture notification frameworks in the United States open a window for novel cetanol derivative introductions with validated environmental safety dossiers. Target pharmaceutical tablet coating applications in Japan where METI-aligned purity standards limit incumbent penetration. Pursue white-label supply agreements with Korean cosmetic innovation labs adopting preservative-free sensitive-skin formulations. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdictional certification timelines strain working capital for mid-scale producers lacking ECHA, EPA, and BIS registrations simultaneously. Long-term viability favors integrated oleochemical majors with captive palm kernel supply and established pharmaceutical-grade finishing infrastructure. Monitor REACH substance evaluation work program announcements for impurity limit tightening that would force legacy emulsion base reformulations and demand spikes for certified supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive palm kernel access in Malaysia and Indonesia insulates margin from commodity volatility. |
| Membrane Filtration Capacity Expansion | Japanese and Korean cosmetic houses adopt ppm-threshold finishing for sensitive-skin lines. |
| Multi-Jurisdictional Registration Investment | Simultaneous ECHA, EPA, and BIS compliance preempts competitor market access delays. |
| Direct Procurement Relationship Development | Cosmetic brand houses mandate sustainability traceability documentation distributors cannot aggregate. |
| Pharmaceutical-Grade Certification Upgrade | USP-NF and endotoxin testing layers exclude non-cGMP producers from drug delivery applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oleochemical plant managers, cosmetic procurement leads, pharmaceutical formulation scientists, and distribution channel partners with secondary validation from customs trade data, ECHA registration databases, SEC filings of listed oleochemical majors, and industry association reports. Bottom-up volume modeling across product types, end-use industries, and packaging formats triangulated against top-down macroeconomic drivers.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical, cosmetic, food, and coatings end-use verticals, with grade-specific purity thresholds and regulatory compliance requirements modeled as demand filters. CAGRs were derived from elasticity-adjusted consumption projections across the analysis window, incorporating feedstock price scenarios and capacity expansion announcements from major hydrogenation and ethylene oligomerization facilities.
Revisions become necessary when REACH substance evaluation programs tighten impurity limits, when Malaysian or Indonesian palm oil export policies shift, or when major cosmetic brand houses accelerate clean-label reformulation timelines. A model refresh is warranted upon material change in pharmaceutical-grade membrane filtration capacity utilization rates or EPA TSCA Section 5 notification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Emulsion Stabilizers Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Detergent Chemicals Market
Surfactants
MDEA Esterquats Market
Surfactants
Cationic Surfactants Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Zeolite for Detergents Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Natural Surfactants Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Dodecanol Market
Surfactants
Microemulsions Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market