
 North America Non-Ionic Surfactants Market | 2026-2036
North America Non-Ionic Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Ionic Surfactants Market Analytics
Canada is fragmenting its non-ionic surfactant supply base as domestic blenders seek alternatives to imported ethoxylate feedstock. BASF SE leverages its integrated ethylene oxide infrastructure along the US Gulf Coast to sustain cost-advantaged supply. Dow Inc. anchors North American capacity through its alcohol ethoxylate network serving industrial cleaning customers. Stepan Company differentiates via specialty sorbitan esters for food-grade applications.
Non-ionic surfactants are amphiphilic compounds lacking dissociable charge groups, typically synthesized through ethoxylation of fatty alcohols or esterification of polyols, with hydrophilic-lipophilic balance values spanning 8 to 18 for broad emulsification utility. Ethoxylates dominate volume shipments across the region due to decades of process optimization and established downstream compatibility. Alkyl polyglucosides represent the fastest-expanding product category as formulators phase out alkylphenol ethoxylates under pressure from EPA Safer Choice and state-level chemical disclosure mandates. Agricultural chemical applications command premium positioning where drift reduction and tank-mix stability justify higher surfactant loading rates.
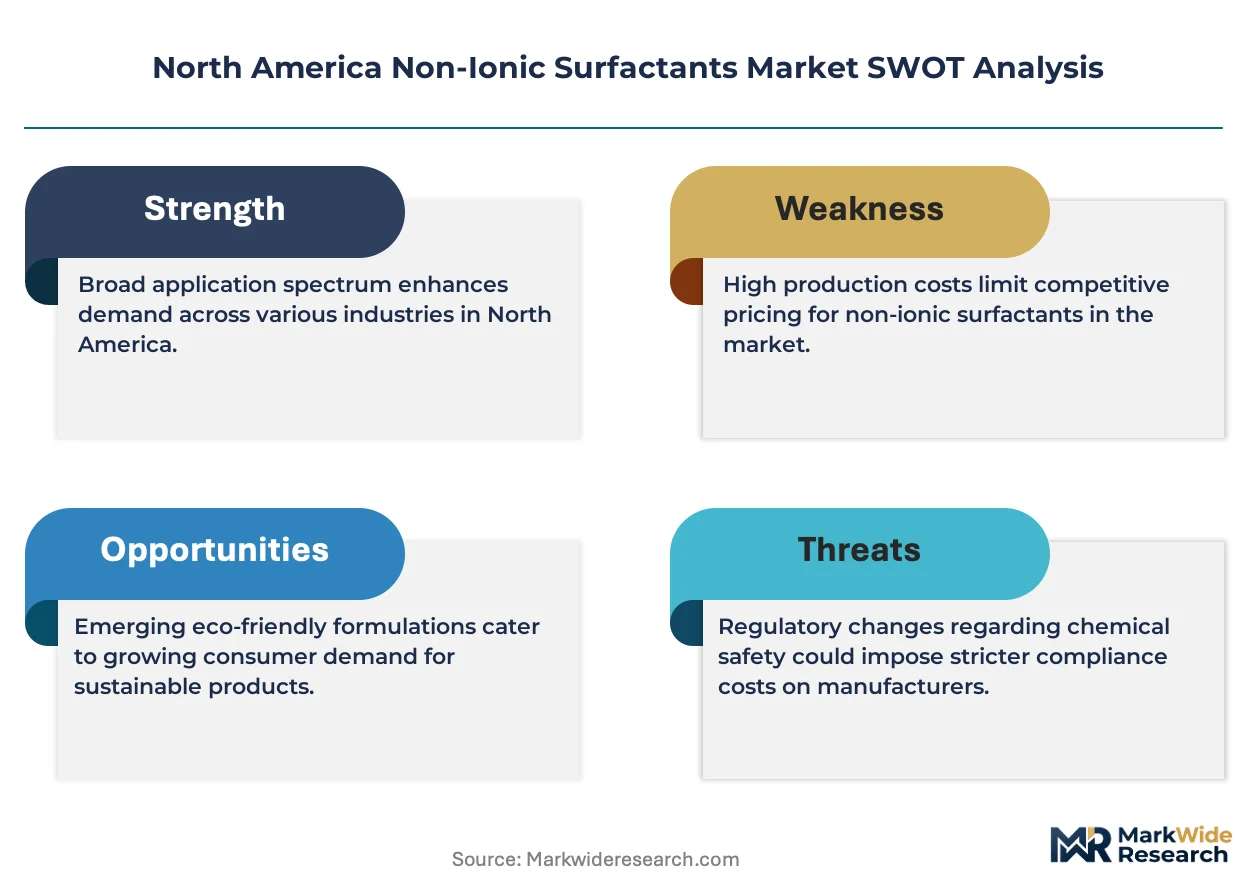
EPA oversight of chemical substance manufacturing under TSCA Section 5, coupled with Health Canada's PMRA re-evaluation of inert ingredients in pesticide formulations, compels producers to document environmental fate and aquatic toxicity profiles. FDA food contact notifications and OSHA permissible exposure limits further constrain process chemistry choices in food and beverage end uses. Stakeholders must track state-level ingredient transparency laws in California and New York while assessing bio-based feedstock certification schemes for premium positioning.
Market Dynamics
Alkylphenol ethoxylate phase-out mandates are compressing product portfolios across the North American non-ionic surfactants market, forcing reformulation investments and feedstock substitution at every tier of the supply chain.
Growth Catalysts
- EPA Safer Choice Program:Federal procurement preferences for certified formulations are pulling alkyl polyglucoside demand into institutional cleaning contracts across federal facilities.
- Texas-Louisiana ethylene oxide cluster:Integrated petrochemical infrastructure along the US Gulf Coast sustains cost-competitive ethoxylate production for regional formulators.
- Agricultural drift reduction:Pesticide applicators in the US Corn Belt are loading higher surfactant concentrations to meet buffer zone requirements under FIFRA enforcement.
Market Restraints
- Ethylene oxide feedstock concentration:Overreliance on Gulf Coast steam crackers exposes surfactant producers to hurricane-related supply interruptions and force majeure events.
- Health Canada PMRA re-evaluation:Extended timelines for inert ingredient registration are freezing new product introductions in Canadian agricultural formulations.
- Linear alcohol supply tightness:Competing demand from lubricant and plasticizer sectors is constraining fatty alcohol availability for ethoxylate producers.
Strategic Opportunities
- Ontario industrial cleaning sector:Provincial green procurement mandates are creating first-mover advantage for bio-based surfactant suppliers establishing Canadian blending capacity.
- Carbon intensity scoring:California's LCFS-style frameworks for chemical products are enabling premium pricing for verified low-carbon ethoxylate routes.
- Enzyme-surfactant hybrid systems:Convergence of biocatalysis and alkyl polyglucoside chemistry is opening performance gaps in cold-water laundry applications.
Industry Challenges
- Process safety engineering talent:Ethylene oxide handling expertise is retiring faster than training programs at Texas and Louisiana facilities can replenish.
- Multi-jurisdiction registration synchronization:Staggered EPA TSCA and Health Canada PMRA review cycles are extending commercialization timelines for new surfactant chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Ionic Surfactants Market |
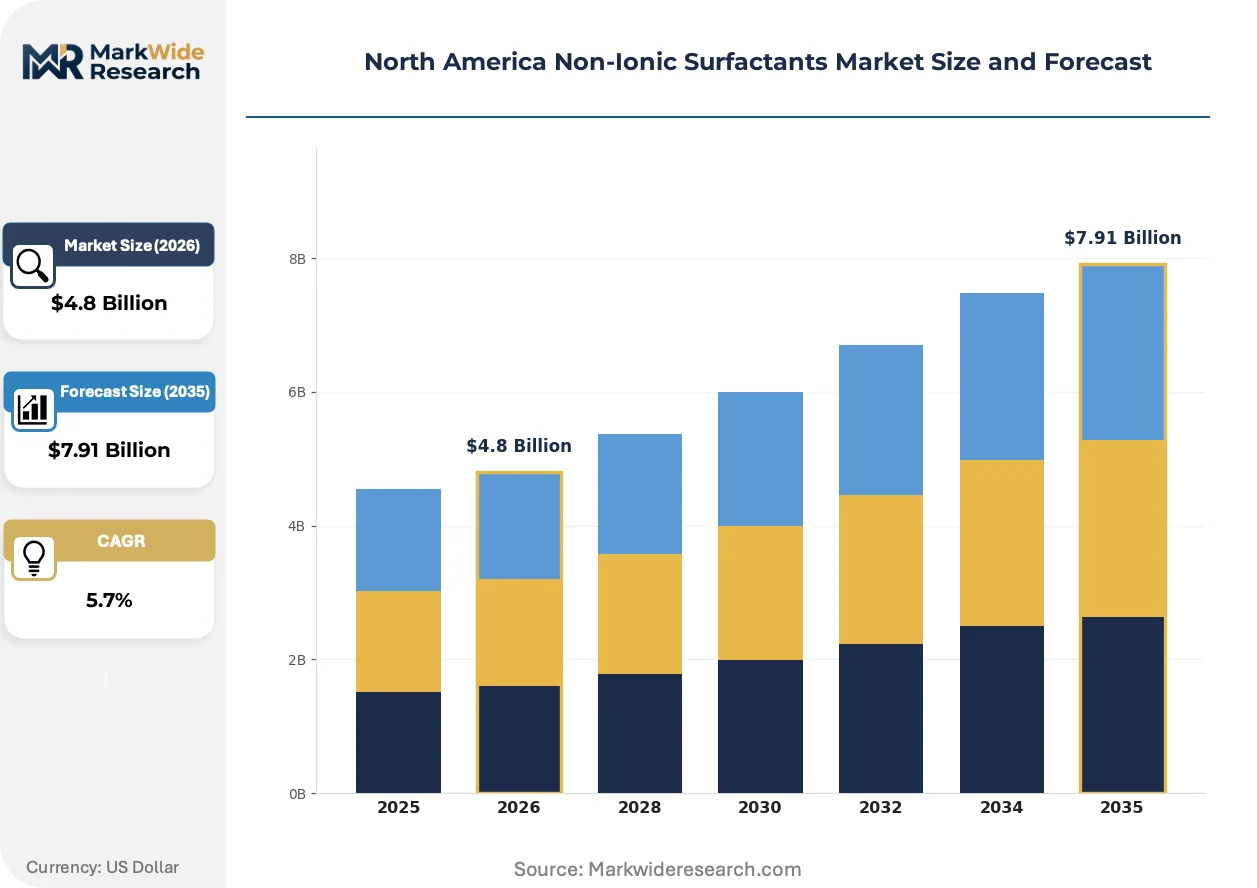
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethoxylates, Sorbitan Esters, Alkylene Glycol Esters, Alkyl Polyglycosides Application: Personal Care, Home Care, Industrial Cleaning, Agricultural Chemicals End User: Cosmetics, Food & Beverage, Textiles, Pharmaceuticals Form: Liquid, Powder, Paste, Granules |
| Companies Covered | BASF SE, Dow Inc., Stepan Company, Clariant AG, Evonik Industries AG, Solvay S.A., Croda International Plc, Huntsman Corporation, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Ionic Surfactants Market Evolving Landscape
Formulation science is pivoting toward bio-based hydrophobes and low-ethoxylate architectures as regulatory pressure and performance requirements converge on surfactant selection criteria.
Bio-based fatty alcohol production via oleochemical fermentation is rendering obsolete petroleum-derived C12-C14 feedstocks in premium personal care segments. Major cosmetics formulators in California and New York have accelerated qualification timelines for fermentation-derived alternatives. The shift is compressing margins for conventional ethoxylate producers lacking renewable alcohol supply agreements.
EPA's expanded TSCA Section 5 significant new use rules are forcing pre-manufacture notification for legacy ethoxylate modifications previously exempt from review. Industrial cleaning compounders are absorbing extended approval timelines into product development cycles. Agricultural adjuvant suppliers face the tightest constraints, as tank-mix surfactant innovations require dual EPA and state-level registrations.
Specification-driven procurement is consolidating surfactant buying power among national janitorial service contractors and food processing chains. Distributor private-label programs are displacing branded surfactant formulations in institutional accounts. The pattern is most pronounced in the US Midwest, where regional cooperatives aggregate volume for direct mill-to-plant alkyl polyglucoside deliveries.
North America Non-Ionic Surfactants Market Segmentation
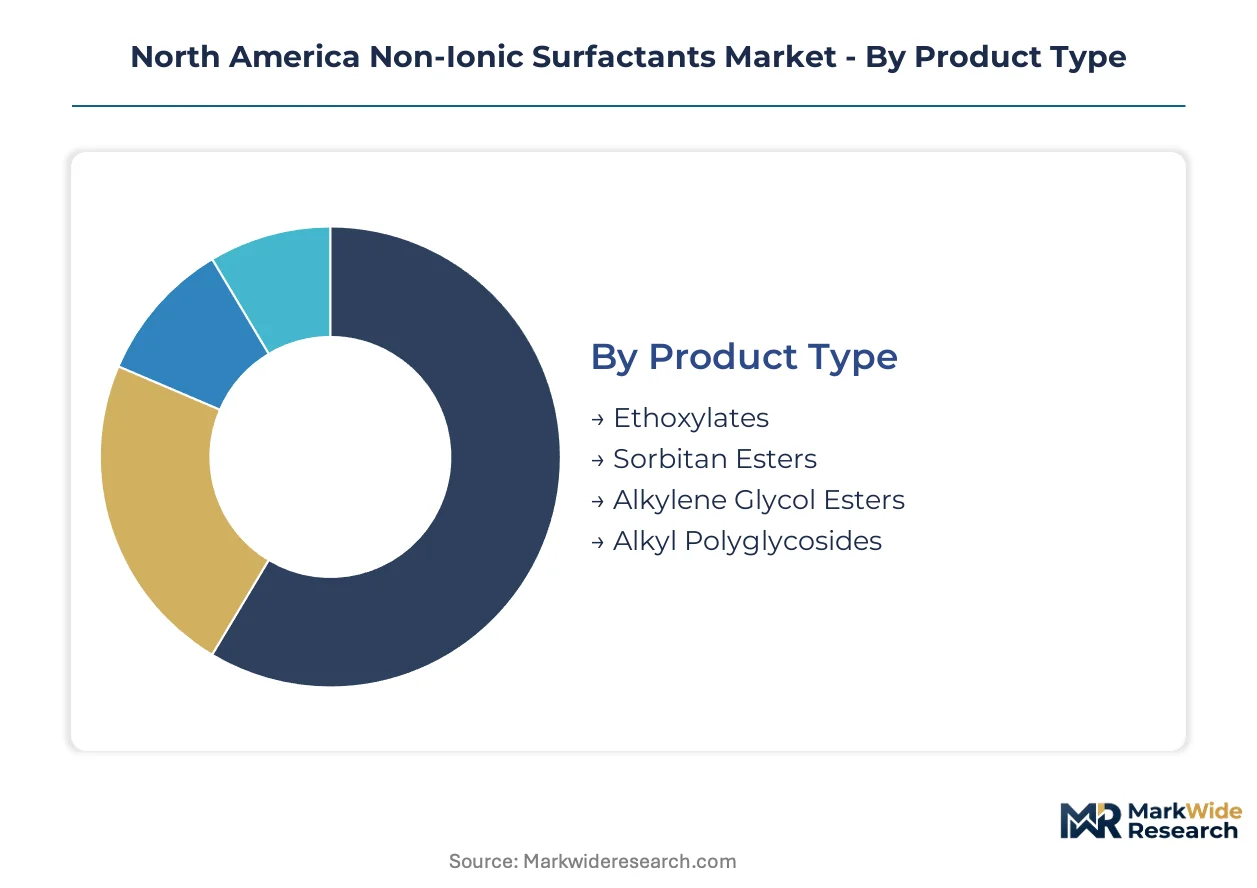
Non-ionic surfactant procurement patterns diverge sharply across formulation chemistry, application intensity, and regulatory exposure. Segment-level demand trajectories reflect divergent compliance burdens and feedstock substitution timelines across the value chain.
Product Type:
Formulators deploy distinct molecular architectures based on hydrophilic-lipophilic balance requirements and biodegradability mandates.
- Ethoxylates:Fatty alcohol ethoxylates synthesized via ethylene oxide addition dominate volume shipments through established compatibility with hard-surface cleaners and textile processing aids. Demand concentrates in Texas and Louisiana corridor facilities serving institutional janitorial contractors under EPA Safer Choice procurement preferences.
- Alkyl Polyglycosides:Glucose-derived hydrophobes combined with fatty alcohols yield low-irritation profiles for premium personal care. Ontario's provincial green procurement mandates are accelerating qualification timelines for bio-based alternatives to alkylphenol ethoxylates in industrial cleaning.
- Sorbitan Esters:Span-series emulsifiers from sorbitol esterification serve food-grade applications requiring FDA food contact notifications.
- Alkylene Glycol Esters:Propylene and ethylene glycol esters function as co-surfactants in agricultural drift reduction formulations.
The dominant share belongs to Ethoxylates, while Alkyl Polyglycosides is closing the gap fastest.
Application:
End-use intensity varies by regulatory scrutiny and surfactant loading rates per formulated unit.
- Industrial Cleaning:High-concentration formulations for food processing equipment and hard-surface sanitation command stringent EPA and OSHA compliance documentation. Demand clusters in Midwest regional cooperatives aggregating volume for direct alkyl polyglucoside deliveries.
- Agricultural Chemicals:Adjuvant and tank-mix applications require dual EPA FIFRA and state-level registrations for drift reduction compliance. Buffer zone requirements in the US Corn Belt justify premium surfactant loading rates.
- Personal Care:Low-irritation specifications drive qualification of fermentation-derived fatty alcohols in California and New York cosmetics formulating.
- Home Care:Laundry and dish formulations balance cost position with biodegradability profiles under municipal wastewater discharge constraints.
Industrial Cleaning captures the largest volume position, though Agricultural Chemicals generates the steepest premium pricing differential.
End User:
Customer sophistication determines specification stringency and contract duration structures.
- Cosmetics:Clean beauty positioning in California and New York accelerates renewable alcohol qualification timelines beyond conventional petrochemical feedstocks.
- Food & Beverage:FDA food contact notifications and OSHA permissible exposure limits constrain process chemistry choices for emulsifier selection.
- Textiles:Scouring and wet-processing applications in Southeast US mills favor ethoxylate compatibility with dye bath chemistry.
- Pharmaceuticals:USP-grade specifications for excipient applications impose batch-level documentation requirements.
Cosmetics exhibits the most rapid specification evolution, while Food & Beverage maintains the most rigid compliance protocols.
Form:
Physical state selection reflects formulation viscosity targets and handling infrastructure at customer sites.
- Liquid:Pumpable concentrates dominate institutional and industrial accounts with bulk storage capacity. Gulf Coast ethylene oxide cluster proximity minimizes delivered cost for high-volume contract customers.
- Powder:Spray-dried granules serve powder detergent manufacturers and dry-blend agricultural formulations requiring extended shelf stability.
- Paste:Semi-solid concentrates target manual compounding operations in smaller-scale food processing and textile facilities.
- Granules:Dust-free agglomerated forms address OSHA respirable particulate concerns in high-throughput manufacturing environments.
Liquid holds the volume leadership position, with Powder gaining share in automated dry-blend operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide infrastructure clusters along the US Gulf Coast anchor regional supply, while Canadian demand diversifies toward bio-based alternatives and Mexico's industrial base absorbs growing volumes of cleaning and agricultural formulations.
United States
Texas and Louisiana host integrated ethylene oxide production corridors serving ethoxylate manufacturers under EPA TSCA Section 5 oversight. The EPA Safer Choice Program drives federal procurement toward certified alkyl polyglucoside formulations. Midwest regional cooperatives aggregate surfactant volumes for direct mill-to-plant deliveries, bypassing traditional distribution channels.
Canada
Ontario's provincial green procurement mandates accelerate qualification timelines for bio-based surfactants in institutional cleaning contracts. Health Canada PMRA re-evaluation of inert ingredients extends registration timelines for new agricultural formulations. Quebec and British Columbia blenders fragment supply sources to reduce dependence on imported ethoxylate feedstock.
Mexico
Nuevo León's manufacturing corridor absorbs growing volumes of industrial cleaning surfactants for food processing and automotive assembly operations. Mexican regulators align chemical substance oversight with evolving North American standards. Bajío Region agricultural operations increase surfactant loading rates for drift reduction compliance in specialty crop applications.
North America Non-Ionic Surfactants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive ethylene oxide or fermentation-derived alcohol assets. The vendor base stratifies between Gulf Coast-integrated ethoxylate producers and specialty emulsifier formulators serving food-grade and pharmaceutical specifications. Three archetypes dominate: integrated petrochemical platforms, bio-based fermentation specialists, and regional blending operations. Capacity expansion along the Texas-Louisiana corridor and backward integration into fatty alcohol supply represent the dominant competitive vectors.
Among integrated petrochemical platforms, BASF SE and Dow Inc. occupy positions anchoring regional ethoxylate supply through Gulf Coast infrastructure. Stepan Company exemplifies the specialty emulsifier archetype, with formulation expertise concentrated in food-grade and personal care applications. These three entities represent distinct strategic postures: captive feedstock integration, scale-driven commodity supply, and specification-driven specialty positioning.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Stepan Company |
| Clariant AG |
| Evonik Industries AG |
| Solvay S.A. |
| Croda International Plc |
| Huntsman Corporation |
| Kao Corporation |
| Others |
Value Network & Pricing Analysis
Tight ethylene oxide capacity utilization along the Texas-Louisiana corridor is compressing supplier margins while amplifying pricing leverage for integrated producers serving institutional cleaning and agricultural adjuvant customers. This utilization dynamic rewards backward-integrated players with captive feedstock and pressures toll-manufacturing dependent blenders into long-term offtake commitments.
Pricing Analysis
EPA Safer Choice Program certification dictates the pricing tier structure across North American non-ionic surfactant procurement, separating premium-validated bio-based formulations from standard petrochemical ethoxylates and economy-grade legacy alkylphenol alternatives. Price differentiation hinges on renewable alcohol certification status and volume scale, with federal procurement preferences tightening margins for uncertified suppliers. Cost compression in standard-tier fatty alcohol ethoxylates is intensifying as fermentation-derived C12-C14 feedstocks achieve cost parity in personal care segments. Institutional janitorial contractors exhibit the highest price sensitivity due to cooperative volume aggregation, while agricultural adjuvant formulators absorb premium surfactant loading rates for drift reduction compliance.
Supply Chain Analysis
Hurricane exposure across the Texas-Louisiana ethylene oxide cluster dominates supply chain risk assessment for North American surfactant procurement. Manufacturing gravity centers on the US Gulf Coast, with secondary concentration in Ontario blending facilities and Nuevo León manufacturing corridors. Feedstock supply draws from petroleum-derived ethylene, bio-based fatty alcohol fermentation streams, and glucose-derived hydrophobes for alkyl polyglucoside production. Single-source vulnerability persists for ethoxylate manufacturers lacking diversified alcohol supply agreements. Distribution runs through regional cooperatives in the US Midwest, direct mill-to-plant deliveries for high-volume institutional accounts, and traditional chemical distribution for smaller-scale food processing and textile facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions are expanding faster than commodity surfactant volumes as customers outsource regulatory compliance documentation and application-specific blending optimization.
For Market Incumbents: Pre-empt alkyl polyglucoside capacity additions in Ontario and Quebec by securing provincial green procurement pre-qualification ahead of mandate expansion. Anchor ethanolamine and ethylene oxide supply through captive Gulf Coast infrastructure or long-term pipeline commitments to defend against force majeure disruptions. Accelerate PMRA registration dossier preparation for inert ingredient re-evaluations freezing competitor product introductions in Canadian agricultural formulations. For New Entrants and Emerging Players: Build out fermentation-derived fatty alcohol supply agreements with cosmetics formulators in California and New York seeking clean beauty positioning beyond conventional petrochemical feedstocks. Target Ontario institutional cleaning contracts under provincial green procurement mandates where incumbent ethoxylate suppliers lack bio-based qualification. Establish technical service capabilities as the primary go-to-market angle, bundling regulatory compliance documentation with surfactant supply to differentiate from commodity distributors. For Investors and Strategic Acquirers: Capital is best deployed toward integrated petrochemical platforms with captive ethylene oxide infrastructure and specialty emulsifier formulators holding FDA food contact notification portfolios. Long-term viability over the coming decade favors assets with renewable alcohol supply agreements and dual EPA-Health Canada registration capabilities. Watch Health Canada PMRA inert ingredient re-evaluation timelines as the signal for competitive repositioning in Canadian agricultural adjuvant markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Supply | Captive renewable feedstock secures margin stability against oleochemical price volatility. |
| Green Manufacturing Transition | Bio-based ethoxylate routes command premium positioning under California LCFS-style frameworks. |
| Long-term Supply Agreement | Fixed-price contracts with Midwest cooperatives lock volume against hurricane-related supply interruptions. |
| Joint Venture | Partnerships with Ontario blenders accelerate provincial green procurement qualification timelines. |
| Capacity Expansion | Alkyl polyglucoside additions in Texas-Louisiana corridor capture EPA Safer Choice procurement pull. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Gulf Coast ethylene oxide facilities, procurement leads at institutional cleaning cooperatives, distribution channel partners, and technical R&D directors at specialty emulsifier formulators; and secondary validation against customs and trade data, American Chemistry Council sector reports, SEC 10-K filings, EPA TSCA Section 5 significant new use rule dockets, and Health Canada PMRA inert ingredient re-evaluation notices. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Forecast inputs span product chemistry, application intensity, regulatory exposure tier, and regional production hub clustering across the projection horizon. Segmentation dimensions include ethoxylate grade tier, end-use industry classification, bio-based content certification status, and customer procurement sophistication. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific inputs incorporate EPA Safer Choice program adoption curves and Health Canada PMRA registration timeline assumptions.
Stress conditions across ethylene oxide supply interruptions, renewable alcohol cost parity achievement, and staggered EPA-Health Canada regulatory synchronization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding feedstock substitution timelines and procurement mandate enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Microemulsions Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Polysorbate 40 Market
Surfactants
Wax Emulsion Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Cationic Surfactants Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Dispersant Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Tetradecyl Chloride Market