
 Global Saponin Market | 2026-2036
Global Saponin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saponin Market Foresight
Green extraction technologies is tilting saponin production toward solvent-free supercritical CO2 and ultrasound-assisted methods that preserve bioactivity while cutting waste streams. KPC Pharmaceuticals leverages its Yunnan botanical supply base to secure raw material continuity for high-purity ginseng saponin output. Indena anchors European pharmaceutical-grade extraction through its Milan-area facilities and long-standing relationships with vaccine adjuvant developers. Laozhiqing Group dominates traditional Chinese medicine channel supply, sustaining volume through direct cultivation contracts across Sichuan and Guizhou provinces.
Saponins comprise amphipathic glycosides built from triterpenoid or steroid aglycone cores linked to one or more sugar chains, with critical micelle concentrations typically spanning 0.01–1.0 g/L depending on sapogenin class and glycosylation pattern; manufacturers isolate these compounds via aqueous extraction followed by chromatographic purification to serve emulsification, foaming, and membrane-permeabilization roles across industries. Quillaja-derived fractions lead pharmaceutical adjuvant applications due to their potent QS-21 immunostimulant content and established inclusion in prophylactic vaccine formulations. Powder and granular forms command premium positioning in nutraceutical encapsulation workflows where dosing precision and shelf stability determine contract viability, while liquid concentrates compete aggressively in agricultural biostimulant spraying systems.
The FDA evaluates saponin-containing vaccine adjuvants through its Center for Biologics Evaluation and Research, requiring extensive toxicity profiling that shapes development timelines and capital allocation for pharmaceutical entrants. China's NMPA and SAMR enforce Good Agricultural Practice standards for botanical raw materials, directly constraining wild-harvested quillaja supply expansion and accelerating cultivated alternatives. REACH registration obligations in Europe demand full substance characterization for imported botanical extracts, filtering out smaller traders and consolidating procurement around certified suppliers. Stakeholders must track extraction technology patent filings and adjuvant pipeline disclosures to anticipate which sapogenin classes will capture the next wave of pharmaceutical formulation demand.
Market Dynamics
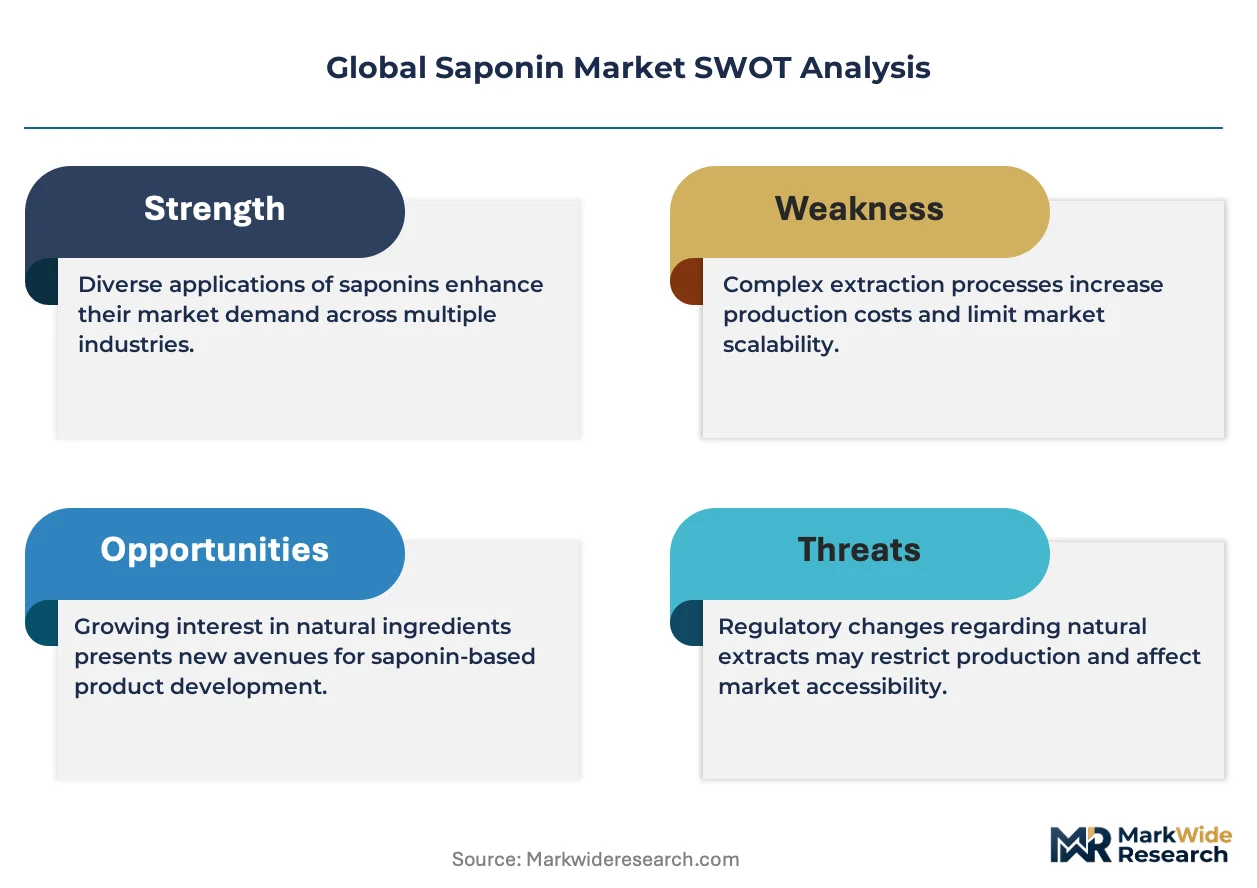
Pharmaceutical-grade saponin supply is consolidating around cultivated quillaja alternatives as wild-harvested bark faces depletion pressure and China's NMPA enforces stricter Good Agricultural Practice traceability. This structural pivot is redrawing procurement relationships and extraction technology investment patterns across adjuvant developers and botanical extractors.
Growth Catalysts
- Vaccine Adjuvant Demand:QS-21 immunostimulant inclusion in prophylactic formulations is pulling high-purity quillaja fractions into pharmaceutical procurement pipelines at expanding volumes.
- EU Green Deal:REACH chemical safety standards and botanical extract sourcing requirements are filtering procurement toward certified European suppliers with verified supply chain documentation.
- Supercritical CO2 Extraction:Solvent-free methods are preserving saponin bioactivity while cutting waste streams, enabling premium positioning in nutraceutical encapsulation workflows.
Market Restraints
- Raw Material Concentration:China dominates raw quillaja bark processing, creating single-source dependency risk for adjuvant manufacturers seeking pharmaceutical-grade inputs.
- REACH Registration Burden:Full substance characterization obligations for imported botanical extracts are filtering out smaller traders and raising capital barriers to European market entry.
- Synthetic Surfactant Substitution:Petroleum-derived emulsifiers compete aggressively on cost in agricultural and industrial applications where bioactivity preservation is non-critical.
Strategic Opportunities
- Cultivated Quillaja Expansion:Domesticated bark production in Chile and Peru offers supply chain diversification beyond wild-harvested Chinese sources.
- Drug Delivery Systems:Saponin micelle formation properties are enabling liposomal encapsulation applications for poorly soluble active pharmaceutical ingredients.
- US Biostimulant Channel:EPA regulatory pathways for agricultural biologicals are opening direct-to-grower distribution models bypassing traditional agrochemical formulation houses.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Vaccine adjuvant developers face acute shortages of toxicologists capable of navigating FDA Center for Biologics Evaluation and Research submission requirements.
- Chromatographic Purification Scale-Up:Industrial-scale high-performance liquid chromatography systems for ginsenoside fractionation demand capital commitments that strain mid-tier extractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saponin Market |
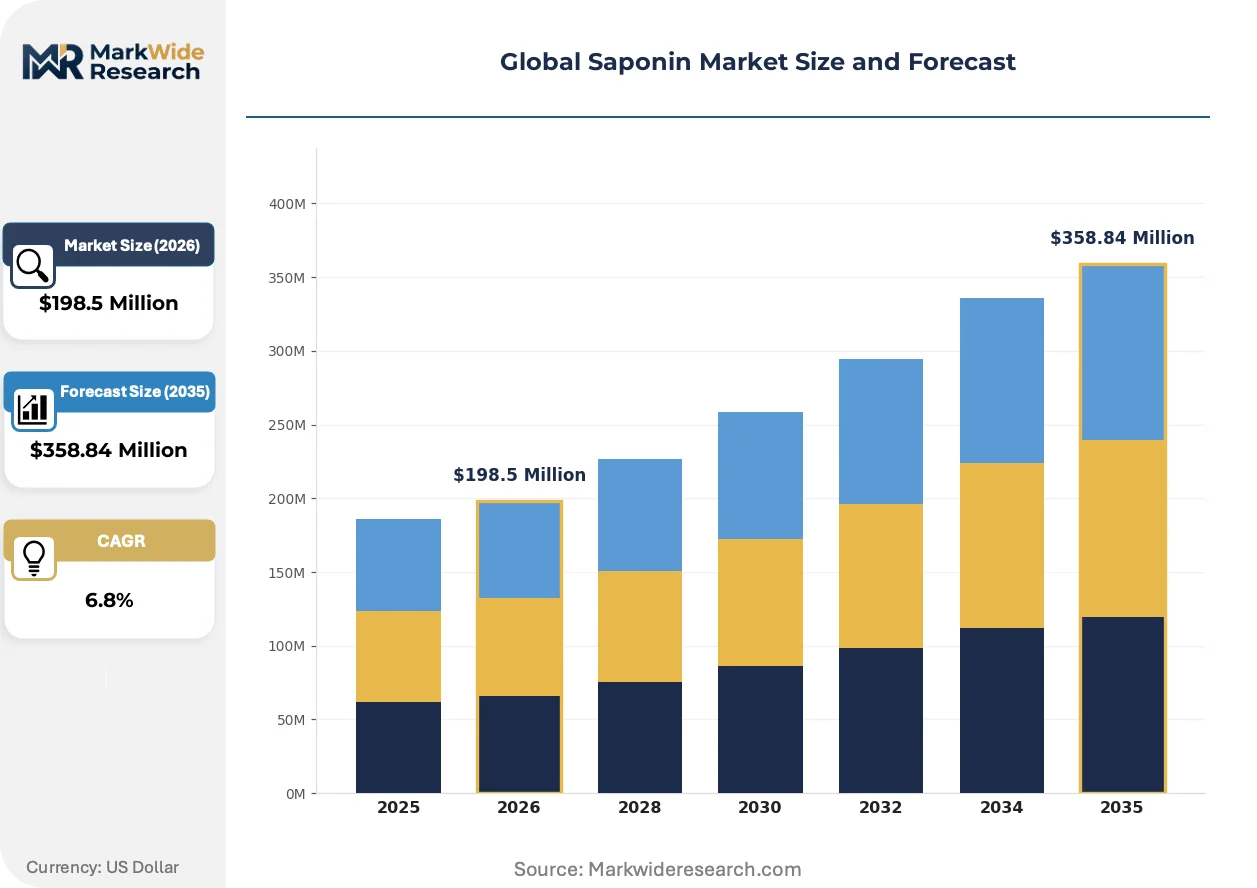
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $358.84 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quillaja, Soybean, Tea, Horse Chestnut, Ginseng, Others Application: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture, Animal Feed, Cleaning Agents Form: Liquid, Powder, Granular, Extract, Concentrate End User Industry: Personal Care, Crop Protection, Nutraceuticals, Veterinary Products, Household Products |
| Companies Covered | KPC Pharmaceuticals, Hubei Jusheng Technology, Laozhiqing Group, Yongxin Youxiang, Indena, Yunnan Baiyao Group, Tianmao Herb Co., Ltd., Zhongheng Group, Weihe Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saponin Market Shifts & Advancements
Green chemistry mandates and pharmaceutical purity specifications are converging to accelerate extraction technology substitution and reshape competitive positioning around bioactivity preservation capabilities.
Supercritical CO2 extraction is hybridizing with ultrasound-assisted pre-treatment to reduce solvent residues in final saponin fractions while maintaining triterpenoid glycoside structural integrity. Adjuvant developers at FDA-regulated vaccine manufacturers are adopting these hybrid systems to meet pharmacopeial monograph specifications. The technology compression is eliminating aqueous ethanol extraction infrastructure for premium pharmaceutical-grade output.
REACH registration obligations in Europe are forcing full substance characterization for imported botanical extracts, consolidating procurement around Milan-area and German extractors with in-house analytical capabilities. ECHA substance identification and naming protocols now require detailed sapogenin class documentation. Vaccine adjuvant formulators are responding by qualifying European suppliers ahead of 2025 registration deadlines.
Direct cultivation contracting is displacing spot-market wild harvesting as the dominant raw material sourcing model for traditional Chinese medicine channel supply. Laozhiqing Group and Yunnan-based operators are locking multi-year quillaja and ginseng root agreements with Sichuan and Guizhou province growers. This behavioral shift is most visible in China where SAMR traceability requirements now mandate field-to-facility documentation.
Global Saponin Market Segmentation
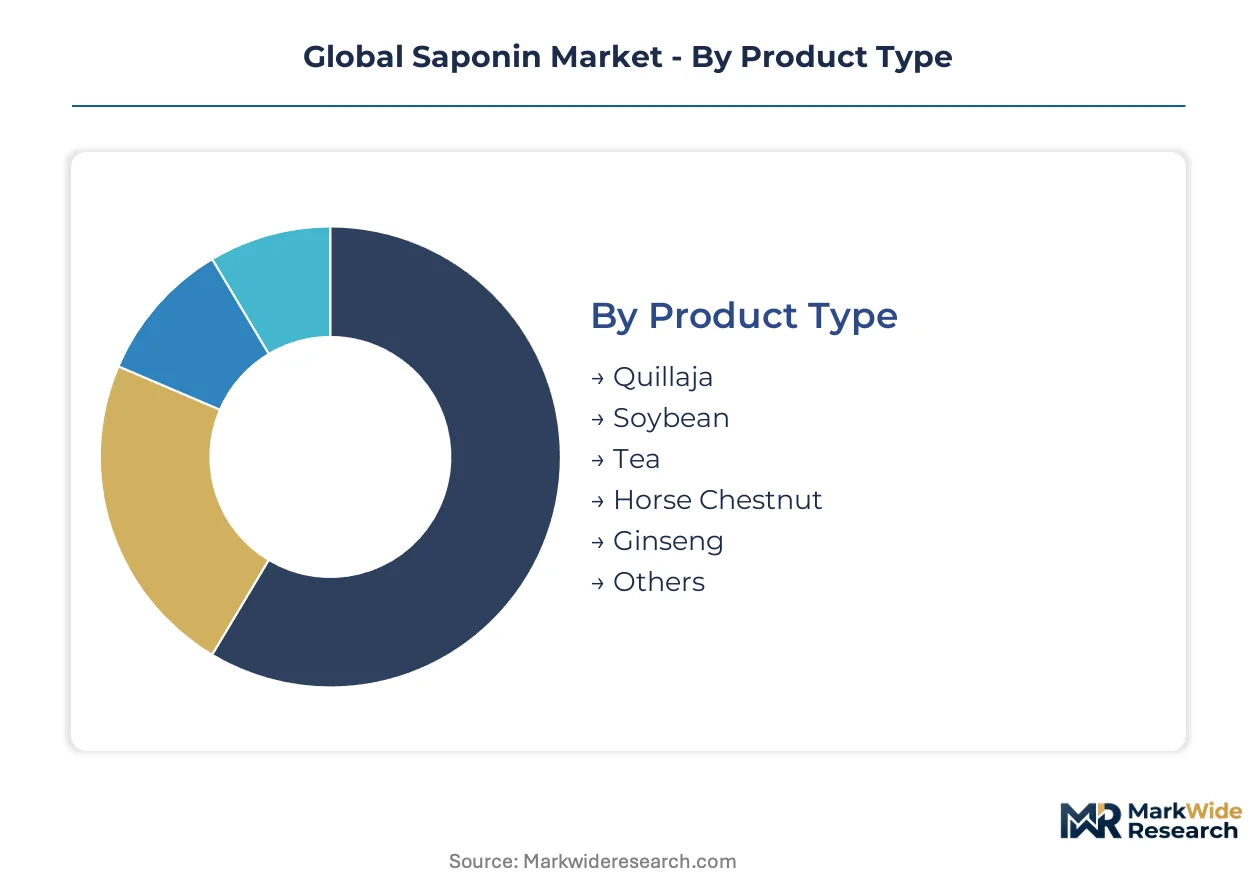
Saponin market segmentation reflects divergent purity requirements across pharmaceutical adjuvant and agricultural biostimulant channels. Formulators select sapogenin classes based on immunostimulant potency, emulsification performance, and regulatory registration pathways.
Product Type:
Mature triterpenoid sources dominate commercial volumes while emerging steroid-class alternatives reshape pharmaceutical procurement.
- Quillaja:Bark-derived triterpenoid glycosides contain QS-21 immunostimulants at concentrations critical for vaccine adjuvant efficacy. Demand concentrates in FDA-regulated pharmaceutical formulators seeking REACH-compliant European supply alternatives to wild-harvested Chinese sources.
- Ginseng:Panax species yield dammarane-type ginsenosides with documented membrane-permeabilization properties. Korean and Chinese nutraceutical encapsulators drive procurement for cognitive health formulations requiring standardized Rb1 and Rg1 fractions.
- Soybean:Soyasaponin B group compounds serve agricultural foaming applications where cost efficiency outweighs bioactivity preservation requirements.
- Tea:Camellia-derived theasaponins support mild surfactant roles in Japanese and Chinese personal care formulations.
- Horse Chestnut:Aescin fractions command specialized venotonic pharmaceutical applications in European phytomedicine channels.
- Others:Yucca and soap bark saponins fill niche foaming agent demand in Latin American and North African industrial applications.
Quillaja retains volume leadership among pharmaceutical-grade sources; ginseng holds the steepest expansion curve in nutraceutical encapsulation workflows.
Application:
Cost tier stratification separates premium pharmaceutical-grade from commodity agricultural applications.
- Pharmaceuticals:Vaccine adjuvant formulations require QS-21 fractions exceeding 95% purity with full toxicological documentation. GSK and Sanofi procurement contracts specify supercritical CO2 extraction methods to satisfy FDA Center for Biologics Evaluation and Research submission standards.
- Agriculture:Biostimulant spraying systems utilize crude saponin concentrates at 20-40% purity for nematode suppression and nutrient uptake enhancement. Brazilian and Australian growers drive volume through EPA and APVMA regulatory pathways.
- Food & Beverage:Natural emulsifiers replace synthetic surfactants in clean-label beverage stabilization.
- Cosmetics:Mild cleansing formulations leverage tea and quillaja saponins for sulfate-free positioning.
- Animal Feed:Methane reduction claims in ruminant nutrition support European and North American adoption.
- Cleaning Agents:Industrial degreasing applications compete directly with petroleum-derived alternatives on unit economics.
Agriculture commands the largest volume position; pharmaceuticals deliver the highest margin realization per kilogram.
Form:
Customer type dictates physical specification requirements across precision dosing and bulk handling workflows.
- Powder:Spray-dried fractions with defined particle size distributions enable capsule filling and tablet compression at nutraceutical contract manufacturers. Shelf stability and flowability parameters determine qualification status with German and Swiss encapsulation houses.
- Liquid:Aqueous concentrates serve agricultural spraying systems requiring immediate dilution compatibility. Brazilian sugarcane and Australian vineyard operators specify 20-40% active content for field-scale biostimulant application.
- Granular:Agglomerated forms reduce dust exposure in feed mill handling environments.
- Extract:Semi-purified intermediates support downstream fractionation at specialized pharmaceutical extractors.
- Concentrate:High-potency fractions target liposomal encapsulation workflows for poorly soluble active pharmaceutical ingredients.
Powder retains volume leadership in nutraceutical channels; liquid concentrates are expanding most quickly in agricultural biologicals.
End User Industry:
Supply concentration in Chinese raw material processing shapes regional procurement patterns across end-use segments.
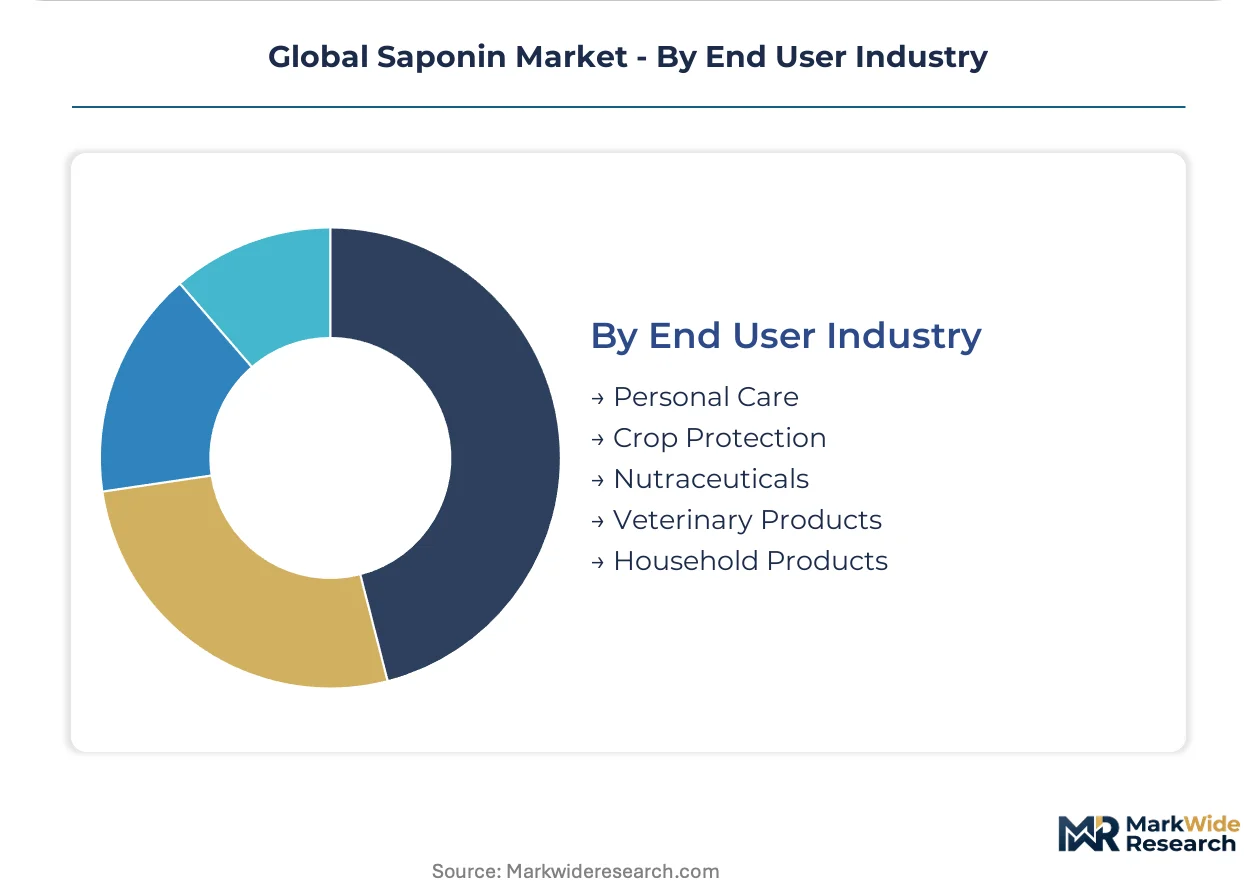
- Nutraceuticals:Ginseng and quillaja fractions enter cognitive health and immune support formulations requiring GMP-certified extraction documentation. US and European brands specify cultivated alternatives to wild-harvested sources.
- Crop Protection:Biostimulant registrations with EPA and state-level departments of agriculture enable direct-to-grower distribution. California and Florida specialty crop operators drive adoption for organic-compliant nematode management.
- Personal Care:Sulfate-free cleansing positioning supports tea saponin incorporation in Korean and French cosmetic formulations.
- Veterinary Products:Feed additive applications target methane reduction claims in European dairy operations.
- Household Products:Natural surface cleaning formulations compete on green chemistry credentials rather than unit cost.
Nutraceuticals retain volume leadership; crop protection holds the steepest expansion trajectory in regulatory-compliant agricultural biologicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile exports cultivated quillaja bark to European vaccine manufacturers seeking REACH-compliant alternatives to wild-harvested Asian sources. This trade corridor is reshaping procurement geography as pharmaceutical formulators diversify supply origins.
China
Raw quillaja bark processing concentrates in Yunnan and Sichuan provinces, supplying global pharmaceutical and nutraceutical channels. SAMR enforces Good Agricultural Practice traceability requirements that mandate field-to-facility documentation for all botanical raw materials. Laozhiqing Group anchors traditional Chinese medicine supply through direct cultivation contracts across Guizhou province.
United States
Vaccine adjuvant developers at GSK and Sanofi drive demand for QS-21 fractions exceeding purity thresholds. FDA Center for Biologics Evaluation and Research mandates extensive toxicological profiling that extends development timelines. Boston-area biotech clusters house formulation specialists navigating these submission standards.
Germany
REACH registration obligations filter botanical extract procurement toward certified domestic suppliers with in-house analytical capabilities. ECHA substance identification protocols now require detailed sapogenin class documentation. Frankfurt and Hamburg harbor specialized extractors qualifying European supply chains ahead of registration deadlines.
Chile
Cultivated quillaja plantations in central valley regions offer supply diversification beyond wild-harvested Chinese sources. Domesticated bark production scales under contract agriculture models serving pharmaceutical export channels. Santiago-based operators coordinate cultivation expansion with European adjuvant developers.
Italy
Milan-area extraction facilities anchor European pharmaceutical-grade saponin output for vaccine adjuvant applications. EMA-aligned quality standards govern production workflows serving GMP-certified pharmaceutical formulators. Northern Italian chemical clusters integrate supercritical CO2 infrastructure to meet pharmacopeial specifications.
Global Saponin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Consolidation pressures favor integrated extractors with captive raw material sourcing and certified analytical capabilities. Three archetypes dominate: Yunnan-based botanical conglomerates with cultivation networks, European pharmaceutical-grade specialists with REACH registration expertise, and mid-tier Chinese processors serving agricultural and nutraceutical channels. Dominant competitive moves include backward integration into cultivated quillaja plantations and technology licensing for green extraction methods.
Among Yunnan-based operators, KPC Pharmaceuticals and Yunnan Baiyao Group represent integrated supply chain archetypes with provincial cultivation networks. Indena exemplifies the European pharmaceutical-grade specialist model through Milan-area extraction infrastructure. Laozhiqing Group occupies a position within traditional Chinese medicine channel supply, sustaining volume through multi-year grower agreements. These three anchors illustrate the geographic and functional stratification shaping procurement relationships.
| Leading Market Players |
|---|
| KPC Pharmaceuticals |
| Hubei Jusheng Technology |
| Laozhiqing Group |
| Yongxin Youxiang |
| Indena |
| Yunnan Baiyao Group |
| Tianmao Herb Co., Ltd. |
| Zhongheng Group |
| Weihe Pharma |
| Others |
Supply & Pricing Matrix
China's Yunnan and Sichuan province quillaja bark processing clusters feed directly into margin capture at European REACH-certified extractors and FDA-regulated pharmaceutical formulators. Wild-harvested raw material scarcity is compressing spreads for mid-tier processors while supercritical CO2 extraction premiums accrue to technology-integrated suppliers.
Pricing Analysis
Aqueous ethanol extraction methods trade at 40-60% discounts to supercritical CO2 and ultrasound-assisted hybrid outputs, creating a pronounced technology-generation pricing gap. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and agricultural-economy levels reflects purity thresholds and certification documentation intensity. Cost compression in agricultural concentrates is intensifying because synthetic surfactant substitutes compete aggressively on unit economics. Agricultural biostimulant buyers exhibit highest price sensitivity; vaccine adjuvant developers show lowest, bound by FDA toxicological profiling requirements.
Supply Chain Analysis
China's NMPA Good Agricultural Practice traceability mandates function as de facto export-control regime filters, constraining wild-harvested bark flows to qualified European and North American buyers. Supply concentrates in China, Chile, and Peru, with cultivated alternatives in central valley regions drawing from domesticated plantation models. Chromatographic purification equipment and supercritical CO2 systems constitute critical input dependencies. Single-source vulnerability risk runs through Yunnan-based raw material channels. Distribution runs through GMP-certified pharmaceutical extractors, direct cultivation contracting networks, and spot-market agricultural intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat. REACH registration obligations and FDA Center for Biologics Evaluation and Research toxicological standards create switching costs that lock in qualified suppliers.
For Market Incumbents: Build regulatory-certification moats through backward integration into cultivated quillaja plantations in Chile and Peru. Secure multi-year grower agreements before SAMR traceability mandates tighten further. Defensive priority centers on supercritical CO2 patent licensing to freeze out aqueous ethanol competitors from pharmaceutical-grade procurement pipelines. For New Entrants and Emerging Players: Pursue EPA-registered agricultural biostimulant channels in Brazilian sugarcane and Australian vineyard segments where purity requirements remain permissive. Direct-to-grower distribution models bypass entrenched agrochemical formulation houses. White-space entry angles include liposomal encapsulation workflows for poorly soluble active pharmaceutical ingredients. For Investors and Strategic Acquirers: Capital is best deployed toward European pharmaceutical-grade specialists with in-house ECHA substance identification capabilities and Milan-area extraction infrastructure. Long-term viability hinges on cultivated raw material sourcing models displacing wild-harvested dependencies. Watch for adjuvant pipeline disclosures from GSK and Sanofi as inflection indicators for QS-21 fraction demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Plantations | Chilean and Peruvian quillaja farms reduce wild-harvest dependency for REACH-compliant European supply. |
| Green Extraction Technology Licensing | Supercritical CO2 hybrid systems preserve QS-21 bioactivity for FDA vaccine adjuvant submissions. |
| REACH Registration Completion | ECHA substance identification protocols filter procurement toward certified Milan-area and German extractors. |
| Direct Cultivation Contracting | Laozhiqing Group's Guizhou province grower agreements lock volume for traditional Chinese medicine channels. |
| EPA Biostimulant Registration | California and Florida specialty crop operators drive organic-compliant nematode management adoption. |
Research Methodology
A spread of perspectives from extraction technology R&D directors, vaccine adjuvant formulators, pharmaceutical procurement managers, and agricultural biologicals distributors converged on the working assumptions underlying demand modeling. Primary interview insights combined with secondary validation from FDA Center for Biologics Evaluation and Research filings, ECHA registration databases, NMPA Good Agricultural Practice documentation, and customs trade flows. Bottom-up volume builds across sapogenin classes and top-down market sizing triangulated on consensus-derived price points.
Demand-supply-balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sapogenin source class, purity grade tier, application channel, and regional regulatory cluster. CAGRs derived from segment-level volume trajectories weighted by pharmaceutical-grade premium realization. Industry-specific forecast inputs incorporated QS-21 adjuvant pipeline disclosures and SAMR traceability mandate implementation timelines.
Sensitivities concentrate around cultivated quillaja plantation scale-up rates and REACH registration deadline compliance patterns. Forecasts reflect assumptions on substitution elasticity between wild-harvested and domesticated bark sources. Material shifts in FDA toxicological profiling requirements or ECHA substance identification protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Polysorbate 40 Market
Surfactants
Global Surfactants Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Wax Emulsion Market
Surfactants
Microemulsions Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Anionic Surfactants Market
Surfactants
Cationic Surfactants Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Global Rhamnolipid Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Global Methyl Soyate Market