
 Chlorosilane Market | 2026-2036
Chlorosilane Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorosilane Market Analysis
Electronics manufacturers are unwinding their historical reliance on commodity-grade chlorosilanes as polysilicon purity requirements tighten for advanced node semiconductors. Shin-Etsu Chemical Co. Ltd. leverages captive silicon metal refining to sustain wafer-grade supply continuity across East Asian fabrication corridors. Wacker Chemie AG anchors European chlorosilane output through integrated silicone-polymer complexes along the Burghausen chemical site. Hemlock Semiconductor Corporation dominates U.S. domestic supply of semiconductor-grade trichlorosilane through its Michigan-based polysilicon vertical.
Chlorosilanes are silicon-hydrogen-chlorine compounds synthesized via direct process reaction of metallurgical-grade silicon with hydrogen chloride at elevated temperatures, yielding intermediates with boiling points ranging from 8°C for dichlorosilane to 57°C for trimethylchlorosilane that serve as precursors for polysilicon deposition and silicone polymer synthesis. Methyldichlorosilane and vinyltrichlorosilane occupy mature volume positions in sealant and adhesive cross-linking applications where formulation chemistry has stabilized over decades. Electronics-grade dichlorosilane leads growth velocity as atomic layer deposition processes in logic chip manufacturing require sub-parts-per-billion metallic impurity thresholds that command premium positioning.
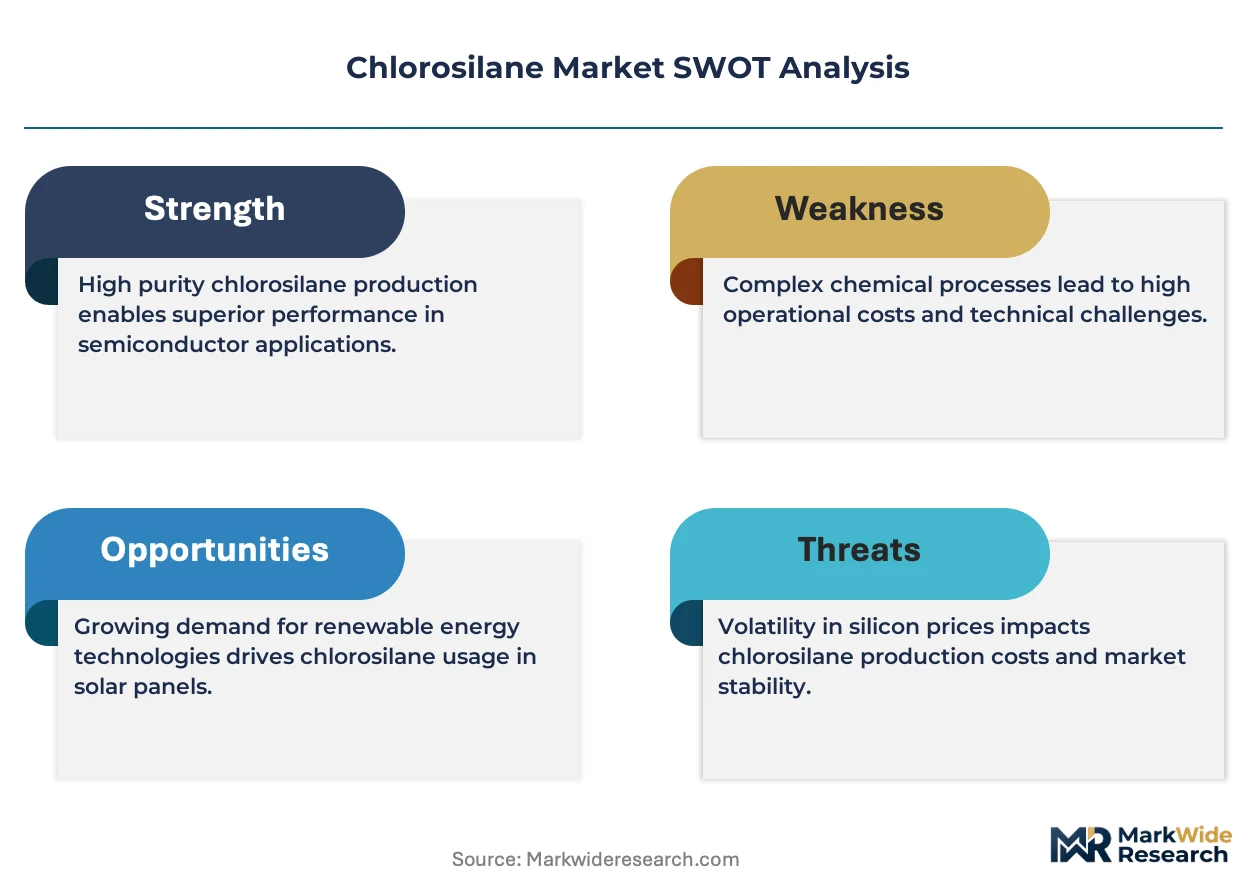
China's MEE enforces GB standards on chlorosilane emissions and wastewater treatment that raise capital barriers for new entrants in the Yangtze River Delta chemical corridor. The EPA's Risk Management Plan and OSHA Process Safety Management requirements govern U.S. chlorosilane storage and handling thresholds, shaping site selection for expansion projects. India's CEA electrical safety codes intersect with chlorosilane use in photovoltaic manufacturing under the PLI scheme. Stakeholders must monitor how diverging purity certification regimes between semiconductor and solar-grade segments fragment procurement specifications.
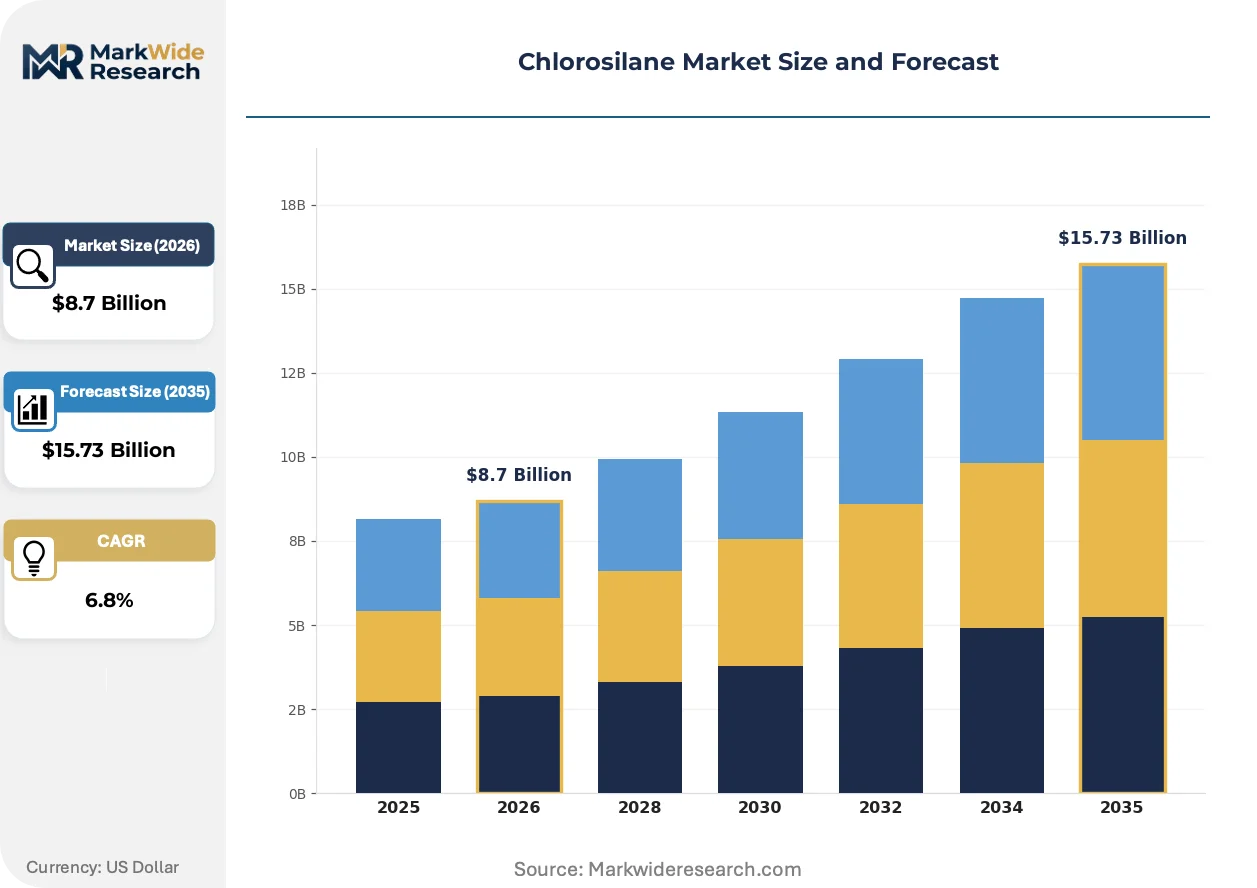
Market Dynamics
Electronics-grade purity thresholds for atomic layer deposition are compressing procurement specifications across semiconductor fabrication, forcing chlorosilane suppliers to recalibrate metallurgical impurity controls from parts-per-million to sub-parts-per-billion baselines.
Growth Catalysts
- China's dual carbon goals:Domestic polysilicon foundries in Jiangsu province are scaling integrated silane production clusters to reduce import dependency for photovoltaic and semiconductor feedstocks.
- Semiconductor node advancement:Logic chip manufacturers below 7nm are mandating dichlorosilane with metallic impurity thresholds below 0.1 ppb for gate oxide deposition processes.
- Hydrogen chloride direct synthesis:Captive metallurgical-grade silicon refining at major chemical complexes is shortening precursor supply chains for wafer-grade chlorosilane output.
Market Restraints
- Metallurgical-grade silicon price volatility:Ferrosilicon alloy competition and energy cost spikes at Chinese smelters transmit directly to chlorosilane variable cost structures.
- Emissions compliance capital intensity:China's MEE GB standards on chlorosilane wastewater treatment and atmospheric emissions are raising facility investment thresholds for new Yangtze River Delta entrants.
- Solid-state precursor substitution:Organosilane alternatives and novel silicon nitride deposition chemistries are encroaching on trichlorosilane's historical dominance in certain dielectric applications.
Strategic Opportunities
- India's PLI scheme for photovoltaic manufacturing:Domestic solar cell and module production incentives are creating captive chlorosilane demand outside traditional Chinese supply orbits.
- Silicone-polymer hybrid materials:Electric vehicle battery thermal management systems are opening specification windows for vinyltrichlorosilane-based ceramic coatings.
- Digital inventory platforms:Specialty chemical distributors are deploying AI-driven purity certification matching to reduce semiconductor foundry procurement cycle times.
Industry Challenges
- Ultra-high-purity analytical chemistry talent:ICP-MS and gas chromatography specialists capable of validating sub-ppb metallic impurity specifications remain concentrated at a handful of national metrology institutes and major supplier laboratories.
- Multi-jurisdictional certification timelines:Reconciling China's GB standards, EPA Risk Management Plan requirements, and REACH registration dossiers for the same product grade extends commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorosilane Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyldichlorosilane, Trimethylchlorosilane, Dichlorosilane, Vinyltrichlorosilane Application: Sealants, Adhesives, Coatings, Electronics End User: Chemical Industry, Electronics Manufacturers, Automotive Sector, Construction Firms Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Evonik Industries AG, Shin-Etsu Chemical Co. Ltd., Gelest Inc., Wacker Chemie AG, OCI Company Ltd., Tokuyama Corporation, Hemlock Semiconductor Corporation, The Dow Chemical Company, Zhejiang Xinan Chemical Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorosilane Market Emerging Trajectories
Atomic layer deposition process adoption is compressing chlorosilane specification windows, while regulatory emissions frameworks and procurement digitization are simultaneously reshaping supply chain configuration and commercial access models.
Electronics-grade dichlorosilane is displacing trichlorosilane in advanced logic node manufacturing due to its superior conformality in high-aspect-ratio trench structures. Taiwan Semiconductor Manufacturing Company and Samsung Foundry have both qualified dichlorosilane for 3nm gate stack deposition, with qualification timelines compressing from 36 months to 18 months as equipment suppliers standardize ALD reactor configurations. This displacement is concentrating procurement power among chlorosilane producers with captive ultra-purification capabilities, marginalizing commodity-grade suppliers from advanced node supply chains.
China's MEE is tightening GB 31571-2015 emissions standards for volatile organic compounds and acid gases from chlorosilane production facilities, with full compliance required for operating permits in the Yangtze River Delta chemical corridor. The regulation is forcing facility retrofits estimated at 15-20% of replacement capital cost for older plants, with smaller producers in Jiangsu and Zhejiang provinces facing consolidation pressure. Semiconductor-grade producers are responding by relocating integrated production to designated chemical industrial parks with centralized wastewater treatment and emissions scrubbing infrastructure.
Foundry procurement teams are compressing supplier qualification cycles from multi-year audits to continuous digital monitoring of batch purity certificates and chain-of-custody documentation. This behavioral shift is disrupting traditional distributor relationships in East Asian semiconductor clusters, with direct supplier-foundry data integration replacing arm's-length transactional purchasing. The transformation is most visible in South Korea's Pyeongtaek and Hwaseong fabrication complexes, where Samsung Electronics has deployed blockchain-based certification tracking for chlorosilane inbound logistics.
Chlorosilane Market Segmentation
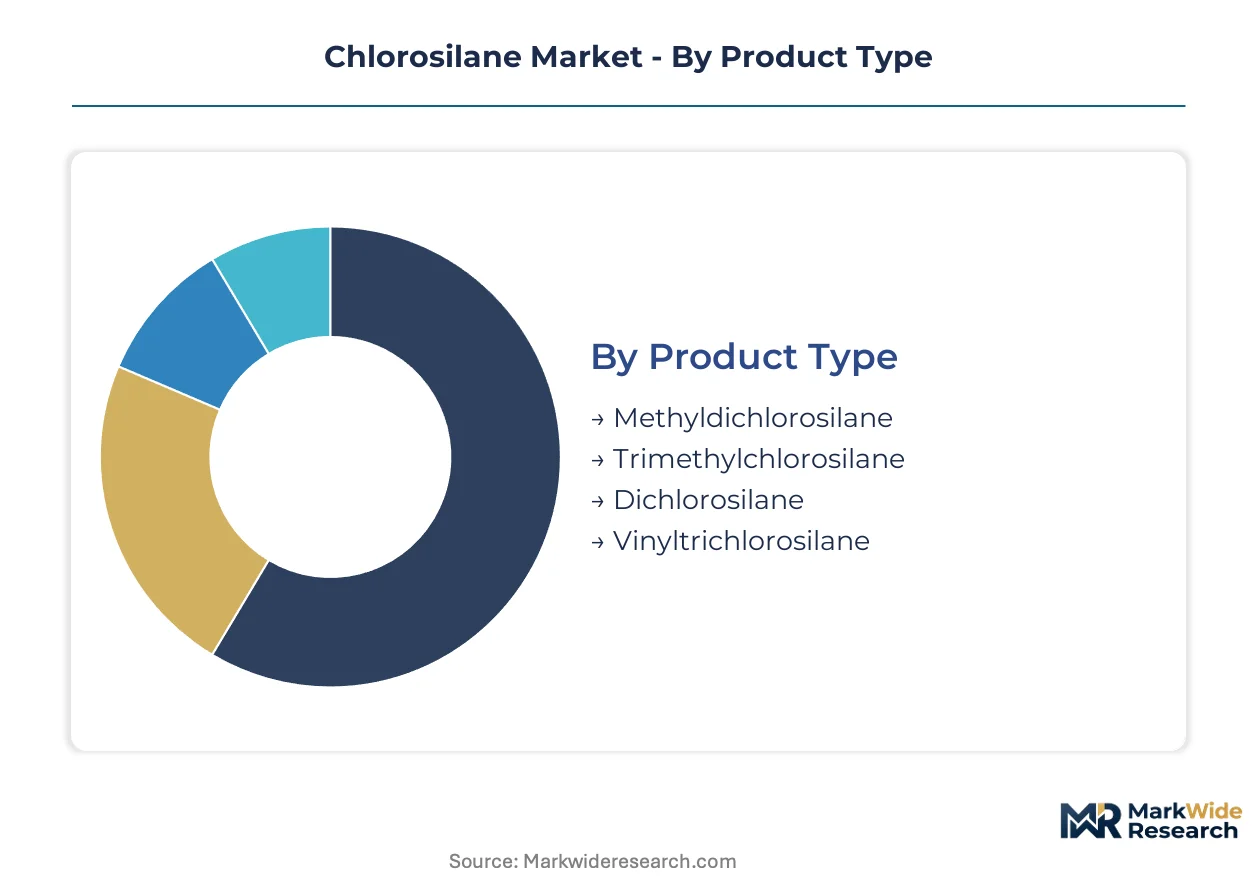
Chlorosilane procurement specifications diverge sharply across semiconductor, solar, and silicone polymer end-uses, creating distinct margin architectures that reward purity certification depth over volume scale. Suppliers must calibrate metallurgical impurity controls, packaging protocols, and logistics infrastructure to match the technical requirements of each segment tier.
Product Type:
Margin pools concentrate in electronics-grade specifications where sub-parts-per-billion metallic impurity thresholds command substantial premiums over commodity-grade alternatives.
- Dichlorosilane:This silicon-hydrogen-chlorine compound with an 8°C boiling point serves as the primary precursor for atomic layer deposition in advanced logic node manufacturing. Taiwan Semiconductor Manufacturing Company and Samsung Foundry have qualified this grade for 3nm gate stack deposition, compressing supplier qualification timelines from 36 months to 18 months as equipment standardization accelerates.
- Trimethylchlorosilane:Boiling at 57°C, this compound anchors silicone polymer synthesis for sealant and adhesive cross-linking applications where formulation chemistry has stabilized over decades. Jiangsu province's chemical industrial parks host integrated production clusters serving domestic polysilicon foundries with captive supply arrangements that bypass merchant market volatility.
- Methyldichlorosilane:Mature volume position in sealant and adhesive applications with standardized formulation requirements.
- Vinyltrichlorosilane:Ceramic coating precursor for electric vehicle battery thermal management systems opening specification windows in automotive silicone-polymer hybrids.
The dominant share belongs to trimethylchlorosilane, while dichlorosilane is closing the gap fastest.
Application:
Application-driven procurement patterns reflect divergent purity certification regimes between semiconductor fabrication and construction chemical segments.
- Electronics:Atomic layer deposition processes in logic chip manufacturing mandate metallic impurity thresholds below 0.1 ppb, concentrating demand among producers with captive ultra-purification capabilities. China's dual carbon goals are scaling domestic polysilicon foundry capacity in Jiangsu province, tightening import substitution timelines for wafer-grade feedstocks.
- Sealants:Methyldichlorosilane and vinyltrichlorosilane occupy established positions in cross-linking chemistry where decades of formulation refinement have locked in specification stability. Construction sector procurement prioritizes volume consistency over purity premiums, compressing margins for merchant-grade suppliers.
- Adhesives:Mature segment with standardized performance requirements and price-sensitive procurement patterns.
- Coatings:Emerging demand from electric vehicle battery thermal management systems creating ceramic coating applications.
Electronics commands the steepest margin expansion trajectory, though sealants retain the largest volume footprint.
End User:
End user concentration patterns reveal how captive chlorosilane production at major chemical complexes is reshaping merchant market access.
- Electronics Manufacturers:Logic chip foundries below 7nm are unwinding historical reliance on commodity-grade chlorosilanes as polysilicon purity requirements tighten. Samsung Electronics has deployed blockchain-based certification tracking for inbound logistics at Pyeongtaek and Hwaseong fabrication complexes.
- Chemical Industry:Integrated silicone-polymer producers like Wacker Chemie AG anchor European output through Burghausen chemical site complexes with captive metallurgical-grade silicon refining.
- Automotive Sector:Electric vehicle battery thermal management systems opening specification windows for vinyltrichlorosilane-based ceramic coatings.
- Construction Firms:Price-sensitive procurement of sealant and adhesive feedstocks with standardized performance requirements.
Electronics manufacturers hold the dominant procurement value position, while the automotive sector is expanding most quickly.
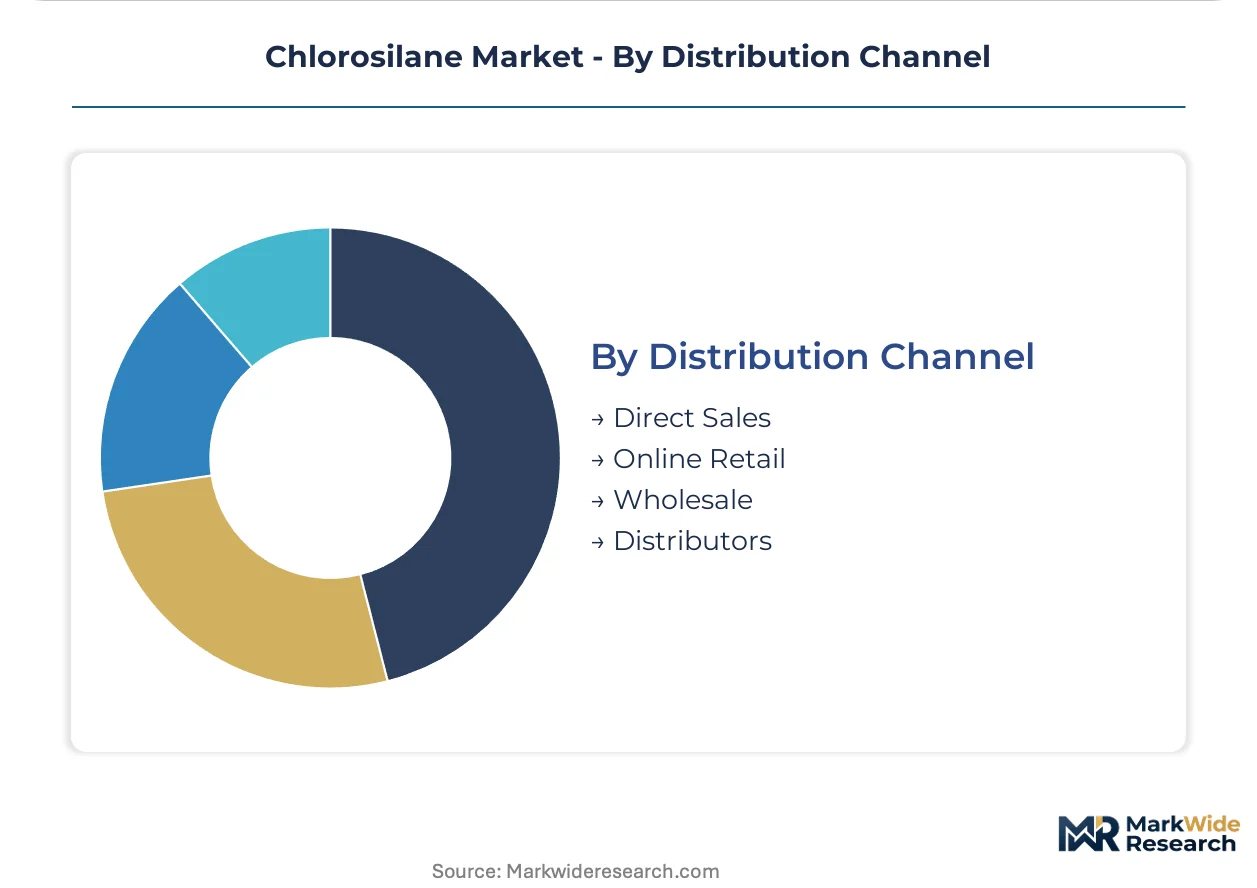
Distribution Channel:
Channel economics are compressing as foundry procurement teams shift from multi-year audits to continuous digital monitoring of batch purity certificates.
- Direct Sales:Semiconductor-grade producers are bypassing traditional distributor relationships through direct supplier-foundry data integration. This behavioral shift is most visible in South Korean fabrication clusters where purity certification matching reduces procurement cycle times.
- Distributors:Specialty chemical distributors are deploying AI-driven purity certification matching to maintain relevance in East Asian semiconductor clusters, though margin pressure intensifies as direct channels expand.
- Wholesale:Volume channel for construction and automotive segments with standardized grade requirements.
- Online Retail:Emerging platform for small-volume procurement of research-grade specifications.
Direct sales capture the dominant share, while distributor channels are adapting fastest to digital certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorosilane supply chains concentrate in East Asian chemical corridors where integrated polysilicon production clusters anchor wafer-grade output. Four countries dominate capacity configuration and regulatory frameworks shaping merchant market access.
China
Jiangsu province's chemical industrial parks host captive silane production clusters serving domestic semiconductor and photovoltaic foundries. The MEE enforces GB 31571-2015 emissions standards requiring facility retrofits estimated at 15-20% of replacement capital cost for older plants in the Yangtze River Delta corridor. Dual carbon goals are accelerating import substitution timelines for wafer-grade feedstocks at integrated complexes in Nantong and Zhangjiagang.
United States
Michigan-based polysilicon verticals dominate domestic semiconductor-grade trichlorosilane supply for advanced logic manufacturing. The EPA's Risk Management Plan and OSHA Process Safety Management requirements govern storage and handling thresholds, shaping site selection for expansion projects in the Midwest chemical belt. Hemlock Semiconductor Corporation anchors regional output through captive metallurgical-grade silicon refining operations.
Germany
Burghausen chemical site complexes integrate silicone-polymer production with captive chlorosilane output for European semiconductor and automotive supply chains. ECHA REACH registration dossiers and the EU Green Deal emissions framework extend commercialization timelines for new product grades entering the common market. Wacker Chemie AG exemplifies the integrated chemical complex model dominating regional capacity.
Japan
Shin-Etsu Chemical Co. Ltd. leverages captive silicon metal refining to sustain wafer-grade supply continuity across East Asian fabrication corridors. METI industrial policy supports domestic polysilicon self-sufficiency targets while JIS standards govern specialty chemical purity certification protocols. The company maintains integrated production from metallurgical-grade silicon through electronics-grade chlorosilane derivatives.
South Korea
Pyeongtaek and Hwaseong fabrication complexes deploy blockchain-based certification tracking for chlorosilane inbound logistics at Samsung Electronics operations. MFDS chemical safety codes intersect with semiconductor manufacturing requirements, while the CEA electrical safety framework governs photovoltaic manufacturing integration. Domestic procurement teams compress supplier qualification cycles through continuous digital monitoring of batch purity certificates.
Chlorosilane Market Vendor Landscape
Concentration sits with integrated chemical conglomerates possessing captive metallurgical-grade silicon refining and ultra-purification capabilities. The vendor base stratifies across three tiers: multinational silicone-polymer majors with backward integration into silicon metal, semiconductor-grade specialists with dedicated polysilicon verticals, and regional Chinese producers serving commodity sealant and adhesive applications. Dominant competitive moves include capacity relocation to designated chemical industrial parks with centralized emissions infrastructure, and direct data integration with foundry procurement systems bypassing traditional distributor channels.
Among German chemical conglomerates, Evonik Industries AG and Wacker Chemie AG exemplify the integrated silicone-polymer complex archetype with captive chlorosilane production. Shin-Etsu Chemical Co. Ltd. represents the East Asian vertical integration model, while Hemlock Semiconductor Corporation occupies the semiconductor-grade specialist position in North American supply chains. These three anchors illustrate how purity certification depth and metallurgical impurity control capabilities determine competitive positioning across diverging end-use specifications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Shin-Etsu Chemical Co. Ltd. |
| Gelest Inc. |
| Wacker Chemie AG |
| OCI Company Ltd. |
| Tokuyama Corporation |
| Hemlock Semiconductor Corporation |
| The Dow Chemical Company |
| Zhejiang Xinan Chemical Group Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Twenty-one-day inventory buffers at Jiangsu province chemical parks compress procurement cycles while amplifying pricing leverage for integrated silane producers serving semiconductor foundries. This lead-time compression tightens the link between captive metallurgical-grade silicon supply and electronics-grade chlorosilane premiums.
Pricing Analysis
China's MEE GB 31571-2015 emissions standards dictate the pricing tier structure across Yangtze River Delta production corridors. Three-tier pricing structure across electronics-grade, solar-grade, and industrial-grade levels separates sub-ppb purity certification from commodity sealant feedstocks. Cost compression in merchant-grade trimethylchlorosilane is intensifying because Jiangsu province's integrated clusters bypass spot market volatility through captive supply arrangements. Construction sector buyers exhibit highest price sensitivity, while logic chip foundries below 7nm absorb premiums for dichlorosilane with metallic impurity thresholds below 0.1 ppb.
Supply Chain Analysis
Container availability constraints on Shanghai-Ningbo trade lanes elevate inbound logistics costs for metallurgical-grade silicon feedstocks entering Yangtze River Delta chlorosilane complexes. Supply concentrates in China, the United States, and Germany, with Michigan-based polysilicon verticals and Burghausen chemical site complexes anchoring regional output. Raw material dependencies rest on metallurgical-grade silicon, hydrogen chloride, and specialized stainless-steel reactor components. Single-source vulnerability in ultra-high-purity analytical chemistry talent concentrates validation capabilities at national metrology institutes. Distribution runs through direct supplier-foundry data integration channels that bypass traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor capital expenditure cycles position chlorosilane demand for recovery as logic node advancement restarts capacity expansion timelines. Foundry equipment utilization rates serve as the cyclical anchor.
For Market Incumbents: Compound backward integration into metallurgical-grade silicon refining to secure feedstock continuity against ferrosilicon alloy competition and energy cost spikes at Chinese smelters. Deepen ultra-purification capabilities to defend electronics-grade margins against solid-state precursor substitution in dielectric applications. Prioritize facility relocation to designated chemical industrial parks with centralized emissions scrubbing infrastructure ahead of MEE compliance deadlines. For New Entrants and Emerging Players: Digital inventory platforms represent the service-layer gap where incumbents under-serve mid-size photovoltaic manufacturers outside integrated supply orbits. Target India's PLI scheme beneficiaries with AI-driven purity certification matching that compresses procurement cycle times for domestic solar cell producers. Deploy direct data integration models to bypass entrenched distributor relationships in emerging chemical manufacturing corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core chlorosilane assets lacking semiconductor-grade certification depth. Five-to-ten-year viability hinges on polysilicon self-sufficiency targets and dual carbon goal acceleration across Asia-Pacific manufacturing belts. Monitor Samsung Electronics blockchain-based certification tracking deployment as the signal for procurement digitization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallurgical-Grade Silicon | Captive silicon metal refining secures wafer-grade chlorosilane supply continuity for East Asian fabrication corridors. |
| Facility Relocation to Designated Chemical Industrial Parks | Centralized wastewater treatment infrastructure satisfies MEE GB 31571-2015 emissions compliance for Yangtze River Delta operations. |
| Ultra-Purification Capability Investment | Sub-ppb metallic impurity validation qualifies dichlorosilane for 3nm gate stack deposition at TSMC and Samsung Foundry. |
| Direct Supplier-Foundry Data Integration | Blockchain-based certification tracking compresses procurement cycles at Pyeongtaek and Hwaseong fabrication complexes. |
| Digital Inventory Platform Deployment | AI-driven purity certification matching reduces semiconductor foundry procurement cycle times through automated batch validation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polysilicon plant managers, semiconductor procurement leads, silicone-polymer R&D directors, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of integrated chemical conglomerates, MEE emissions compliance disclosures, and semiconductor equipment supplier technical specifications. Bottom-up capacity modeling and top-down demand aggregation were triangulated to reconcile divergent purity certification regimes across end-use segments.
Across the projection horizon, the analytical framework modeled chlorosilane output by product type, application purity tier, end-user concentration patterns, and regional production hub configuration. CAGRs were derived from segmented volume trajectories calibrated against polysilicon foundry expansion timelines and photovoltaic manufacturing capacity additions. Forecast inputs incorporated logic node advancement roadmaps, dual carbon policy implementation velocity, and emissions retrofit capital intensity estimates for Yangtze River Delta facilities.
Underlying assumptions cover sustained semiconductor capital expenditure recovery, stable metallurgical-grade silicon feedstock availability, and gradual solid-state precursor substitution limits, with deviation risk concentrated in multi-jurisdictional certification timeline extensions and abrupt regulatory emissions threshold tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phenylethyl Market
Chemicals
Benzenoid Market
Chemicals
Pentanedione Market
Chemicals
United Kingdom Methanol Market
Chemicals
Calcium Hydroxide Market
Chemicals
Sodium Azide Market
Chemicals
Elemental Fluorine Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Menadione Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
CHPTAC Market
Chemicals
Europe Biguanide Market