
 Glyoxylic Acid Market | 2026-2036
Glyoxylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Glyoxylic Acid Market Outlook
Pharmaceutical formulators are reorganizing procurement priorities around glyoxylic acid purity grades for active pharmaceutical ingredient intermediates. Akema S.r.l. leverages its European manufacturing base to supply high-purity grades for regulated drug applications. STAN Chemical Co., Ltd anchors volume production through integrated nitric acid oxidation capabilities in China. WeylChem International GmbH differentiates via specialized glyoxylic acid derivatives serving European cosmetics and fine chemical customers.
Glyoxylic acid is an organic compound with the formula OCHCOOH, typically produced through nitric acid oxidation of glyoxal or catalytic oxidation of acetaldehyde, yielding aqueous solutions at 40-50% concentration for industrial use. The chemical serves as a versatile building block for synthesizing aromas, agrochemicals, and pharmaceutical intermediates through its dual aldehyde and carboxylic acid functionality. Glyoxylic Acid Monohydrate commands the largest product share due to its handling stability and compatibility with pharmaceutical synthesis protocols. Dye Manufacturing applications exhibit the fastest structural expansion as textile producers in South Asia substitute conventional reducing agents with glyoxylic acid-based alternatives for environmental compliance.
China's SAMR enforces GB standards on industrial chemical purity that filter out uncertified glyoxylic acid producers from pharmaceutical supply chains. The EU REACH regulation and ECHA substance evaluations impose registration burdens on glyoxylic acid importers that favor established European manufacturers with compliance infrastructure. India's CDSCO aligns active pharmaceutical ingredient import rules with ICH Q3D guidelines, elevating trace metal specifications that glyoxylic acid suppliers must certify. Stakeholders must monitor evolving pharmaceutical-grade certification requirements across multiple jurisdictions to sustain market access and margin positioning.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while redirecting procurement toward integrated manufacturers with captive nitric acid oxidation capabilities and validated quality management systems.
Growth Catalysts
- API Intermediate Demand:Pharmaceutical formulators in India and China are expanding glyoxylic acid offtake for cephalosporin and allantoin synthesis, tightening specifications on aldehyde content and trace metals.
- REACH Registration Completion:ECHA substance evaluation milestones for glyoxylic acid have clarified compliance pathways, reducing regulatory uncertainty for European fine chemical buyers and enabling contract volume expansion.
- East China Chemical Cluster Concentration:Integrated production sites in Jiangsu and Zhejiang provinces achieve feedstock-to-derivative economics that standalone Western converters cannot replicate, anchoring export supply.
Market Restraints
- Nitric Acid Price Volatility:Feedstock cost swings for the dominant oxidation route compress margins at non-integrated producers, particularly those reliant on merchant acid purchases.
- Chinese Supply Concentration Risk:Over two-thirds of merchant glyoxylic acid volume originates from Shandong and Jiangsu province facilities, creating single-geography exposure for global pharmaceutical formulators.
- Formaldehyde Substitution Pressure:Textile finishing applications in Bangladesh and Vietnam are testing glyoxal-based alternatives that bypass glyoxylic acid entirely for certain reducing-agent functions.
Strategic Opportunities
- Brazilian Agrochemical Formulation:ANVISA registration pathways for glyoxylic acid-derived crop protection intermediates remain underdeveloped, offering first-mover positioning for certified suppliers.
- Biocatalytic Oxidation Routes:Enzymatic conversion of glycolic acid using engineered aldehyde dehydrogenases promises to bypass nitric acid entirely, appealing to cosmetics brands with Scope 3 reduction commitments.
- EU Green Deal Chemicals Strategy:The sustainable-by-design framework elevates glyoxylic acid's profile as a C2 building block with favorable biodegradation profiles versus petrochemical alternatives in fragrance synthesis.
Industry Challenges
- ICH Q3D Implementation Gap:Pharmaceutical-grade suppliers must demonstrate elemental impurity control across raw material streams, requiring analytical capability investments that smaller Chinese converters struggle to fund.
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with USP-NF, EP, and ChP monographs for glyoxylic acid monohydrate creates documentation burdens that extend qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyoxylic Acid Market |
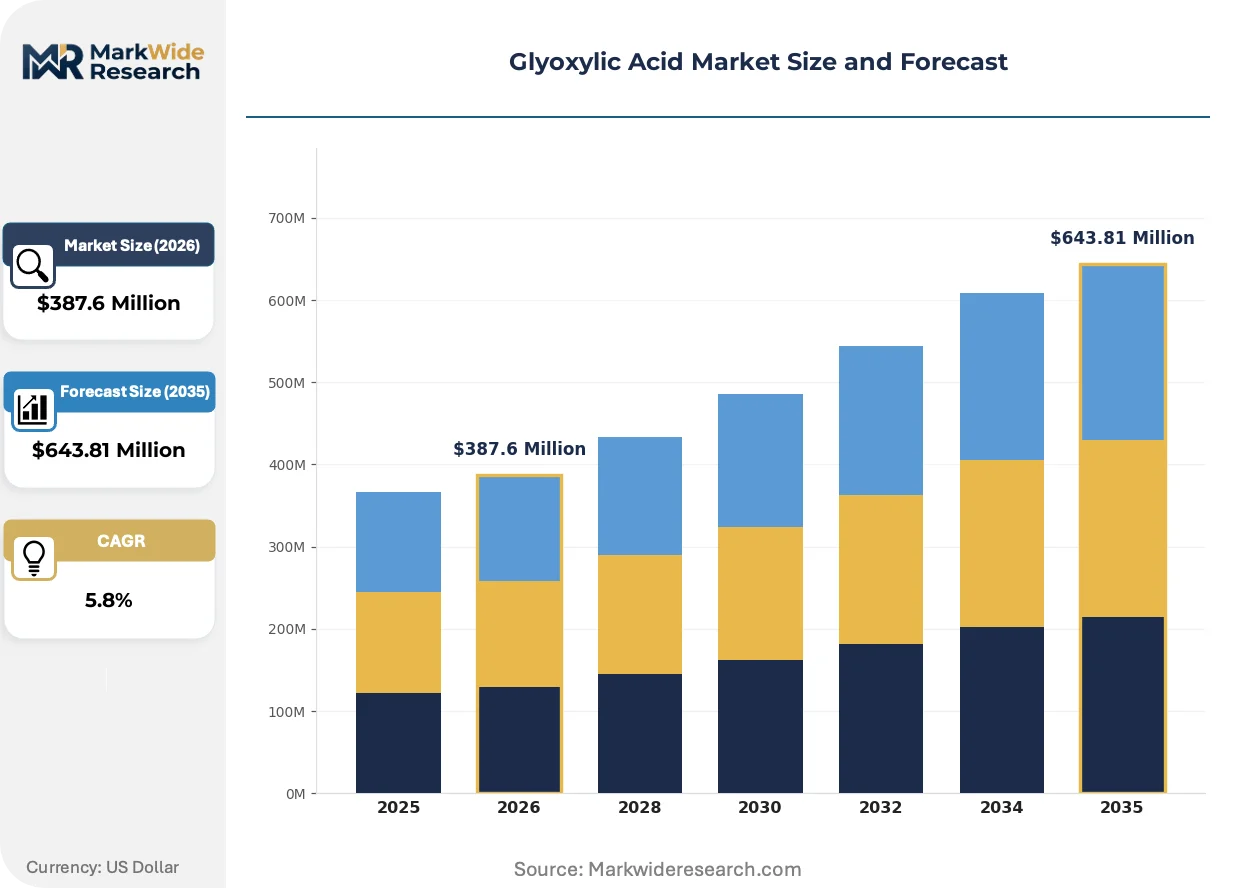
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glyoxylic Acid Monohydrate, Glyoxylic Acid Anhydrous, Glyoxylic Acid Derivatives, Ethylene Glycol End Use Industry: Textiles, Cosmetics, Pharmaceuticals, Agriculture Application: Resin Production, Dye Manufacturing, Antioxidants, Chemical Synthesis Delivery Mode: Bulk Supply, Packaged Supply, Liquid Form, Powder Form |
| Companies Covered | Akema S.r.l., Zhonglan Industry Co., Ltd, STAN Chemical Co., Ltd, Xinjiang Guolin New Materials Co., Ltd, WeylChem International GmbH, Haihang Industry, Hubei Hongyuan Pharmaceutical Technology Co., Ltd, JIAXING ZHONGHUA CHEMICAL Co., Ltd, Amzole India Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyoxylic Acid Market Strategic Shifts
Electrochemical synthesis routes and membrane separation technologies are disrupting the nitric-acid-dominated production paradigm, while regulatory chemistry restrictions in the European Union and textile sustainability mandates in South Asia reshape demand composition.
Membrane electrodialysis for glyoxylic acid purification is decomposing the traditional crystallization-evaporation sequence that has defined monohydrate production for three decades. Specialty chemical distributors in Germany and Switzerland are qualifying electrochemically refined grades for high-value fragrance intermediates. The technology is decomposing cost structures for sub-50-ton annual volume requirements that previously forced buyers toward standardized Chinese merchant supply.
EU F-Gas Regulation restrictions on perfluorinated membrane materials are forcing glyoxylic acid producers to source alternative ion-exchange components for electrochemical cells. Industrial gas suppliers with fluoropolymer recycling capabilities are capturing premium positioning in the retrofit supply chain. German fine chemical manufacturers are accelerating in-house membrane development partnerships to avoid import dependency on Chinese fluorinated material suppliers.
Direct long-term contracting between pharmaceutical API manufacturers and glyoxylic acid producers is displacing the merchant distributor channel that historically intermediated Asian supply. CDSCO-aligned Indian formulators are demanding audit rights over nitric acid sourcing and oxidation reactor conditions as contractual prerequisites. This pattern is most visible among Mumbai and Hyderabad-based generic API exporters supplying regulated European and North American markets.
Glyoxylic Acid Market Segmentation
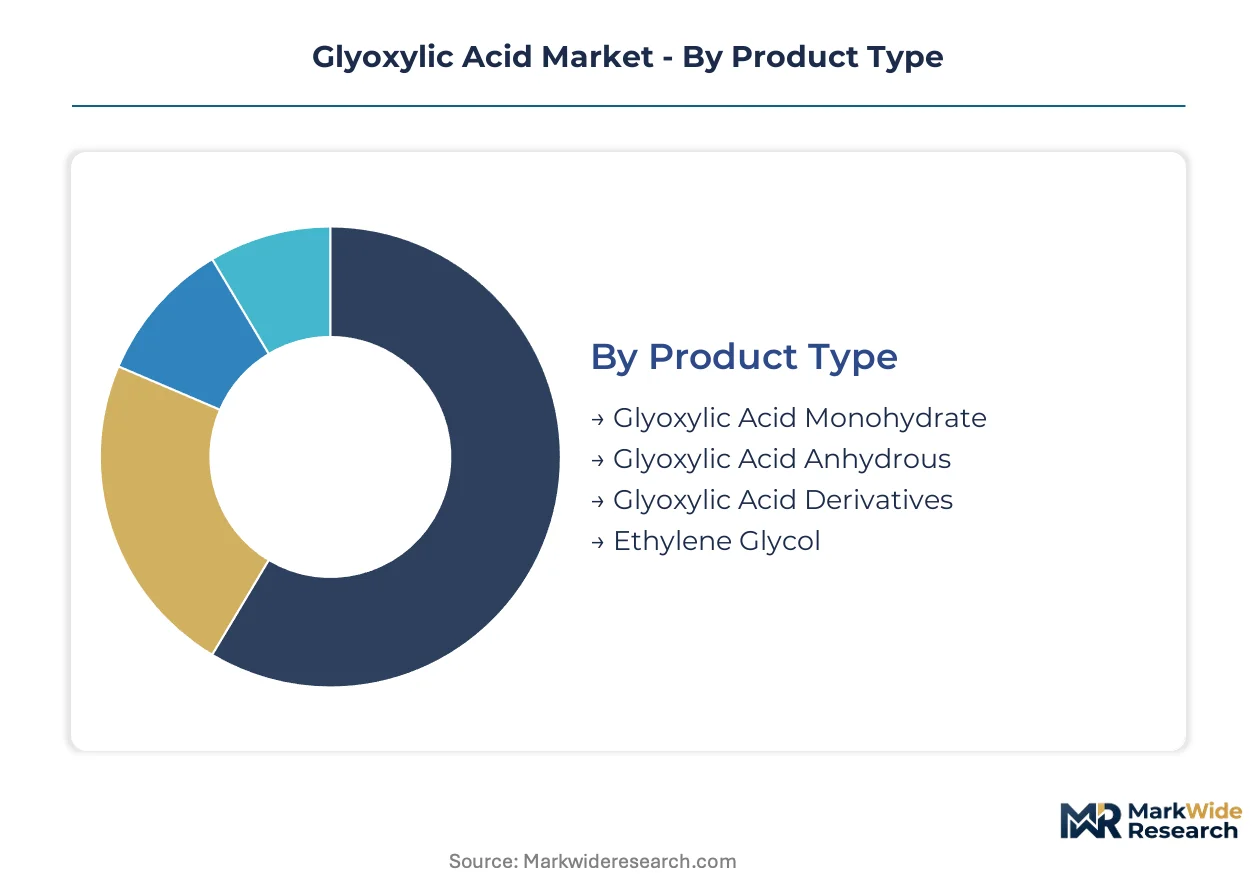
Glyoxylic acid segmentation reveals how purity grades, delivery formats, and application specifications fragment procurement patterns across pharmaceutical, textile, and agrochemical value chains. Understanding these divides exposes where integrated producers capture margin premiums versus commodity converters competing on volume.
Product Type:
Domestic Chinese consumption concentrates on standard-grade monohydrate for textile and agrochemical applications, while export demand tilts toward high-purity anhydrous grades serving European pharmaceutical and fragrance synthesis.
- Glyoxylic Acid Monohydrate:Crystalline solid at 98% minimum assay with controlled water content provides handling stability for long-haul shipping and extended storage. Pharmaceutical formulators in Hyderabad and Mumbai specify monohydrate for cephalosporin intermediate synthesis under CDSCO-aligned import protocols. The segment anchors volume production at Jiangsu and Shandong facilities serving both domestic textile mills and export API manufacturers.
- Glyoxylic Acid Anhydrous:Water-free formulation at 99%+ purity enables precise stoichiometry in moisture-sensitive fragrance and fine chemical reactions. German and Swiss specialty distributors qualify anhydrous grades for high-value aroma chemical production where trace moisture compromises yield. Supply concentrates at European electrochemical refiners and select Chinese exporters with membrane purification capabilities.
- Glyoxylic Acid Derivatives:Functionalized variants including glyoxylic acid esters and amides serve niche cosmetic and agrochemical formulation requirements.
- Ethylene Glycol:Co-product stream from certain oxidation routes finds secondary application in polyester precursor manufacturing.
Glyoxylic Acid Monohydrate holds the largest share; momentum sits with Glyoxylic Acid Anhydrous as European fragrance houses tighten purity specifications.
End Use Industry:
Cost tier stratification separates premium pharmaceutical-grade supply from standard industrial grades, with certification investments creating margin cliffs between regulated and unregulated applications.
- Pharmaceuticals:Active pharmaceutical ingredient intermediates for allantoin, cephalosporin side chains, and synthetic building blocks demand ICH Q3D-compliant elemental impurity profiles. Indian generic API exporters in Mumbai and Hyderabad now require audit rights over nitric acid sourcing and oxidation reactor conditions. CDSCO-aligned trace metal specifications filter out uncertified Chinese converters lacking analytical infrastructure.
- Textiles:Reducing agent substitution in dye fixation and finishing applications drives volume offtake across Bangladesh, Vietnam, and South Asian garment manufacturing hubs. Environmental compliance pressures displace conventional sulfite-based reducing agents with glyoxylic acid alternatives that reduce effluent toxicity. Procurement concentrates among integrated dye houses seeking dual cost and compliance advantages.
- Cosmetics:Hair straightening formulations and personal care intermediates utilize glyoxylic acid derivatives for formaldehyde-free alternatives.
- Agriculture:Crop protection intermediate synthesis for herbicide and fungicide active ingredients represents emerging demand from Brazilian and Argentinian formulators.
Pharmaceuticals commands premium pricing; Textiles generates steepest volume expansion as South Asian environmental mandates accelerate substitution.
Application:
Volume scale separates bulk resin and dye manufacturing from specialized antioxidant and fine chemical synthesis requiring sub-50-ton annual deliveries.
- Dye Manufacturing:Textile reducing agent applications in vat dye fixation and discharge printing substitute glyoxylic acid for environmentally restricted alternatives. Bangladeshi and Vietnamese dye houses expand offtake as buyer compliance programs from European apparel brands mandate cleaner chemical inputs. The segment climbs fastest as regulatory chemistry restrictions tighten across EU and North American import markets.
- Resin Production:Urea-glyoxylic acid condensation products serve as crosslinking agents for permanent-press textile finishes and wood adhesive formulations. Chinese resin compounders in Zhejiang province anchor merchant demand through integrated feedstock access. Specifications emphasize aldehyde content control for consistent curing performance.
- Antioxidants:Glyoxylic acid-derived phenolic compounds stabilize polymers and lubricants against oxidative degradation.
- Chemical Synthesis:Versatile C2 building block functionality enables custom fine chemical and pharmaceutical intermediate production.
Resin Production holds established volume; Dye Manufacturing gains share fastest as environmental substitution accelerates.
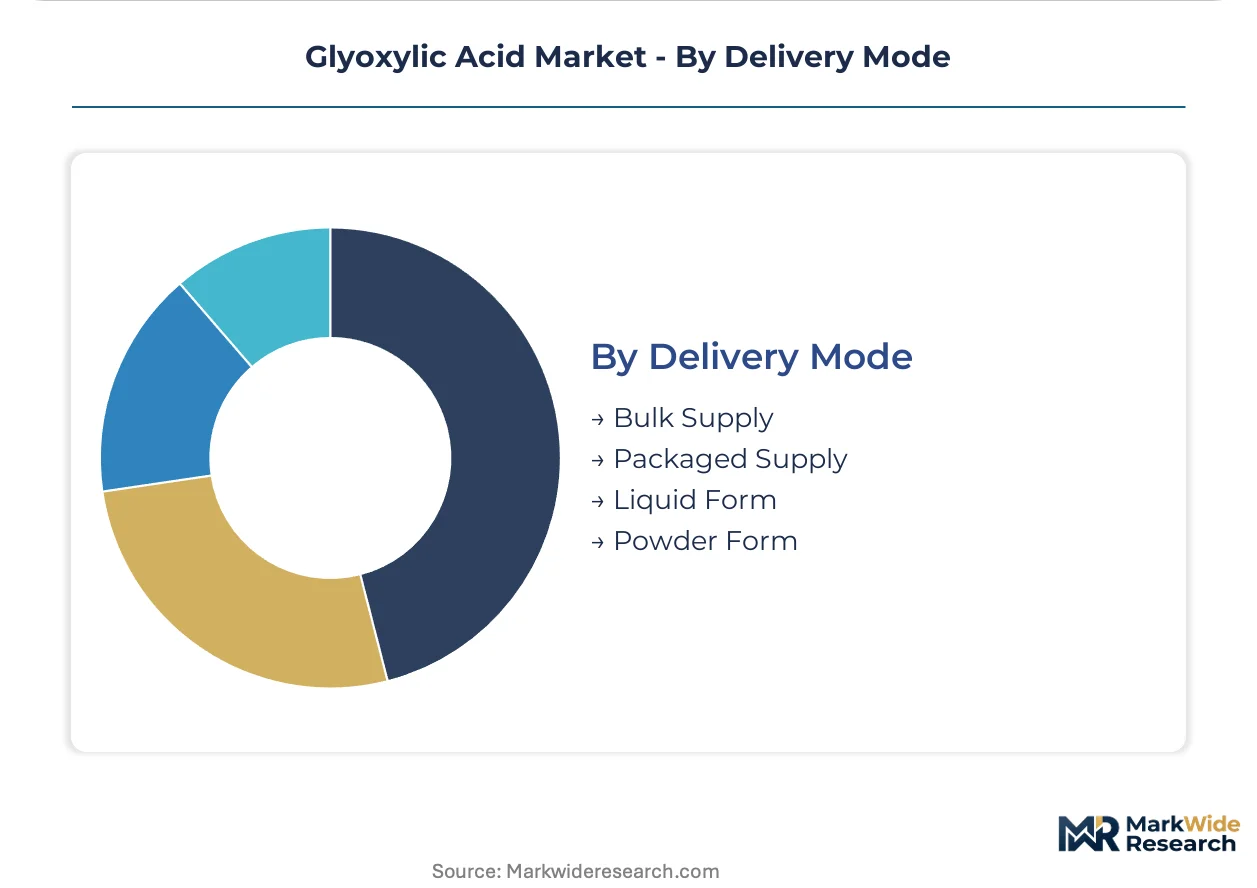
Delivery Mode:
Customer type fragmentation separates multinational pharmaceutical formulators demanding packaged, certified supply from textile mills accepting bulk liquid delivery.
- Bulk Supply:Tanker and ISO-container liquid delivery at 40-50% aqueous concentration serves high-volume textile and resin manufacturers with on-site storage infrastructure. East China chemical clusters around Shanghai and Jiangsu province optimize logistics economics through pipeline and short-haul tanker networks. Procurement concentrates among integrated downstream processors with captive formulation capabilities.
- Liquid Form:Standard aqueous solution packaging in drums and IBC totes bridges bulk and packaged supply for mid-scale processors.
- Packaged Supply:Drummed and palletized solid monohydrate caters to pharmaceutical and fine chemical users requiring batch traceability and contamination control. Swiss and German distributors maintain inventory positions for just-in-time delivery to fragrance houses and API manufacturers. Documentation burdens including COA, MSDS, and regulatory certificates accompany each shipment.
- Powder Form:Micronized solid grades facilitate precise dosing in automated pharmaceutical and cosmetic manufacturing lines.
Bulk Supply dominates volume throughput; Packaged Supply expands most quickly as pharmaceutical direct-contracting displaces merchant distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese glyoxylic acid shipments dominate cross-border supply to European pharmaceutical formulators and Indian API manufacturers, with Jiangsu and Shandong province facilities anchoring export volumes.
China
Jiangsu and Zhejiang province chemical clusters feed pharmaceutical-grade demand from Mumbai and Hyderabad formulators. SAMR enforces GB standards on industrial chemical purity that filter uncertified producers from regulated supply chains. Shanghai port logistics optimize bulk liquid export economics to South Asian textile processors.
India
Mumbai and Hyderabad-based generic API exporters expand glyoxylic acid offtake for cephalosporin and allantoin synthesis. CDSCO aligns active pharmaceutical ingredient import rules with ICH Q3D guidelines, elevating trace metal specifications. Gujarat dye houses substitute conventional reducing agents with glyoxylic acid alternatives for European apparel brand compliance.
Germany
Rhineland-Palatinate and North Rhine-Westphalia fine chemical manufacturers qualify electrochemically refined grades for fragrance intermediate production. ECHA substance evaluation milestones for glyoxylic acid have clarified REACH compliance pathways. Frankfurt specialty distributors maintain inventory positions for just-in-time delivery to Swiss and French aroma houses.
United States
New Jersey and Pennsylvania pharmaceutical formulators source packaged monohydrate grades for cephalosporin side chain synthesis. FDA enforces elemental impurity controls under ICH Q3D that elevate analytical certification burdens. Gulf Coast chemical distributors bridge Asian bulk supply with domestic batch-traceability requirements.
Brazil
São Paulo and Minas Gerais agrochemical formulators test glyoxylic acid-derived crop protection intermediates for regional herbicide markets. ANVISA registration pathways for glyoxylic acid derivatives remain underdeveloped, offering positioning opportunities. Port of Santos logistics infrastructure handles incremental import volumes from Chinese merchant suppliers.
Glyoxylic Acid Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and oxidation technology access. The vendor base stratifies between integrated nitric acid oxidizers with captive feedstock and merchant converters dependent on spot acid markets. Three archetypes dominate: Jiangsu-based volume producers, European electrochemical refiners, and Indian import-dependent formulators. Capacity expansion and direct long-term contracting displace traditional distributor channels.
Within the European electrochemical tier, WeylChem International GmbH exemplifies specialized glyoxylic acid derivative supply for cosmetics and fine chemical customers. Akema S.r.l. occupies a position serving high-purity pharmaceutical grades from its Italian manufacturing base. Among Chinese volume producers, STAN Chemical Co., Ltd anchors merchant supply through integrated oxidation capabilities. These three represent distinct competitive positions: European specialty refinement, Mediterranean pharmaceutical certification, and East Asian scale production.
| Leading Market Players |
|---|
| Akema S.r.l. |
| Zhonglan Industry Co., Ltd |
| STAN Chemical Co., Ltd |
| Xinjiang Guolin New Materials Co., Ltd |
| WeylChem International GmbH |
| Haihang Industry |
| Hubei Hongyuan Pharmaceutical Technology Co., Ltd |
| JIAXING ZHONGHUA CHEMICAL Co., Ltd |
| Amzole India Pvt. Ltd |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Jiangsu and Shandong oxidation facilities anchors regional cost floors, concentrating pricing power among integrated nitric acid producers while squeezing merchant-dependent converters. This scale asymmetry shapes procurement negotiations, with pharmaceutical formulators accepting premium certification-grade pricing to secure supply continuity against concentrated geography risk.
Pricing Analysis
Nitric-acid-generation pricing gaps separate legacy oxidation facilities from emerging electrochemical refiners, with membrane-purified anhydrous grades commanding substantial premiums over standard monohydrate. Contract-based long-term offtake dominates pharmaceutical procurement, where ICH Q3D certification tier and audit-rights bundling drive price differentiation. Cost compression in standard-grade supply is intensifying because Shandong merchant producers compete for textile mill volume. Bangladeshi dye houses exhibit highest price sensitivity; Swiss fragrance houses demonstrate lowest.
Supply Chain Analysis
China and India anchor glyoxylic acid supply, with Jiangsu province facilities feeding pharmaceutical-grade export demand and Mumbai-Hyderabad formulators driving API intermediate consumption. Nitric acid, glyoxal feedstock, and fluorinated membrane materials constitute critical input dependencies. Single-source vulnerability concentrates in Shandong merchant oxidation capacity. Distribution runs through direct long-term contracting between API manufacturers and integrated producers, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glyoxylic acid sits in early-cycle expansion as pharmaceutical-grade certification requirements penetrate Indian and Chinese API supply chains, accelerating adoption of audited, high-purity supply relationships.
For Market Incumbents: Consolidate oxidation capacity integration and certification infrastructure to defend against electrochemical refining entrants and regulatory exclusion. Deepen backward integration into nitric acid production to neutralize feedstock volatility. Prioritize CDSCO and ECHA compliance investments to lock in Mumbai and European formulator contracts. For New Entrants and Emerging Players: Electrochemical purification service gaps in sub-50-ton fragrance intermediate volumes offer white-space positioning against Chinese bulk supply. Target Swiss and German specialty distributors with membrane-refined anhydrous grades. Pursue direct technical partnerships with fragrance houses seeking Scope 3 reduction credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated oxidation producers with pharmaceutical certification and captive nitric acid supply. Long-term viability favors backward-integrated assets with multi-jurisdiction compliance infrastructure. Monitor ANVISA registration progress as inflection signal for Brazilian agrochemical derivative demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitric Acid | Neutralizes feedstock volatility for Jiangsu and Shandong oxidation facilities. |
| Electrochemical Refining Capacity Addition | Bypasses nitric acid entirely, appealing to EU Green Deal-aligned fragrance customers. |
| Pharmaceutical-Grade Certification Investment | Enables CDSCO and ECHA compliance for Mumbai and European API supply. |
| Direct Long-Term Supply Agreement | Displaces distributor channels, securing audit rights for Hyderabad formulators. |
| ANVISA Registration Pathway Development | Opens Brazilian agrochemical intermediate market for first-mover positioning. |
Study Parameters
Operator-level perspectives from oxidation plant managers, pharmaceutical procurement leads at Mumbai and Hyderabad API exporters, and specialty chemical distribution partners anchored the qualitative base. Secondary validation drew from customs trade data, CDSCO import filings, ECHA substance evaluation records, and SEC disclosures from listed chemical producers. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis.
Sensitivity analysis tested forecast outputs across feedstock cost volatility, regulatory implementation timing, and substitution elasticity scenarios. Segmentation dimensions included purity grade tier, end-use industry, delivery mode format, and regional production hub classification. CAGRs were derived from installed capacity utilization trajectories and downstream demand elasticity modeling, incorporating nitric acid price correlation and pharmaceutical certification penetration rates.
Forecasts assume regulatory continuity in ECHA REACH enforcement and CDSCO ICH Q3D alignment; material policy shifts in purity standards or import documentation would require re-modeling. Specific risks include Chinese environmental enforcement tightening, EU F-Gas membrane material restrictions, and Brazilian ANVISA registration delays. Recalibration cycles align with material shifts in pharmaceutical certification mandates and electrochemical technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global N-Butanol Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Canada Methanol Market
Chemicals
Lime Sulfur Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
1, 4 Butanediol Market
Chemicals
Pinoxaden Market
Chemicals
Roofing Chemical Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
China Amines Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Aluminum Phosphide Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Egypt Acidulants Market
Chemicals
North America Tartaric Acid Market