
 Germany Sodium Reduction Ingredient Market | 2026-2036
Germany Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Sodium Reduction Ingredient Market Foresight
Modular ingredient bundling is shifting how German food manufacturers procure sodium reduction systems, moving from single-chemical substitutes to pre-blended mineral complexes with integrated flavor masking. Cargill Incorporated leverages its broad portfolio to supply bundled potassium chloride and yeast extract systems for processed meat applications. Jungbunzlauer Suisse AG specializes in mineral salt blends that anchor clean-label positioning for bakery clients. Leiber GmbH competes through yeast-based flavor enhancers that reduce sodium without bitter aftertaste.
Sodium reduction ingredients comprise mineral salts, yeast extracts, and plant-derived compounds formulated to replicate sodium chloride's functional properties in food matrices while delivering substantially lower sodium content per serving. Potassium chloride dominates volume due to its direct ionic substitution capability and established GRAS status, though magnesium sulfate and calcium chloride segments are gaining traction in dairy alternative formulations where solubility and taste neutrality prove critical. Application demand in meat substitutes outpaces processed foods growth as German consumers prioritize plant-based proteins requiring sodium-mimetic texture and flavor solutions. Direct sales channels control the premium segment, while wholesale distributors occupy mid-tier volume flows for regional manufacturers.
Germany's Federal Ministry of Food and Agriculture enforces the National Reduction and Innovation Strategy, compelling manufacturers to meet phased sodium targets across processed food categories. BSI standards for food-grade mineral salts and EU Regulation 1169/2011 nutritional labeling requirements shape product development timelines and reformulation investments. Stakeholders must monitor evolving sodium threshold commitments under the EU Farm to Fork Strategy and assess mineral salt supplier qualification gaps before compliance deadlines tighten.
Market Dynamics
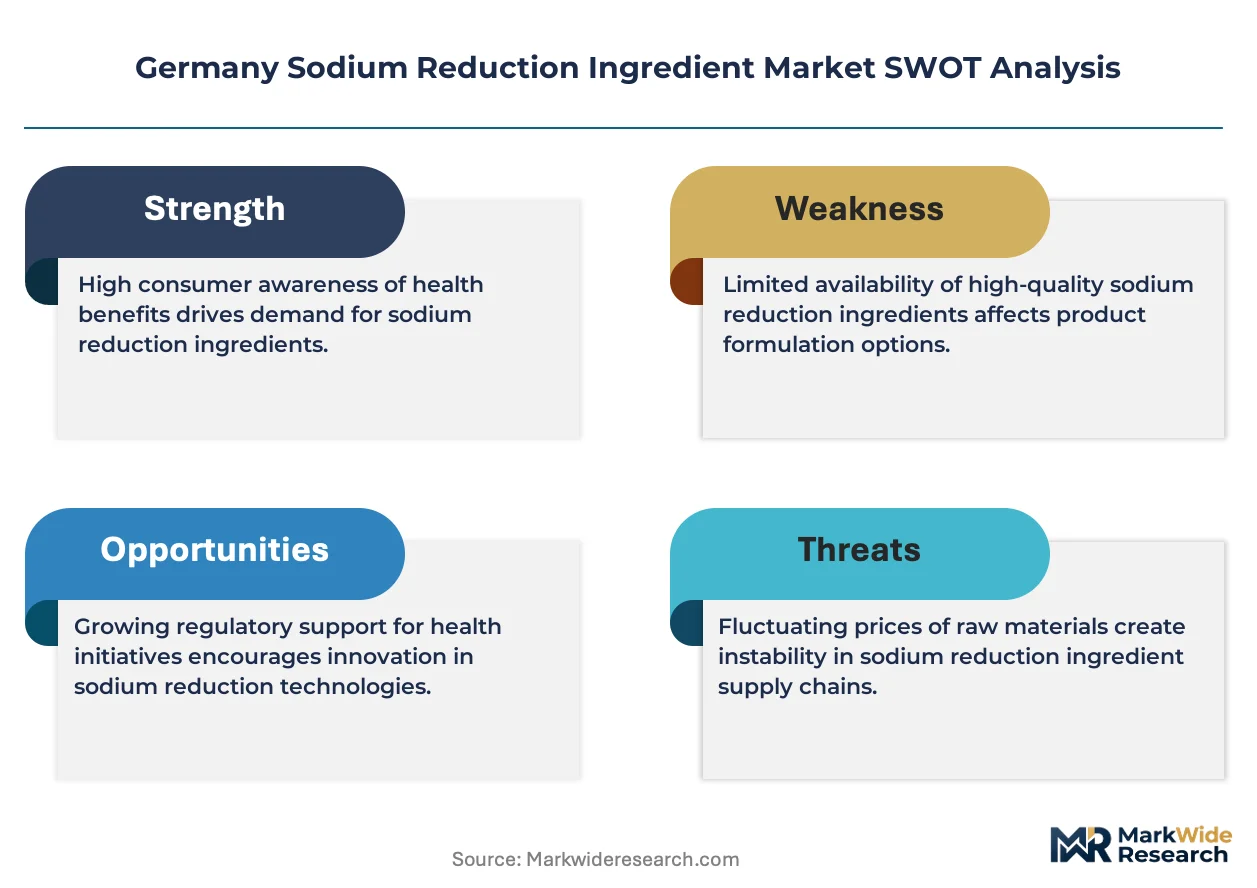
Germany's National Reduction and Innovation Strategy for sugars, fats, and salt is forcing accelerated reformulation timelines across processed food categories. Bavarian and North Rhine-Westphalian manufacturers now face binding sodium thresholds that compress product development cycles and intensify supplier qualification demands.
Growth Catalysts
- EU Farm to Fork Strategy:Phased sodium reduction mandates create sustained procurement pull from meat substitute and bakery manufacturers seeking compliant mineral salt systems.
- Meat Substitute Expansion:Plant-based protein formulators in Berlin and Hamburg require sodium-mimetic texture solutions that potassium chloride and yeast extract blends deliver.
- Clean-Label Positioning:Consumer preference for ingredient transparency drives adoption of mineral salt complexes over conventional sodium chloride in premium packaged foods.
Market Restraints
- Potassium Chloride Supply Concentration:Dependence on limited domestic mineral processing capacity creates input volatility for regional formulators.
- Bitter Aftertaste Technical Barrier:High-concentration potassium chloride applications face sensory rejection without integrated flavor masking systems.
- EU Regulation 1169/2011 Compliance Friction:Nutritional labeling recalculation requirements extend reformulation timelines and elevate regulatory consulting costs.
Strategic Opportunities
- Dairy Alternative Formulations:Magnesium sulfate and calcium chloride blends address solubility gaps in oat and almond milk applications where taste neutrality commands premium positioning.
- Direct Sales Channel Expansion:Premium segment manufacturers bypass wholesale distributors to capture margin through technical service partnerships with ingredient suppliers.
- Bundled Mineral Complex Innovation:Pre-blended systems integrating potassium chloride, yeast extracts, and natural flavor enhancers reduce customer formulation burden and lock in supplier relationships.
Industry Challenges
- Sensory Scientist Talent Scarcity:Shortage of professionals skilled in salt taste receptor mapping and bitter blocking formulation slows product iteration cycles.
- BSI Certification Timeline Compression:Food-grade mineral salt qualification protocols create bottlenecks as multiple manufacturers simultaneously pursue reformulation approvals.
- Legacy Equipment Integration:Existing processing lines designed for sodium chloride require retrofitting to handle hygroscopic potassium chloride without caking or flow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Sodium Reduction Ingredient Market |
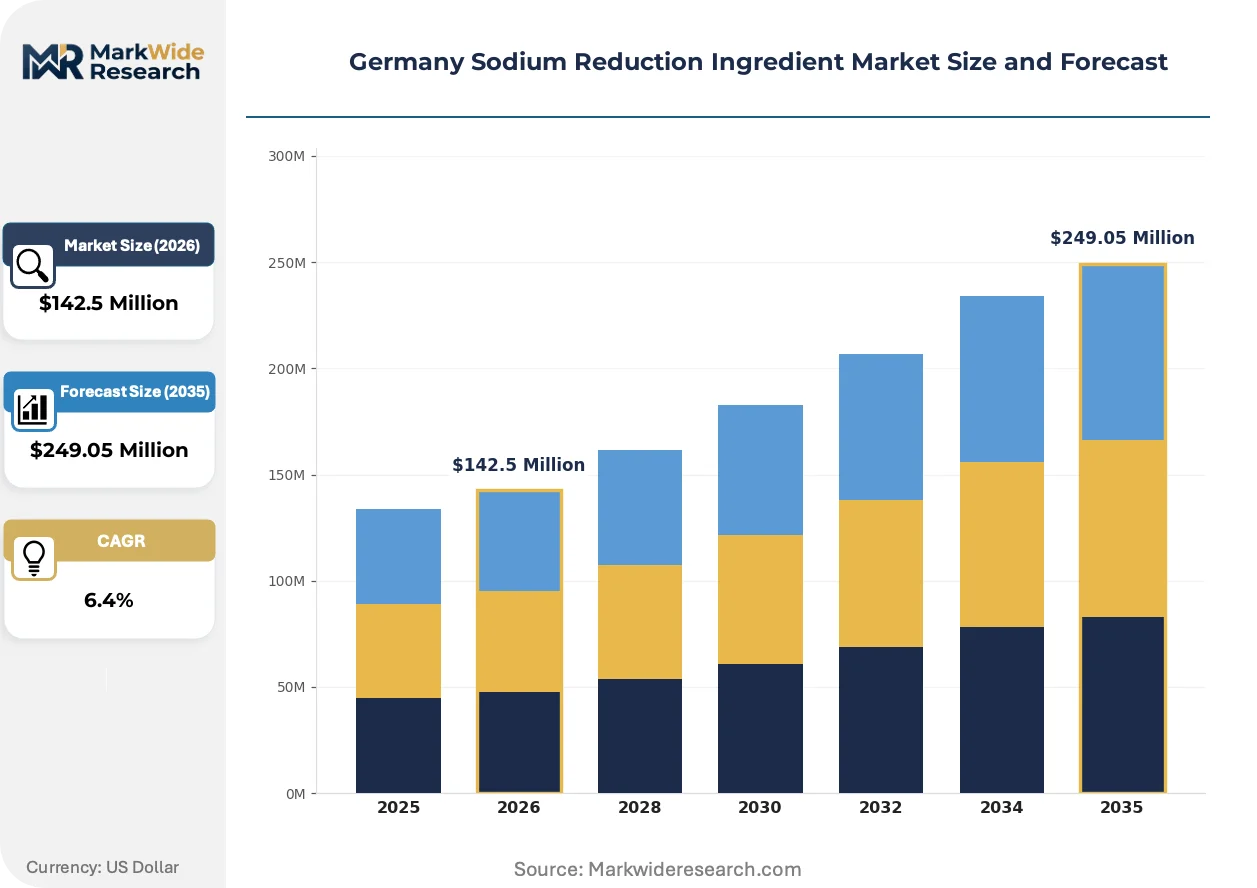
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Chloride, Calcium Chloride, Magnesium Sulfate, Sea Salt Extracts Application: Processed Foods, Dairy Alternatives, Meat Substitutes, Bakery Products End User: Food & Beverage Manufacturers, Contract Packers, Nutraceutical Companies, Functional Food Producers Distribution Channel: Direct Sales, Online Platforms, Wholesale Distributors, Specialty Ingredient Suppliers |
| Companies Covered | Cargill Incorporated, Corbion NV, Tate & Lyle PLC, Leiber GmbH, LALLEMAND Inc., K+S Minerals and Agriculture GmbH, DEUSA International GmbH, Dr. Paul Lohmann GmbH & Co. KG, Jungbunzlauer Suisse AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Sodium Reduction Ingredient Market Shifts & Advancements
Modular ingredient bundling is restructuring how German food manufacturers procure sodium reduction systems. Pre-blended mineral complexes with integrated flavor masking are displacing single-chemical substitution approaches across meat, bakery, and dairy alternative applications.
Yeast-based flavor enhancers are electrifying clean-label sodium reduction strategies in processed meat applications. Leiber GmbH and specialized suppliers deploy autolyzed yeast extracts that amplify umami perception without bitter potassium chloride aftertaste. Bavarian sausage manufacturers adopt these systems at accelerated pace to meet National Reduction and Innovation Strategy thresholds. This technology is electrifying competitive differentiation as technical service capabilities separate premium suppliers from commodity mineral salt distributors.
Germany's Federal Ministry of Food and Agriculture enforces phased sodium targets that tighten through 2035. The National Reduction and Innovation Strategy compels manufacturers to submit reformulation roadmaps with binding intermediate milestones. Processed meat and ready meal segments face the steepest compliance curves, driving concentrated investment in mineral salt supplier partnerships and sensory testing infrastructure.
Ingredient procurement is consolidating around technical partnership models rather than transactional mineral salt purchasing. Mid-tier regional manufacturers in North Rhine-Westphalia now demand bundled formulation support including sensory validation and label claim verification. Direct sales channels capture this preference shift, displacing traditional wholesale distributor relationships where technical service remains limited.
Germany Sodium Reduction Ingredient Market Segmentation
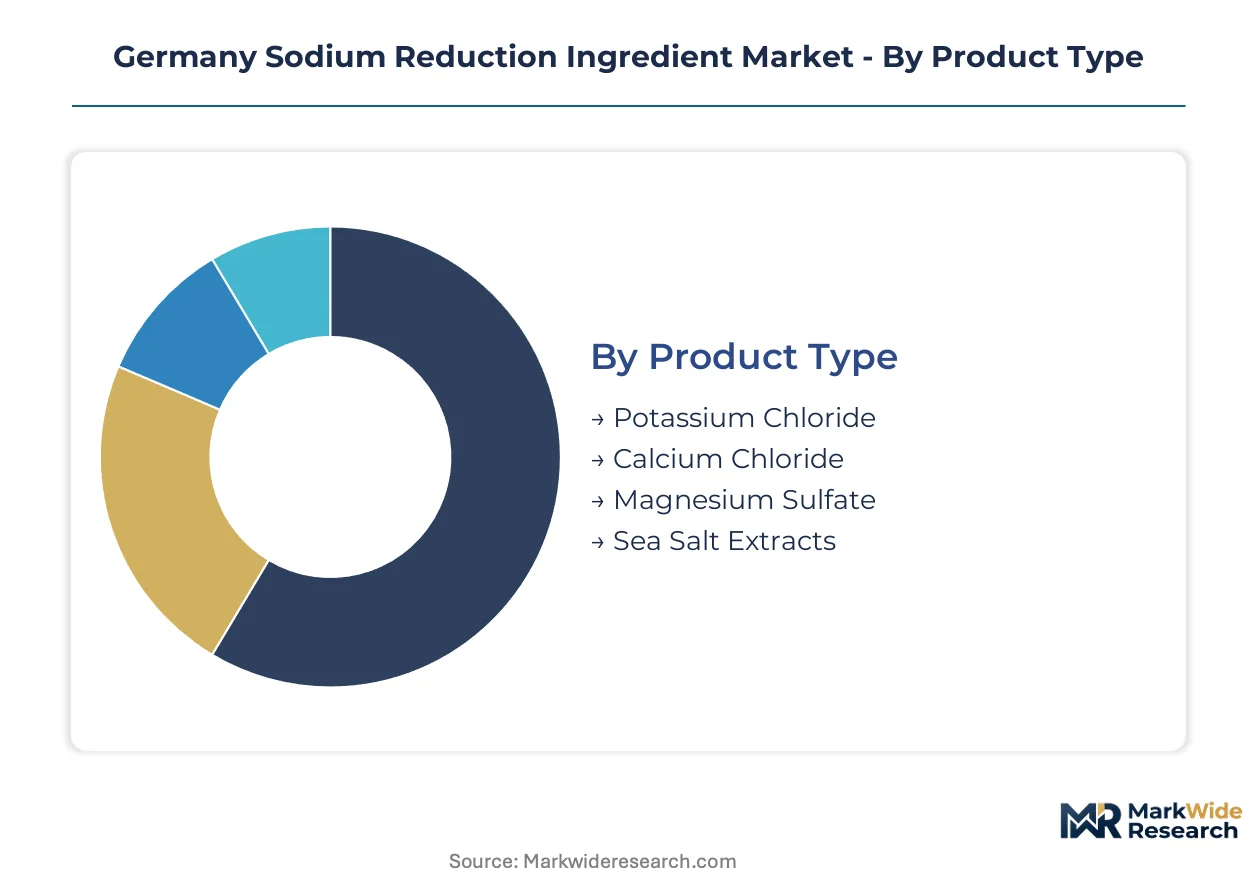
German food manufacturers select sodium reduction ingredients based on functional requirements, regulatory compliance timelines, and clean-label positioning. Segmentation reveals how procurement priorities diverge across reformulation complexity tiers and end-use categories.
Product Type:
Cost tier separates commodity mineral salts from premium extract-based systems requiring advanced flavor masking.
- Potassium Chloride:Ionic sodium substitute with established GRAS status delivers direct chloride replacement in processed meat matrices. Bavarian sausage manufacturers anchor procurement volumes here, though bitter aftertaste constraints limit standalone concentration thresholds.
- Sea Salt Extracts:Brine-derived mineral complexes with natural potassium-magnesium profiles enable clean-label claims without artificial additive classification. North Rhine-Westphalian premium bakery formulators drive adoption where ingredient transparency commands shelf price premiums.
- Calcium Chloride:Hygroscopic salt with texture-modifying properties serves dairy alternative applications requiring solubility control in oat and almond milk systems.
- Magnesium Sulfate:Bitter-neutral mineral additive addresses taste-critical formulations where potassium chloride sensory rejection risks commercial failure.
Potassium Chloride leads volumes today; Sea Salt Extracts is gaining share fastest.
Application:
Reformulation urgency varies by category exposure to Germany's National Reduction and Innovation Strategy binding thresholds.
- Meat Substitutes:Plant-based protein matrices demand sodium-mimetic texture systems combining mineral salts with yeast-derived flavor enhancers. Berlin and Hamburg formulators invest heavily in sensory validation infrastructure to meet compressed compliance timelines.
- Processed Foods:Ready meals and cured meat products face the steepest sodium reduction curves under federal mandates, driving bundled mineral complex procurement from technical service-oriented suppliers.
- Dairy Alternatives:Oat and almond milk processors prioritize magnesium sulfate and calcium chloride blends where taste neutrality determines repeat purchase rates.
- Bakery Products:Sodium reduction in bread and pastry applications requires fermentation-process adjustments alongside mineral salt substitution, extending development cycles.
Processed Foods anchors current revenue; Meat Substitutes shows steepest expansion trajectory.
End User:
Volume scale and technical capability determine whether buyers self-formulate or demand supplier-integrated solutions.
- Food & Beverage Manufacturers:Large-scale processors in Bavaria and North Rhine-Westphalia maintain in-house R&D teams for iterative reformulation, purchasing mineral salts in bulk tonnage.
- Contract Packers:Mid-tier co-manufacturers serving multiple brands require pre-blended sodium reduction systems to minimize line changeover complexity and regulatory documentation burden.
- Nutraceutical Companies:Health-positioned product developers prioritize sea salt extracts and magnesium-based systems for supplement and functional food applications.
- Functional Food Producers:Niche formulators targeting cardiovascular health claims invest in yeast extract flavor enhancers to maintain palatability at aggressive sodium reduction targets.
Food & Beverage Manufacturers dominate procurement volumes; Contract Packers are expanding most quickly.
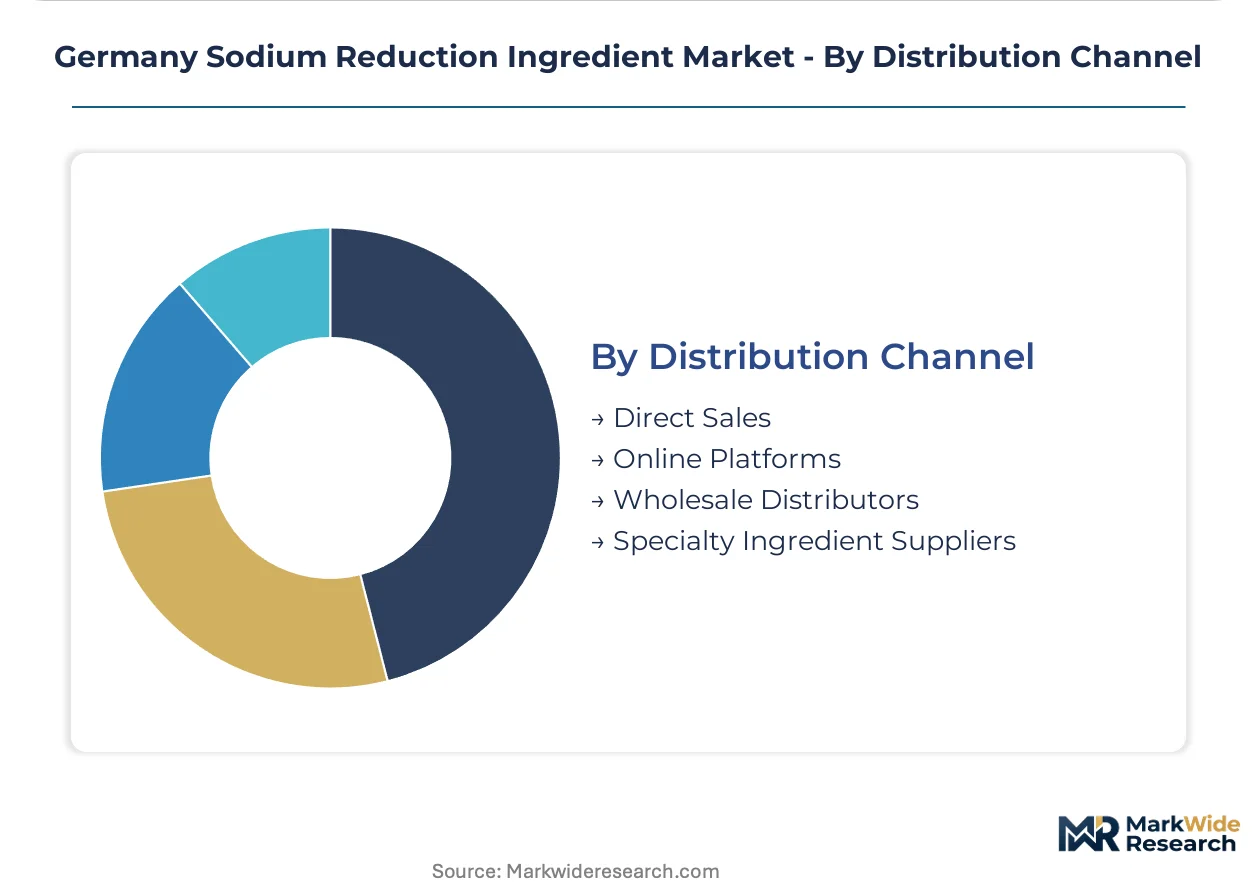
Distribution Channel:
Service intensity requirements separate premium direct relationships from transactional wholesale flows.
- Direct Sales:Technical partnership models deliver bundled formulation support, sensory validation, and label claim verification to large manufacturers bypassing distributor margins.
- Wholesale Distributors:Regional volume flows for mid-tier processors rely on standardized mineral salt specifications with limited customization or regulatory guidance.
- Specialty Ingredient Suppliers:Focused distributors of yeast extracts and sea salt derivatives serve clean-label formulators requiring application-specific technical consultation.
- Online Platforms:Emerging procurement channel for smaller functional food producers and nutraceutical startups seeking rapid sample access and minimum order quantity flexibility.
Wholesale Distributors handle largest tonnage today; Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's sodium reduction ingredient industry traces its commercial roots to post-war food processing clusters in Bavaria and the Rhineland, where meat curing traditions demanded precise salt control. Federal nutrition policy since the 2000s transformed regional reformulation expertise into a structured compliance industry serving domestic and adjacent European markets.
Bavaria
Munich and Nuremberg sausage manufacturers drive potassium chloride procurement volumes under the National Reduction and Innovation Strategy's processed meat thresholds. BSI certification protocols for food-grade mineral salts create supplier qualification bottlenecks as reformulation deadlines compress. Ingolstadt's technical service hubs now anchor bundled mineral complex distribution for southern German meat processors.
North Rhine-Westphalia
Düsseldorf and Cologne food conglomerates prioritize clean-label sea salt extracts for premium bakery positioning. The Federal Ministry of Food and Agriculture's phased sodium targets accelerate R&D investment in yeast-based flavor masking systems. Dortmund's contract packing corridor demands pre-blended sodium reduction systems to minimize line changeover complexity across multiple brand portfolios.
Baden-Württemberg
Stuttgart's precision fermentation sector supplies autolyzed yeast extracts for meat substitute umami enhancement. EU Regulation 1169/2011 nutritional labeling recalculations extend product development cycles for regional functional food startups. Karlsruhe's ingredient technology parks concentrate sensory scientist talent pools for bitter-blocking formulation.
Berlin-Brandenburg
Plant-based protein formulators in Berlin and Potsdam require sodium-mimetic texture solutions combining mineral salts with yeast derivatives. The EU Farm to Fork Strategy's sodium reduction mandates drive venture capital into alternative protein infrastructure. Adlershof's food tech cluster incubates magnesium sulfate applications for dairy alternative taste neutrality.
Hamburg
Port logistics and maritime food processing heritage position Hamburg as a distribution node for imported potassium chloride and specialty mineral salts. Wholesale distributors serving northern German mid-tier manufacturers concentrate inventory here to bypass direct sales channel premiums. The city's trading houses increasingly bundle regulatory documentation services with bulk mineral salt shipments.
Germany Sodium Reduction Ingredient Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with broad mineral salt portfolios and technical service capabilities. Tiered supplier segmentation separates premium bundled solution providers from commodity mineral salt distributors. Three archetypes dominate: integrated agribusiness conglomerates leveraging cross-category formulation expertise; specialized mineral salt processors with BSI-certified production assets; and yeast biotechnology firms deploying fermentation-derived flavor enhancers. Capacity expansion in potassium chloride processing and strategic partnerships for flavor masking technology licensing represent the dominant competitive moves.
Among diversified agribusiness conglomerates, Cargill Incorporated occupies a position exemplifying cross-category mineral salt bundling capabilities. Specialized mineral salt processors include K+S Minerals and Agriculture GmbH and Jungbunzlauer Suisse AG, representing the BSI-certified production archetype with established pharmaceutical and food-grade qualifications. Yeast biotechnology specialists such as Leiber GmbH anchor the fermentation-derived flavor enhancement segment, occupying positions where sensory science capabilities differentiate premium positioning from commodity mineral salt supply.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Corbion NV |
| Tate & Lyle PLC |
| Leiber GmbH |
| LALLEMAND Inc. |
| K+S Minerals and Agriculture GmbH |
| DEUSA International GmbH |
| Dr. Paul Lohmann GmbH & Co. KG |
| Jungbunzlauer Suisse AG |
| Others |
Supply & Pricing Matrix
Family-owned mineral salt processors across Saxony-Anhalt and Lower Saxony anchor supply-side ownership structures, translating generational technical expertise into pricing discipline that resists commodity erosion despite potassium chloride import dependency. Their entrenched BSI certification assets create switching costs that sustain margin capture even as wholesale distributors face compression from direct sales channel expansion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by technical service intensity and certification grade. Premium tiers bundle sensory validation and regulatory documentation with mineral salt complexes, while economy tiers transact commodity potassium chloride through wholesale distributors. Cost compression in mid-tier contract packing segments intensifies as reformulation deadlines compress procurement timelines. Large Bavarian meat processors exhibit lowest price sensitivity due to compliance penalty exposure; regional bakery co-manufacturers demonstrate highest sensitivity, prioritizing minimum order quantity flexibility over technical partnership depth.
Supply Chain Analysis
Germany's National Reduction and Innovation Strategy domestic-content preferences reshape sourcing patterns, favoring EU-sourced mineral salts over extra-EU imports despite cost premiums. Primary supply draws from domestic potash deposits in Lower Saxony, with secondary sourcing from Dutch and Belgian mineral processing hubs. Raw material dependencies center on potassium chloride ore, autolyzed yeast biomass, and magnesium sulfate brine extraction. Single-source vulnerability concentrates in specialty yeast extract supply from Stuttgart's precision fermentation cluster. Distribution runs through Ingolstadt technical service hubs for bundled mineral complexes, while Hamburg port logistics handle bulk potassium chloride flows to northern German processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's sodium reduction ingredient market represents a late-cycle quality story as meat substitute formulators shift procurement toward premium bundled mineral complexes with integrated flavor masking and regulatory documentation.
For Market Incumbents: Extend technical service capabilities into sensory validation and label claim verification to lock out wholesale distributor competition. Deepen backward integration into autolyzed yeast extract production to secure supply against Stuttgart fermentation cluster bottlenecks. Prioritize BSI certification timeline acceleration as multiple manufacturers simultaneously pursue reformulation approvals under compressed National Reduction and Innovation Strategy deadlines. For New Entrants and Emerging Players: Specialty ingredient suppliers with clean-label mineral salt expertise represent the most penetrable channel partner type for market entry. Target Berlin-Brandenburg plant-based protein startups requiring rapid sample access and flexible minimum order quantities for sodium-mimetic texture systems. Pursue white-label bundled formulation partnerships with North Rhine-Westphalian contract packers seeking to minimize line changeover complexity across multiple brand portfolios. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier mineral salt processors lacking bundled technical service capabilities but holding BSI-certified production assets. Long-term viability hinges on acquisition targets' capacity to pivot from commodity mineral salt distribution toward integrated formulation partnerships. Watch yeast biotechnology licensing deal velocity as the inflection signal indicating whether fermentation-derived flavor enhancement achieves cost parity with mineral salt substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Extract Production | Secures supply of autolyzed umami enhancers against Stuttgart fermentation cluster capacity constraints. |
| BSI Certification Acceleration Program | Compresses food-grade mineral salt qualification timelines ahead of National Reduction and Innovation Strategy deadlines. |
| Bundled Mineral Complex Launch | Integrates potassium chloride, magnesium sulfate, and flavor masking into pre-blended systems for meat substitute formulators. |
| Direct Sales Channel Expansion | Bypasses wholesale distributor margins to capture premium positioning with large Bavarian and North Rhine-Westphalian processors. |
| Sensory Science Talent Acquisition | Addresses bitter-blocking formulation expertise scarcity slowing product iteration cycles in high-concentration potassium chloride applications. |
Research Methodology
Coverage spans Germany's federal states with primary inputs from each, combining structured interviews with food technologists, procurement leads at meat substitute startups, sensory scientists, regulatory affairs specialists at ingredient suppliers, and wholesale distribution channel managers. Secondary validation draws from Federal Ministry of Food and Agriculture strategy documents, BSI food-grade mineral salt standards, EU Regulation 1169/2011 nutritional labeling frameworks, and customs trade data on potassium chloride imports. Bottom-up demand modeling triangulates against top-down market sizing across reformulation investment flows.
Granularity-level framing models volume and value at product type, application, end user, and distribution channel dimensions, with additional segmentation by federal state production cluster. Growth trajectories derive from reformulation timeline compression under binding sodium thresholds, meat substitute capacity expansion rates, and clean-label premium capture elasticity. Industry-specific forecast inputs include BSI certification queue depths and yeast extract fermentation capacity utilization across Stuttgart and Hamburg biotech infrastructure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Farm to Fork Strategy sodium mandate acceleration or delay, potassium chloride import tariff adjustments, and breakthroughs in non-mineral sodium-mimetic technologies. Forecasts reflect documented assumptions regarding regulatory timeline adherence and sensory scientist labor market expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Binder Excipients Market
Additives
Americas Coating Additives Market
Additives
Phthalate Plasticizer Market
Additives
Fluoropolymer Additives Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Lead Stearate Market
Additives
Marine Fuel Additives Market
Additives
Europe Anti-Caking Market
Additives
Europe UV Stabilizers Market
Additives
United States Citric Acid Market
Additives
Global Synthetic Tackifier Market
Additives
Flux Injection System Market
Additives
Global Acidulants Market
Additives
Viscosity Index Improvers Market
Additives
Lubricant Additives Market
Additives
Calcium Tartrate Market