
 Humectants Market | 2026-2036
Humectants Market Size, Share, and Industry Trends Forecast 2026-2036
Humectants Market Intelligence
Formulation support and co-development services are repositioning the value proposition beyond simple ingredient sales. This shift favors large, diversified suppliers with deep application expertise. BASF SE leverages its broad chemical portfolio to offer integrated solutions. Cargill Incorporated sustains its market presence through extensive agricultural sourcing and processing capabilities, while Roquette Frères specializes in plant-based ingredients for clean-label products.
Humectants are hygroscopic substances that attract and hold water molecules from the surrounding environment. Their function relies on forming hydrogen bonds, which prevents moisture loss in a final product. Glycerin and sorbitol represent foundational, high-volume product types used across multiple industries. In contrast, hyaluronic acid commands premium pricing within high-performance cosmetic and pharmaceutical applications due to its superior moisture retention properties.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) define purity standards and usage levels. In parallel, China's National Medical Products Administration (NMPA) governs ingredients used in cosmetics and pharmaceuticals, impacting market access. Sourcing decisions between synthetic and plant-derived humectants will dictate future supply chain investments and cost structures.
Market Dynamics
The central dynamic in the humectants market is the tension between the food and personal care industries' demand for natural, plant-derived ingredients and the persistent cost-efficiency of traditional synthetic humectants, forcing suppliers to manage dual supply chains.
Growth Catalysts
- Processed Food Expansion:Demand for shelf-stable products in the food and beverage sector, particularly in Southeast Asian and Latin American markets, drives volume consumption of foundational humectants like sorbitol and glycerin to manage moisture and extend product life.
- Clean-Label Cosmetics:The consumer-driven clean-beauty movement in Europe and North America fuels demand for plant-based and fermentation-derived humectants, such as vegetable glycerin and hyaluronic acid, in skincare and haircare formulations.
- Pharmaceutical Excipient Use:Growth in oral solid dosage forms and topical drug delivery systems increases the need for high-purity, pharmacopeia-grade humectants to ensure stability, palatability, and active ingredient integrity in medications.
Market Restraints
- Raw Material Volatility:Prices for agricultural feedstocks, such as corn for sorbitol and vegetable oils for glycerin, are subject to significant fluctuations, creating margin pressure and unpredictable input costs for humectant producers.
- Regulatory Scrutiny:Stringent purity standards and maximum usage levels imposed by the US FDA and the European Food Safety Authority (EFSA) create high compliance costs and lengthen development timelines for new humectant ingredients.
- Substitution from Multifunctionals:Formulators are increasingly using ingredients that offer multiple benefits, such as hydrocolloids that also provide humectancy, which can reduce the required volume of dedicated humectants in a final product.
Strategic Opportunities
- Animal Feed Applications:The use of humectants in animal nutrition to improve the palatability, texture, and shelf life of pet foods and livestock feed represents a significant, underpenetrated application area for suppliers.
- Bio-fermented Humectants:Developing novel humectants like ectoine through bio-fermentation processes offers a pathway to high-margin, premium products for the high-performance cosmetic sector, moving beyond commodity glycols and polyols.
- Controlled-Release Systems:Integrating humectants with encapsulation technology allows for the creation of advanced moisture-release systems, providing functional benefits in activewear textiles, advanced wound care, and specialty food products.
Industry Challenges
- Supply Chain Traceability:Ensuring consistent quality and full traceability for natural humectants sourced from geographically diverse agricultural origins is a major operational challenge, especially for food-grade and pharmaceutical-grade materials.
- Certification Management:The need to secure and maintain multiple certifications, including Non-GMO, Halal, and Kosher, for a single product to serve global customers adds significant administrative complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humectants Market |
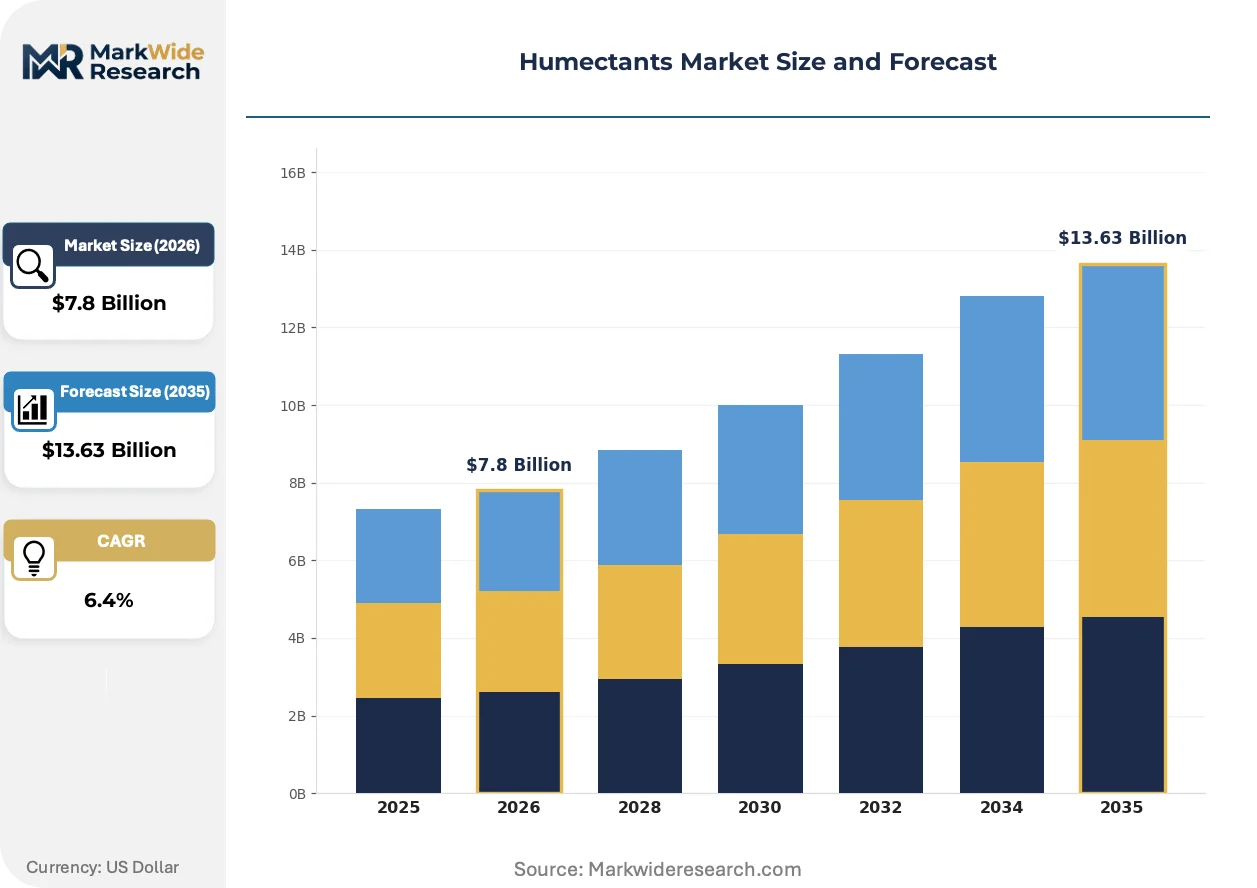
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerin, Sorbitol, Hyaluronic Acid, Propylene Glycol Application: Cosmetics, Food & Beverage, Pharmaceuticals, Personal Care Functionality: Moisture Retention, Texturizing Agent, Baking Enhancer, Stabilizing Agent End User: Manufacturers, Retailers, Consumers, Distributors |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill Incorporated, DuPont de Nemours, Ashland Global Holdings Inc., Roquette Frères, Ingredion Incorporated, Brenntag AG, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humectants Market Strategic Shifts & Innovations
Innovation is centered on developing multifunctional humectants that provide benefits beyond simple hydration, such as skin barrier protection or improved textural properties in foods. The industry is also seeing a pronounced shift toward sustainable production methods, including bio-fermentation and the use of agricultural side-streams as feedstocks.
Bio-fermentation enables the production of high-purity, nature-identical humectants like hyaluronic acid and ectoine. High-end cosmetic and dermo-cosmetic brands are the primary adopters, seeking ingredients with proven efficacy claims and strong clean-label credentials. This move toward precision-fermented ingredients is rewriting the performance benchmarks for premium skincare, shifting focus from basic moisturization to active biological benefits like skin barrier repair.
China's National Medical Products Administration (NMPA) has implemented stricter data requirements for cosmetic ingredient registration under its CSAR framework. This policy compels ingredient suppliers to provide comprehensive safety and efficacy dossiers, increasing the cost and time-to-market for new humectants. The personal care segment is most affected, with formulators now prioritizing humectants that already possess a robust, NMPA-compliant data package to streamline product launches in China.
A clear shift in sourcing criteria now favors humectants with a documented low environmental impact, such as those derived from upcycled agricultural materials or certified sustainable feedstocks. This change disrupts traditional procurement models that were based primarily on price and technical specifications, creating an advantage for suppliers with transparent and certified supply chains. This behavior is most visible among multinational consumer goods companies in North America and Europe, responding to internal ESG targets and consumer demand for sustainable products.
Humectants Market Segmentation
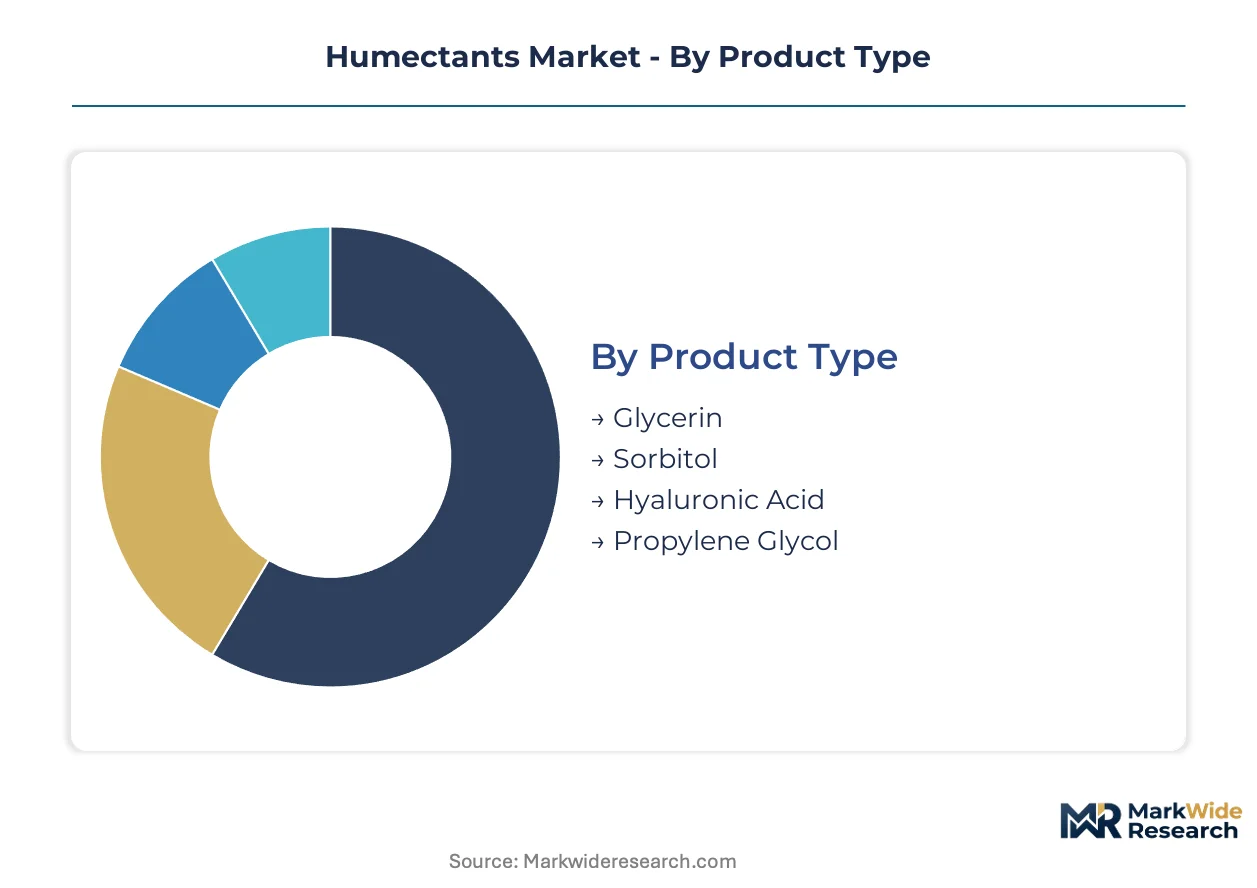
The humectants market segmentation provides a granular view of product types, applications, functionalities, and end-user dynamics. This detailed breakdown illuminates how diverse industry needs shape demand patterns and influence strategic investment decisions for suppliers. Understanding these distinct segments is crucial for identifying specific growth pockets.
Product Type:
The product type segmentation highlights the spectrum from widely standardized commodity humectants to highly specialized, custom-formulated ingredients.
- Glycerin:This polyol is a foundational humectant derived from vegetable oils or petroleum, known for its high water-attracting capability and versatility. Demand concentrates in the food and beverage industry, driven by its cost-effectiveness and ability to extend shelf life in processed foods.
- Hyaluronic Acid:A premium polysaccharide, hyaluronic acid excels in moisture retention and skin barrier repair, often produced via bio-fermentation for high purity. Its demand is strongest in high-performance cosmetic and pharmaceutical applications, where superior efficacy justifies higher pricing.
- Sorbitol:A sugar alcohol, sorbitol is widely used as a bulk sweetener and humectant, particularly in confectionery and oral care products.
- Propylene Glycol:This synthetic organic compound serves as a solvent, humectant, and preservative across personal care and pharmaceutical formulations.
Leading the category by volume: Glycerin. Growing fastest: Hyaluronic Acid.
Application:
The application landscape reflects varying requirements for purity, regulatory compliance, and functional performance across different industrial sectors.
- Food & Beverage:This segment utilizes humectants to control moisture, prevent drying, and enhance texture in baked goods, confectionery, and processed meats. Demand is particularly strong in emerging markets seeking shelf-stable food products, driven by urbanization and changing dietary habits.
- Cosmetics:Formulators employ humectants for skin hydration, texture improvement, and active ingredient delivery in skincare, haircare, and makeup products. The clean-beauty movement in Europe and North America fuels demand for natural and bio-fermented humectants in this sector.
- Pharmaceuticals:Humectants serve as excipients in drug formulations, ensuring stability, palatability, and moisture control in oral and topical medications.
- Personal Care:This broad category includes products like soaps, lotions, and deodorants, where humectants provide moisturizing and conditioning benefits.
The Food & Beverage segment commands the largest share, while Cosmetics exhibits significant expansion due to consumer preference for advanced skincare.
Functionality:
The functionality segmentation delineates the primary benefits humectants deliver, from basic hydration to complex textural and stabilizing roles in final products.
- Moisture Retention:This core function involves attracting and holding water molecules, preventing product desiccation and maintaining desired hydration levels. This functionality is critical across cosmetics and food products, where product integrity and sensory attributes depend on stable moisture content.
- Texturizing Agent:Humectants contribute to the desired mouthfeel, viscosity, and spreadability of various products, particularly in food and personal care formulations. In bakery and confectionery, this role is crucial for achieving specific product characteristics and consumer acceptance.
- Baking Enhancer:Humectants improve crumb structure, extend freshness, and prevent staling in baked goods by managing water activity.
- Stabilizing Agent:These substances help maintain the physical and chemical stability of emulsions and suspensions, preventing phase separation in various formulations.
Moisture Retention remains the most sought-after functionality, with Texturizing Agent applications showing robust growth in specialized food products.
End User:
The end-user segmentation illustrates how different stakeholders engage with humectant products, from large-scale industrial procurement to direct consumer interaction.
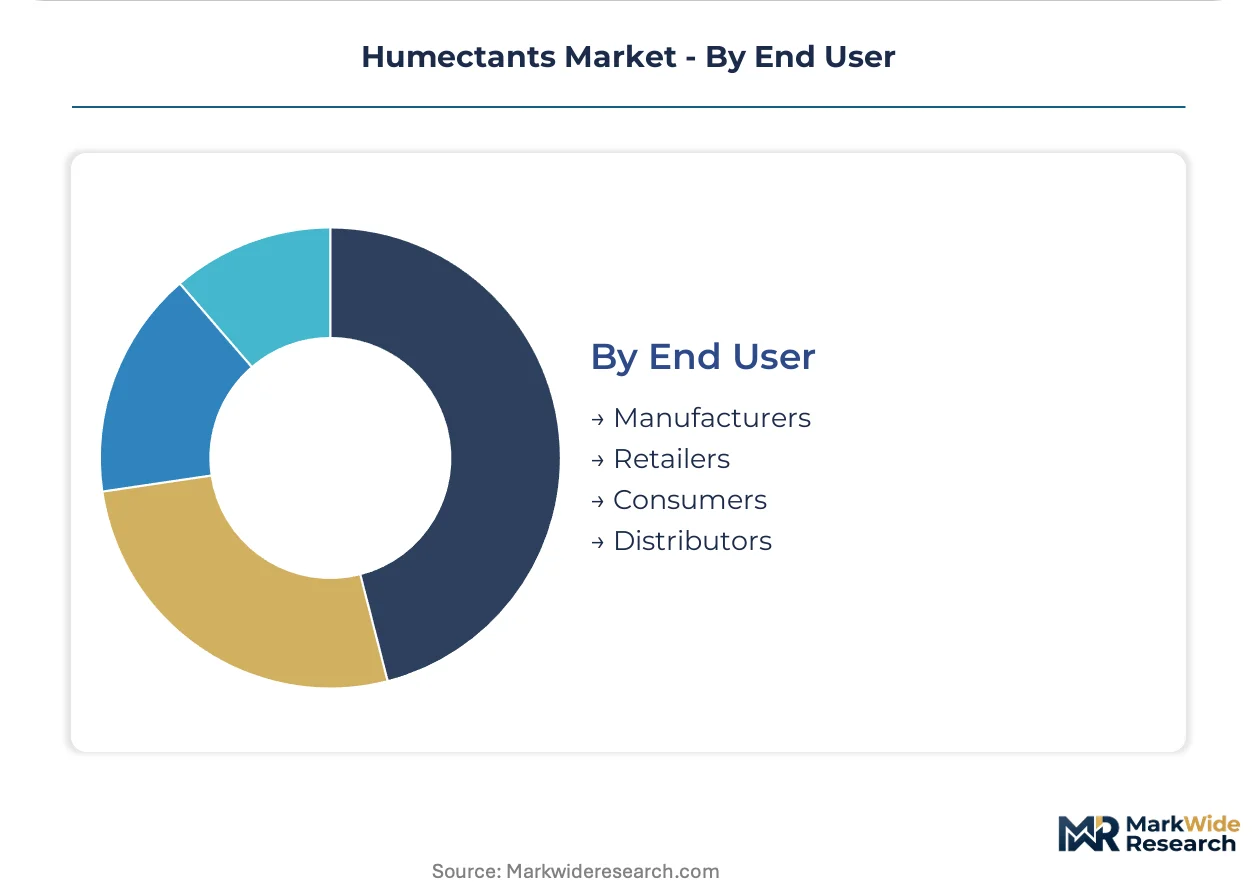
- Manufacturers:Industrial manufacturers, including food processors, cosmetic companies, and pharmaceutical firms, procure humectants as raw materials for their product formulations. Procurement decisions are heavily influenced by regulatory compliance, cost-efficiency, and the need for specific technical specifications.
- Consumers:Consumers indirectly drive demand through their purchase of finished products containing humectants, particularly in personal care and packaged food sectors. Growing consumer awareness of ingredient benefits, such as hydration in skincare, directly influences manufacturer formulation choices.
- Retailers:Retailers distribute finished products containing humectants, acting as a crucial link between manufacturers and the end consumer.
- Distributors:These entities manage the supply chain, facilitating the flow of humectant raw materials from producers to various manufacturing clients globally.
Manufacturers represent the largest direct purchasing segment, while Consumers exert significant influence on product innovation and ingredient selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The humectants market exhibits a significant production-consumption imbalance, with manufacturing capacities often concentrated in specific regions while demand drivers are globally dispersed. China anchors a substantial portion of global production, while consumer-driven segments in Europe and North America represent high-value consumption hubs.
China
Demand for humectants in China is driven by its large-scale processed food and personal care manufacturing industries. China's National Medical Products Administration (NMPA) governs ingredient registration, influencing market access for cosmetic humectants. Major industrial clusters in the Yangtze River Delta actively integrate humectants into diverse product formulations for both domestic and export markets.
United States
The United States market is characterized by strong demand from the food & beverage and pharmaceutical sectors for shelf-life extension and excipient functions. The US Food and Drug Administration (FDA) sets purity standards and usage levels for humectants in regulated products. Innovation centers in California and the Northeast corridor focus on developing high-performance humectants for advanced cosmetic and medical applications.
Germany
Germany's humectants market benefits from a robust chemical industry and a strong focus on high-purity ingredients for pharmaceuticals and clean-label cosmetics. The European Food Safety Authority (EFSA) and REACH regulations significantly impact product development and market entry. Chemical manufacturing hubs in North Rhine-Westphalia are key producers and innovators for specialized humectant types.
India
India represents a high-growth market for humectants, propelled by its expanding food processing industry and a rapidly urbanizing population. The Food Safety and Standards Authority of India (FSSAI) regulates food additives, including humectants, ensuring compliance and consumer safety. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat are major consumers of pharmacopeia-grade humectants.
Brazil
In Brazil, the humectants market is primarily influenced by the agricultural and food industries, with a rising demand for processed foods and personal care products. ANVISA, Brazil's health surveillance agency, regulates cosmetic and food ingredients, impacting product formulations. Industrial zones around São Paulo drive significant consumption of humectants in confectionery and personal care manufacturing.
Humectants Market Key Industry Players
Top-tier vendors anchor the humectants market with broad portfolios and integrated supply chains, while specialized manufacturers focus on niche applications or specific ingredient types. The market structure favors diversified chemical and agricultural processing giants, alongside innovative biotechnology firms. Key strategic archetypes include large-scale commodity producers, specialty ingredient innovators, and regional distributors. Capacity expansion and portfolio diversification represent dominant competitive moves.
Within the large-scale commodity tier, BASF SE leverages its broad chemical portfolio to offer integrated solutions across multiple industries. Cargill Incorporated sustains its market presence through extensive agricultural sourcing and processing capabilities, particularly for glycerin and sorbitol. Roquette Frères exemplifies a specialist in plant-based ingredients, focusing on clean-label products and bio-fermented options for premium segments.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| DuPont de Nemours |
| Ashland Global Holdings Inc. |
| Roquette Frères |
| Ingredion Incorporated |
| Brenntag AG |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Fluctuations in vegetable oil prices, a key feedstock for glycerin, directly influence humectant pricing across different tiers. This volatility cascades through the supply chain, impacting both commodity and specialty ingredient costs.
Pricing Analysis
Cost-down pressure on commodity humectants accelerates due to raw material volatility and intense competition among large-scale producers. The dominant pricing model for high-volume humectants involves contract-based long-term offtake agreements. Price differentiation stems from quality grade, such as pharmacopeia-grade purity, and specific certifications like Halal or Kosher. Food and beverage manufacturers exhibit the highest price sensitivity, unlike high-performance cosmetic and pharmaceutical formulators.
Supply Chain Analysis
Regional distribution centers play a crucial role in managing the flow of humectants from concentrated production hubs to diverse end-user markets. Supply concentrates heavily in China, the United States, and Germany, drawing from raw materials like corn starch and vegetable oils. Commodity price volatility represents a significant structural risk, impacting cost structures for producers globally. Distribution typically runs through specialized entities facilitating raw material delivery to manufacturing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The humectants market is increasingly defined by a cost-of-compliance narrative, where stringent regulatory frameworks like China's NMPA act as significant market entry barriers. This creates a moat for established players with robust compliance capabilities.
For Market Incumbents: Deploy R&D investments into bio-fermentation processes to counter substitution from multifunctional ingredients and secure premium positioning. Incumbents should also pursue backward integration into key agricultural feedstocks to mitigate raw material volatility. Maintaining multiple certifications like Halal and Kosher reinforces market access against emerging regional players. Deep application expertise in co-development services further cements customer relationships.
For New Entrants and Emerging Players: Specialized distributors offer new entrants a critical pathway to market access, especially in fragmented end-user segments. Target underpenetrated application areas like animal feed and advanced controlled-release systems for early market traction. Focus on niche high-performance cosmetic segments with novel bio-fermented humectants, leveraging efficacy-driven claims for differentiation. Emphasize sustainable sourcing credentials to appeal to multinational consumer goods companies.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty ingredient innovators in Europe and North America, particularly those with patented bio-fermentation technologies. The long-term viability of humectants is assured by stable demand across food, personal care, and pharmaceutical sectors. Target mid-sized manufacturers possessing robust NMPA-compliant data packages for cosmetic ingredients. Watch for consolidation among plant-based feedstock suppliers as an inflection indicator for future input cost stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses growing demand for shelf-stable foods in emerging markets. |
| Backward Integration into Agricultural Feedstocks | Mitigates raw material price volatility for glycerin and sorbitol producers. |
| Investment in Bio-fermentation R&D | Develops high-purity, premium humectants like ectoine for cosmetics. |
| Secure Long-term Supply Agreements with Key Buyers | Provides revenue stability and volume predictability for commodity humectant suppliers. |
| Joint Ventures for Regional Distribution Networks | Enhances market penetration and logistics efficiency in high-growth regions like India. |
Research Approach
EFSA reports, FDA filings, and NMPA guidelines formed the secondary backbone for this analysis, complemented by extensive customs and trade data. Primary interviews with R&D directors, procurement leads, and brand managers across food, personal care, and pharmaceutical sectors provided critical qualitative insights. Regulatory affairs specialists also contributed to understanding market access complexities. A rigorous bottom-up and top-down triangulation approach validated all quantitative and qualitative findings.
A bottom-up approach estimated volume outputs based on end-use application growth, while a top-down model validated value projections across the analysis window. Segmentation included product type, application, functionality, and end-user, alongside regional regulatory clusters. Compound annual growth rates were derived from historical growth trends, expert consensus, and projected demand shifts. Key forecast inputs included raw material price forecasts and clean-label ingredient adoption rates.
Caveats apply where geopolitical instability or unforeseen technological breakthroughs could materially shift the outlook for humectants. Forecasts reflect assumptions documented at the time of publication. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antimicrobial Additives Market
Additives
Potting Mix Additives Market
Additives
Chelating Agents Market
Additives
Bromine Derivatives Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Global Low-Profile Additive Market
Additives
Global PVC Additives Market
Additives
Gasoline Additives Market
Additives
Plastic Fillers Market
Additives
Agrochemicals Additives Market
Additives
Plastic Antioxidants Market
Additives
Rheological Additives Market
Additives
Calcium Diglutamate Market
Additives
LAMEA Driveline Additives Market
Additives
Sodium Citrate Anhydrous Market
Additives
Additives for Floor Coatings Market