
 Morpholine Market | 2026-2036
Morpholine Market Size, Share, and Industry Trends Forecast 2026-2036
Morpholine Market Outlook
ISO 14001 environmental management certification is unwinding competitive access for smaller producers lacking verified lifecycle documentation. BASF SE leverages integrated ethylene oxide supply chains to sustain cost leadership across European pharmaceutical-grade output. Huntsman Corporation anchors North American rubber-processing demand through dedicated morpholine-thiazole accelerator production. Sinochem Group Co. Ltd. dominates domestic Chinese distribution by controlling captive amine feedstock from coal-chemical complexes.
Morpholine is a saturated heterocyclic amine with the molecular formula C4H9NO, synthesized primarily through diethanolamine cyclodehydration or via the reaction of ethylene oxide with ammonia; it functions as a versatile intermediate, corrosion inhibitor, and solvent across industrial process streams. Industrial-grade morpholine leads volume consumption due to saturated gas-treatment applications in fossil-fuel power generation, while pharmaceutical-grade formulations command premium positioning amid tightening pharmacopeial purity thresholds. Rubber-processing applications are expanding fastest as tire manufacturers reformulate accelerator packages to meet evolving vulcanization performance standards.
EPA effluent guidelines constrain US morpholine discharge limits from pesticide formulation plants, compelling end users to adopt closed-loop recovery systems. ECHA REACH substance evaluation drives substitution testing for reproductive-toxicity classifications affecting European import volumes. China's MEE enforces stricter volatile organic compound emission caps on amine production facilities in the Yangtze River Economic Belt. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate product-registration investments and avoid stranded inventory in non-compliant markets.
Market Dynamics
Coal-fired power plant scrubber retrofits across China are absorbing industrial-grade morpholine volumes at rates that outstrip Western pharmaceutical demand growth, compressing regional price arbitrage windows and redirecting merchant supply flows toward East Asian utilities.
Growth Catalysts
- Scrubber corrosion inhibition:China's coal-plant desulfurization mandates under MEE directives require morpholine-based neutralizing amines for flue-gas treatment, sustaining bulk chemical offtake.
- REACH substitution testing:ECHA's reproductive-toxicity evaluations are disqualifying competitive amines, opening formulation slots for lower-classified morpholine derivatives in European rubber processing.
- Ethylene oxide integration:Captive diethanolamine feedstock from integrated petrochemical complexes is securing cost-advantaged cyclodehydration capacity for export-grade output.
Market Restraints
- Ethylene oxide feedstock volatility:Crude-linked ethylene pricing transmits directly to morpholine production economics, eroding margin predictability for non-integrated producers.
- Yangtze River emission caps:China's MEE volatile organic compound limits on amine facilities are idling smaller batch reactors without scrubber retrofit capital.
- MEA substitution in gas treatment:Monoethanolamine's lower molecular weight and established logistics are defending market share in lean-amine CO2 capture systems.
Strategic Opportunities
- Indian pharmaceutical excipient registration:CDSCO's harmonization with ICH Q3C residual solvent guidelines is creating first-mover advantage for pharmacopeial-grade morpholine suppliers.
- Rubber accelerator package reformulation:Tire manufacturers are substituting thiazole accelerators with morpholine-derived sulfenamides to meet lower-nitrosamine vulcanization standards.
- Closed-loop recovery systems:EPA effluent guidelines for pesticide formulation plants are mandating amine recovery infrastructure, creating aftermarket equipment and chemical-services bundling potential.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP monograph compliance for pharmaceutical-grade output requires 18-24 month stability documentation cycles that strain working capital.
- Legacy accelerator inventory displacement:Rubber compounders face technical-service costs and mixing-line revalidation when switching from CBS to morpholine-based sulfenamide accelerators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morpholine Market |
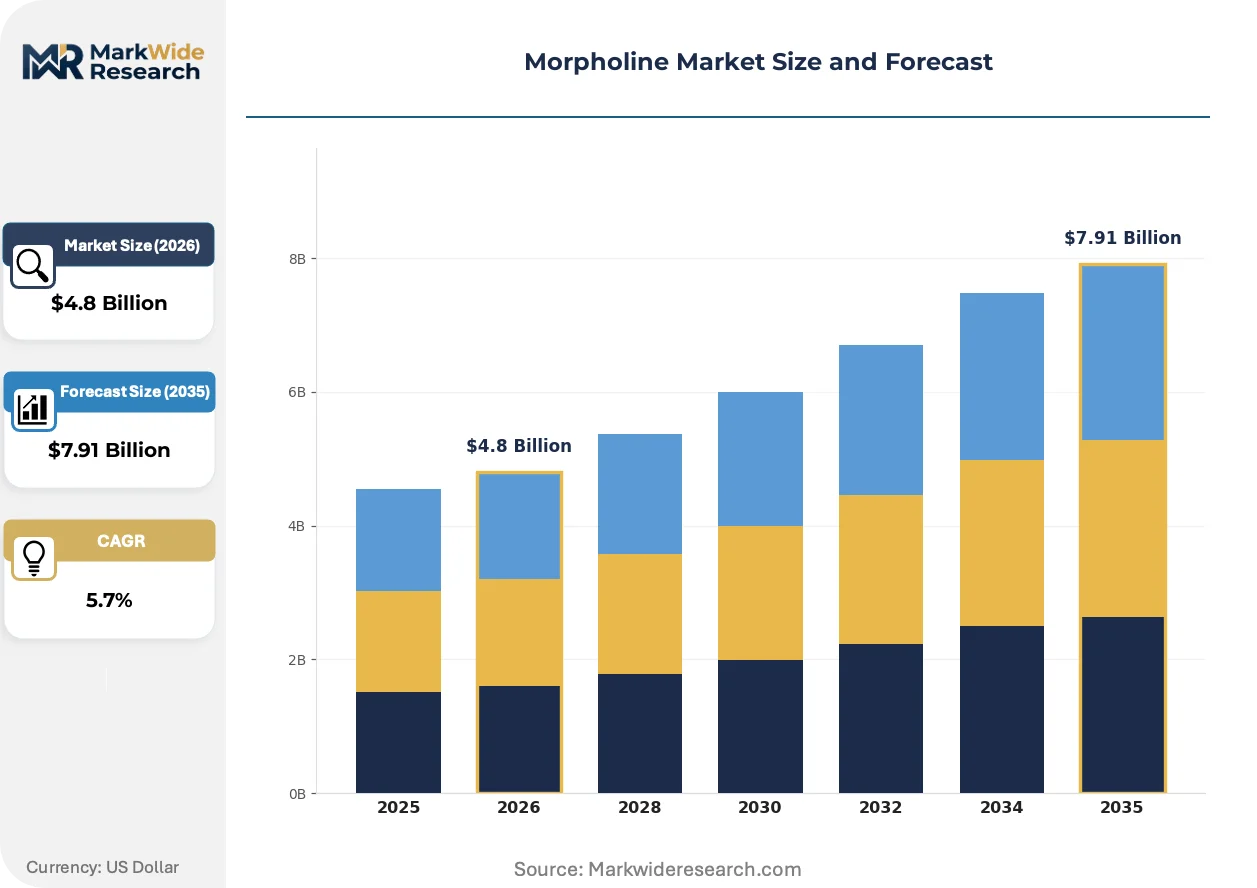
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Agrochemical Grade, Solvent Grade Application: Gas Treatment, Rubber Processing, Pesticide Production, Detergent Manufacturing End User: Pharmaceuticals, Agriculture, Textile, Construction Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | BASF SE, Huntsman Corporation, Nippon Nyukazai Co. Ltd., Sinochem Group Co. Ltd., Balaji Amines Ltd., Anhui Haoyuan Chemical Industry Group Co. Ltd., Nouryon Chemicals Holding B.V., APL (Amines And Plasticizers Ltd.), Zhengzhou Fuyuan Chemical Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morpholine Market Strategic Shifts
Process intensification and regulatory reclassification are fragmenting the morpholine value chain into distinct pharmaceutical and industrial supply tiers with incompatible specification, documentation, and pricing architectures.
Membrane-based amine recovery is bifurcating gas-treatment chemical economics. The technology strips morpholine from lean amine streams at 85-90 percent recovery rates versus thermal regeneration's 60-70 percent. US power utilities adopting membrane units are extending chemical inventory cycles from 45 to 90 days. This compression of replacement demand is forcing merchant suppliers toward toll-processing contracts with guaranteed offtake minimums.
REACH substance evaluation under ECHA's 2023-2025 work program is reclassifying morpholine derivatives for reproductive toxicity. The industrial consequence is mandatory substitution testing for rubber-accelerator formulators using N-oxydiethylene-2-benzothiazole sulfenamide. European tire manufacturers are accelerating qualification of alternative vulcanization chemistries, with compound development cycles compressing from 36 months to 18 months to meet 2026 formulation deadlines.
Specification-driven procurement is consolidating morpholine buying among ISO 14001-certified compounders. Tire manufacturers are unbundling chemical supply from mixing services, issuing direct purchase orders to verified lifecycle-documented suppliers. This channel disintermediation is most visible in Germany's Ruhr industrial cluster, where Continental and Michelin facilities have eliminated distributor markups on accelerator packages in favor of direct BASF and Lanxess contracts with quarterly carbon-intensity reporting.
Morpholine Market Segmentation
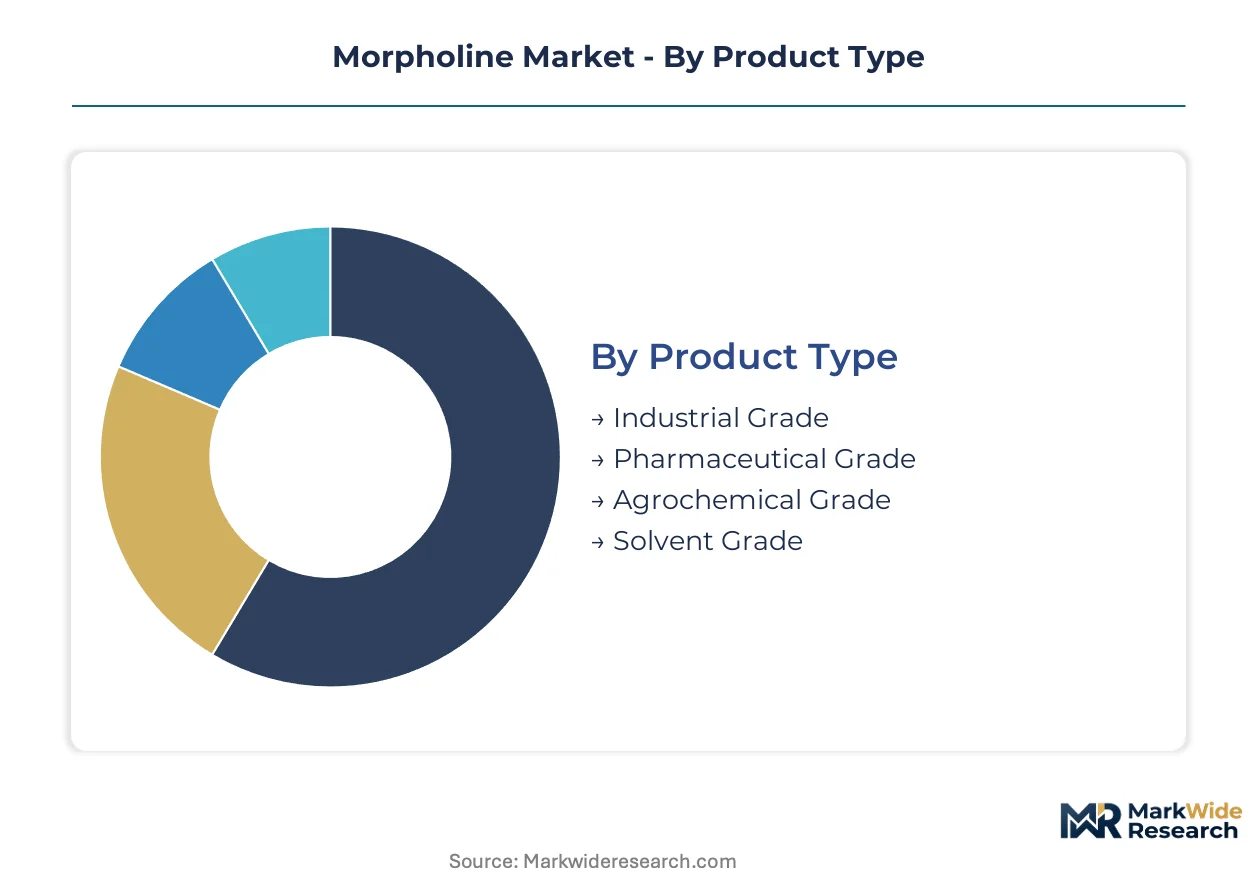
Morpholine's chemical versatility creates divergent value capture across purity grades and application chemistries. Specification thresholds separate commodity bulk supply from pharmacopeial-certified output with 3-5x margin multiples.
Product Type:
Margin pools concentrate in pharmaceutical-grade certification where USP and EP monograph compliance commands substantial premia over industrial specifications.
- Industrial Grade:Contains 99.0-99.5% morpholine with controlled water content for gas-treatment applications. Coal-fired power plant scrubber retrofits in China absorb volumes at rates compressing regional arbitrage windows and redirecting merchant supply flows toward East Asian utilities.
- Pharmaceutical Grade:Meets USP and EP monograph specifications with residual solvent documentation under ICH Q3C guidelines. CDSCO harmonization in India is creating first-mover advantage for suppliers with 18-24 month stability documentation cycles already completed.
- Agrochemical Grade:Balances purity against cost for pesticide formulation feedstock. EPA effluent guidelines constrain US discharge limits from formulation plants.
- Solvent Grade:Optimized for extraction and reaction media in fine chemical synthesis. Specifications vary by end-use solubility requirements.
Industrial grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
Application:
Volume concentration tracks fossil-fuel power generation infrastructure while formulation innovation shifts value toward rubber-processing chemistry.
- Gas Treatment:Neutralizing amine for flue-gas desulfurization and acid gas removal. MEE directives in China mandate scrubber upgrades sustaining bulk offtake from coal-plant operators.
- Rubber Processing:Sulfenamide accelerator precursor for tire vulcanization. ECHA reproductive-toxicity reclassifications are accelerating qualification cycles as compounders substitute away from competitive thiazole chemistries.
- Pesticide Production:Intermediate for fungicide and herbicide synthesis. Closed-loop recovery systems are becoming mandatory under EPA effluent guidelines.
- Detergent Manufacturing:pH adjuster and corrosion inhibitor in industrial cleaning formulations. Demand tracks institutional and commercial cleaning service procurement.
Gas treatment anchors volume throughput. Rubber processing is climbing the fastest as tire manufacturers reformulate accelerator packages.
End User:
Customer procurement maturity separates ISO 14001-certified compounders from spot-market buyers without lifecycle documentation capabilities.
- Pharmaceuticals:Excipient and synthesis solvent for active pharmaceutical ingredient manufacturing. Pharmacopeial certification timelines strain working capital for suppliers.
- Agriculture:Pesticide formulation and crop protection chemical synthesis. REACH compliance redirects formulation strategies toward lower-toxicity derivatives.
- Textile:Fiber conditioning agent and dye bath pH control. Demand tracks synthetic fiber production volumes.
- Construction:Concrete admixture and corrosion inhibitor for reinforced structures. Application penetration varies by regional building codes.
Pharmaceuticals concentrate value capture. Agriculture is expanding most quickly as crop protection chemical procurement intensifies.
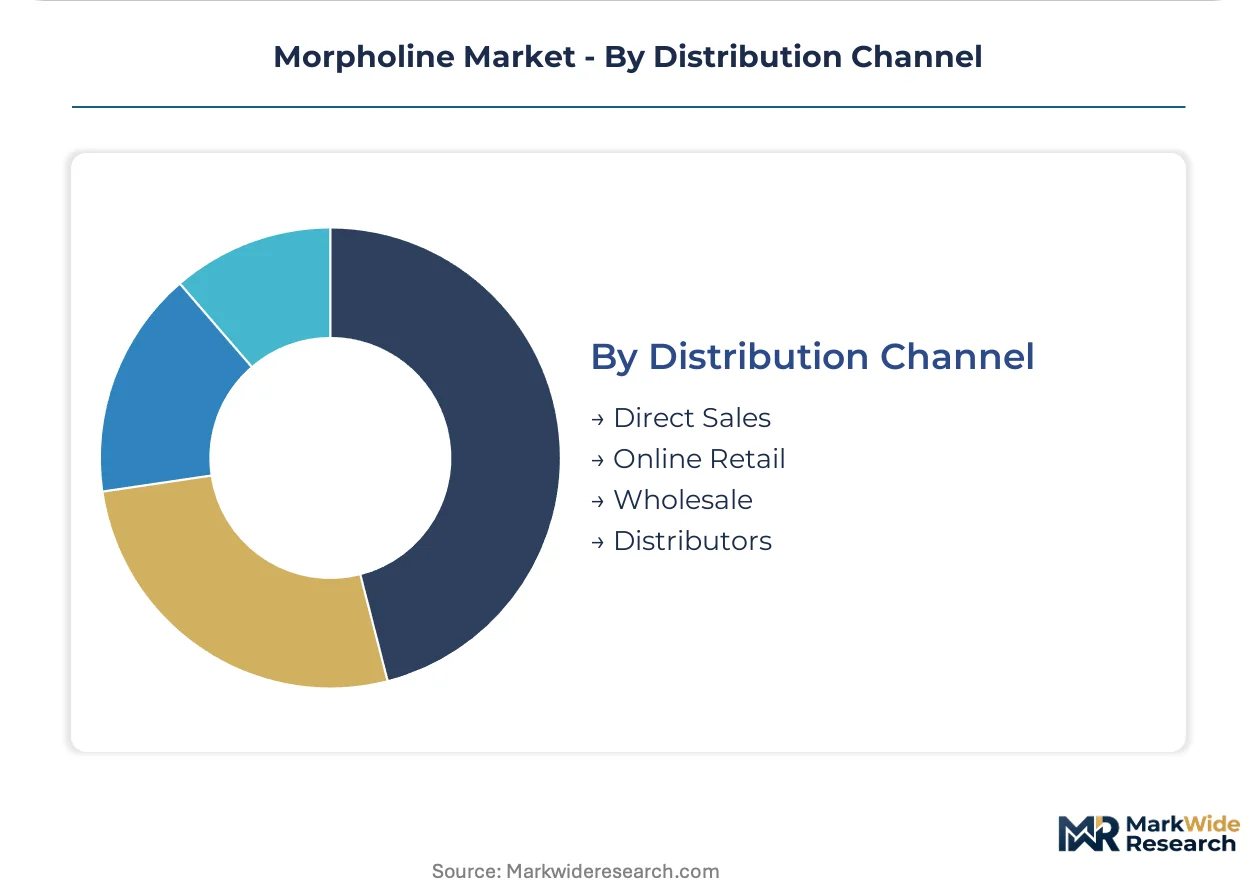
Distribution Channel:
Channel economics fragment between bulk tanker direct supply and packaged-goods distribution with incompatible logistics infrastructure.
- Direct Sales:Bulk tanker and drum shipments to integrated chemical processors. Continental and Michelin facilities in Germany's Ruhr cluster have eliminated distributor markups in favor of direct contracts with quarterly carbon-intensity reporting.
- Online Retail:Small-package sales to research institutions and specialty chemical buyers. Specifications concentrate in laboratory-grade offerings.
- Wholesale:Intermediate volume aggregation for regional chemical distributors. Inventory cycles vary by end-use seasonality.
- Distributors:Technical service and formulation support for rubber compounders. Legacy accelerator inventory displacement creates technical-service costs during switching events.
Direct sales holds capacity concentration. Distributors are gaining share fastest as specification-driven procurement consolidates buying among verified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE scrubber mandates and India's CDSCO harmonization are redirecting investment toward East Asian utilities and South Asian pharmaceutical registration. Regulatory divergence between EPA effluent rules and REACH reclassification is fragmenting procurement strategies across major demand centers.
China
Coal-fired power plant desulfurization retrofits under MEE directives absorb industrial-grade morpholine volumes at rates exceeding pharmaceutical demand growth. The Yangtze River Economic Belt emission caps on amine facilities are idling smaller batch reactors without scrubber retrofit capital. Zhejiang and Jiangsu provinces concentrate captive amine feedstock production from coal-chemical complexes serving regional utilities.
Germany
Ruhr industrial cluster tire manufacturers have eliminated distributor markups on accelerator packages in favor of direct contracts with quarterly carbon-intensity reporting. ECHA REACH substance evaluation drives substitution testing for reproductive-toxicity classifications affecting rubber-processing import volumes. BASF SE leverages integrated ethylene oxide supply chains from Ludwigshafen to sustain cost leadership across pharmaceutical-grade output.
United States
EPA effluent guidelines constrain morpholine discharge limits from pesticide formulation plants, compelling closed-loop recovery system adoption. Membrane-based amine recovery technology extends chemical inventory cycles from 45 to 90 days at power utilities. Gulf Coast petrochemical complexes anchor merchant supply capacity for export-grade cyclodehydration output.
India
CDSCO harmonization with ICH Q3C residual solvent guidelines creates first-mover advantage for pharmacopeial-grade morpholine suppliers with completed stability documentation. Balaji Amines Ltd. and APL anchor domestic production from Maharashtra and Gujarat chemical corridors. Crop protection chemical procurement intensification drives agrochemical-grade consumption across Punjab and Haryana agricultural belts.
Japan
PMDA pharmacopeial certification requirements align with USP and EP monograph standards for pharmaceutical excipient registration. Tire manufacturers in Kansai and Chubu industrial zones reformulate accelerator packages to meet evolving vulcanization performance standards. Ethylene oxide feedstock integration from Chiba and Yokkaichi petrochemical complexes supports cost-competitive domestic output.
Morpholine Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive ethylene oxide supply chains and regional specialty amine producers serving pharmaceutical and agrochemical niches. Market structure concentrates volume leadership among three to four vertically integrated operators while fragmented batch-reactor specialists compete on specification flexibility. Strategic archetypes include integrated petrochemical majors, coal-chemical conglomerates, and pharmacopeial-certified specialists. Competitive dynamics center on backward integration into diethanolamine feedstock and pharmacopeial certification timeline acceleration.
Within the integrated petrochemical tier, BASF SE and Huntsman Corporation exemplify cost-leadership positioning through captive ethylene oxide supply chains. Sinochem Group Co. Ltd. occupies a distinctive position controlling captive amine feedstock from coal-chemical complexes for domestic Chinese distribution. Among Asian specialty producers, Balaji Amines Ltd. and Nippon Nyukazai Co. Ltd. represent pharmacopeial-grade specialists navigating 18-24 month stability documentation cycles.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| Nippon Nyukazai Co. Ltd. |
| Sinochem Group Co. Ltd. |
| Balaji Amines Ltd. |
| Anhui Haoyuan Chemical Industry Group Co. Ltd. |
| Nouryon Chemicals Holding B.V. |
| APL (Amines And Plasticizers Ltd.) |
| Zhengzhou Fuyuan Chemical Industry Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive diethanolamine capacity at integrated Ludwigshafen and Chiba petrochemical complexes anchors cost leadership for export-grade cyclodehydration output, compressing price floors for merchant producers without backward integration into ethylene oxide feedstock. Scale advantages in amine production concentrate pricing power among three to four vertically integrated operators while fragmenting margin capture across specification tiers.
Pricing Analysis
Certification level creates the primary spread between industrial-grade bulk supply and pharmacopeial-certified output. Three-tier pricing structure across pharmaceutical, industrial, and agrochemical grades reflects documentation burden and purity thresholds. Cost compression in industrial-grade volumes is intensifying because China's MEE emission caps are idling smaller batch reactors without scrubber retrofit capital. Rubber-processing compounders exhibit highest price sensitivity due to accelerator package reformulation cycles, while pharmaceutical excipient buyers prioritize USP and EP monograph compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of ethylene oxide derivatives dominates inventory strategy among tire manufacturers facing 18-month accelerator qualification windows. Geographic supply concentration centers on China, Germany, and the United States for integrated cyclodehydration capacity. Feedstock dependencies draw from ethylene oxide, ammonia, and diethanolamine intermediates. Single-source vulnerability runs through Yangtze River Economic Belt amine facilities subject to MEE volatile organic compound enforcement. Distribution runs through direct bulk tanker contracts with quarterly carbon-intensity reporting for ISO 14001-certified compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morpholine demand is recovering from cyclical lows as coal-fired power plant scrubber retrofits across China absorb industrial-grade volumes at rates exceeding prior replacement cycles. This utility-driven offtake anchors near-term volume recovery while pharmaceutical-grade margins sustain structural premia.
For Market Incumbents: Consolidate backward integration into diethanolamine feedstock to defend margin position against ethylene oxide price volatility. Accelerate pharmacopeial certification timelines for Indian CDSCO registration to capture first-mover advantage before stability documentation cycles strain competitor working capital. Capacity concentration in Zhejiang and Jiangsu provinces offers geographic defense against Yangtze River emission enforcement.
For New Entrants and Emerging Players: Technical-service gaps in rubber accelerator package reformulation present white-space entry points where incumbents under-serve compounders facing legacy inventory displacement costs. Target agrochemical-grade supply to pesticide formulation plants under EPA effluent guideline compliance deadlines. Pursue toll-processing contracts with guaranteed offtake minimums to secure membrane-based amine recovery infrastructure partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmacopeial-grade specialists with completed USP and EP stability documentation cycles. Long-term viability favors acquisition targets with captive ethylene oxide integration and verified lifecycle documentation for ISO 14001-certified procurement channels. Watch ECHA REACH substance evaluation outcomes as inflection indicators for reproductive-toxicity reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive diethanolamine feedstock from Ludwigshafen complexes secures cost-advantaged cyclodehydration capacity. |
| Pharmacopeial Certification Acceleration | CDSCO harmonization with ICH Q3C guidelines creates first-mover positioning for Indian pharmaceutical excipient registration. |
| Membrane-Based Amine Recovery Deployment | US power utilities adopting membrane units extend chemical inventory cycles from 45 to 90 days. |
| Long-Term Supply Agreement with Tire Manufacturers | Direct contracts with quarterly carbon-intensity reporting eliminate distributor markups in Germany's Ruhr cluster. |
| Joint Venture for Coal-Chemical Feedstock Access | Sinochem's captive amine supply from coal-chemical complexes dominates domestic Chinese distribution networks. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors and secondary validation through customs/trade data, ACC and Cefic reports, SEC 10-K filings, and ECHA REACH substance evaluation records anchors the qualitative findings. Bottom-up capacity and consumption modeling triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around ethylene oxide feedstock pricing, MEE emission enforcement intensity, and ECHA reproductive-toxicity reclassification outcomes stress-tests projection robustness. The analytical framework segments across grade tier, end-use industry, packaging format, and regional production hub throughout the forecast period. CAGRs derive from regression against historical cyclodehydration capacity utilization and scrubber retrofit installation rates in Chinese coal-fired power generation.
Forecasts assume regulatory continuity in EPA effluent guidelines, ECHA REACH evaluations, and China's MEE emission caps; material policy shifts would require re-modeling. Revision becomes warranted when ethylene oxide price volatility crosses margin compression thresholds or when Yangtze River enforcement idles capacity exceeding regional demand buffers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Waterborne Curing Agents Market
Chemicals
Global Thiophene Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Hydrazine Market
Chemicals
Lead Tetracetate Market
Chemicals
Benzenoid Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
China Amines Market
Chemicals
Potassium Fluoride Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Nonanoic Acid Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Resorcinol Market
Chemicals
Aluminum Chemicals Market