
 Trifluoroacetic Acid (TFA) Market | 2026-2036
Trifluoroacetic Acid (TFA) Market Size, Share, and Industry Trends Forecast 2026-2036
Trifluoroacetic Acid (TFA) Market Analytics
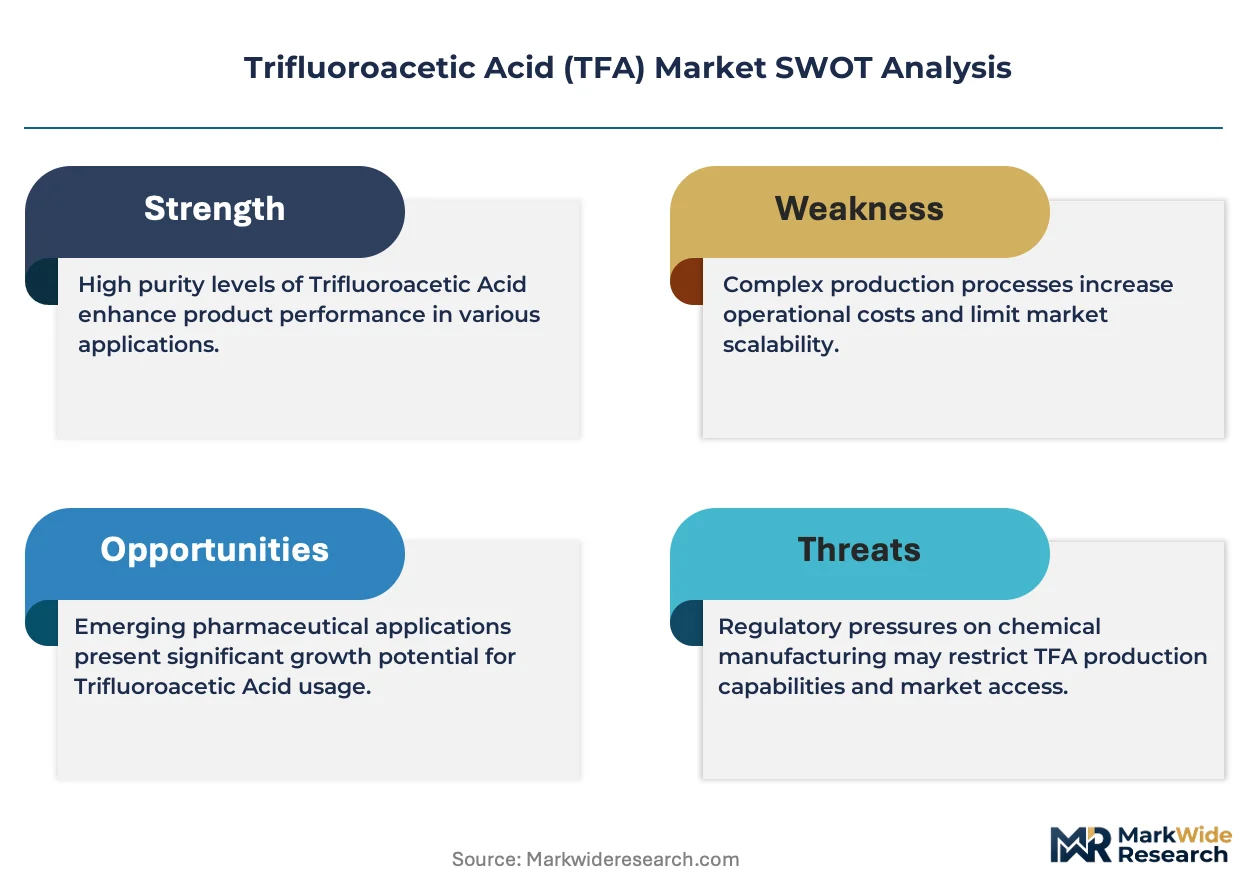
Contract manufacturing and toll-processing arrangements is realigning how TFA value gets captured, shifting margin from commodity volume to technical service bundles. Solvay leverages its European fluorochemistry heritage to sustain premium positioning in high-purity grades. SRF anchors South Asian supply through backward integration into chlorodifluoromethane feedstock. Halocarbon specializes in North American pharmaceutical-grade distribution, competing on lot traceability and regulatory documentation.
Trifluoroacetic acid is a perfluorinated carboxylic acid with formula CF3COOH, featuring a strongly electron-withdrawing trifluoromethyl group that imparts exceptional acidity (pKa 0.3) and makes it indispensable for peptide deprotection, NMR spectroscopy solvents, and fluorinated intermediate synthesis. Pharmaceutical-grade TFA commands the deepest margin pool as peptide therapeutics and oligonucleotide manufacturing expand, while reagent-grade volumes dominate unit shipments to academic and industrial R&D laboratories. Industrial-grade applications in electronics etching and agrochemical synthesis represent mature, price-sensitive demand with thinner returns.
China's MEE enforces fluorinated organic compound discharge limits under revised water pollution prevention standards, compelling domestic producers to upgrade effluent treatment. The EU REACH framework classifies TFA as a substance of very high concern candidate, pressuring importers to document substitution assessments and safe-use protocols. FDA chemistry, manufacturing, and controls guidelines for peptide drug applications specify residual TFA limits, directly shaping pharmaceutical-grade purity specifications. Stakeholders must monitor evolving fluorochemical restrictions across manufacturing jurisdictions while calibrating grade-mix investments against therapeutic modality shifts in the peptide pipeline.
Market Dynamics
Peptide therapeutic pipelines are expanding TFA consumption as GLP-1 agonists and oligonucleotide manufacturing scale, while fluorochemical discharge regulations in major manufacturing jurisdictions force simultaneous purity upgrades and environmental compliance investments.
Growth Catalysts
- Peptide synthesis expansion:Contract manufacturers in Zhejiang and Jiangsu provinces are expanding deprotection capacity for incretin-based therapies, directly lifting pharmaceutical-grade TFA offtake.
- NMPA impurity mandates:China's tightened fluorinated reagent profiling requirements are pushing domestic producers toward higher-purity grades, compressing low-grade supply and elevating technical barriers.
- REACH documentation pressure:EU importers must complete substitution assessments and safe-use protocols for SVHC-candidate substances, favoring established suppliers with regulatory dossiers.
Market Restraints
- Chlorodifluoromethane feedstock volatility:HCFC-22 supply fluctuations and phase-out schedules under the Montreal Protocol create raw material cost instability for TFA producers.
- Effluent treatment capex:China's MEE water pollution standards mandate fluorinated organic compound discharge limits that require multi-million-dollar wastewater infrastructure upgrades.
- Perfluoroalkyl substitution risk:Green chemistry initiatives in pharmaceutical R&D are exploring enzymatic deprotection and ionic liquid alternatives to TFA-mediated cleavage.
Strategic Opportunities
- Indian CMO corridor development:Hyderabad and Ahmedabad peptide manufacturing clusters lack domestic high-purity TFA supply, creating import substitution potential for qualified suppliers.
- Regenerative medicine applications:Cell therapy manufacturing protocols are adopting TFA for extracellular matrix peptide modification, opening adjacent demand beyond traditional pharmaceuticals.
- Dual-use electronics qualification:Semiconductor etching applications require sub-ppb metal specifications that command pricing premiums above pharmaceutical grades.
Industry Challenges
- Analytical chemist scarcity:Fluorinated impurity profiling by LC-MS/MS requires specialized expertise that contract labs struggle to staff, extending batch release timelines.
- Multijurisdictional dossier maintenance:Simultaneous FDA chemistry manufacturing controls, EMA REACH compliance, and NMPA registration create documentation complexity and audit frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trifluoroacetic Acid (TFA) Market |
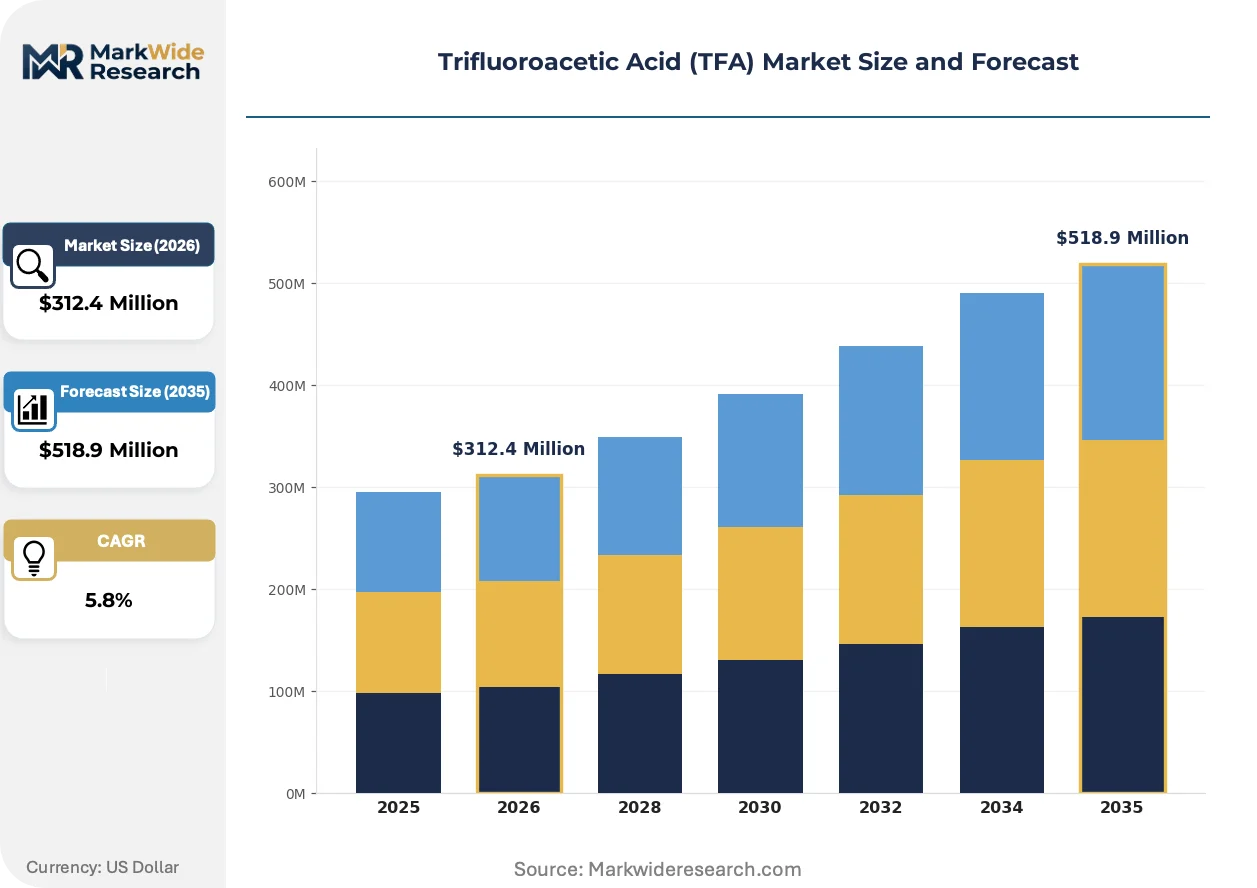
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Analytical Grade, Industrial Grade, Pharmaceutical Grade End Use Industry: Chemical Synthesis, Pharmaceuticals, Agrochemicals, Electronics Packaging Type: Drums, Bottles, Bulk Containers, Carboys Grade: High Purity, Standard Purity, Low Purity, Technical Grade |
| Companies Covered | SRF, Shandong Xingfu, Solvay, Nantong Baokai, Zhenfu New Materials, Halocarbon, Bluestar, Anhui Jinao, Sinochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trifluoroacetic Acid (TFA) Market Evolving Landscape
Continuous flow peptide synthesis is compressing batch sizes and residual solvent specifications, while regulatory frameworks in major manufacturing jurisdictions are tightening fluorochemical accountability.
Membrane-based TFA recovery systems are overtaking traditional distillation for waste acid reclamation in large-scale peptide manufacturing facilities. European CMOs operating under F-Gas Regulation constraints are installing electrodialysis units to achieve closed-loop acid circulation. This technology is overtaking thermal separation methods by reducing energy intensity and enabling compliance with EU Green Deal carbon intensity benchmarks.
China's MEE revised water pollution prevention standards now enforce fluorinated organic compound discharge limits that exceed previous provincial thresholds. Domestic producers in Taizhou and Changzhou chemical parks must upgrade biological treatment trains with activated carbon polishing. Pharmaceutical-grade manufacturers are responding by segregating high-purity production streams from industrial-grade operations to isolate effluent treatment costs.
Specification-driven procurement now dominates peptide API supply agreements, with buyers mandating lot-level impurity certificates and chain-of-custody documentation. Large pharmaceutical sponsors are disintermediating distributors to contract directly with TFA producers capable of FDA-compliant master file support. This pattern concentrates most visibly in Massachusetts and California biotech corridors where sponsor quality audit frequency has doubled.
Trifluoroacetic Acid (TFA) Market Segmentation
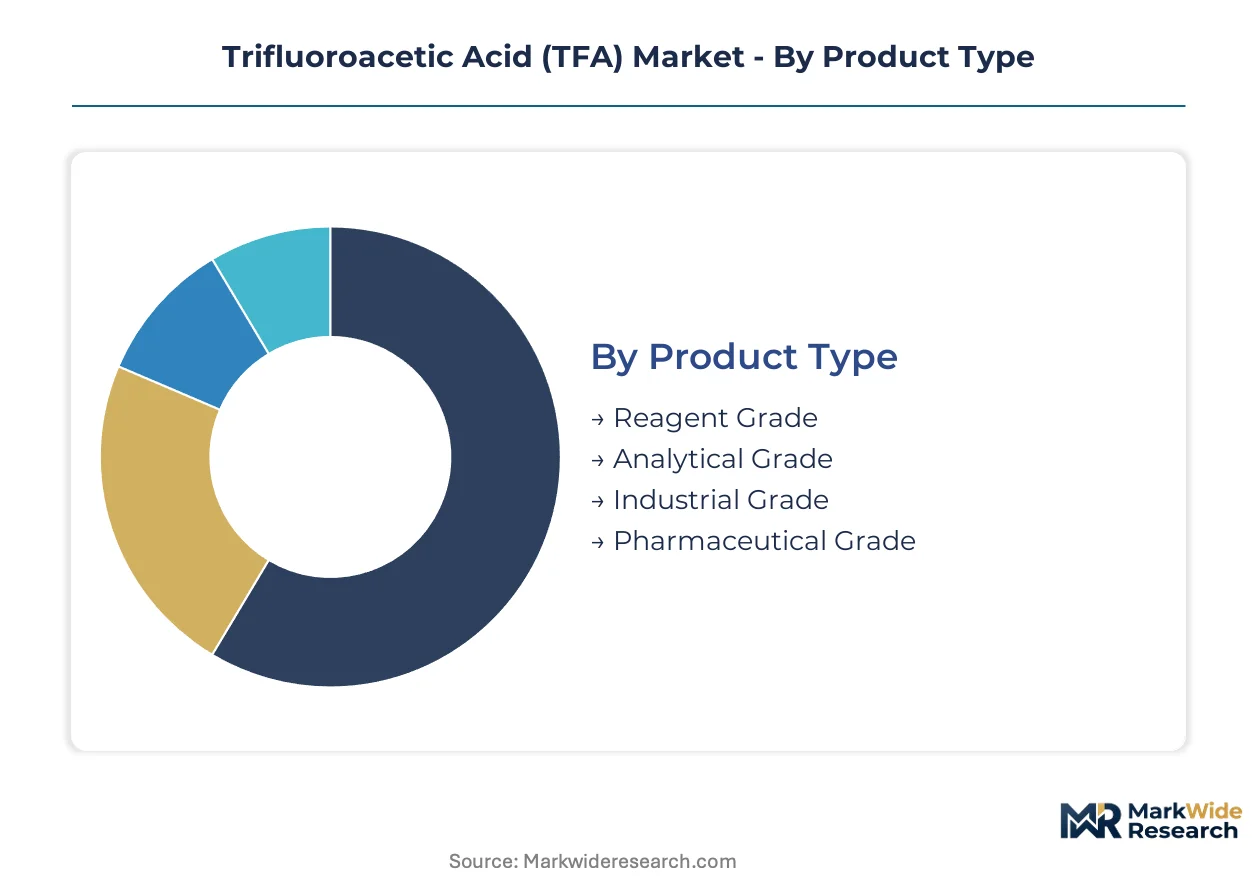
Grade purity specifications and packaging configurations determine margin capture in TFA supply chains. Pharmaceutical sponsors now mandate lot-level documentation that forces segmentation clarity across producer portfolios.
Product Type:
Upgrade cycles from industrial to pharmaceutical grades are compressing as peptide therapeutic pipelines expand and residual solvent specifications tighten.
- Pharmaceutical Grade:Purity exceeds 99.5% with sub-ppm metal specifications and full regulatory dossier support. Demand concentrates in Zhejiang and Jiangsu province CMOs manufacturing GLP-1 agonists, where NMPA impurity profiling mandates now require certificates of analysis for every lot.
- Reagent Grade:Standard laboratory purity suitable for peptide deprotection and NMR spectroscopy solvents. Academic and industrial R&D laboratories in Massachusetts and California biotech corridors drive steady offtake, though procurement is shifting toward specification-driven direct contracts with producers.
- Analytical Grade:Ultra-high purity for chromatography and analytical method development. Quality control laboratories in FDA-regulated facilities require this grade for reference standard preparation.
- Industrial Grade:Lower purity for electronics etching and agrochemical intermediate synthesis. Price-sensitive demand with thinner returns characterizes this segment.
Pharmaceutical Grade sits at the top of the volume ranking, with Reagent Grade climbing the fastest as continuous flow synthesis expands laboratory-scale consumption.
End Use Industry:
Cost tier differentiation separates validated pharmaceutical applications from commodity chemical synthesis on specification stringency and documentation burden.
- Pharmaceuticals:Peptide synthesis deprotection and counterion formation in active pharmaceutical ingredient production. Contract manufacturers face FDA chemistry manufacturing controls guidelines specifying residual TFA limits, directly shaping purity procurement standards.
- Chemical Synthesis:Fluorinated intermediate production and organic transformation reagent applications. Industrial chemical producers in Taizhou chemical parks consume standard grades with minimal documentation requirements.
- Electronics:Semiconductor etching and wafer cleaning applications requiring sub-ppb metal specifications. This segment commands pricing premiums above pharmaceutical grades when dual-use qualification is achieved.
- Agrochemicals:Herbicide and pesticide intermediate manufacturing. Mature demand with environmental compliance pressure from China's MEE water pollution standards limiting discharge of fluorinated organic compounds.
Pharmaceuticals dominates revenue contribution, with Electronics gaining share fastest on semiconductor fabrication expansion.
Packaging Type:
Customer type and volume scale determine packaging selection, with large pharmaceutical sponsors favoring bulk configurations while research laboratories require smaller units.
- Bulk Containers:Tank trucks and ISO tanks for high-volume pharmaceutical manufacturing sites. Direct producer relationships with Massachusetts and California biotech sponsors favor this format for cost efficiency and chain-of-custody documentation.
- Drums:Standard 200-liter steel or HDPE drums for mid-scale chemical synthesis operations. Widely used across industrial-grade applications in Changzhou chemical parks.
- Carboys:Returnable and disposable options for pharmaceutical cleanroom environments. Hyderabad and Ahmedabad peptide manufacturing clusters import these given limited domestic high-purity supply.
- Bottles:Glass and fluoropolymer bottles for laboratory-scale reagent distribution. Academic procurement through distributors maintains this segment.
Bulk Containers leads volume throughput, with Carboys expanding most quickly on Indian CMO corridor development.
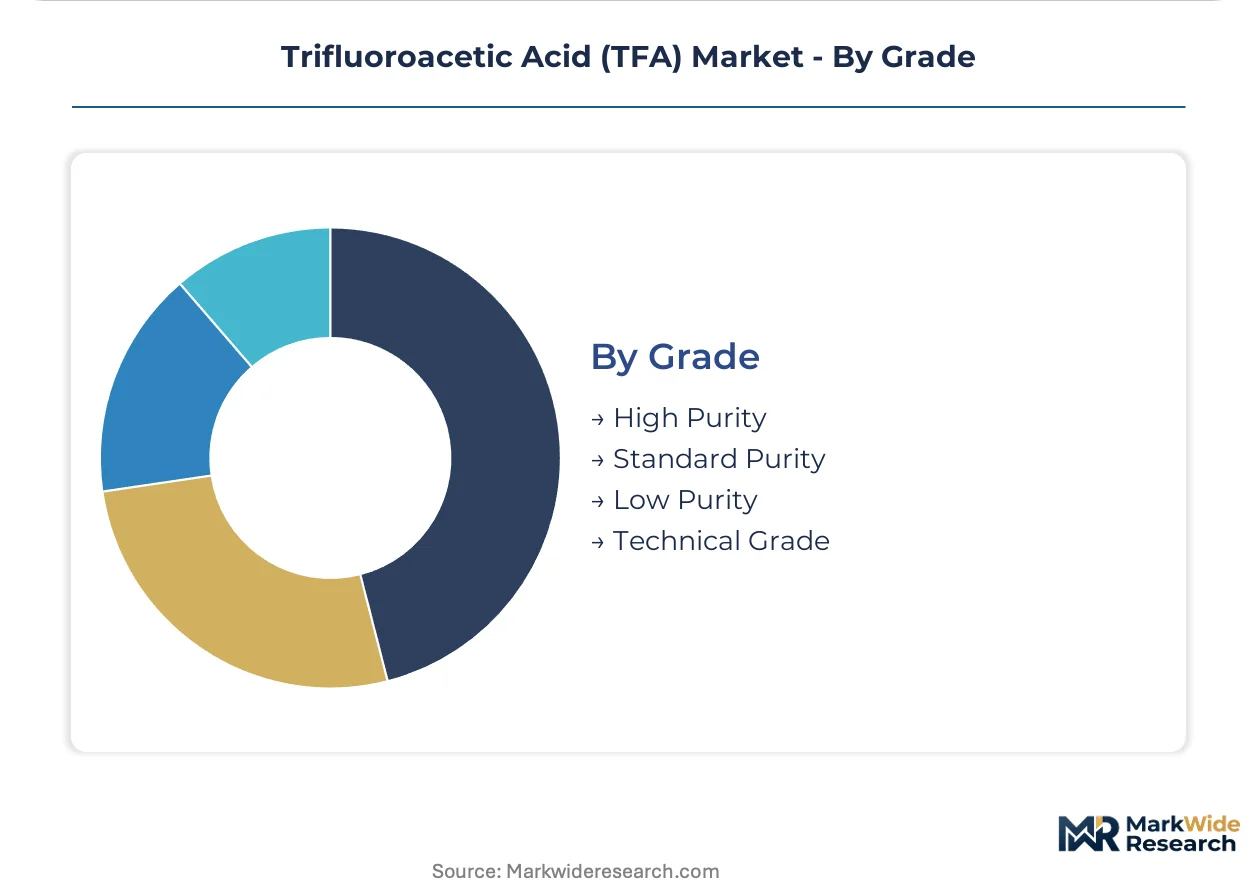
Grade:
Margin concentration tracks purity tier, with high-purity production segregated from industrial streams to isolate effluent treatment costs.
- High Purity:Sub-ppm impurities with full analytical characterization including LC-MS/MS fluorinated impurity profiling. EU REACH framework classification as SVHC candidate pressures importers toward documented safe-use protocols and substitution assessments.
- Standard Purity:Conventional laboratory and industrial specifications. General chemical synthesis and academic research applications absorb this tier.
- Low Purity:Basic industrial applications with minimal analytical burden. Electronics etching without semiconductor qualification accepts this grade.
- Technical Grade:Unspecified purity for bulk chemical processing where TFA serves as acid catalyst or process solvent. Price-competitive positioning with thinnest margins.
High Purity commands the steepest expansion trajectory, with Technical Grade contracting as environmental compliance costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes more pharmaceutical-grade TFA than any other single country, yet India's peptide manufacturing clusters now import record volumes as domestic supply falls short of purity requirements.
United States
Massachusetts and California biotech corridors drive pharmaceutical-grade offtake for GLP-1 agonist manufacturing. FDA chemistry manufacturing controls guidelines specify residual TFA limits that shape procurement standards. Direct sponsor-producer contracts are disintermediating distributors in Greater Boston.
China
Zhejiang and Jiangsu province CMOs anchor demand for deprotection reagents in incretin-based therapy production. MEE water pollution standards enforce fluorinated organic compound discharge limits exceeding prior provincial thresholds. Taizhou and Changzhou chemical parks are segregating high-purity streams from industrial-grade operations.
Germany
European CMOs under F-Gas Regulation constraints are installing electrodialysis units for closed-loop acid circulation. EU REACH framework classification of TFA as SVHC candidate pressures importers toward documented substitution assessments. Bavaria-based peptide manufacturers are qualifying membrane-based recovery systems.
India
Hyderabad and Ahmedabad peptide manufacturing clusters lack domestic high-purity TFA supply, creating import dependency. CDSCO registration requirements for fluorinated reagents are tightening quality documentation burdens. Gujarat-based API houses are expanding deprotection capacity without matching feedstock infrastructure.
Japan
PMDA guidelines for peptide drug applications align with FDA residual solvent specifications, driving pharmaceutical-grade procurement. METI industrial standards for fluorochemical manufacturing are elevating analytical characterization requirements. Osaka-based CMOs are qualifying sub-ppm metal specification supply chains.
Trifluoroacetic Acid (TFA) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical service bundles capturing margin from commodity volume players. The supplier base concentrates around three strategic archetypes: European heritage fluorochemists with regulatory dossier depth, South Asian feedstock-integrated producers, and North American pharmaceutical-grade distributors competing on lot traceability. Dominant competitive moves include backward integration into chlorodifluoromethane feedstock and geographic expansion into underserved Indian CMO corridors.
Among European heritage producers, Solvay occupies a position exemplifying premium-grade positioning through regulatory dossier support. SRF represents the feedstock-integrated archetype with captive chlorodifluoromethane supply. Halocarbon anchors North American pharmaceutical-grade distribution capabilities. These three patterns illustrate how margin capture shifts from volume to technical service bundles across the value chain.
| Leading Market Players |
|---|
| SRF |
| Shandong Xingfu |
| Solvay |
| Nantong Baokai |
| Zhenfu New Materials |
| Halocarbon |
| Bluestar |
| Anhui Jinao |
| Sinochem |
| Others |
Value Network & Pricing Analysis
Membrane-based TFA recovery systems are compressing unit economics for large-scale peptide manufacturers while simultaneously concentrating supply leverage among European CMOs with installed electrodialysis capacity. China's MEE discharge mandates are forcing domestic producers to segregate high-purity streams, elevating cost structures and compressing low-grade availability.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for pharmaceutical-grade material as NMPA impurity profiling mandates elevate technical barriers. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades tracks certification burden and analytical documentation depth. Cost compression in industrial grades is intensifying because environmental compliance capex cannot be recovered at commodity price points. Academic laboratories exhibit highest price sensitivity, while GLP-1 agonist sponsors accept premium positioning for FDA-compliant master file support.
Supply Chain Analysis
Dual-sourcing requirements from Massachusetts and California biotech sponsors are fragmenting procurement across Solvay's European heritage supply, SRF's South Asian feedstock-integrated production, and Halocarbon's North American distribution. Raw material flows draw from chlorodifluoromethane feedstock concentrated in China and India, fluoropolymer packaging from Japan, and analytical reference standards from Germany. Single-source vulnerability runs through HCFC-22 phase-out schedules under the Montreal Protocol. Distribution runs through direct producer-sponsor contracts disintermediating traditional chemical distributors in high-purity segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA chemistry manufacturing controls guidelines for residual TFA limits in peptide applications directly expand pharmaceutical-grade demand.
For Market Incumbents: Cement regulatory dossier depth against REACH SVHC-candidate substitution pressures by completing ECHA safe-use protocols and maintaining NMPA registration currency. Backward integration into chlorodifluoromethane feedstock anchors margin control against HCFC-22 volatility. Capacity expansion in Hyderabad and Ahmedabad corridors captures Indian CMO import dependency before domestic qualification spreads. For New Entrants and Emerging Players: Enter via analytical-grade specialization targeting quality control laboratories in FDA-regulated facilities where lot-level impurity certificates command pricing premiums. Indian peptide manufacturing clusters present the most penetrable geography given CDSCO registration barriers limiting qualified domestic supply. Technical service bundling with membrane-based recovery system integration offers differentiated positioning against commodity volume players. For Investors and Strategic Acquirers: Valuations sit cheapest among technical-grade producers facing MEE effluent treatment capex without pharmaceutical-grade margin buffers. Long-term viability centers on feedstock-integrated specialists with captive chlorodifluoromethane supply and regulatory dossier depth across FDA, EMA, and NMPA jurisdictions. Watch enzymatic deprotection technology maturation in pharmaceutical R&D as substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HCFC-22 Feedstock | Captive chlorodifluoromethane supply insulates SRF against Montreal Protocol phase-out volatility. |
| Membrane-Based Recovery System Deployment | Electrodialysis units enable Bavarian CMOs to achieve F-Gas Regulation closed-loop compliance. |
| Indian CMO Corridor Qualification | Hyderabad and Ahmedabad peptide clusters lack domestic high-purity supply, creating import substitution entry. |
| FDA Master File Support Investment | Direct sponsor contracts in Massachusetts disintermediate distributors on lot traceability documentation. |
| Dual-Use Electronics Qualification | Sub-ppb metal specifications for semiconductor etching command pricing premiums above pharmaceutical grades. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with peptide manufacturing executives, regulatory affairs leads at fluorochemical producers, procurement managers at CMOs, and technical R&D directors. Secondary validation draws from FDA chemistry manufacturing controls guidelines, ECHA REACH SVHC candidate listings, NMPA impurity profiling standards, and customs trade data for fluorinated organic compound flows. Bottom-up grade-tier volume estimates triangulate against top-down peptide therapeutic pipeline projections.
Granularity-level modeling distinguishes pharmaceutical, reagent, analytical, and industrial grades across purity specifications, with end-use industry segmentation tracking peptide synthesis, electronics etching, and agrochemical intermediate applications. Regional production hub clustering captures Zhejiang-Jiangsu corridor concentration versus Indian import dependency. CAGRs derive from therapeutic modality shifts in GLP-1 agonist and oligonucleotide manufacturing expansion across the projection horizon.
Inputs from sponsor quality audits and CMO procurement databases were available through the study window; gaps in real-time HCFC-22 feedstock pricing introduce uncertainty bands around cost structure projections. Forecasts reflect assumptions regarding NMPA enforcement consistency and REACH SVHC candidate progression. Deviation in enzymatic deprotection technology maturation or Montreal Protocol acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Trichlorosilane Market
Chemicals
Methylamines Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Global Thiophene Market
Chemicals
Roofing Chemical Market
Chemicals
Phosgene Market
Chemicals
6 Hexanediol Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
P-Ethylphenol Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global Glycine Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Periodic Acid Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Hydrogenated Dimer Acid Market