
 Sodium Tripolyphosphate (STPP) Market | 2026-2036
Sodium Tripolyphosphate (STPP) Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Tripolyphosphate (STPP) Market Analytics
Market Context with Strategic Players
Modular detergent formulations is rebalancing procurement patterns as manufacturers unbundle phosphate sourcing from surfactant supply agreements. PhosAgro Group leverages captive phosphate rock reserves to sustain cost leadership across European supply corridors. WENGFU GROUP CO. LTD. anchors its position through backward integration into phosphate mining and sulfuric acid production. Hubei Xingfa Chemicals Group Co. Ltd. competes on granular STPP specialization for industrial water treatment clients.
Technical Definition and Structural Segments
Sodium tripolyphosphate is a sodium salt of the polyphosphate penta-anion with the formula Na5P3O10, produced through the thermal dehydration of monosodium and disodium phosphate mixture at controlled temperature profiles exceeding 300°C. The compound functions primarily as a sequestrant, dispersant, and pH buffer across detergent, food processing, and water treatment applications. Industrial grade STPP dominates volume throughput due to entrenched demand from cleaning products manufacturers, while food grade commands premium positioning tied to FSSAI and FDA compliance burdens. Powder form occupies the largest share of shipment configuration, though granular variants are gaining traction in automated dosing systems for water treatment facilities.
Regulatory Frame and Forward-Looking Close
REACH restrictions on phosphate discharge in European waterways, coupled with EPA phosphorus loading limits for municipal wastewater, are forcing detergent reformulation toward concentrated and phosphate-free alternatives. China's MEE enforces discharge standards for phosphate-containing effluents from chemical production clusters, raising compliance costs for domestic manufacturers. India's BIS certification requirements for food-grade STPP create non-tariff barriers that filter substandard imports. Stakeholders must monitor regulatory divergence between jurisdictions that ban phosphates outright versus those that permit controlled agricultural runoff applications.
Market Dynamics
Formulation unbundling across detergent supply chains is fragmenting phosphate procurement from surfactant sourcing, forcing manufacturers to rebuild supplier relationships around discrete chemical inputs rather than bundled ingredient packages.
Growth Catalysts
- MEE discharge standards:China's tightening effluent rules for phosphate-containing chemical production are accelerating consolidation toward compliant manufacturers with captive treatment infrastructure.
- Industrial water treatment:Granular STPP adoption in automated dosing systems for municipal and facility-scale water treatment is expanding addressable demand beyond traditional detergent channels.
- Food-grade certification premiums:FSSAI and FDA compliance burdens for food processing applications are creating price insulation for certified producers against commodity-grade competition.
Market Restraints
- Phosphate rock supply concentration:Captive mining assets held by integrated producers in Morocco and Russia limit raw material access for non-integrated compounders.
- REACH discharge restrictions:European phosphorus loading limits for municipal wastewater are mandating reformulation away from phosphate-based detergents in core Western European markets.
- Zeolite substitution:Alternative builders in phosphate-free laundry formulations are displacing STPP in household applications where regulatory bans apply.
Strategic Opportunities
- Southeast Asian production expansion:Vietnam and Indonesia offer underexploited manufacturing bases with proximity to growing ASEAN detergent demand and less stringent discharge regulation.
- Agricultural runoff applications:Controlled phosphate release in fertilizer formulations represents a regulatory-permitted outlet where outright detergent bans create supply overhang.
- Dual-carbon policy alignment:China's national carbon intensity targets reward energy-efficient thermal dehydration processes with preferential licensing in chemical industry zones.
Industry Challenges
- Process engineer scarcity:Specialized expertise in high-temperature phosphate dehydration reactor operation is concentrated among retiring workforces at legacy production facilities.
- Food-grade certification timelines:BIS and FSSAI approval cycles for new STPP production lines extend 18-24 months, freezing capital deployment until clearance.
- Legacy dosing system incompatibility:Water treatment facilities with powder-optimized infrastructure face retrofit costs to accommodate granular product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Tripolyphosphate (STPP) Market |
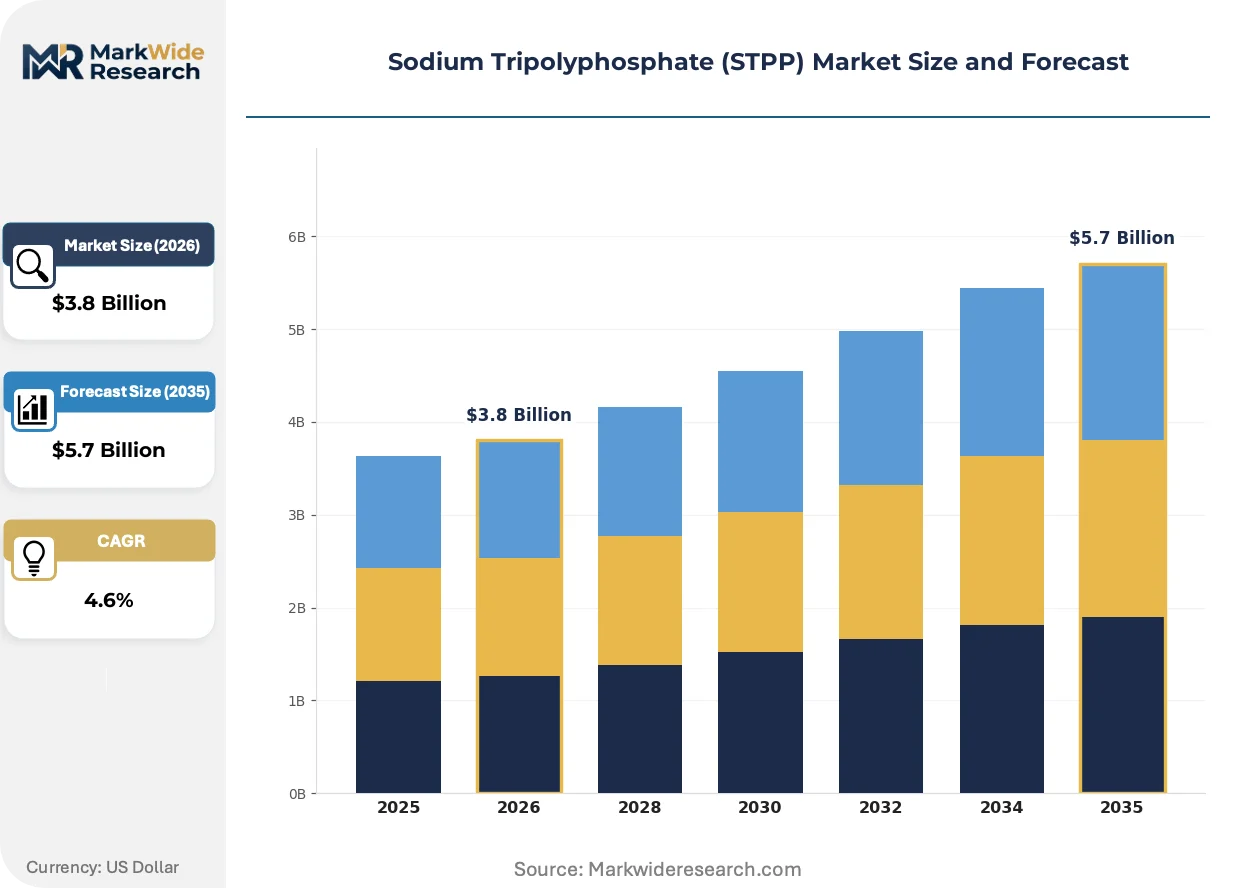
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
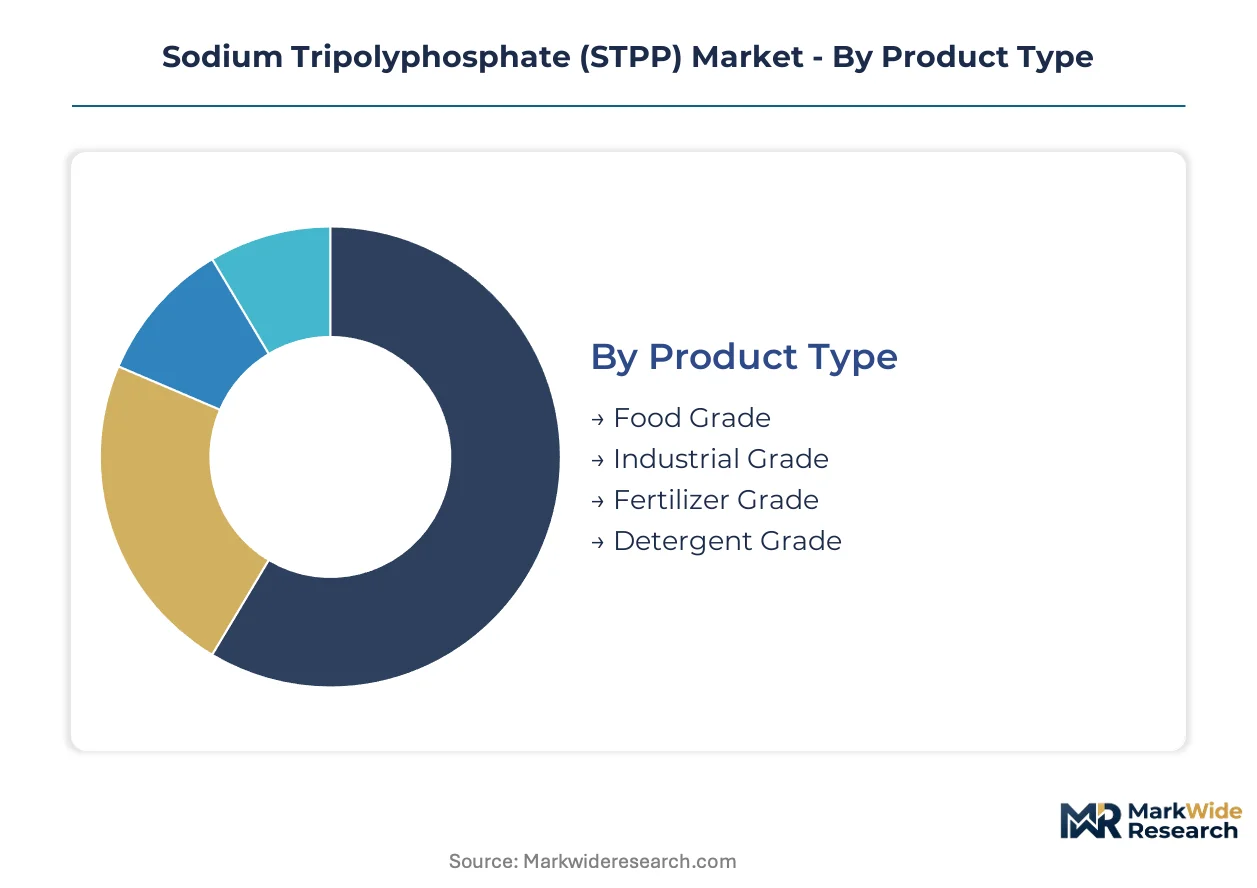
| Segmentation | Product Type: Food Grade, Industrial Grade, Fertilizer Grade, Detergent Grade Application: Food Preservation, Detergents, Water Treatment, Agriculture End User: Food Industry, Cleaning Products Manufacturers, Water Treatment Facilities, Agriculture Sector Form: Powder, Granular, Liquid, Crystalline |
| Companies Covered | PhosAgro Group, Wuhan Inorganic Salt Chemical Plant, WENGFU GROUP CO. LTD., Haifa Group, Hubei Xingfa Chemicals Group Co. Ltd., Yuntianhua Co., Ltd., Yibin Tianyuan Group, Grasim Industries Ltd., Yunphos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Tripolyphosphate (STPP) Market Evolving Landscape
Automation and regulatory differentiation are splitting the market into two velocity tiers: commodity-grade volume competing on thermal efficiency, and certified-grade specialty commanding compliance-linked premiums.
Membrane filtration pre-treatment is converging with thermal dehydration in next-generation STPP production lines. Chinese chemical manufacturers in the Yangtze River Delta are piloting integrated membrane-concentration systems that reduce energy input per ton by recovering process water. This technology convergence is compressing operating cost spreads between integrated and merchant producers.
EPA phosphorus loading limits for municipal wastewater are forcing detergent reformulation timelines in the United States. The industrial consequence is accelerated R&D spending on builder alternatives by multinational cleaning product manufacturers. Household laundry applications in the Great Lakes watershed are most affected, with regional brands already launching phosphate-free variants ahead of federal mandate expansion.
Direct procurement from phosphate compounders is displacing distributor-mediated sourcing among large detergent manufacturers. Regional surfactant suppliers that previously bundled STPP are losing chemical sourcing relationships to dedicated phosphate traders with logistics specialization. This channel disintermediation is most visible in East Asian production clusters where manufacturer scale justifies container-direct import arrangements.
Sodium Tripolyphosphate (STPP) Market Segmentation
STPP procurement patterns diverge sharply across certification tiers, with food-grade and industrial-grade specifications commanding entirely different supplier relationships and compliance timelines. Formulation requirements in detergents, water treatment, and food processing create distinct demand profiles that resist standardization.
Product Type:
Certification burdens stratify procurement costs: FDA and FSSAI compliance for food-grade STPP extends approval cycles 18-24 months, while industrial-grade operates under discharge-focused MEE and EPA frameworks without equivalent pre-market barriers.
- Industrial Grade:Thermal dehydration at controlled temperature profiles exceeding 300°C yields sodium salt of polyphosphate penta-anion optimized for sequestrant and dispersant functions. Demand concentrates in East Asian detergent manufacturing clusters where Chinese chemical producers supply container-direct arrangements to unbundled procurement operations. REACH phosphorus loading limits in European waterways constrain volume growth in core Western markets.
- Food Grade:Stringent Na5P3O10 purity specifications with heavy metal and arsenic limits enforced by FDA 21 CFR and FSSAI Food Safety Standards. Premium positioning reflects compliance infrastructure investments in HACCP-certified production lines and batch traceability systems. India's BIS certification creates non-tariff barriers filtering substandard imports from Southeast Asian producers.
- Fertilizer Grade:Controlled phosphate release formulations for agricultural runoff applications where detergent bans redirect supply overhang.
- Detergent Grade:Modular formulation inputs for manufacturers rebuilding supplier relationships around discrete chemical sourcing.
Leading the category by volume: Industrial Grade. Growing fastest: Food Grade.
Application:
End-use concentration determines margin structure, with food preservation and water treatment commanding compliance-linked premiums against commodity-exposed detergent channels facing zeolite substitution pressure.
- Detergents:Builder and sequestrant functions in laundry and dish formulations, now reformulating toward concentrated and phosphate-free alternatives under EPA phosphorus limits for Great Lakes watershed and European REACH discharge restrictions. Volume pressure from zeolite substitution in household applications.
- Water Treatment:Municipal and facility-scale applications adopting granular STPP in automated dosing systems for scale inhibition and corrosion control. Municipal procurement in United States Great Lakes region accelerates ahead of federal mandate expansion.
- Food Preservation:Moisture retention and texture modification in processed meat and seafood, requiring FSSAI and FDA batch certification with 18-24 month approval timelines freezing capital deployment.
- Agriculture:Controlled phosphate release in fertilizer formulations representing regulatory-permitted outlet where outright detergent bans create supply overhang.
Detergents retain volume dominance. Water Treatment expands most quickly on automated dosing adoption.
End User:
Customer scale dictates channel structure, with large detergent manufacturers disintermediating regional surfactant suppliers for direct phosphate compounder relationships while water treatment facilities face retrofit costs for granular compatibility.
- Cleaning Products Manufacturers:Unbundled procurement from surfactant bundles toward discrete phosphate sourcing, with container-direct import arrangements in East Asian production clusters.
- Water Treatment Facilities:Municipal and industrial scale operations with powder-optimized infrastructure facing capital costs to accommodate granular product transitions.
- Food Industry:Processed meat, seafood, and dairy operations requiring FSSAI and FDA certified inputs with traceability documentation.
- Agriculture Sector:Fertilizer compounders absorbing supply overhang from detergent reformulation in permitted runoff applications.
Cleaning Products Manufacturers anchor demand. Water Treatment Facilities gain share fastest on infrastructure automation.
Form:
Physical configuration determines logistics economics and dosing system compatibility, with powder dominating shipment volumes while granular variants capture automation-driven water treatment expansion.
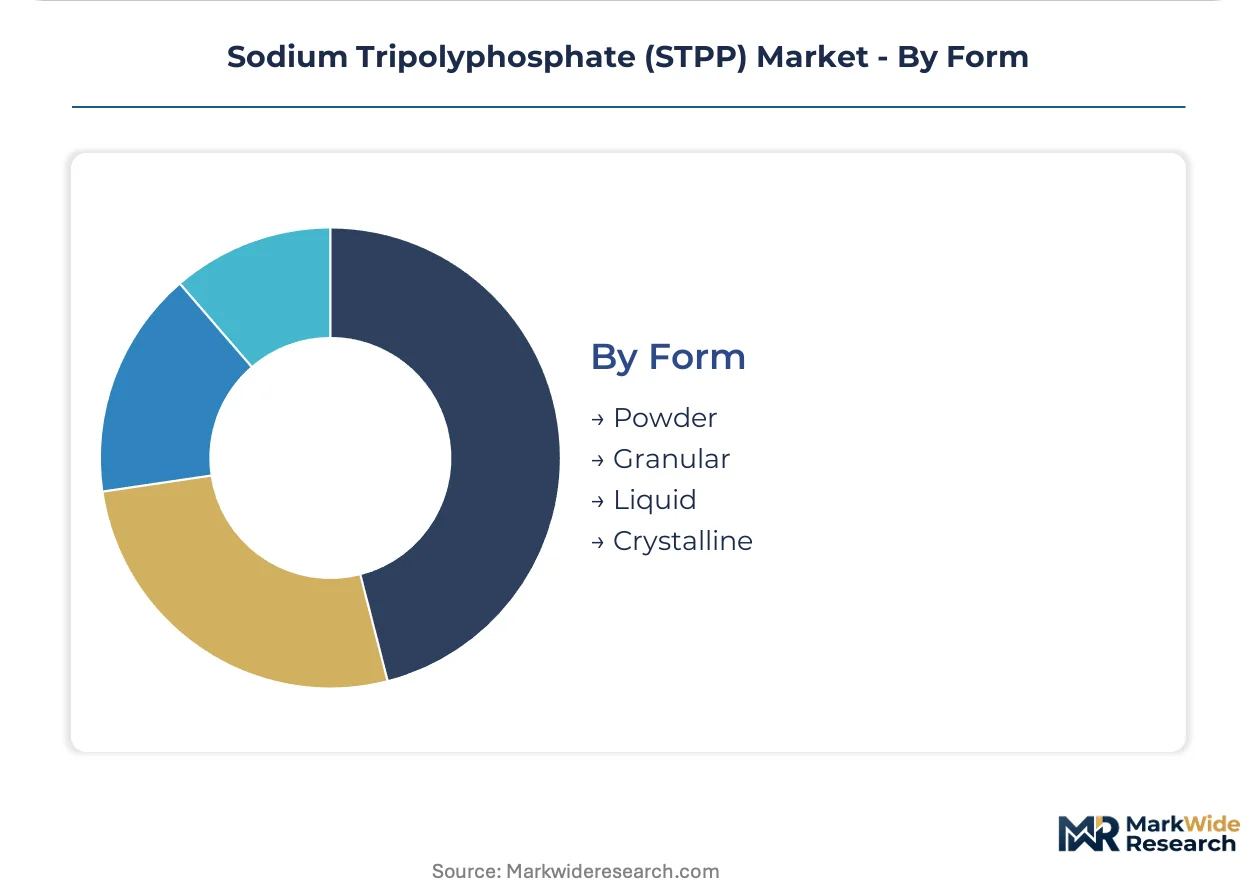
- Powder:Dominant shipment configuration for detergent and food processing applications with established handling infrastructure. Bulk density optimized for containerized ocean freight.
- Granular:Automated dosing system compatibility driving municipal water treatment adoption, requiring flowability specifications for pneumatic conveying systems.
- Liquid:Pre-dissolved formulations for specialized industrial water treatment applications with space-constrained dosing stations.
- Crystalline:High-purity specifications for laboratory and pharmaceutical buffer applications with limited volume throughput.
Powder leads by shipment volume. Granular climbs the fastest on water treatment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of global STPP output while Western consumption faces regulatory compression. East Asian manufacturing clusters absorb phosphate rock from captive mining assets. European and North American demand channels are restructuring around discharge-limited formulations.
China
Detergent manufacturers in the Yangtze River Delta drive granular STPP procurement for automated dosing systems. MEE discharge standards for phosphate-containing effluents raise compliance costs for chemical production clusters. Hubei province anchors thermal dehydration capacity with manufacturers piloting membrane-concentration systems to reduce energy input per ton.
United States
Water treatment facilities in the Great Lakes watershed accelerate STPP procurement ahead of federal mandate expansion. EPA phosphorus loading limits for municipal wastewater force detergent reformulation toward phosphate-free alternatives. Midwestern industrial corridors host legacy powder-optimized infrastructure facing retrofit costs for granular compatibility.
Germany
REACH restrictions on phosphate discharge in European waterways constrain volume growth in core Western markets. ECHA frameworks mandate reformulation timelines for cleaning product manufacturers. The Rhine-Ruhr chemical cluster sustains merchant compounder operations despite raw material access limitations versus integrated Moroccan and Russian producers.
India
Food processing operations require FSSAI-certified STPP inputs with 18-24 month approval timelines freezing capital deployment. BIS certification requirements for food-grade specifications create non-tariff barriers filtering substandard imports. Gujarat and Maharashtra host detergent manufacturing expansion absorbing regional phosphate compounder output.
Brazil
Agricultural runoff applications absorb supply overhang from detergent reformulation in permitted fertilizer formulations. ANVISA frameworks govern food-grade import specifications with compliance burdens similar to FDA structures. São Paulo state anchors cleaning products manufacturing with procurement shifting toward direct phosphate compounder relationships.
Sodium Tripolyphosphate (STPP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and geographic corridors. The market structure stratifies around captive phosphate rock access, thermal dehydration efficiency, and food-grade compliance infrastructure. Three archetypes dominate: integrated miners with backward control into phosphate rock, merchant compounders specializing in granular automation compatibility, and regional traders with logistics specialization for container-direct arrangements. Capacity consolidation and geographic expansion represent the dominant competitive moves as manufacturers seek compliant production bases.
Among integrated producers with captive mining assets, PhosAgro Group exemplifies the cost-leadership archetype through European supply corridor dominance. WENGFU GROUP CO. LTD. occupies a position within the Chinese state-affiliated tier with upstream control over phosphate mining and sulfuric acid production. Hubei Xingfa Chemicals Group Co. Ltd. represents the granular specialization vector for industrial water treatment automation. These three anchors illustrate how competitive positioning diverges across raw material access, process specialization, and end-use certification tiers.
| Leading Market Players |
|---|
| PhosAgro Group |
| Wuhan Inorganic Salt Chemical Plant |
| WENGFU GROUP CO. LTD. |
| Haifa Group |
| Hubei Xingfa Chemicals Group Co. Ltd. |
| Yuntianhua Co., Ltd. |
| Yibin Tianyuan Group |
| Grasim Industries Ltd. |
| Yunphos |
| Others |
Value Network & Pricing Analysis
Detergent manufacturers' unbundling of phosphate procurement from surfactant bundles is forcing supply chain reconfiguration around discrete chemical inputs, compressing margins for bundled suppliers while rewarding dedicated phosphate traders with logistics specialization.
Pricing Analysis
Margin tightening in industrial-grade STPP reflects thermal dehydration energy costs and MEE discharge compliance investments. Three-tier pricing structure across food-grade premium, industrial-grade standard, and fertilizer-grade economy levels stratifies procurement. Cost-down pressure on commodity grades accelerates because Chinese manufacturers with membrane-concentration systems recover process water and reduce per-ton energy input. Large detergent manufacturers with container-direct arrangements exhibit lowest price sensitivity; small compounders dependent on distributor mediation face highest.
Supply Chain Analysis
Food-grade certification timelines extending 18-24 months gate supply chain participation for new entrants. Production concentrates in China, Morocco, and Russia, with captive phosphate rock assets in the latter two anchoring cost leadership. Thermal dehydration capacity draws from phosphate rock, sulfuric acid, and energy inputs. Single-source vulnerability concentrates in Moroccan mining assets controlled by integrated producers. Distribution runs through dedicated phosphate traders with container-direct arrangements displacing regional surfactant bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
STPP supply is tightening around compliant production capacity as MEE discharge standards and food-grade certification timelines freeze capital deployment, propping pricing power for incumbent certified producers.
For Market Incumbents: To counter zeolite substitution in household detergents, deepen backward integration into phosphate mining to sustain cost leadership against merchant compounders, and expand granular STPP capacity for automated water treatment dosing systems where substitution pressure is weakest.
For New Entrants and Emerging Players: Begin with Southeast Asian production bases in Vietnam and Indonesia where discharge regulation is less stringent and ASEAN detergent demand is expanding fastest, targeting container-direct arrangements with unbundled procurement operations at mid-scale detergent manufacturers.
For Investors and Strategic Acquirers: The window for entry favors granular-specialized merchant compounders with water treatment channel relationships and existing MEE compliance infrastructure. Long-term viability hinges on positioning for agricultural runoff applications as detergent bans redirect supply overhang. Watch EPA mandate expansion timeline as inflection indicator for North American water treatment procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphate rock access insulates PhosAgro and WENGFU from raw material volatility in European and Chinese corridors. |
| Membrane-Concentration Deployment | Yangtze River Delta manufacturers reduce thermal dehydration energy input per ton through process water recovery systems. |
| Food-Grade Certification Investment | FSSAI and FDA compliance infrastructure creates 18-24 month barriers that filter substandard Southeast Asian imports from Indian processors. |
| Granular Capacity Expansion | Automated dosing system compatibility captures municipal water treatment procurement ahead of Great Lakes watershed mandate expansion. |
| Joint Venture in Southeast Asia | Vietnam and Indonesia manufacturing partnerships exploit proximity to ASEAN detergent demand with less stringent MEE-equivalent discharge rules. |
Research Methodology
Multi-period observation of phosphate procurement unbundling patterns, MEE discharge compliance cost trajectories, and granular STPP adoption rates anchored the trend analysis, supplemented by interviews with thermal dehydration plant managers, detergent procurement leads, phosphate rock traders, water treatment facility engineers, and food-grade certification consultants. Secondary validation drew from Chinese customs export data, ACC industrial chemical reports, EPA phosphorus loading limit dockets, and SEC 10-K filings of integrated producers. Bottom-up capacity modeling triangulated against top-down demand segmentation across certification tiers.
Input-output matrices mapped thermal dehydration capacity, phosphate rock supply corridors, and end-use demand channels across the projection horizon. Segmentation dimensions modeled included grade tier, end-use application, physical form, and regional production hub. CAGRs derived from slope analysis of historical shipment volumes adjusted for regulatory phase-in schedules. Forecast inputs incorporated MEE enforcement intensity scenarios and zeolite substitution elasticity in household detergent formulations.
Regulatory enforcement delays, faster-than-anticipated zeolite substitution rates, and phosphate rock supply disruptions from mining asset nationalization are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EPA mandate expansion timeline or MEE discharge standard tightening beyond piloted membrane-concentration compliance economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Amyl Nitrite Market
Chemicals
Quaternium-15 Market
Chemicals
Hexachloroethane Market
Chemicals
Sodium Hydride Market
Chemicals
Ethyl Chloride Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Brazil Methanol Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
White Phosphorus Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Chromium Trioxide Market
Chemicals
Phenothiazine Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market