
 3-Iodoaniline Market | 2026-2036
3-Iodoaniline Market Size, Share, and Industry Trends Forecast 2026-2036
3-Iodoaniline Market Outlook
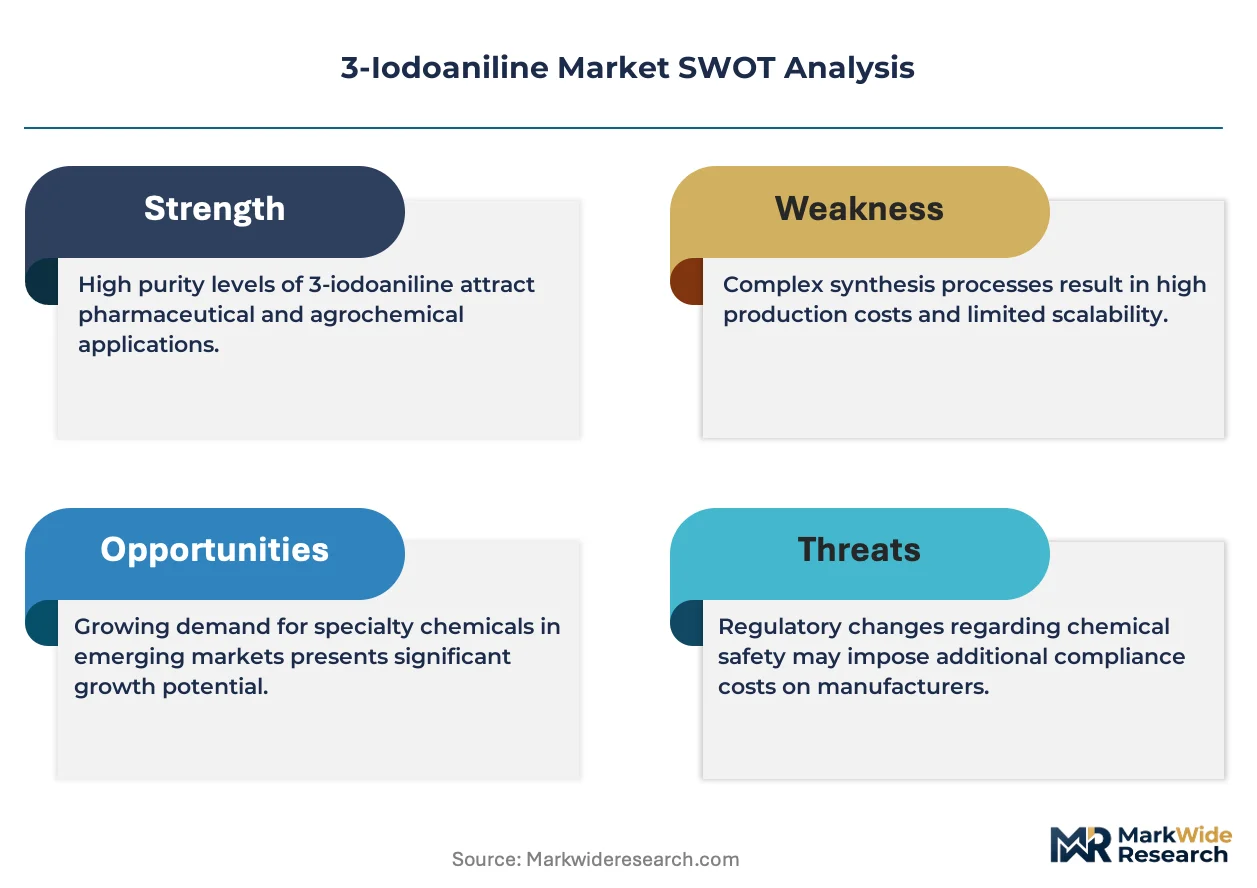
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct manufacturer-to-laboratory channels. Capot Chemical Co. Ltd anchors its position through backward integration into iodine sourcing. TCI Chemicals differentiates via catalog breadth and same-day fulfillment to research laboratories. Apollo Scientific Ltd competes on pharmaceutical-grade certification and UK-based custom synthesis capabilities.
3-Iodoaniline is an aryl halide compound featuring an iodine substituent at the meta position of an aniline ring, typically synthesized through diazotization-iodination of meta-nitroaniline followed by reduction, with purity grades ranging from technical (95%) to pharmaceutical (99.5%+). The compound serves primarily as a halogenated building block for cross-coupling reactions in pharmaceutical and agrochemical synthesis. Purified 3-Iodoaniline commands the dominant share of value as contract manufacturers enforce stricter impurity profiles for GMP-compliant intermediates. Pharmaceutical intermediates represent the fastest-growing application as antibody-drug conjugates and kinase inhibitors drive demand for regioselective halogenated anilines.
EPA oversight of halogenated aromatic imports shapes US market access requirements, while REACH registration in Europe mandates full toxicological dossiers for volumes above one tonne annually. China's NMPA alignment with ICH Q3D guidelines on elemental impurities is forcing export-oriented producers to upgrade purification systems. Stakeholders must monitor evolving dual-use chemical controls, as iodinated aromatics face heightened customs scrutiny in multiple jurisdictions.
Market Dynamics
Contract manufacturers are consolidating iodinated aromatic sourcing around GMP-certified suppliers as pharmaceutical clients enforce ICH Q11 quality-by-design standards for starting materials.
Growth Catalysts
- Antibody-drug conjugate pipelines:Oncology developers require regioselective halogenated anilines for linker-payload attachment chemistry.
- REACH registration deadlines:European importers now demand full substance dossiers, filtering non-compliant Asian suppliers and elevating certified producers.
- Cross-coupling protocol standardization:Palladium-catalyzed Suzuki and Buchwald-Hartwig aminations have institutionalized 3-iodoaniline as a preferred electrophile.
Market Restraints
- Iodine supply volatility:Chilean caliche ore and Japanese brine extraction dominate raw material sourcing, exposing producers to geopolitical and climatic disruptions.
- Substitution by brominated analogs:Cost-sensitive agrochemical formulators increasingly specify 3-bromoaniline for non-pharmaceutical applications.
- Dual-use chemical scrutiny:US Customs and Border Protection has heightened inspection protocols for iodinated aromatics under precursor chemical controls.
Strategic Opportunities
- India's API manufacturing expansion:The country's PLI scheme for bulk drugs is attracting iodination capacity investments to serve domestic and export markets.
- Flow chemistry adoption:Continuous diazotization-iodination systems promise yield improvements and reduced waste profiles for high-purity grades.
- Research chemical direct channels:Same-day fulfillment platforms are capturing share from traditional distributor networks in academic and biotech procurement.
Industry Challenges
- Specialized iodination expertise shortage:Mastery of controlled exothermic diazotization requires experienced process chemists in short supply across contract manufacturing organizations.
- Elemental impurity validation:ICP-MS testing for arsenic, cadmium, and mercury to meet ICH Q3D specifications extends batch release timelines by two to four weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Iodoaniline Market |
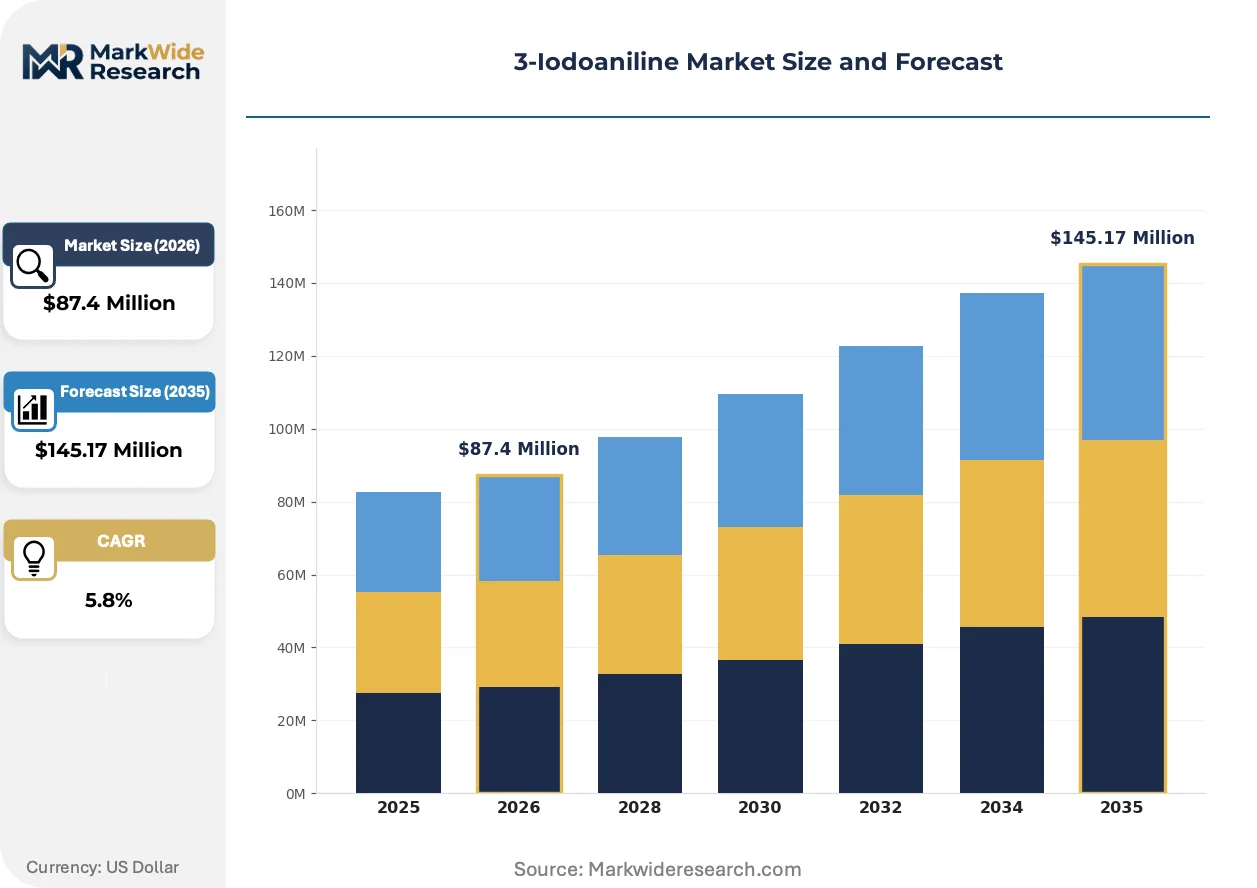
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude 3-Iodoaniline, Purified 3-Iodoaniline, Powder, Liquid, Stabilized Solution Application: Pharmaceutical Intermediates, Dye Manufacturing, Agrochemical Production, Photographic Chemicals, Polymer Additives End User: Fine Chemical Producers, Research Laboratories, Specialty Chemical Manufacturers, Custom Synthesis Providers, Academic Institutions Packaging Type: Drums, Bottles, Bulk Bags, Carboys, Intermediate Bulk Containers |
| Companies Covered | Capot Chemical Co. Ltd, Simagchem Corp, Thermo Scientific Chemicals, Hubei Shishun Biotechnology Co., Ltd, Shaanxi Dideu Medichem Co. Ltd, TCI Chemicals, Apollo Scientific Ltd, Career Henan Chemical Co. Ltd, Henan Tianfu Chemical Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Iodoaniline Market Strategic Shifts
Process intensification and regulatory data transparency are compressing the gap between laboratory-scale iodination and commercial GMP production.
Continuous flow reactor technology is migrating from academic demonstration to commercial deployment. European fine chemical manufacturers are retrofitting batch diazotization lines with microreactor systems. This migration from conventional stirred-tank operations is enabling real-time reaction monitoring and tighter temperature control for impurity-sensitive pharmaceutical grades.
China's NMPA alignment with ICH Q3D guidelines is forcing purification upgrades. Export-oriented producers in Shandong province are installing multi-stage crystallization and activated carbon treatment systems. Pharmaceutical intermediates destined for US FDA and EMA filings now require validated residual solvent and elemental impurity specifications.
Research procurement patterns are fragmenting across channel types. Biotech startups and university labs are bypassing regional distributors for manufacturer-direct e-commerce platforms. This channel compression is most pronounced in North America and Western Europe, where same-day delivery expectations have normalized for catalog chemicals.
3-Iodoaniline Market Segmentation
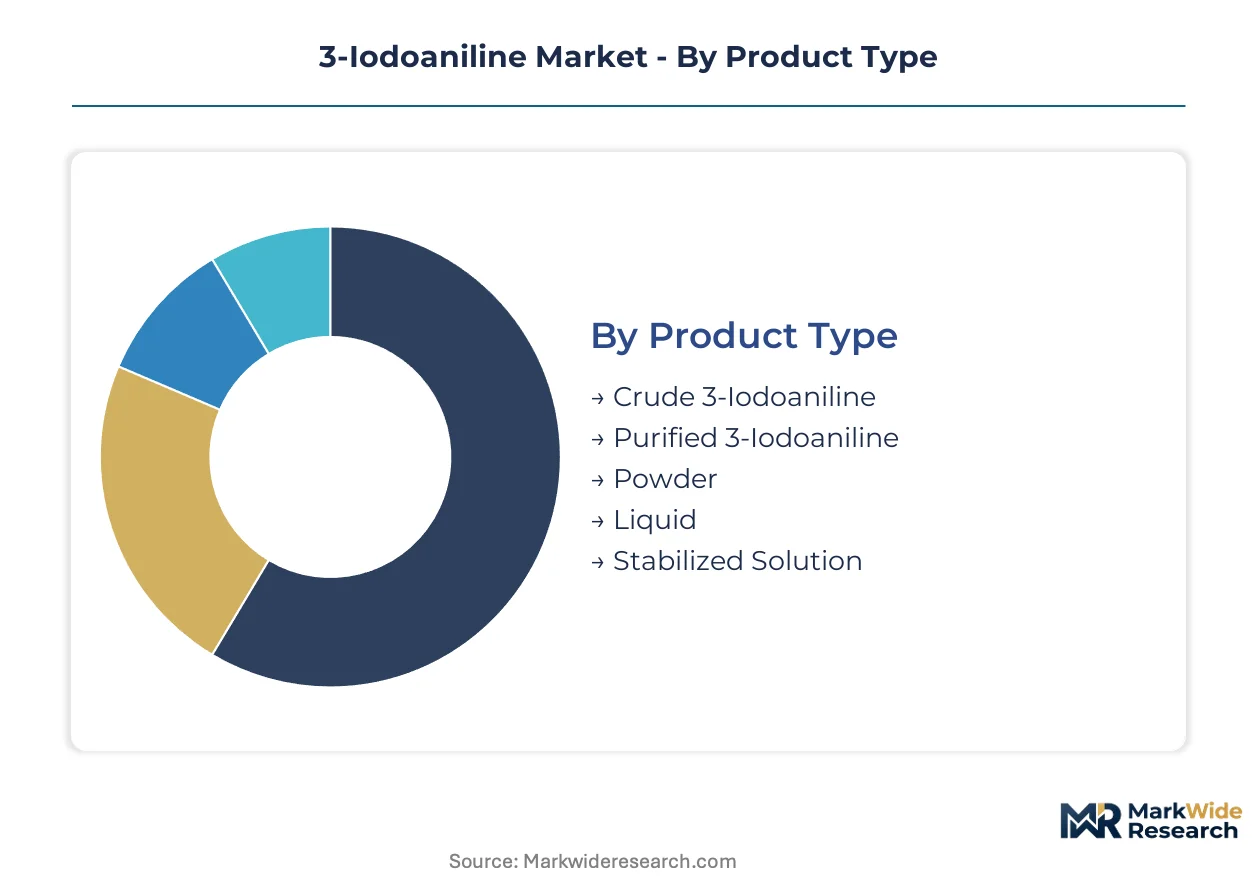
Segmentation in the 3-iodoaniline market reflects divergent purity requirements and procurement patterns across pharmaceutical, agrochemical, and research end-uses. Contract manufacturers enforce strict impurity profiles that fragment demand across technical and pharmaceutical-grade tiers. Packaging and logistics configurations further stratify supply chains serving bulk chemical producers versus laboratory-scale consumers.
Product Type:
Mature grades dominate volume flows while emerging purification technologies reshape value capture in high-specification segments.
- Crude 3-Iodoaniline:Technical-grade material at 95% purity serves as feedstock for downstream purification or non-critical agrochemical applications. Demand concentrates in Shandong province manufacturing clusters where local formulators tolerate higher impurity loads for cost-sensitive herbicide synthesis.
- Purified 3-Iodoaniline:Pharmaceutical-grade specification at 99.5%+ purity enables GMP-compliant cross-coupling reactions. US FDA and EMA filing requirements for antibody-drug conjugate linkers are concentrating demand with certified producers operating ICP-MS validated batch release protocols.
- Powder:Solid form factor suits long-haul shipping and ambient storage conditions for contract manufacturing organization procurement.
- Liquid:Dissolved preparation eliminates dust exposure hazards during transfer operations in continuous flow reactor setups.
- Stabilized Solution:Antioxidant-doped formulation extends shelf life for research laboratory inventory management.
Purified 3-Iodoaniline handles the majority of throughput; pharmaceutical intermediates are expanding most quickly on share.
Application:
Cost tier stratification separates premium pharmaceutical specifications from economy agrochemical grades.
- Pharmaceutical Intermediates:Regioselective halogenated aniline building blocks enable Suzuki and Buchwald-Hartwig aminations in kinase inhibitor synthesis. Oncology pipeline expansion at Boston and San Francisco biotech clusters is accelerating procurement of GMP-certified material.
- Dye Manufacturing:Azo coupling reactions consume technical-grade material for pigment intermediate production. Textile hub demand in Ahmedabad and Surat drives volume procurement through Indian fine chemical distributors.
- Agrochemical Production:Herbicide and fungicide formulators specify 3-bromoaniline substitution where cost constraints override iodine reactivity advantages.
- Photographic Chemicals:Legacy silver halide emulsion chemistry maintains niche consumption in specialty film manufacturing.
- Polymer Additives:Flame retardant and stabilizer applications absorb technical-grade volumes in compounding operations.
Pharmaceutical intermediates handle the majority of throughput; agrochemical production is gaining share fastest amid India's PLI scheme expansion.
End User:
Customer type fragmentation separates bulk chemical procurement from research-scale fulfillment channels.
- Fine Chemical Producers:Multi-tonne consumers operate dedicated iodination capacity or source through long-term supply agreements with Shandong and Hubei manufacturers.
- Research Laboratories:Sub-kilogram demand for method development and route scouting flows through manufacturer-direct e-commerce platforms with same-day fulfillment expectations.
- Specialty Chemical Manufacturers:Mid-scale consumers balance catalog availability against custom synthesis flexibility for proprietary intermediates.
- Custom Synthesis Providers:CDMOs enforce ICH Q11 quality-by-design standards that filter supplier qualification to GMP-certified producers.
- Academic Institutions:Grant-funded procurement operates through institutional purchasing agreements with catalog chemical distributors.
Fine chemical producers handle the majority of throughput; research laboratories are climbing the fastest on share through channel compression.
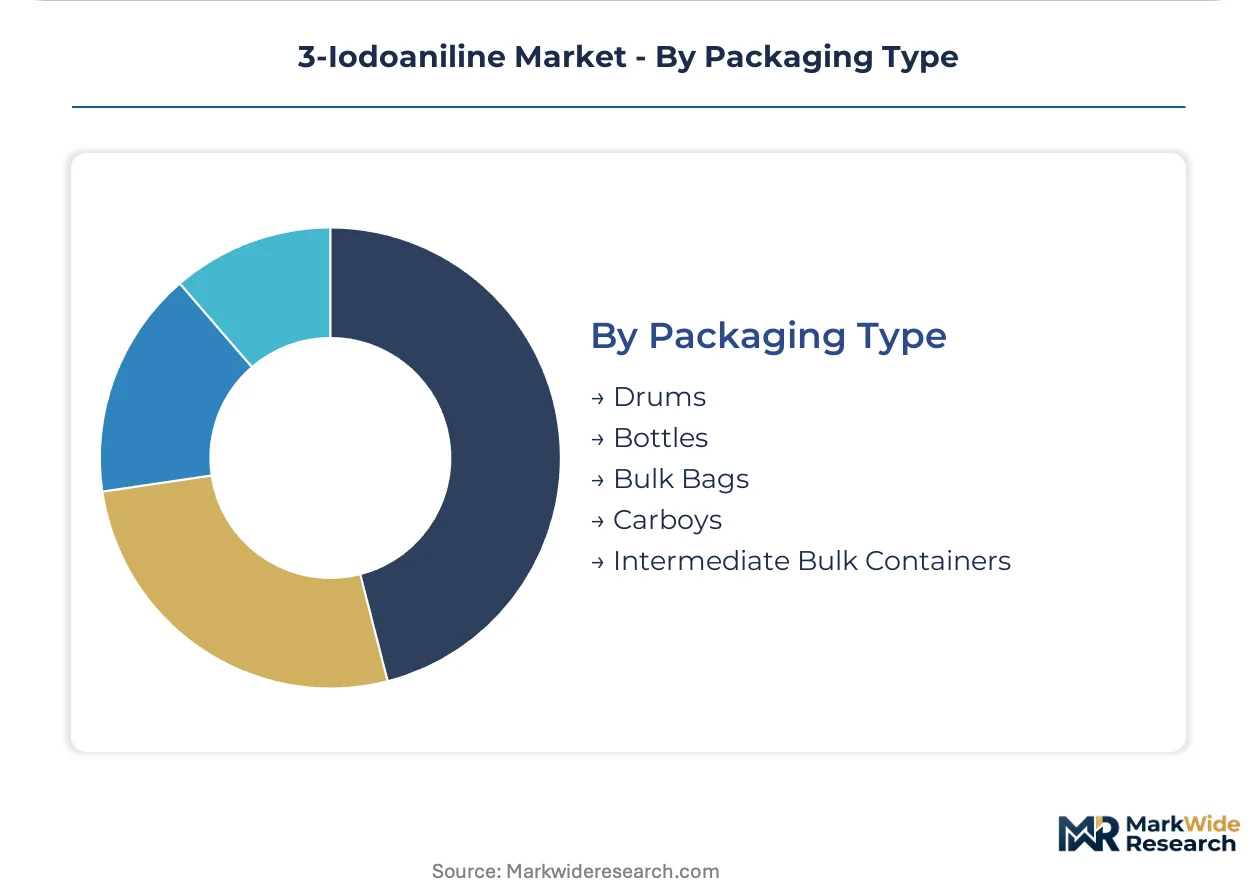
Packaging Type:
Supply concentration in drum and bulk configurations reflects production-scale chemical movement while emerging formats serve laboratory decentralization.
- Drums:Standard 200-liter steel containment dominates intercontinental shipment of liquid and powder grades to contract manufacturing sites.
- Bottles:Amber glass or fluoropolymer containers preserve stability for gram-scale research chemical distribution.
- Bulk Bags:Flexible intermediate bulk containers reduce per-kilogram logistics cost for powder shipments to agrochemical formulators.
- Carboys:Polypropylene vessels suit corrosive liquid handling in pilot plant environments.
- Intermediate Bulk Containers:Reusable totes enable closed-loop supply arrangements between certified producers and pharmaceutical API manufacturers.
Drums handle the majority of throughput; bottles are expanding most quickly on share through direct-to-laboratory channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for bulk drugs is redirecting iodination capacity investments toward pharmaceutical-grade production. China's NMPA alignment with ICH Q3D guidelines is forcing purification system upgrades across Shandong and Hubei manufacturing clusters. These policy shifts are redistributing competitive positioning among Asia-Pacific producers while tightening regulatory entry barriers in Western markets.
China
Antibody-drug conjugate linker chemistry for export markets drives demand for GMP-certified 3-iodoaniline. NMPA enforcement of ICH Q3D elemental impurity standards is compelling producers to install ICP-MS validated batch release protocols. Shandong province manufacturing clusters are retrofitting diazotization lines with multi-stage crystallization systems to meet US FDA and EMA filing requirements.
United States
Oncology biotech clusters in Boston and San Francisco are accelerating procurement of regioselective halogenated anilines for kinase inhibitor pipelines. EPA oversight of halogenated aromatic imports shapes customs clearance protocols and purity documentation requirements. Texas and New Jersey chemical distribution hubs are consolidating sourcing around REACH-registered suppliers to mitigate supply interruption risks.
India
The PLI scheme for bulk drugs is attracting iodination capacity investments to serve domestic API manufacturing and export markets. CDSCO alignment with ICH Q11 quality-by-design standards is filtering supplier qualification toward GMP-certified producers. Gujarat and Maharashtra fine chemical corridors are expanding diazotization capacity to capture pharmaceutical intermediate demand from European and North American clients.
Germany
EMA filing requirements for antibody-drug conjugate starting materials are concentrating demand with certified producers operating validated impurity profiles. REACH registration mandates for volumes above one tonne annually are elevating compliance costs and filtering non-compliant Asian suppliers. Bavaria-based fine chemical manufacturers are retrofitting batch operations with continuous flow microreactor systems for pharmaceutical-grade output.
United Kingdom
Custom synthesis providers serving oncology developers are enforcing ICH Q11 standards that limit qualified supplier pools for halogenated aromatic starting materials. MHRA post-Brexit regulatory autonomy maintains alignment with EMA purity specifications for imported aryl halides. Manchester and Cambridge research corridors are bypassing regional distributors for manufacturer-direct e-commerce platforms with same-day fulfillment capabilities.
3-Iodoaniline Market Competitive Environment
On the supply side, the industry is consolidating around GMP-certified producers capable of validated elemental impurity testing and ICH Q3D compliance documentation. Three strategic archetypes dominate: vertically integrated iodine processors controlling raw material sourcing, catalog chemical distributors with same-day fulfillment infrastructure, and custom synthesis specialists offering pharmaceutical-grade certification. Competitive moves center on backward integration into iodine supply chains and flow chemistry technology licensing for continuous diazotization operations.
Among China-based producers, Capot Chemical Co. Ltd and Hubei Shishun Biotechnology Co., Ltd exemplify the integrated manufacturing archetype with positions in Shandong and Hubei province clusters. TCI Chemicals occupies the catalog distribution tier with research-scale fulfillment capabilities. These three companies represent contrasting strategic positions: captive iodine sourcing versus regional manufacturing concentration versus direct-to-laboratory channel control.
| Leading Market Players |
|---|
| Capot Chemical Co. Ltd |
| Simagchem Corp |
| Thermo Scientific Chemicals |
| Hubei Shishun Biotechnology Co., Ltd |
| Shaanxi Dideu Medichem Co. Ltd |
| TCI Chemicals |
| Apollo Scientific Ltd |
| Career Henan Chemical Co. Ltd |
| Henan Tianfu Chemical Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Shandong province manufacturing clusters anchor global 3-iodoaniline capacity, and their diazotization-iodination output volumes directly determine pricing leverage for downstream pharmaceutical and agrochemical buyers. Contract manufacturers sourcing GMP-certified grades face concentrated supplier power, while technical-grade purchasers retain more negotiating room through fragmented regional distributors.
Pricing Analysis
Certification level creates the primary spread, with pharmaceutical-grade material commanding substantial premiums over technical grades due to ICH Q3D elemental impurity validation and ICP-MS batch release protocols. Three-tier pricing structure across GMP-certified, research-grade, and technical-economy levels reflects purity differential and documentation burden. Cost compression in the technical tier intensifies because agrochemical formulators increasingly substitute 3-bromoaniline where iodine reactivity advantages do not justify cost. CDMOs and API manufacturers show least price sensitivity, while regional dye and pigment producers drive hardest bargain on volume contracts.
Supply Chain Analysis
Extended payment terms from large pharmaceutical buyers strain working capital for mid-tier producers, accelerating consolidation toward iodine-backward-integrated players with balance sheet depth. Manufacturing concentrates in China, India, and Germany, with Shandong and Hubei provinces hosting diazotization capacity while Gujarat and Bavaria add pharmaceutical-grade finishing. Raw material sourcing draws from Chilean caliche ore and Japanese brine extraction for iodine, plus nitrobenzene derivatives from petrochemical feedstocks. Single-source vulnerability runs through Chilean iodine supply exposed to climatic and geopolitical disruption. Distribution runs through manufacturer-direct channels for research quantities and long-term offtake agreements for bulk pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mastery of controlled exothermic diazotization represents the critical capability gap, with experienced process chemists in short supply across contract manufacturing organizations and GMP-certified producers. This scarcity concentrates margin capture with incumbents who have secured specialized talent and validated purification infrastructure.
For Market Incumbents: Build regulatory-data moats by investing in REACH dossier completeness and ICH Q11 quality-by-design documentation ahead of European registration deadlines. Secure backward integration into iodine sourcing to buffer Chilean supply volatility, and expand flow chemistry licensing partnerships to differentiate yield efficiency against batch competitors. Threat from brominated analog substitution in cost-sensitive segments demands premium-grade certification investment to maintain pharmaceutical lock-in. For New Entrants and Emerging Players: Research-scale direct-to-laboratory fulfillment in North American and Western European biotech corridors represents the most penetrable entry point, bypassing entrenched distributor relationships. India's PLI scheme-attracted API manufacturing expansion offers second white-space opportunity for pharmaceutical-grade iodination capacity serving export markets. Go-to-market angle should emphasize same-day fulfillment platforms with validated elemental impurity documentation to capture channel-compression momentum. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because regulatory compliance burdens and iodine supply concentration favor scaled, integrated producers over fragmented competitors. Acquisition target archetype: mid-cap manufacturers with captive iodine sourcing and existing GMP certification infrastructure. Signal to watch is NMPA enforcement timeline for ICH Q3D alignment in China, which will force purification capex and filter sub-scale producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iodine Sourcing | Captive supply of Chilean and Japanese iodine raw material buffers price volatility and secures batch continuity for pharmaceutical clients. |
| Flow Chemistry Technology Licensing | Continuous diazotization-iodination microreactor deployment reduces waste profiles and yield variance for high-purity GMP grades. |
| REACH Registration Completion | Full toxicological dossiers for European volumes above one tonne annually filter non-compliant Asian competitors from EU market access. |
| Direct-to-Laboratory E-Commerce Platform | Same-day fulfillment capabilities capture procurement share from traditional distributors in Boston and San Francisco biotech clusters. |
| ICH Q3D Purification System Upgrade | Multi-stage crystallization and activated carbon treatment installations meet US FDA and EMA filing requirements for antibody-drug conjugate linkers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, fine chemical industry association reports, and regulatory filing databases. Process chemists at iodination facilities, procurement leads at pharmaceutical CDMOs, distribution channel partners, and technical R&D directors contributed stakeholder perspective. Bottom-up triangulation from production capacity and batch release volumes converged with top-down demand estimation from pharmaceutical pipeline analysis and agrochemical formulation trends.
Forecast inputs include grade tier stratification, end-use industry application, packaging format configuration, and regional production hub dynamics across the analysis window. CAGRs derive from segmented volume projections calibrated to purity-grade demand shifts and regulatory compliance timeline impacts. Iodine supply volatility indices and pharmaceutical pipeline advancement rates inform scenario-weighted outputs.
Practitioners should monitor NMPA enforcement intensity, REACH registration deadline compliance rates, and brominated substitution adoption in agrochemical segments for early signals. Forecasts embed assumptions regarding continued oncology pipeline expansion and sustained iodine supply concentration. Macroeconomic contraction in pharmaceutical R&D spending, regulatory timeline acceleration, or breakthrough bromination reactivity improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Benzenoid Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Methylamines Market
Chemicals
Industrial Odor Management Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Isoamyl Acetate Market
Chemicals
Pyrimidine Market
Chemicals
Triethylenediamine Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Di Nitro Toluene Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Formalin Market
Chemicals
Stimulation Materials Market
Chemicals
Global Inorganic Fluorides Market