
 Glycyrrhizic Acid Glycosides Market | 2026-2036
Glycyrrhizic Acid Glycosides Market Size, Share, and Industry Trends Forecast 2026-2036
Glycyrrhizic Acid Glycosides Market Insights
Synthetic surfactants in personal care formulations is decoupling from premium positioning as glycyrrhizic acid glycosides demonstrate comparable emulsification with superior skin tolerability. MAFCO Worldwide LLC leverages captive licorice root sourcing from Central Asian growing regions to secure raw material continuity. C.E. Roeper GmbH anchors its competitiveness in pharmaceutical-grade refinement, sustaining batch-to-batch consistency that meets European Pharmacopoeia monograph requirements. Maruzen Pharmaceuticals Co., Ltd differentiates through fermentation-derived glycyrrhizin variants that reduce agricultural land dependency.
Glycyrrhizic acid glycosides comprise triterpenoid saponins extracted from Glycyrrhiza glabra root, typically standardized to 90-98% purity for pharmaceutical applications and 20-26% for cosmetic use, functioning primarily as anti-inflammatory, skin-conditioning, and flavor-masking agents. The personal care application segment leads current value generation due to formulator preference for natural-origin brightening agents replacing hydroquinone derivatives. Sodium glycyrrhizate is gaining fastest within product types as salt forms improve water solubility for beverage and oral care applications. Pharmaceutical-grade pure glycyrrhizic acid commands the deepest margin pool owing to compendial testing burdens and limited qualified suppliers.
EMA's quality guidelines for herbal medicinal products and REACH registration requirements for imported botanical extracts jointly elevate compliance costs for non-European suppliers seeking European market access. China's NMPA implementation of revised botanical drug master file standards is reshaping documentation expectations for glycyrrhizin-containing APIs entering clinical trials. The US FDA GRAS notification pathway for glycyrrhizic acid in food applications remains underutilized relative to its established safety record. Stakeholders must monitor convergence between cosmetic ingredient transparency mandates and pharmaceutical-grade certification to capture cross-sector premium positioning.
Market Dynamics
China's NMPA tightening of botanical extract purity standards is redirecting procurement toward certified European suppliers, concentrating demand in Germany's specialized phytochemical processing corridor around Hamburg and reshaping competitive positioning across the value chain.
Growth Catalysts
- Cosmetic Formulation Shift:Skin-brightening product lines are replacing hydroquinone derivatives with glycyrrhizic acid glycosides as the primary active, driven by formulator preference for natural-origin agents with comparable efficacy and superior tolerability profiles.
- REACH Registration Pathway:European chemical registration requirements for imported botanical extracts are elevating compliance barriers that favor established European refiners with existing dossiers and analytical capabilities.
- Fermentation-Derived Variants:Bioprocess engineering advances are reducing agricultural land dependency for glycyrrhizin production, enabling supply security decoupled from licorice root harvest volatility in Central Asian growing regions.
Market Restraints
- Input Cost Volatility:Licorice root supply fluctuations in Kazakhstan and Uzbekistan create raw material price instability that compresses margins for non-vertically integrated processors lacking captive sourcing arrangements.
- Compendial Testing Burden:European Pharmacopoeia monograph requirements for pharmaceutical-grade glycyrrhizic acid impose analytical cost structures that limit qualified supplier pools and sustain premium pricing tiers.
- Synthetic Surfactant Substitution:Petroleum-derived emulsifiers retain cost advantages in mass-market personal care, constraining glycyrrhizic acid glycoside penetration outside premium positioning segments.
Strategic Opportunities
- Beverage Application Expansion:Sodium glycyrrhizate salt forms with improved water solubility are opening formulation opportunities in functional beverages and oral care products previously inaccessible to standard glycyrrhizic acid.
- US FDA GRAS Pathway:The underutilized GRAS notification pathway for glycyrrhizic acid in food applications represents a regulatory tailwind for suppliers seeking to expand beyond cosmetic and pharmaceutical segments.
- Cross-Sector Certification Convergence:Cosmetic ingredient transparency mandates are aligning with pharmaceutical-grade certification requirements, creating premium positioning opportunities for dual-compliant suppliers.
Industry Challenges
- Analytical Talent Scarcity:Batch-to-batch consistency for European Pharmacopoeia compliance requires specialized phytochemical analysts, with skill shortages concentrated in quality control functions.
- Documentation Reconfiguration:China's revised botanical drug master file standards are forcing API suppliers to rebuild regulatory dossiers, extending certification timelines for clinical trial entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycyrrhizic Acid Glycosides Market |
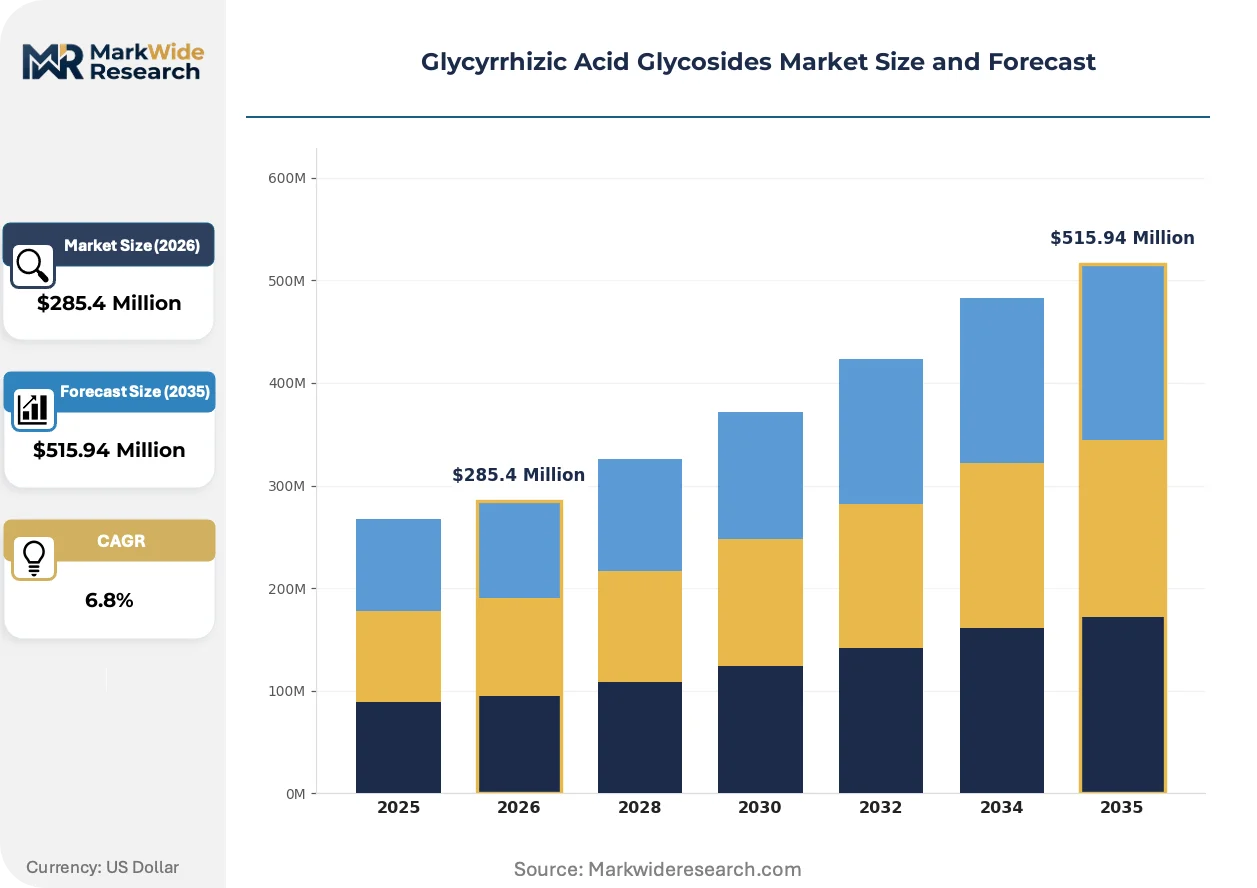
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Glycyrrhizic Acid, Sodium Glycyrrhizate, Potassium Glycyrrhizate, Glycyrrhizin Application: Personal Care, Food & Beverage, Pharmaceuticals, Dietary Supplements End User: Cosmetics Manufacturers, Food Manufacturers, Pharmaceutical Companies, Nutraceutical Firms Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | MAFCO Worldwide LLC, C.E. Roeper GmbH, Norevo GmbH, F&C Licorice Ltd, Maruzen Pharmaceuticals Co., Ltd, Glycyrrhiza Glabra Co., Ltd, Zagros Licorice Co., Shaanxi Fujie Pharmaceutical Co., Ltd, Indena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycyrrhizic Acid Glycosides Market Trends and Innovations
Fermentation technology, regulatory documentation convergence, and procurement model evolution are collectively restructuring how glycyrrhizic acid glycosides are produced, certified, and sourced across end-use verticals.
Bioprocess-derived glycyrrhizin variants are expanding into pharmaceutical and cosmetic manufacturing as an alternative to agricultural extraction. Maruzen Pharmaceuticals and specialized fermentation houses are scaling tank-based production to reduce dependency on Central Asian licorice root cultivation. This technology is expanding into supply security strategies for manufacturers seeking batch consistency independent of harvest cycles and climate variability.
EMA quality guidelines for herbal medicinal products are tightening documentation requirements for botanical drug substances entering European clinical trials. The industrial consequence is a documentation burden that favors established European refiners with existing quality management systems over Asian extract importers. Pharmaceutical-grade glycyrrhizic acid API suppliers are responding by pre-building European Pharmacopoeia-compliant master files ahead of NMPA alignment pressures.
Direct sourcing relationships between cosmetic formulators and certified European refiners are displacing traditional distributor intermediaries in high-purity segments. Hamburg's phytochemical processing cluster is capturing concentrated procurement volume as brand owners seek supply chain transparency and batch traceability. This pattern is most visible in German and French skin-brightening product lines where ingredient storytelling drives consumer preference.
Glycyrrhizic Acid Glycosides Market Segmentation
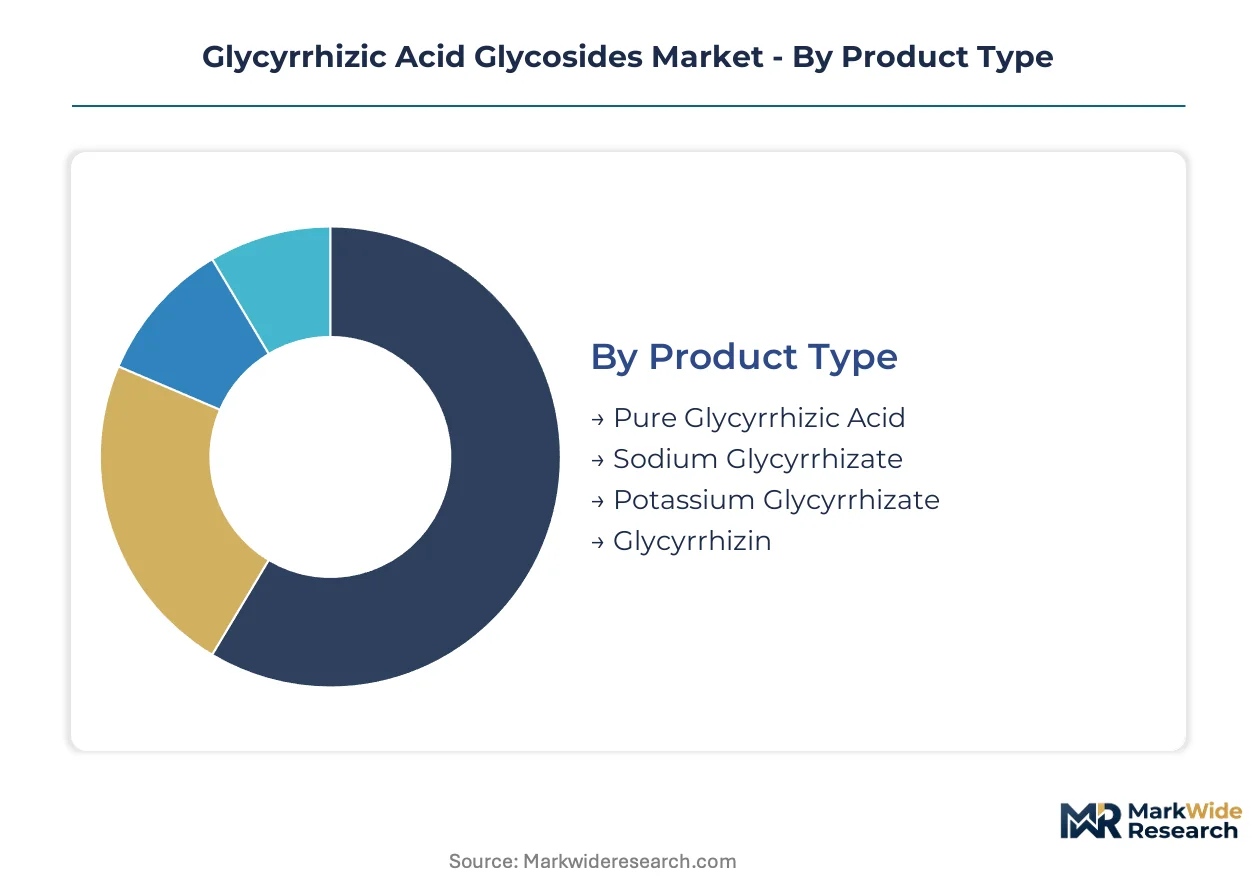
Segmentation in glycyrrhizic acid glycosides reveals how purity grades and salt forms align with divergent regulatory burdens and formulation requirements across end-use verticals. The market fragments along technical specifications that determine whether glycosides function as standalone actives or embedded functional ingredients.
Product Type:
Integration depth varies sharply across salt and acid forms, with standalone pharmaceutical applications demanding compendial-grade purity while embedded cosmetic formulations tolerate broader specification ranges.
- Pure Glycyrrhizic Acid:Pharmaceutical-grade material standardized to 90-98% purity with full European Pharmacopoeia monograph compliance. Demand concentrates in German and Swiss API manufacturing corridors where batch-to-batch consistency commands premium positioning against limited qualified supplier pools.
- Sodium Glycyrrhizate:Salt form engineered for enhanced water solubility, enabling beverage and oral care formulations previously inaccessible to standard glycyrrhizic acid. Formulators in Japan and South Korea are expanding procurement volumes for functional drink applications.
- Potassium Glycyrrhizate:Alternative salt variant with modified ionic properties for specialized cosmetic emulsions.
- Glycyrrhizin:Crude extract fraction containing 20-26% glycyrrhizic acid content for cost-sensitive flavor-masking applications.
Pure Glycyrrhizic Acid leads volumes today; Sodium Glycyrrhizate is gaining share fastest.
Application:
Cost tier stratification separates premium-positioned personal care actives from commodity-grade food and beverage flavoring applications.
- Personal Care:Skin-brightening formulations leverage glycyrrhizic acid glycosides as hydroquinone replacements, with German and French cosmetics manufacturers driving specification standards for natural-origin tolerability claims.
- Pharmaceuticals:Anti-inflammatory and hepatoprotective APIs require full drug master file documentation, with EMA quality guidelines and China's NMPA standards imposing parallel compliance burdens.
- Food & Beverage:Flavor-masking and sweetening functions in functional beverages utilize GRAS-eligible sodium glycyrrhizate at lower purity thresholds.
- Dietary Supplements:Encapsulated licorice root extracts for adrenal support and digestive health applications.
Personal Care dominates revenue contribution; Pharmaceuticals sustains the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding full supply chain traceability while food manufacturers prioritize volume pricing.
- Cosmetics Manufacturers:Direct sourcing relationships with Hamburg-area phytochemical refiners are displacing traditional distributor channels as brand owners seek ingredient storytelling transparency for consumer-facing labels.
- Pharmaceutical Companies:Compendial-grade API procurement requires pre-qualified suppliers with existing European Pharmacopoeia master files, limiting vendor pools.
- Food Manufacturers:Sodium glycyrrhizate volumes for beverage applications are scaling through fermentation-derived supply to reduce agricultural dependency.
- Nutraceutical Firms:Standardized extract procurement for capsule and tablet formulations with moderate purity requirements.
Cosmetics Manufacturers anchor current demand; Pharmaceutical Companies are deepening specification requirements fastest.
Distribution Channel:
Supply concentration favors direct technical relationships in high-purity segments while commodity grades flow through conventional wholesale channels.
- Direct Sales:Pharmaceutical and premium cosmetic applications require technical service support, specification negotiation, and batch certification documentation that mandates manufacturer-direct procurement.
- Specialty Stores:Small-batch cosmetic formulators and regional nutraceutical compounders source through ingredient-focused distributors with quality documentation capabilities.
- Online Retail:Research-grade and small-volume cosmetic raw material procurement is shifting to digital platforms for specification comparison.
- Supermarkets:Mass-market food and beverage applications utilize conventional food ingredient distribution networks.
Direct Sales commands the highest value concentration; Specialty Stores are expanding technical service capabilities most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg's phytochemical processing corridor anchors procurement concentration for glycyrrhizic acid glycosides, with European refiners capturing redirected demand from Chinese manufacturers facing tightened NMPA standards. The geographic distribution reflects divergent regulatory compliance capabilities and raw material sourcing strategies across major consuming markets.
Germany
Pharmaceutical-grade refinement for European Pharmacopoeia compliance drives demand concentration in the Hamburg processing cluster. EMA quality guidelines for herbal medicinal products elevate documentation requirements that favor established domestic refiners. C.E. Roeper GmbH anchors batch-to-batch consistency capabilities that meet compendial testing burdens for API manufacturing.
China
Domestic consumption of licorice root extracts faces procurement redirection as NMPA botanical drug master file standards tighten purity documentation. The regulator's revised standards force API suppliers to rebuild regulatory dossiers, extending certification timelines. Shaanxi Fujie Pharmaceutical Co., Ltd exemplifies domestic processors navigating documentation reconfiguration pressures.
Japan
Fermentation-derived glycyrrhizin variants reduce agricultural land dependency for manufacturers seeking supply security decoupled from harvest volatility. PMDA alignment with ICH quality guidelines shapes documentation expectations for botanical drug substances entering clinical trials. Maruzen Pharmaceuticals Co., Ltd occupies a position within bioprocess engineering advances for tank-based production scaling.
United States
GRAS notification pathway utilization for food applications remains underdeveloped relative to established safety records, creating regulatory expansion opportunities. FDA oversight of botanical ingredient labeling drives formulator preference for certified supply chain transparency. MAFCO Worldwide LLC leverages Central Asian captive sourcing to secure raw material continuity for North American supply.
France
Skin-brightening cosmetic formulations drive specification standards for natural-origin tolerability claims in premium personal care lines. ANSM oversight of cosmetic ingredient safety aligns with emerging transparency mandates that favor pharmaceutical-grade certification. Direct sourcing relationships between Paris-based formulators and Hamburg-area refiners displace traditional distributor intermediaries.
Glycyrrhizic Acid Glycosides Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation technology scales and European refiners absorb redirected Chinese procurement. The vendor base stratifies across three tiers: pharmaceutical-grade specialists with compendial dossiers, fermentation-derived variant producers reducing agricultural dependency, and root-extraction processors with captive Central Asian sourcing. Strategic archetypes include European pharmacopoeia-compliant refiners, bioprocess engineering specialists, and vertically integrated licorice root processors. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers seek regulatory arbitrage and supply security.
Among European specialists, C.E. Roeper GmbH and Norevo GmbH exemplify the pharmaceutical-grade refinement archetype with Hamburg-cluster positioning for EMA-aligned quality systems. MAFCO Worldwide LLC represents the captive-sourcing model with Central Asian root supply integration, while Maruzen Pharmaceuticals Co., Ltd anchors the fermentation-derived variant segment with bioprocess engineering capabilities. Indena occupies a position within botanical extract specialists serving cosmetic and pharmaceutical formulators with standardized phytochemical supply. Zagros Licorice Co. and F&C Licorice Ltd sit within root-extraction processors dependent on agricultural harvest cycles.
| Leading Market Players |
|---|
| MAFCO Worldwide LLC |
| C.E. Roeper GmbH |
| Norevo GmbH |
| F&C Licorice Ltd |
| Maruzen Pharmaceuticals Co., Ltd |
| Glycyrrhiza Glabra Co., Ltd |
| Zagros Licorice Co. |
| Shaanxi Fujie Pharmaceutical Co., Ltd |
| Indena |
| Others |
Pricing and Supply Chain Analysis
Licorice root futures volatility in Kazakhstan and Uzbekistan cascades through extraction, refinement, and formulation stages, concentrating pricing power with Hamburg-area processors commanding European Pharmacopoeia certification premiums while compressing margins for non-captive Asian suppliers.
Pricing Analysis
Input-cost pass-through from Central Asian agricultural harvests creates three-tier pricing stratification across pharmaceutical-grade, cosmetic-grade, and flavor-masking tiers. Price differentiation hinges on European Pharmacopoeia compliance burden and volume scale, with certification investment acting as the dominant margin driver. Pricing pressure intensifies in standard cosmetic grades as fermentation-derived variants displace agricultural extraction. Food manufacturers exhibit highest price sensitivity due to GRAS-eligible purity thresholds, while pharmaceutical API buyers accept premium positioning for batch-to-batch consistency.
Supply Chain Analysis
Analytical talent scarcity in German and Swiss quality control functions constrains Hamburg-cluster expansion despite surging procurement redirection from Chinese manufacturers facing NMPA documentation burdens. Supply concentration centers on Germany, China, and Japan, with raw material dependencies on Kazakhstan and Uzbekistan licorice root cultivation and fermentation feedstock streams. Single-source vulnerability runs through Central Asian agricultural harvest cycles exposed to climate variability. Distribution runs through direct technical relationships in pharmaceutical and premium cosmetic segments, with commodity grades flowing through conventional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA quality guideline tightening for herbal medicinal products creates accelerating demand for pre-qualified European refiners with existing master file infrastructure.
For Market Incumbents: Acquire fermentation technology platforms to reduce agricultural land dependency and secure supply continuity independent of Central Asian harvest volatility. Deepen Hamburg-cluster analytical capabilities to defend against emerging bioprocess specialists. Prioritize European Pharmacopoeia master file pre-building ahead of anticipated NMPA alignment pressures.
For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade glycyrrhizic acid creates entry opportunity for fermentation-derived variants achieving compendial equivalence. Target beverage applications with sodium glycyrrhizate salt forms where water solubility requirements favor technical differentiation over certification burden. Pursue direct sourcing relationships with French and German cosmetic formulators seeking supply chain transparency for consumer-facing ingredient storytelling.
For Investors and Strategic Acquirers: Asymmetric upside sits with bioprocess engineering specialists scaling tank-based production to capture pharmaceutical-grade margin pools. Long-term viability favors fermentation-derived variant producers decoupled from agricultural commodity cycles. Monitor NMPA botanical drug master file approval velocity as inflection indicator for European refiner demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Scale-Up | Maruzen Pharmaceuticals demonstrates tank-based production reducing Central Asian root dependency. |
| European Pharmacopoeia Master File Pre-Building | C.E. Roeper GmbH anchors competitiveness through existing dossier infrastructure meeting EMA guidelines. |
| Captive Licorice Root Sourcing | MAFCO Worldwide LLC secures raw material continuity through Central Asian growing region control. |
| Direct Cosmetic Formulator Relationships | Hamburg-cluster refiners displace distributor intermediaries in premium skin-brightening supply chains. |
| Sodium Glycyrrhizate Formulation Expansion | Japanese and South Korean beverage manufacturers drive salt-form procurement for functional drink applications. |
Research Methodology
Direct dialogue with pharmaceutical API procurement managers, cosmetic formulation directors, botanical extract quality control leads, and fermentation technology R&D heads grounded qualitative findings in operational reality. Secondary validation drew from EMA quality guideline publications, NMPA botanical drug master file standards, European Pharmacopoeia monograph updates, and REACH registration dossiers. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level value outputs reflect disaggregated modeling across purity grade tiers, salt form variants, application verticals, and geographic regulatory clusters. CAGRs derived from regression analysis incorporating input cost indices, certification timeline assumptions, and end-use demand elasticity parameters. Forecast inputs included fermentation technology adoption curves, NMPA documentation reconfiguration timelines, and Hamburg-cluster capacity expansion announcements.
Caveats apply where NMPA enforcement intensity, Central Asian agricultural harvest disruption, or European Pharmacopoeia monograph revision could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Global Lubricating Oil Additives Market
Additives
Oxygen Scavengers Market
Additives
North America Potassium Nitrate Market
Additives
Antimicrobial Ingredients Market
Additives
Canada Anti-Caking Market
Additives
Global Zinc Stearate Market
Additives
Water-Borne Coating Additives Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Global Feed Acidifiers Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Liquid Thickeners Market
Additives
Global Packaging Additives Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Anti-Wear Additives Market
Additives
Polyols and Sorbitols Products Market