
 PVC Plasticizers and Stabilizers Market | 2026-2036
PVC Plasticizers and Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Plasticizers and Stabilizers Market Analytics
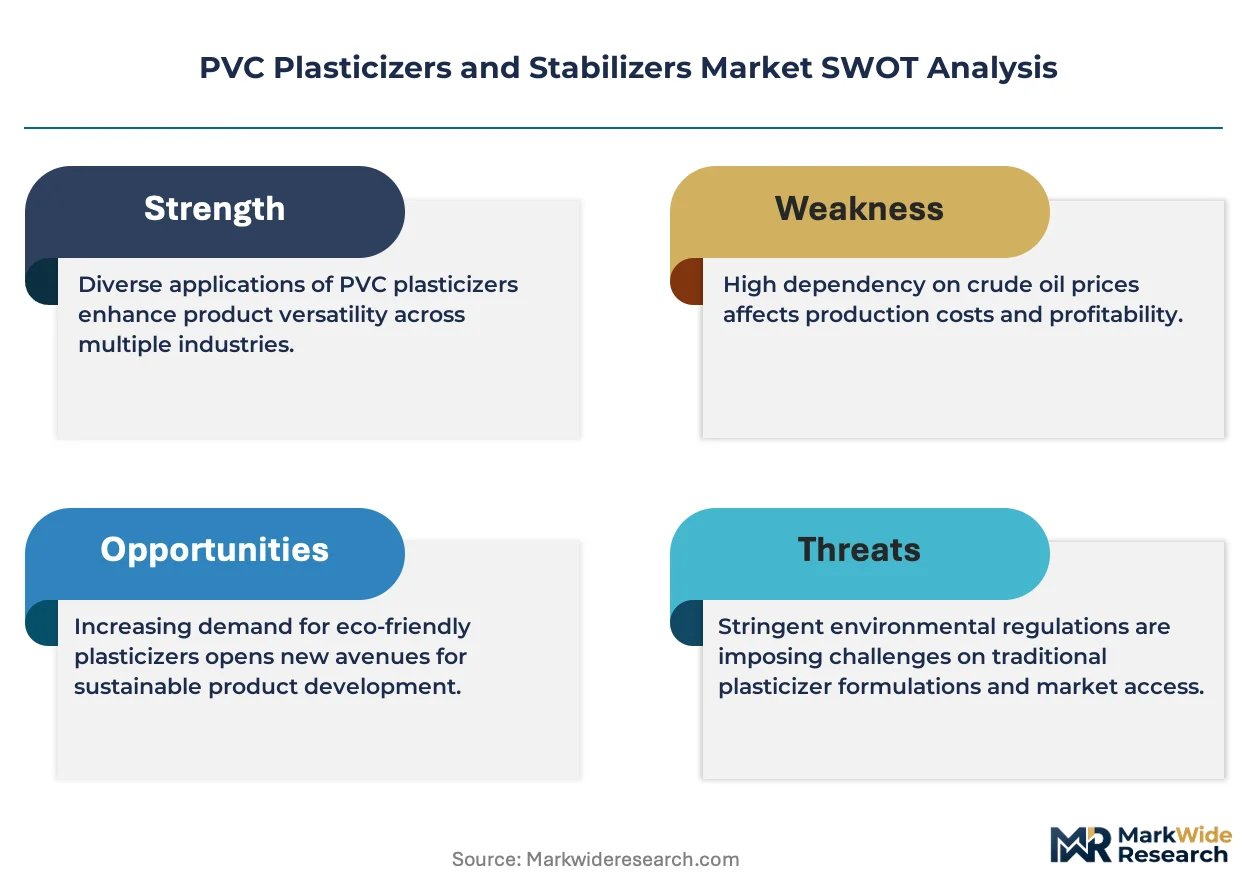
REACH registration deadlines for SVHC substances is collapsing the supplier base for legacy phthalate formulations across European downstream markets. BASF SE leverages its integrated C4 value chain to sustain cost-competitive non-phthalate supply to German automotive OEMs. Arkema SA anchors its position through specialty polymer plasticizer technology leadership in high-durability cable applications. Baerlocher GmbH differentiates via calcium-zinc and mixed-metal stabilizer systems that serve medical-grade film producers navigating stringent migration limits.
PVC plasticizers and stabilizers comprise organic additives—typically ester compounds for flexibility enhancement and metallic soaps or organotin compounds for thermal degradation prevention—that are compounded into polyvinyl chloride resin at 15-50 parts per hundred by weight depending on end-use hardness requirements. These additives enable PVC to process at 160-200°C without dehydrochlorination while delivering Shore A hardness tunability from 70 to 95 for extruded and calendered goods. Non-phthalate plasticizers now capture the fastest expansion trajectory as brand owners and specifiers enforce substance restrictions ahead of regulatory mandates. Bio-based alternatives from epoxidized soybean oil and citrate esters occupy emerging margin pools in premium consumer goods and food-contact film segments where petrochemical provenance carries commercial liability. Phthalate categories remain volume-dominant in cost-sensitive pipe and flooring applications across developing construction markets.
EPA scrutiny under TSCA Section 6 for DINP and DIDP phthalates is reshaping permissible exposure pathways in US consumer products and building materials. ECHA restrictions under REACH Annex XVII on DEHP, BBP, DBP, and DIBP continue to narrow formulation options for European medical device and toy manufacturers, accelerating substitution timelines. China's GB standards for plasticizer migration in food-contact materials and MEE enforcement of dual carbon goals are elevating domestic technical barriers for import and local production alike. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
Regulatory pressure on legacy phthalate chemistries is forcing formulators to rebuild additive portfolios around migration-compliant alternatives. REACH Annex XVII restrictions and emerging state-level bans in the US are collapsing the addressable market for DEHP, BBP, DBP, and DIBP in sensitive applications.
Growth Catalysts
- China's infrastructure build-out:Domestic construction and automotive manufacturing sustain high-volume offtake for flexible PVC piping, flooring, and cable sheathing.
- REACH SVHC registration deadlines:The collapsing supplier base for legacy phthalates redirects formulation investment toward non-phthalate and bio-based alternatives.
- Epoxidized soybean oil technology:Bio-based plasticizers occupy emerging margin pools in premium consumer goods and food-contact film segments.
Market Restraints
- Feedstock volatility:Propylene and butadiene price swings compress margins for integrated C4-based plasticizer producers.
- European supply concentration:REACH compliance costs eliminate smaller compounders, consolidating formulation expertise among a handful of multinationals.
- Performance gaps in bio-based alternatives:Epoxidized oils and citrate esters exhibit inferior low-temperature flexibility versus ortho-phthalates in medical tubing.
Strategic Opportunities
- India's construction sector:Underpenetrated flexible PVC flooring and waterproofing membrane demand offers white space for non-phthalate suppliers.
- EU Green Deal chemistry incentives:Bio-based feedstock mandates and carbon border adjustments reward low-carbon plasticizer production pathways.
- Medical device requalification:MDR migration limits create replacement demand for DEHP-free alternatives in blood bags and infusion sets.
Industry Challenges
- Formulation requalification timelines:OEM validation cycles for new plasticizer-stabilizer combinations extend months beyond regulatory deadlines.
- Calcium-zinc stabilizer process engineering:Substituting lead and organotin heat stabilizers requires extruder recalibration and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Plasticizers and Stabilizers Market |
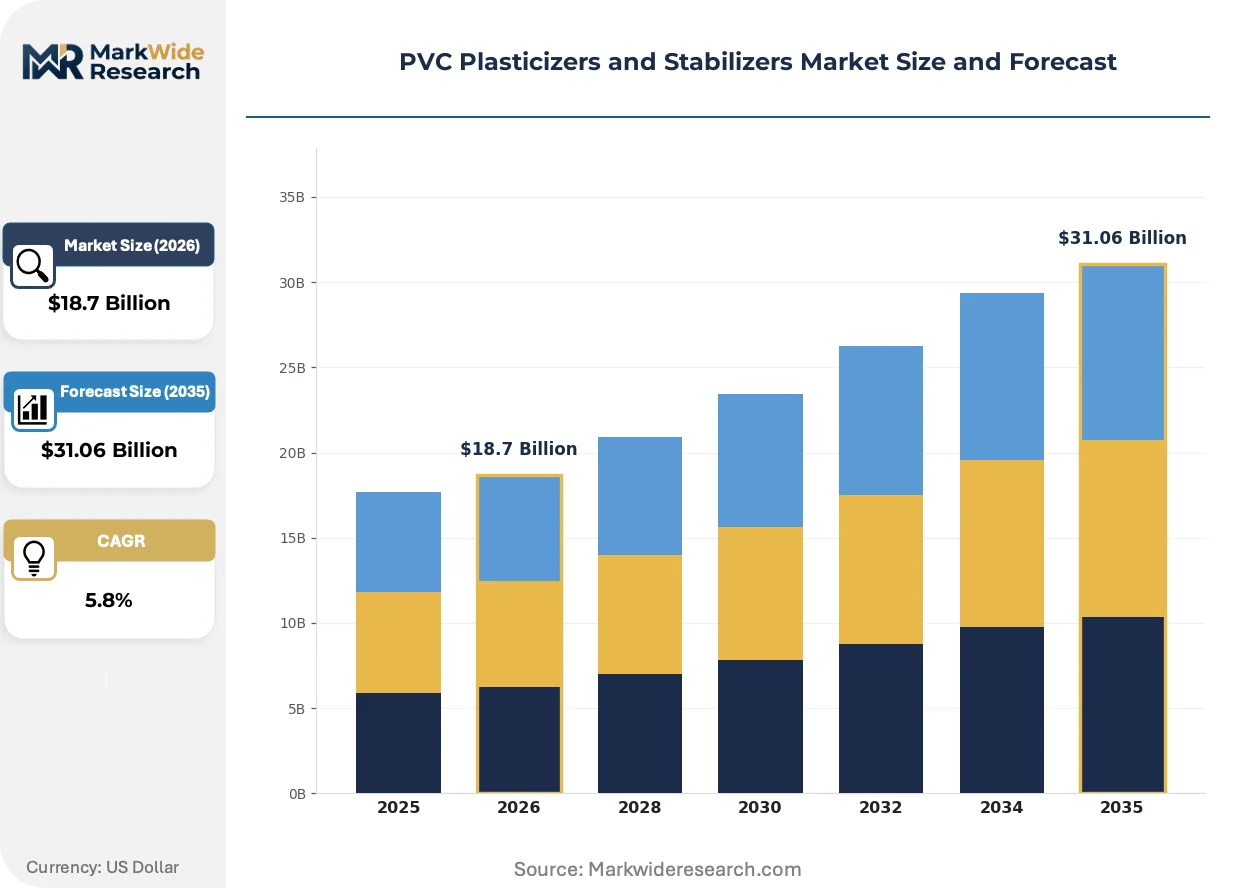
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalates, Non-Phthalates, Polymer, Bio-based Application: Films, Pipes, Flooring, Coatings End User: Construction, Automotive, Electronics, Consumer Goods Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | Adeka Corporation, Baerlocher GmbH, Clariant AG, Arkema SA, BASF SE, Valtris Specialty Chemicals, SONG WON Industrial Group, Akdeniz Chemson, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Plasticizers and Stabilizers Market Evolving Landscape
Formulation science is diverging along regulatory fault lines, with bio-based chemistries and non-phthalate esters advancing on parallel development tracks. Technology licensing and joint development agreements now precede commercial scale-up.
Polymeric plasticizer technology is fragmenting the high-durability cable and automotive interior segments. These macromolecular additives deliver superior migration resistance and fogging performance versus monomeric alternatives. Tier-1 automotive suppliers in Germany and Japan have accelerated adoption timelines. The technology is fragmenting specification standards across OEMs, complicating compounder qualification burdens.
ECHA restrictions under REACH Annex XVII on DEHP, BBP, DBP, and DIBP continue to narrow formulation options for European medical device and toy manufacturers. Substitution timelines have compressed from voluntary transition to mandatory compliance windows. Medical-grade film producers are navigating stringent migration limits through calcium-zinc and mixed-metal stabilizer systems.
Brand owners now enforce substance restrictions ahead of regulatory mandates, compressing supplier switching cycles. Large retailers and consumer goods manufacturers conduct their own restricted substance screening beyond legal minimums. Food-contact film and premium packaging verticals in North America and Western Europe exhibit the most aggressive self-regulation.
PVC Plasticizers and Stabilizers Market Segmentation
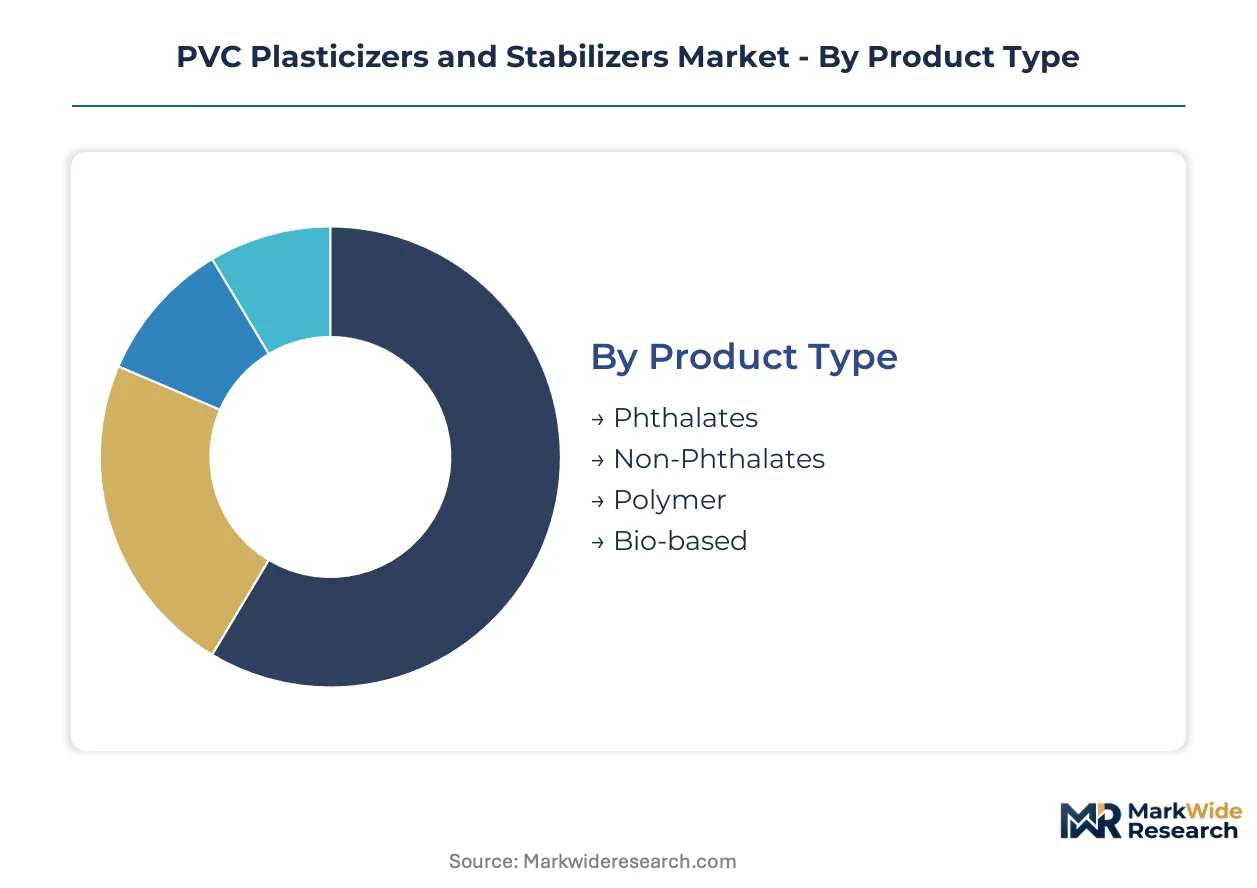
PVC plasticizer and stabilizer selection dictates processing latitude, end-product durability, and regulatory compliance scope. Formulators segment procurement by migration performance, thermal stability requirements, and compounding line compatibility. Margin capture varies sharply across these dimensions.
Product Type:
Non-phthalate alternatives command premium positioning as REACH Annex XVII and FDA scrutiny collapse legacy chemistry viability. Margin pools concentrate in migration-compliant formulations serving medical device and food-contact specifications.
- Phthalates:Ortho-phthalate esters including DEHP, DINP, and DIDP deliver cost-efficient plasticization at 15-50 parts per hundred resin. DEHP retains volume dominance in Chinese construction piping despite European phase-out, while DINP sustains automotive wire harness demand in cost-sensitive markets facing delayed regulatory adoption.
- Non-Phthalates:Adipate, trimellitate, and terephthalate esters achieve Shore A hardness tunability without SVHC classification. German automotive OEMs mandate these alternatives for interior applications, with trimellitates capturing high-temperature wire insulation specifications where volatility resistance outweighs raw material premiums.
- Polymer:Macromolecular additives from polyester and polyacrylate chemistries deliver superior migration resistance for durable goods.
- Bio-based:Epoxidized soybean oil and citrate esters serve food-contact film producers seeking petrochemical-free provenance.
Phthalates hold installed capacity across Asian pipe extrusion. Non-phthalates are rotating up the share rankings in European medical and automotive qualification programs.
Application:
Film and coating applications concentrate specification complexity where migration limits and surface aesthetics intersect. Volume gravity sits in bulk construction materials with lower technical barriers.
- Films:Calendered and blown PVC films for food packaging, medical blood bags, and stationery require plasticizer-stabilizer combinations meeting stringent extractables limits. ECHA migration thresholds and FDA food-contact notifications drive formulation toward epoxidized soybean oil and calcium-zinc stabilizer systems in German and US medical device supply chains.
- Pipes:Flexible PVC piping for drainage, irrigation, and electrical conduit consumes high-volume phthalate plasticization at hardness specifications from Shore A 70 to 90. Chinese infrastructure build-out sustains DINP and DIDP offtake for non-pressure applications where cost efficiency dominates specification.
- Flooring:Homogeneous and heterogeneous vinyl tiles demand plasticizer permanence to prevent surface exudation and staining.
- Coatings:Plastisol and organosol formulations for dip-molding and spray applications require precise viscosity control.
Pipes hold installed capacity across residential and civil construction. Films are climbing the fastest as medical device requalification accelerates substitution timelines.
End User:
Automotive interior specifications concentrate the most demanding performance requirements for fogging resistance, VOC emissions, and thermal aging stability. Construction volume spreads across dispersed compounder networks with lower consolidation.
- Construction:Waterproofing membranes, flexible conduit, and resilient flooring consume plasticizer volumes at 25-45 parts per hundred resin. Indian residential and commercial build-out offers white space for non-phthalate suppliers penetrating cost-sensitive specification environments.
- Automotive:Dashboard skins, door panels, and wire insulation demand low-volatility trimellitates and polymer plasticizers meeting OEM fogging tests. Japanese and German tier-1 suppliers enforce substance restrictions beyond regulatory minimums, compressing supplier qualification cycles.
- Electronics:Cable sheathing and connector housings require thermal stability for reflow soldering compatibility.
- Consumer Goods:Toys, footwear, and sporting goods face retailer-driven restricted substance screening ahead of legal mandates.
Construction holds installed capacity across developing infrastructure markets. Automotive is expanding most quickly as electrification reshapes wire harness specifications.
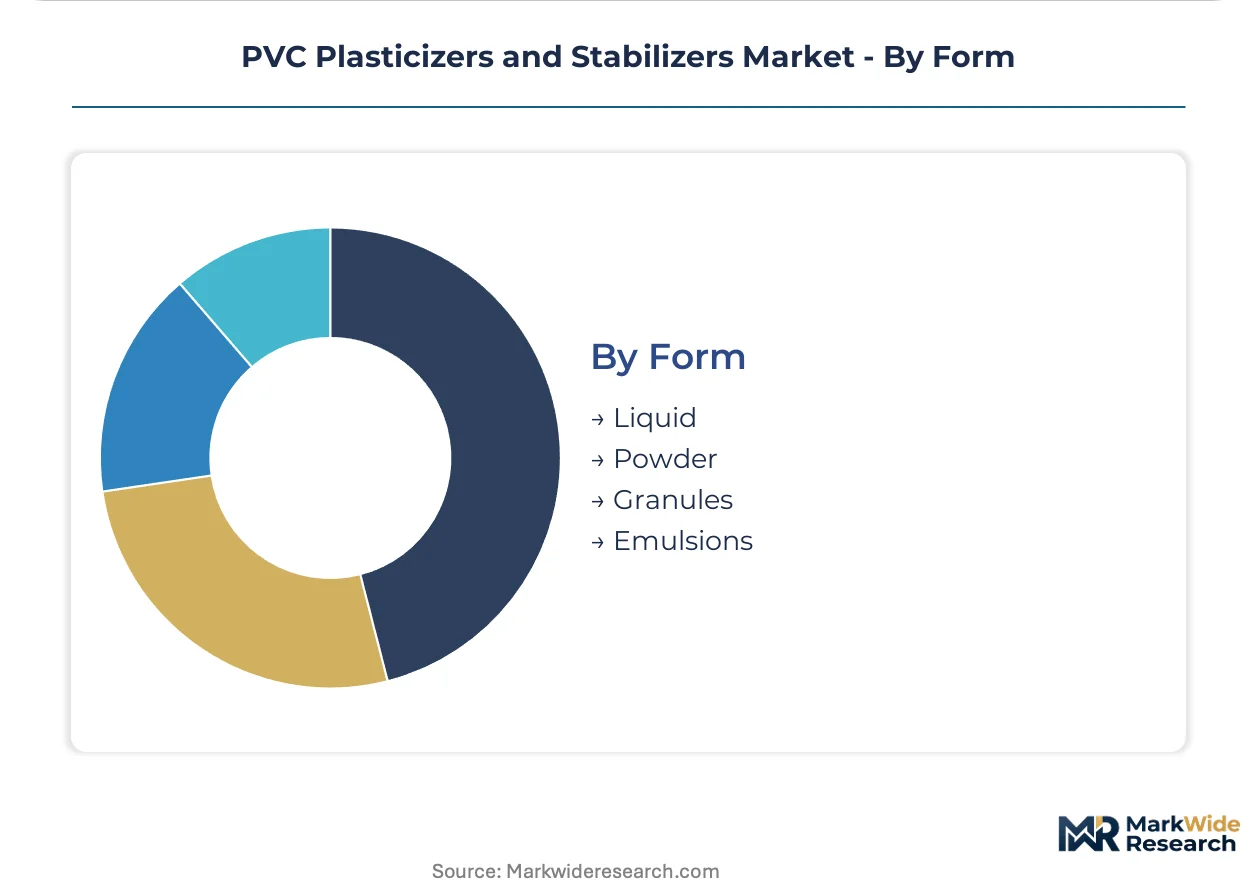
Form:
Liquid delivery dominates high-throughput compounding operations where metering precision and dispersion efficiency determine line productivity. Solid forms capture specialized applications requiring dust-free handling or delayed-action processing.
- Liquid:Monomeric and polymeric esters in bulk tanker or drum delivery enable continuous dosing into PVC dry-blend or plastisol mixing. High-volume Chinese pipe and flooring compounders prefer liquid phthalates for processing efficiency at multi-ton daily throughputs.
- Powder:Spray-dried stabilizer blends and plasticizer adsorbates serve powder-PVC compounders seeking dust-free handling and precise batch weighing. Medical film producers in Switzerland and Germany specify powder calcium-zinc systems for cleanroom compounding environments.
- Granules:Extruded or pan-coated masterbatches concentrate stabilizer or plasticizer loading for let-down ratios.
- Emulsions:Aqueous dispersions enable latex-compatible PVC applications and textile coating processes.
Liquid holds installed capacity across bulk construction compounding. Granules are gaining share fastest as automated dosing systems penetrate mid-scale extrusion operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH SVHC registration deadlines and China's dual carbon enforcement are redirecting formulation investment toward migration-compliant alternatives across major manufacturing economies.
China
Infrastructure build-out and domestic automotive production sustain high-volume offtake for flexible PVC piping and cable sheathing. MEE enforcement of dual carbon goals elevates technical barriers for local production and import alike. The Yangtze River Delta concentration hosts compounders serving construction and automotive OEMs with DINP and DIDP formulations.
Germany
Automotive interior specifications concentrate demand for low-volatility trimellitates and polymer plasticizers meeting OEM fogging tests. REACH Annex XVII restrictions on DEHP, BBP, DBP, and DIBP collapse legacy formulation options for medical device manufacturers. The industrial corridor spanning North Rhine-Westphalia and Bavaria anchors BASF SE's integrated C4 value chain operations.
United States
Building materials and consumer products face EPA scrutiny under TSCA Section 6 for DINP and DIDP phthalates. FDA food-contact notifications drive medical-grade film producers toward epoxidized soybean oil alternatives. The Gulf Coast petrochemical complex sustains cost-competitive phthalate production for pipe and flooring applications.
India
Residential and commercial construction build-out offers white space for non-phthalate suppliers penetrating cost-sensitive specification environments. BIS standards for plasticizer migration in food-contact materials are elevating domestic technical barriers. The Gujarat-Maharashtra industrial belt concentrates flexible PVC flooring and waterproofing membrane demand.
Japan
Wire harness electrification specifications reshape plasticizer requirements for thermal aging stability and low-VOC emissions. METI chemical management frameworks accelerate substitution timelines ahead of regulatory mandates. The Kansai and Chubu industrial regions host tier-1 automotive suppliers enforcing substance restrictions beyond regulatory minimums.
PVC Plasticizers and Stabilizers Market Competitive Landscape
Player mix skews toward integrated petrochemical majors and specialty additive specialists. The supplier base concentrates among multinational compounders with captive feedstock positions and regional formulators serving cost-sensitive construction segments. Strategic archetypes include C4-integrated producers leveraging backward integration into butadiene and propylene, and migration-compliance specialists targeting medical and food-contact specifications. Competitive moves center on capacity reconfiguration toward non-phthalate esters and technology licensing partnerships for bio-based feedstock conversion.
Within the integrated multinational tier, BASF SE and Arkema SA exemplify divergent positioning strategies. BASF SE anchors the C4-integrated archetype through its German manufacturing footprint. Arkema SA occupies the specialty polymer plasticizer segment. Baerlocher GmbH represents the stabilizer systems specialist archetype. These three entities collectively illustrate how REACH compliance costs are consolidating formulation expertise among players with scale and technical service depth.
| Leading Market Players |
|---|
| Adeka Corporation |
| Baerlocher GmbH |
| Clariant AG |
| Arkema SA |
| BASF SE |
| Valtris Specialty Chemicals |
| SONG WON Industrial Group |
| Akdeniz Chemson |
| Lanxess |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day order-to-delivery cycles for specialty plasticizers concentrate pricing power with C4-integrated producers in Germany and China, while spot-market buyers of commodity phthalates face sharper volatility from propylene feedstock swings. Inventory positioning separates contract-tied automotive compounders from construction distributors operating on lean, price-sensitive restocking.
Pricing Analysis
Certification level creates the primary spread between REACH-compliant non-phthalate premiums and commodity DINP baselines. Three-tier pricing structure across medical-grade, automotive-specification, and construction-economy levels reflects migration testing burdens and OEM qualification depth. Cost compression in standard phthalate tiers is intensifying because Chinese pipe compounders negotiate volume aggregations against propylene cost pass-throughs. Construction distributors exhibit highest price sensitivity; medical device manufacturers absorb premiums for DEHP-free alternatives without volume elasticity.
Supply Chain Analysis
Just-in-time delivery dominates German automotive compounding, while Chinese construction distributors maintain strategic stockpiles against MEE environmental enforcement disruptions. Supply concentrates in Germany, China, and the US Gulf Coast, with backward integration into butadiene and propylene feedstocks anchoring cost positions. Raw material dependencies span n-butanol, phthalic anhydride, and epoxidized soybean oil, with soybean oil price volatility tethered to agricultural commodity cycles. Single-source vulnerability runs through European calcium-zinc stabilizer precursor supply. Distribution runs through regional distributor networks serving dispersed construction compounders, contrasted with direct mill-to-OEM contracts in automotive wire harnessing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from cyclical trough conditions as China's infrastructure stimulus and European medical device requalification cycles synchronize demand upticks.
For Market Incumbents: Shield formulation expertise through captive technical service teams embedded at German and Japanese automotive OEMs, countering specialty polymer plasticizer entrants. Deepen backward integration into bio-based feedstock conversion to capture EU Green Deal chemistry incentives before carbon border adjustments harden cost disadvantages. Prioritize calcium-zinc stabilizer process engineering partnerships with extruder OEMs to accelerate lead-substitution timelines for medical film producers. For New Entrants and Emerging Players: Lead with epoxidized soybean oil formulations targeting Indian waterproofing membrane specifications, where BIS migration standards are elevating technical barriers faster than local supply can adapt. Penetrate through toll-compounding partnerships with established PVC resin distributors, avoiding capital-intensive captive compounding investments. Position against REACH-compliant certification gaps in Southeast Asian medical device supply chains. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded phthalate capacity and underutilized regulatory affairs infrastructure for non-phthalate transition. Long-term viability hinges on migration-compliance specialization rather than commodity scale. The signal to watch is MEE enforcement intensity against dual carbon violators, which would accelerate Chinese domestic substitution demand and validate bio-based plasticizer capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captures EU Green Deal incentives and insulates against agricultural commodity volatility in epoxidized soybean oil supply. |
| Long-term Supply Agreement with Automotive OEMs | Locks in trimellitate and polymer plasticizer volumes through electrification-driven wire harness specification changes. |
| Joint Venture for Calcium-Zinc Stabilizer Scale-up | Combines Baerlocher's formulation expertise with regional compounder distribution reach in India's construction belt. |
| Green Manufacturing Transition | Aligns production pathways with MEE dual carbon enforcement and EU carbon border adjustment mechanics. |
| Technology Licensing for Medical-grade Migration Compliance | Monetizes proprietary calcium-zinc stabilizer systems through royalty streams in blood bag and infusion set applications. |
Research Methodology
A spread of perspectives from plant managers at integrated C4 producers, procurement leads at German automotive Tier 1 suppliers, distribution channel partners serving Chinese pipe compounders, and technical R&D directors at stabilizer specialists converged on the working assumptions. Secondary validation drew from ECHA SVHC registration databases, USITC trade flow records, SEC 10-K chemical segment disclosures, and MEE environmental enforcement bulletins. Bottom-up capacity and demand estimates were cross-checked against top-down macroeconomic elasticity models.
Segmentation dimensions modeled include plasticizer chemistry tier, end-use application hardness specification, regional regulatory cluster, and compounding line form factor preference across the projection horizon. CAGRs were derived from regression-weighted scenario analysis incorporating feedstock cost trajectories and substitution elasticity parameters. Industry-specific forecast inputs encompassed automotive wire harness content-per-vehicle trends and medical device MDR requalification pipeline visibility.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure stimulus in China or accelerated REACH enforcement in medical devices would require recalibration. Forecasts reflect documented assumptions regarding propylene-butadiene spread stability and epoxidized soybean oil agricultural yield patterns. Revision becomes warranted when MEE dual carbon penalty thresholds cross enforcement intensity levels that trigger abrupt Chinese domestic supply restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Potassium Tartrate Market
Additives
Global Rheology Modifiers Market
Additives
Chelated Selenium Market
Additives
Tartaric Acid Market
Additives
China Feed Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Calcium Tartrate Market
Additives
Antiknock Agents Market
Additives
FD and C Lakes Market
Additives
Sodium Metabisulfite Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Wax Additives Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Biofuel Additives Market