
 Zinc Chemicals Market | 2026-2036
Zinc Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Chemicals Market Intelligence
The rise of asset-light toll processing agreements is fragmenting the supply base, allowing smaller firms to compete without heavy capital investment in smelting and refining infrastructure. EverZinc leverages its multinational production footprint to serve diverse end-markets. Zochem Inc. specializes in high-purity zinc oxide grades for pharmaceutical and personal care applications. Meanwhile, RUBAMIN anchors its position through large-scale manufacturing capacity in India.
Zinc chemicals are inorganic compounds produced primarily from refined zinc metal or its ores. These materials, such as zinc oxide, function as crucial catalysts and activators in processes like rubber vulcanization. The zinc oxide product type commands the largest market share, driven by its extensive use in the rubber industry. The agriculture application, utilizing zinc sulfate to correct soil deficiencies, represents a significant growth vector.
Regulatory frameworks established by the US EPA and Europe's ECHA under REACH dictate permissible impurity levels and handling protocols. In China, MEE regulations on industrial emissions and waste disposal impact production costs for zinc chemical manufacturers. Navigating these divergent regional environmental standards is a primary strategic challenge for suppliers seeking to maintain market access.
Market Dynamics
The market's central dynamic is the friction between globalized end-markets, such as automotive and agriculture, and the increasingly fragmented, regionally-governed production base. Manufacturers must navigate divergent environmental mandates from bodies like the EU's ECHA and China's MEE to maintain access.
Growth Catalysts
- Automotive Sector Demand:Sustained vehicle production, particularly in Asia, drives consumption of zinc oxide as an essential activator for the vulcanization of rubber used in tires and automotive components, improving their durability and thermal stability.
- Agricultural Productivity Initiatives:Government programs in countries like India promoting soil health and crop yields are increasing the use of zinc sulfate as a micronutrient fertilizer to correct widespread zinc deficiencies in arable land.
- Food Fortification Policies:Public health mandates aimed at combating malnutrition are boosting the incorporation of high-purity zinc compounds, such as zinc sulfate and zinc oxide, into staple foods like flour and rice.
Market Restraints
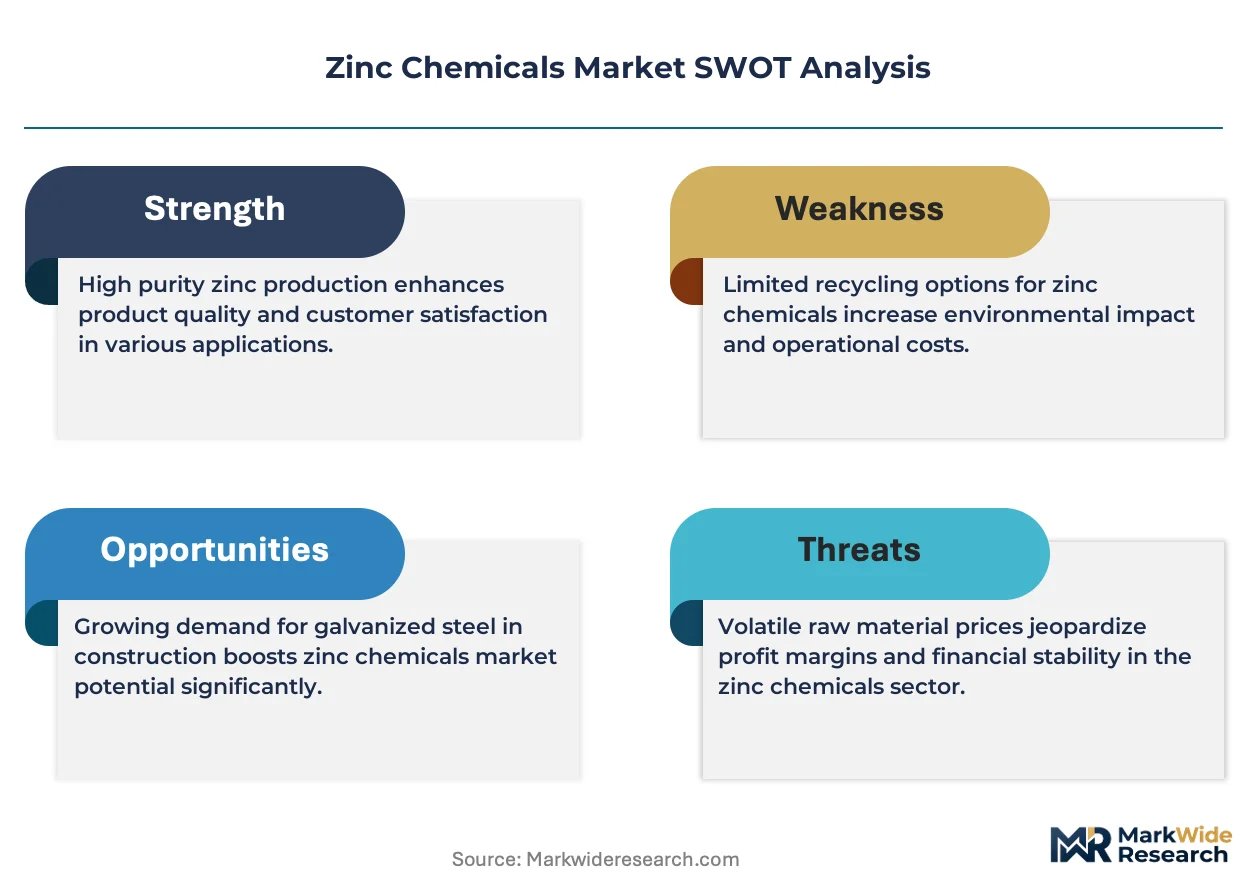
- Raw Material Price Volatility:The production cost of zinc chemicals is directly linked to the price of zinc metal, which is subject to significant fluctuations on the London Metal Exchange, creating margin pressure and planning uncertainty for manufacturers.
- Stringent Environmental Regulations:Compliance with strict standards for heavy metal emissions and waste disposal, enforced by agencies like the US EPA and under Europe's REACH framework, requires substantial capital investment in pollution control technology.
- Threat of Substitution:Ongoing research into alternative, non-zinc-based activators and organic vulcanizing agents for the rubber industry presents a long-term substitution risk, particularly in applications where cost is the primary driver.
Strategic Opportunities
- High-Purity Grades:Expanding into high-purity zinc oxide for pharmaceutical, personal care, and electronics applications offers a significant value-add opportunity, moving producers away from commodity-driven segments toward specialized, higher-margin products.
- Nanomaterial Applications:The development of nano-sized zinc oxide opens new avenues in advanced materials, including more effective UV-blocking agents for sunscreens, antimicrobial coatings, and performance-enhancing additives for plastics and textiles.
- Agricultural Expansion in New Geographies:Underpenetrated agricultural markets in Latin America and Southeast Asia represent a major growth vector for zinc sulfate, as awareness of soil nutrient management and its impact on crop yields increases.
Industry Challenges
- Regulatory Navigation:Managing and documenting compliance across disparate and evolving environmental regulations in key markets, including China, the EU, and the United States, requires significant administrative overhead and specialized expertise.
- Quality Control in Fragmented Supply:The rise of toll processing agreements introduces complexity in ensuring consistent product quality and purity, demanding more rigorous qualification and monitoring of third-party manufacturing partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Chemicals Market |
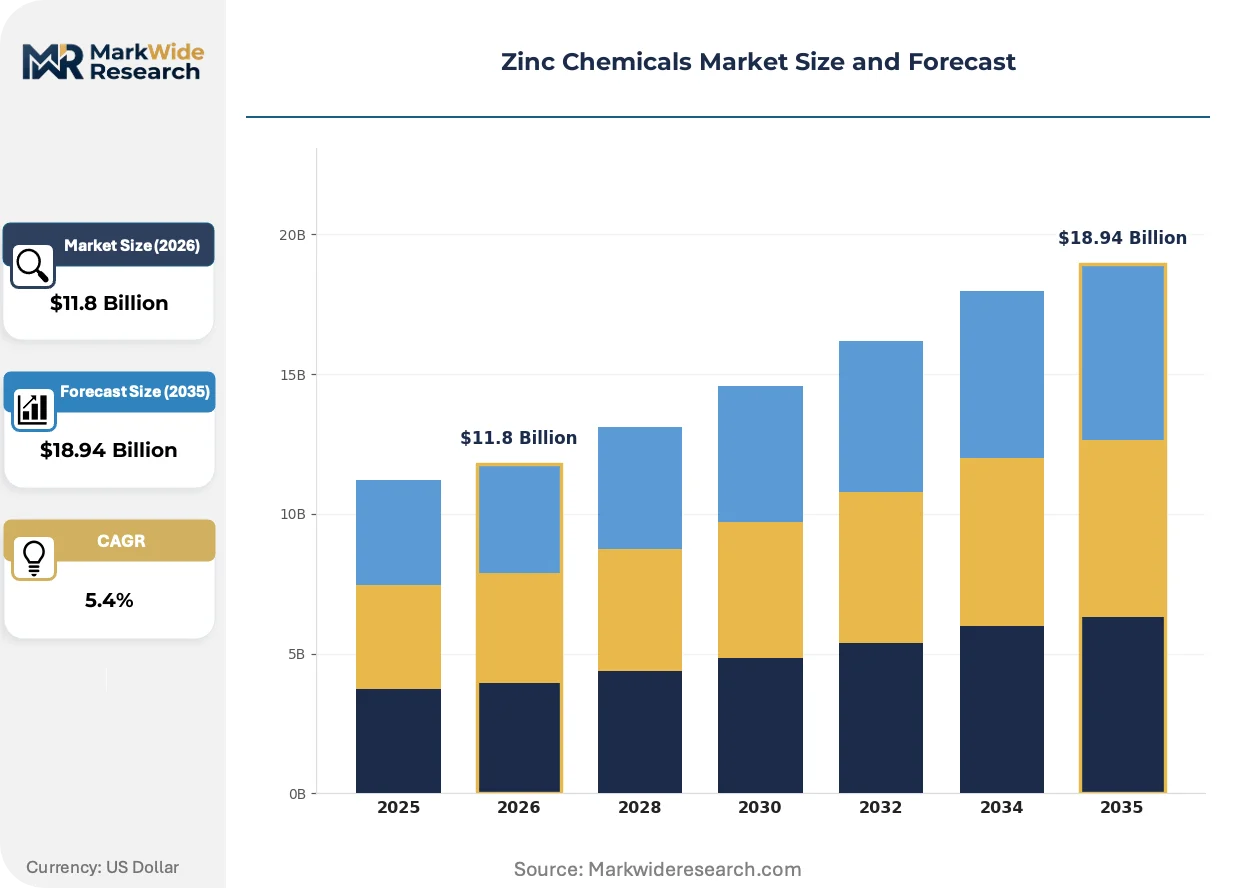
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Oxide, Zinc Sulfate, Zinc Chloride, Zinc Acetate Application: Rubber, Coatings, Agriculture, Pharmaceuticals End Use Industry: Automotive, Construction, Electronics, Healthcare Packaging Type: Bags, Drums, Pails, Totes |
| Companies Covered | Weifang Longda Zinc Industry Co., Ltd., EverZinc, Zochem Inc., HAKUSUI TECH., RUBAMIN, U.S. Zinc, Akrochem Corporation, Pan-Continental Chemical Co., Ltd., L. Brüggemann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Chemicals Market Strategic Shifts & Innovations
A fundamental reorientation toward value-added products and sustainable manufacturing defines the current competitive environment. This shift is a direct response to tightening environmental regulations and sophisticated end-user demands for performance-specific materials.
Specialty zinc oxide production is evolving to meet stringent purity requirements for sensitive applications. The pharmaceutical and personal care industries are rapidly adopting these advanced grades for use in ointments and sunscreens. The market is migrating from a focus on bulk industrial grades toward specialized, high-purity formulations that offer superior performance and safety.
China's Ministry of Ecology and Environment (MEE) has implemented stricter controls on wastewater discharge and air emissions from zinc smelting and chemical production. These regulations increase operational costs and drive industry consolidation by phasing out smaller, non-compliant facilities. Zinc chemical producers within China are consequently investing heavily in pollution abatement technologies to secure their operating licenses.
Sourcing behavior is changing as buyers increasingly utilize toll processing agreements for customized chemical batches. This model allows end-users to bypass the large minimum order quantities of major integrated producers, favoring more flexible, specialized firms. This pattern is particularly evident in the North American cosmetics and European specialty coatings sectors, where formulation-specific grades are required.
Zinc Chemicals Market Segmentation
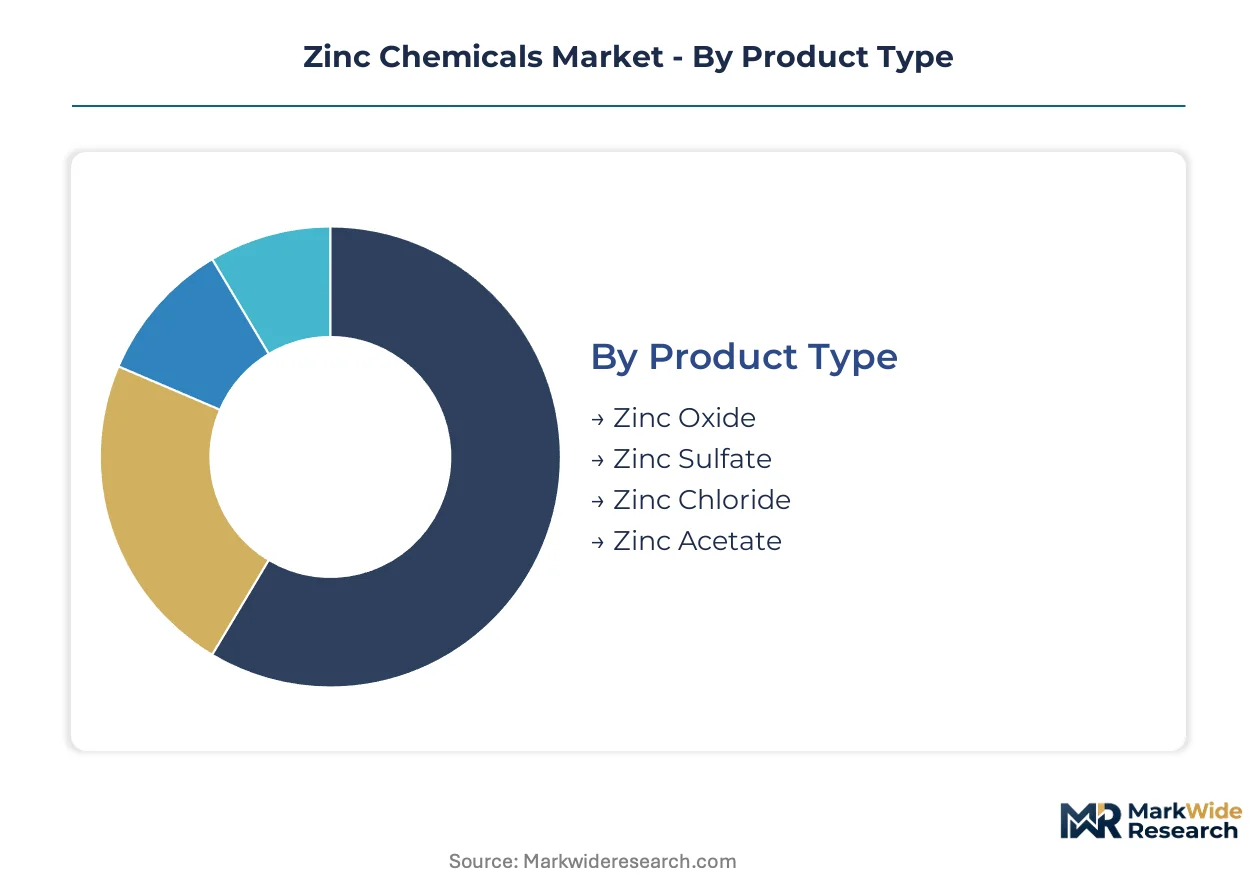
Understanding the Zinc Chemicals Market structure requires a detailed examination of its various segments. This segmentation analysis provides clarity on the distinct product types, applications, end-use industries, and packaging formats. It highlights the differentiated demands and competitive dynamics shaping each market dimension.
Product Type:
The product type segmentation reveals a mix of mature, high-volume compounds and emerging, specialized formulations driving market evolution.
- Zinc Oxide:Zinc oxide is an inorganic compound produced from refined zinc metal, primarily functioning as a crucial activator and catalyst. Demand concentrates in China's automotive sector for rubber vulcanization, improving tire durability and thermal stability.
- Zinc Sulfate:Zinc sulfate is a crystalline inorganic salt, widely utilized as a micronutrient supplement for soil and animal feed. Agricultural productivity initiatives in India are increasing its consumption to correct widespread zinc deficiencies in arable land.
- Zinc Chloride:Zinc chloride serves as a versatile chemical, finding use in fluxing agents, wood preservatives, and dry cell batteries.
- Zinc Acetate:Zinc acetate is a salt of acetic acid, valued in pharmaceutical formulations, food supplements, and as a mordant in dyeing.
Zinc Oxide retains volume leadership; Zinc Sulfate holds the steepest expansion curve.
Application:
Application segments differentiate by their specific performance requirements and associated cost structures, influencing material selection and pricing.
- Rubber:The rubber application primarily utilizes zinc oxide as a vulcanization activator, enhancing elasticity and strength in rubber products. Sustained vehicle production in Asia drives consumption for tires and automotive components, improving their durability.
- Agriculture:Agriculture employs zinc sulfate to correct soil deficiencies, acting as a vital micronutrient for crop health and yield improvement. Government programs in India promoting soil health are increasing its use, boosting crop productivity.
- Coatings:Coatings incorporate zinc chemicals for corrosion resistance, UV protection, and antifungal properties in various industrial and architectural finishes.
- Pharmaceuticals:Pharmaceuticals leverage high-purity zinc oxide and zinc sulfate in ointments, dietary supplements, and as active ingredients in medicinal formulations.
Performance demands in Pharmaceuticals drive premiumization, while volume requirements characterize Rubber.
End Use Industry:
End-use industries exhibit varied consumption patterns, from high-volume industrial applications to specialized, lower-volume sectors with stringent quality demands.
- Automotive:The automotive sector is a major consumer, utilizing zinc chemicals primarily in rubber components like tires and seals for durability. Sustained vehicle production, particularly in China, drives demand for vulcanization activators, improving component longevity.
- Healthcare:Healthcare applications demand high-purity zinc compounds for pharmaceutical formulations, personal care products, and medical devices. Public health mandates combating malnutrition boost incorporation of zinc compounds into staple foods, driving this segment.
- Construction:Construction uses zinc chemicals in paints, coatings, and wood preservatives, providing corrosion protection and antifungal properties for building materials.
- Electronics:Electronics integrates zinc compounds in components like varistors, transparent conductors, and phosphors, enhancing device performance and efficiency.
Automotive represents the largest consumption base, while Healthcare demonstrates robust expansion.
Packaging Type:
Packaging types reflect logistical efficiencies and bulk handling requirements, with supply concentration varying across different container formats.
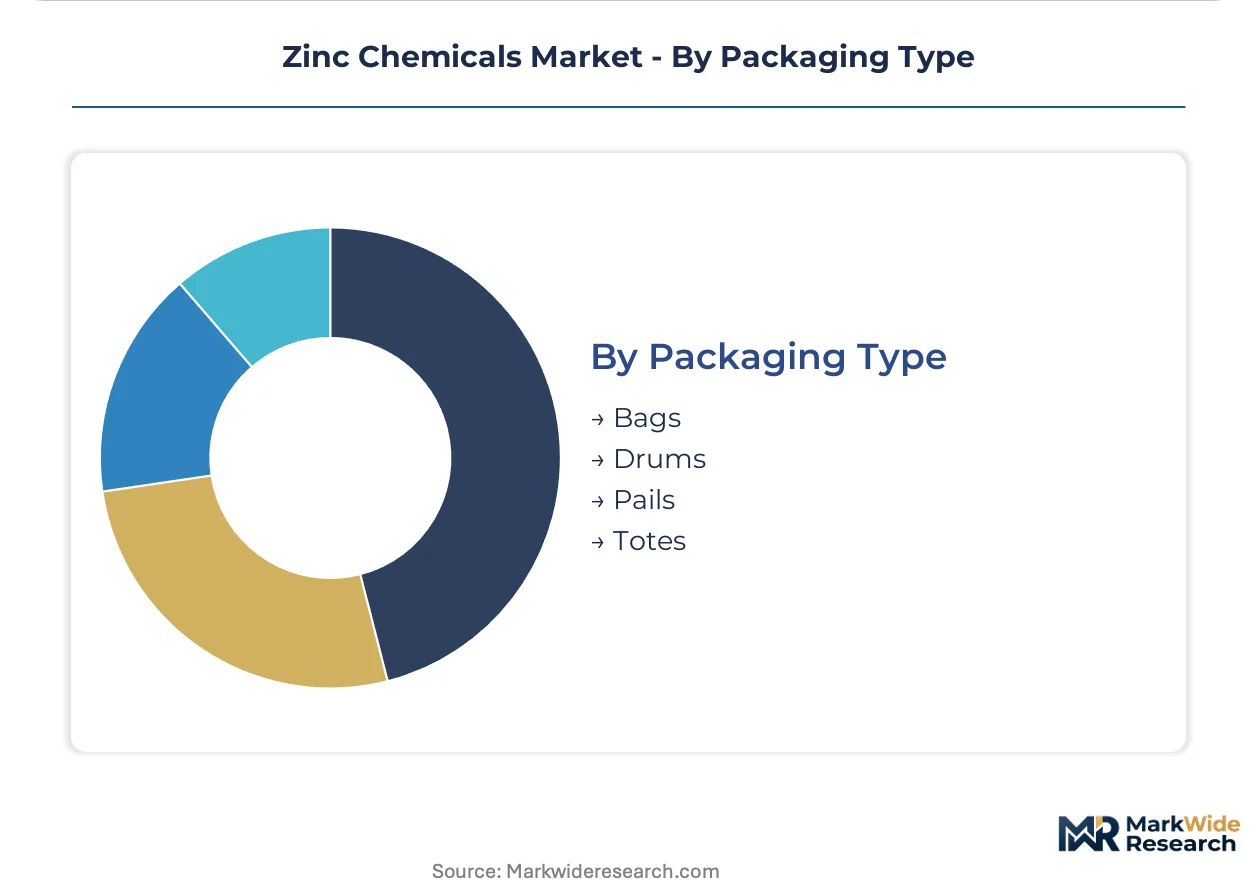
- Bags:Bags are a common packaging choice for powdered zinc chemicals, offering cost-effectiveness and ease of handling for bulk shipments. This format supports large-volume industrial deliveries to diverse manufacturing facilities, particularly in Asia.
- Drums:Drums provide secure containment for both solid and liquid zinc chemical formulations, ensuring product integrity during transport and storage. Their robust construction supports international shipping and protects sensitive materials from environmental factors.
- Pails:Pails offer a convenient, smaller-volume option for specialized zinc chemical batches, favored by end-users requiring precise quantities.
- Totes:Totes, or intermediate bulk containers, facilitate efficient handling of larger, semi-bulk quantities, bridging the gap between drums and full truckloads.
Cost-efficiency considerations favor Bags, whereas Totes address specialized handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting agricultural productivity and public health mandates drive zinc chemical consumption globally. Environmental regulations from bodies like the EU's ECHA and China's MEE influence production costs and market access. These policy frameworks create distinct regional dynamics for manufacturers.
China
Sustained vehicle production in China drives demand for rubber vulcanization agents, particularly zinc oxide. MEE regulations on industrial emissions and waste disposal significantly impact production costs for local manufacturers. Industrial clusters in the Yangtze River Delta concentrate zinc chemical manufacturing, serving both domestic and export markets. This region remains a primary production and consumption hub.
India
Agricultural productivity initiatives in India increase zinc sulfate consumption to correct widespread soil deficiencies and boost crop yields. The country's PLI scheme for specialty chemicals encourages domestic manufacturing and innovation. Gujarat and Maharashtra host major chemical production facilities, supporting the growing agricultural demand. These states are critical for zinc chemical supply.
United States
High-purity zinc oxide demand stems from pharmaceutical and personal care applications, valued for their safety and efficacy. The US EPA dictates permissible impurity levels and handling protocols for chemical producers. The Gulf Coast region possesses extensive chemical processing infrastructure, supporting diverse industrial needs. This area contributes significantly to domestic supply.
Germany
Automotive sector demand for rubber components drives zinc oxide consumption, ensuring tire durability and thermal stability. EU's REACH regulation heavily influences material sourcing and product formulation for manufacturers. The Rhine-Ruhr area represents a key chemical industry cluster, with advanced production capabilities. This industrial heartland leads European chemical output.
Brazil
Underpenetrated agricultural markets represent a major growth vector for zinc sulfate, improving crop health and yields. The country's national environmental agency enforces waste disposal standards, affecting operational costs. São Paulo state contains a large portion of Brazil's chemical industry, facilitating regional distribution. This region is vital for Latin American supply.
Zinc Chemicals Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. The market exhibits a blend of large, integrated producers and specialized niche firms. Strategic archetypes include vertically integrated material suppliers, high-purity specialists, and regional volume manufacturers. Companies pursue capacity expansion and strategic partnerships to secure market share and optimize distribution.
EverZinc, with its multinational production footprint, exemplifies a diversified global producer, serving diverse end-markets across multiple geographies. Zochem Inc. occupies a position as a high-purity specialist, catering to sensitive pharmaceutical and personal care applications requiring stringent quality and specific formulations. RUBAMIN anchors its position as a large-scale manufacturer in India, leveraging significant domestic capacity for volume-driven industrial segments. These companies collectively illustrate the market's varied operational scales and strategic focuses, from global reach to niche specialization and regional dominance.
| Leading Market Players |
|---|
| Weifang Longda Zinc Industry Co., Ltd. |
| EverZinc |
| Zochem Inc. |
| HAKUSUI TECH. |
| RUBAMIN |
| U.S. Zinc |
| Akrochem Corporation |
| Pan-Continental Chemical Co., Ltd. |
| L. Brüggemann GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Industrial centers within China, concentrating production, exert significant influence over global zinc chemical pricing. This capacity dynamic shapes downstream purchasing power for major end-users.
Pricing Analysis
Certification level, including REACH compliance, creates the primary spread in zinc chemical pricing. The market operates on a hybrid model, combining commodity spot pricing for bulk grades with long-term contracts for specialized formulations. Price differentiation stems from quality grade, volume scale, and customization. Pricing pressure stems from London Metal Exchange zinc metal price volatility, and pharmaceutical applications show the least price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common, easing working capital strain for manufacturers. Geographic supply concentrates heavily in China and India, which also serve as major consumption hubs. The supply chain draws from refined zinc metal and its ores, creating a dependency on global mining output. Regulatory restrictions, particularly MEE and ECHA mandates, pose a structural risk to consistent supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rise of asset-light toll processing agreements is fragmenting the supply base, shifting power toward buyers seeking customized chemical batches. This reorientation demands agile strategic responses from all market participants.
For Market Incumbents: Harden core market positions by investing in advanced manufacturing for high-purity grades, mitigating the threat of substitution from alternative activators. Secure long-term raw material contracts to buffer against LME zinc price volatility. Diversify production footprint across multiple geographies, leveraging multinational operations like EverZinc to navigate diverse regulatory landscapes. Invest in R&D for sustainable production methods.
For New Entrants and Emerging Players: Pursue niche opportunities in high-purity zinc oxide for electronics and personal care, where specialized formulations command premium pricing. Target underpenetrated agricultural markets in Latin America and Southeast Asia with zinc sulfate products. A focused go-to-market strategy emphasizing flexibility and rapid customization through toll processing agreements offers a viable entry point. Develop nanomaterial applications for advanced UV-blocking agents.
For Investors and Strategic Acquirers: Carve-out targets emerge from large integrated chemical producers seeking to divest non-core zinc chemical assets. Long-term viability rests on sustained demand from automotive and agriculture, coupled with expanding high-margin pharmaceutical applications. Acquisition archetypes include high-purity specialists like Zochem Inc. and regional volume manufacturers in growth geographies such as RUBAMIN in India. The signal to watch is the consistent enforcement of environmental regulations in China, driving consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | This move addresses growing agricultural demand for zinc sulfate and leverages government PLI schemes. |
| High-Purity Product Line Development | This initiative captures premium margins in pharmaceutical and personal care sectors. |
| Investment in Pollution Abatement | This secures operating licenses in China and ensures compliance with MEE regulations. |
| Long-Term Zinc Metal Offtake Agreements | This mitigates raw material price volatility and ensures supply stability for manufacturers. |
| Strategic Partnerships for Nanomaterials | This accelerates entry into advanced materials for UV-blocking and antimicrobial applications. |
Research Approach
Initial hypotheses were tested against primary input from plant managers, R&D directors, procurement leads at downstream OEMs, and regulatory specialists. This primary research was then validated and augmented through a comprehensive review of secondary data sources. Secondary sources included customs and trade data, industry association reports from Cefic, and publications from environmental agencies like MEE and ECHA. Bottom-up and top-down triangulation ensured robust data integrity.
Demand-supply-balance dynamics formed the core of the analytical framework for market projections across the analysis window. Segmentation dimensions modeled included product type, application, end-use industry, packaging format, and regional regulatory influence. Compound annual growth rates were derived from historical trends and projected future demand. Key industry-specific inputs included global vehicle production forecasts and agricultural yield targets.
Sensitivities concentrate around raw material price volatility, new environmental regulations, and the emergence of substitution technologies. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Hexachloroethane Market
Chemicals
Desalination Chemicals Market
Chemicals
Sodium Ethylate Market
Chemicals
Xanthates Market
Chemicals
Linear Mercaptans Market
Chemicals
Formalin Vials Market
Chemicals
Valeryl Chloride Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Global Butanediol Market
Chemicals
Sodium Hydride Market
Chemicals
Sulfur Chemicals Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Aluminum Phosphide Market
Chemicals
Hydrogenated Dimer Acid Market