
 Global Commodity Chemicals Market | 2026-2036
Global Commodity Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commodity Chemicals Market Analysis
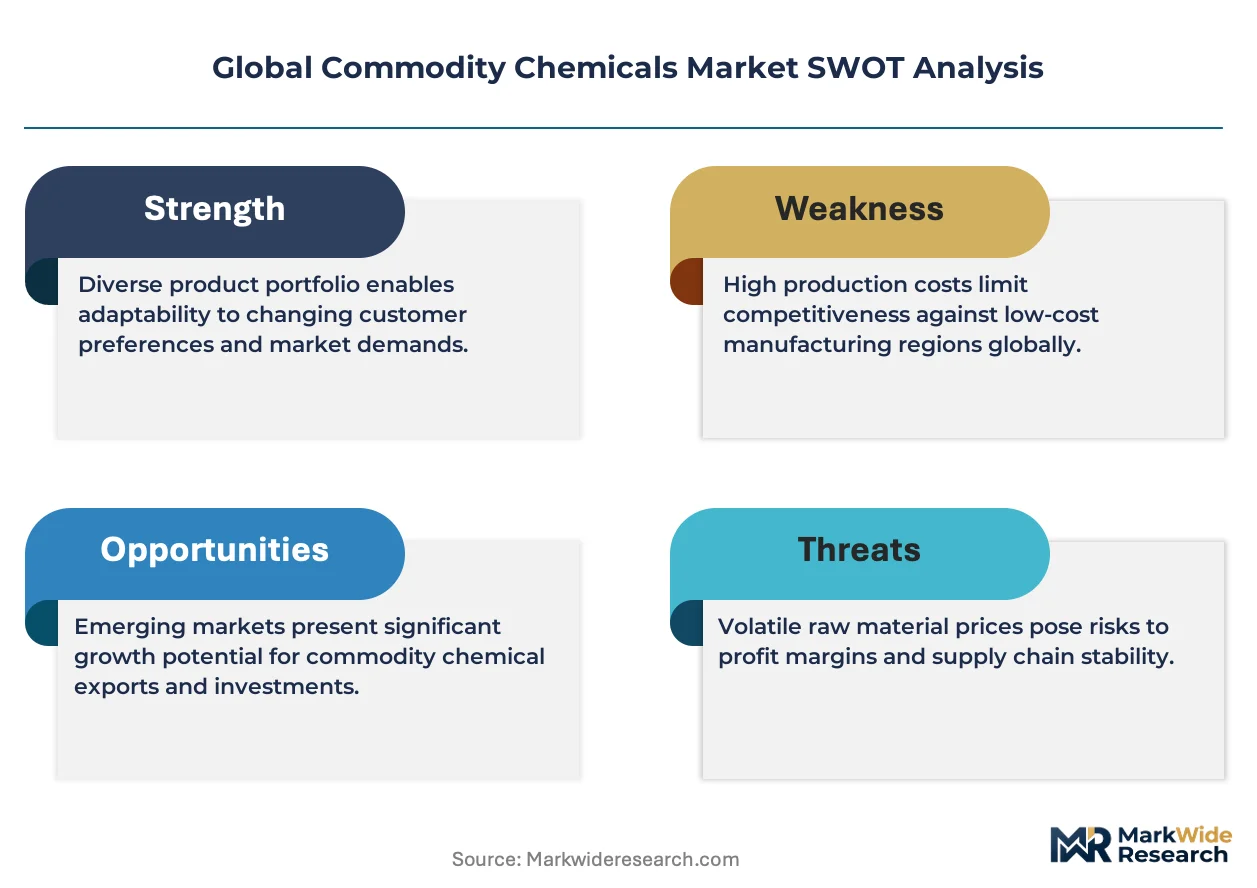
Project finance tied to carbon-abatement milestones is tilting competitive access toward firms with balance-sheet depth. BASF leverages its integrated Verbund sites to capture process efficiencies across ethylene and propylene chains. SABIC anchors its position through captive feedstock access at Jubail and Yanbu. LyondellBasell Industries competes on scale, operating some of the largest single-train crackers outside the Middle East.
Commodity chemicals encompass high-volume, low-margin intermediates produced through continuous catalytic or thermal processes, typically operating at purities above 99 percent for polymer-grade ethylene and propylene. These substances serve as foundational inputs for plastics, synthetic fibers, agrochemical formulations, and industrial coatings across virtually all manufacturing sectors. Ethylene and propylene together occupy the dominant share of product-type value pools, reflecting their role as precursors to polyethylene and polypropylene resins. Methanol is gaining structural importance as a hydrogen carrier and marine fuel blendstock, while acrylics concentrate margin in specialty coatings and superabsorbent polymer applications. Delivery mode selection—bulk pipeline, railcar, or packaged powder—directly shapes logistics costs and customer switching economics in regional markets.
EPA emissions standards under the Clean Air Act, EU ETS carbon pricing, and China's MEE enforcement of dual carbon targets are collectively raising the cost of conventional naphtha cracking and favoring ethane-based and bio-attributed feedstock shifts. REACH registration requirements and impending EU PFAS restrictions are forcing reformulation in adhesives and solvent applications, redirecting R&D spending toward compliant chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded asset exposure in high-carbon production configurations.
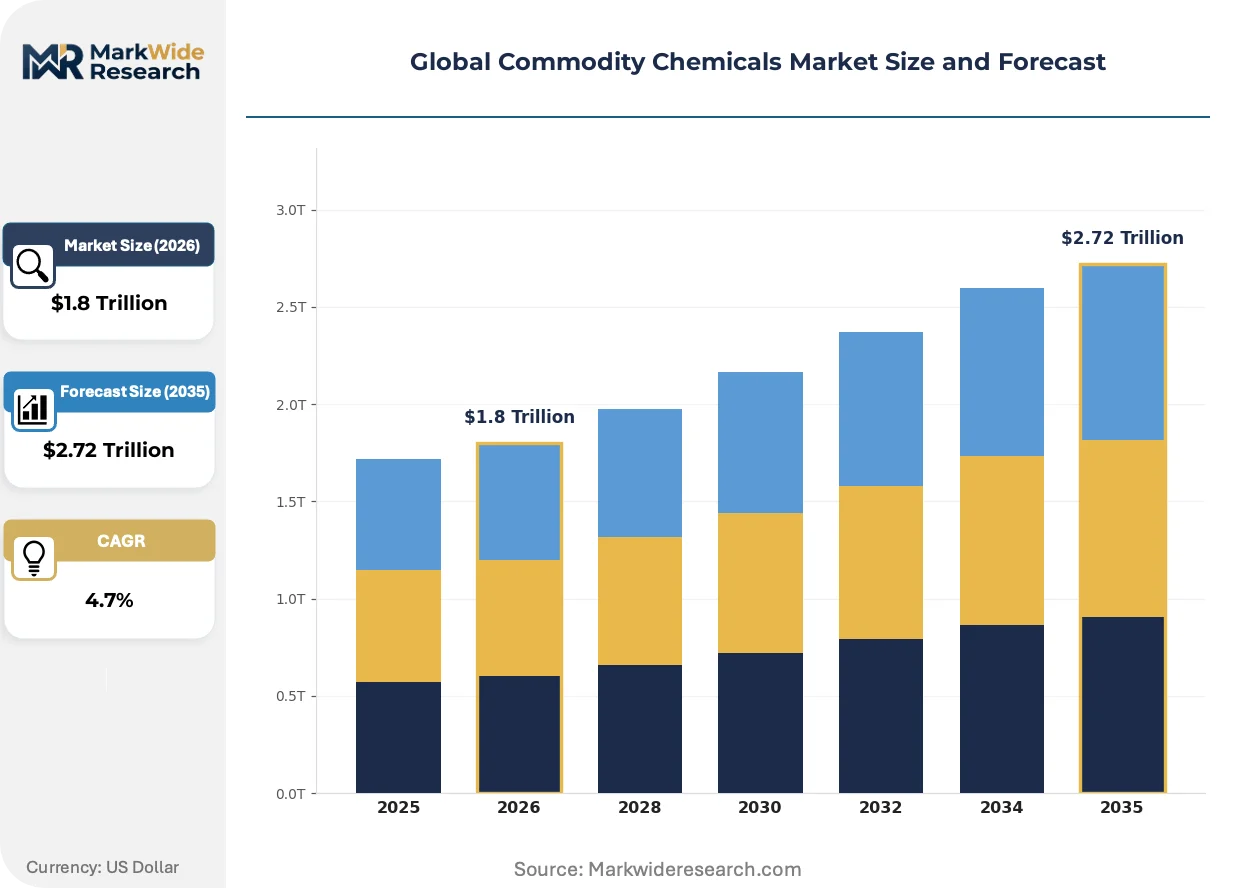
Market Dynamics
Capital allocation across the commodity chemicals sector is pivoting toward carbon-abatement compliance as EU ETS pricing and China's MEE enforcement restructure feedstock economics. Project finance now ties disbursement milestones to verified emissions reductions, favoring producers with balance-sheet depth for retrofit investments.
Growth Catalysts
- EU ETS Carbon Pricing:The EU's emissions trading system is accelerating capital flows toward ethane-based and bio-attributed feedstock configurations, rewarding early movers with lower marginal production costs.
- India Infrastructure Build-out:The country's PLI scheme and national infrastructure pipeline are concentrating acrylics demand for automotive coatings and textile treatments in Gujarat and Maharashtra industrial corridors.
- Methanol Marine Fuel Adoption:The International Maritime Organization's decarbonization timeline is elevating methanol as a hydrogen carrier and blendstock for dual-fuel vessel engines.
Market Restraints
- Naphtha Feedstock Volatility:Crude-linked naphtha pricing exposes conventional crackers in Northwest Europe to margin compression when crude benchmarks spike above ethane-equivalent economics.
- Middle Eastern Supply Concentration:Captive feedstock access at Jubail and Yanbu clusters gives Saudi producers structural cost advantages that limit margin recovery for European and Asian competitors.
- REACH Registration Burden:The EU's chemical registration requirements impose fixed compliance costs that disproportionately burden mid-scale producers lacking dedicated regulatory affairs infrastructure.
Strategic Opportunities
- India Demand Concentration:The country's chemicals consumption is growing at multiples of GDP as per-capita plastics use converges toward East Asian levels, creating white space for localized propylene derivatives.
- Bio-attributed Polymer Certification:Mass-balance chain-of-custody standards are enabling premium positioning for ethylene and propylene with renewable feedstock attribution.
- Pipeline-Rail Intermodal Logistics:New terminal infrastructure at Rotterdam and Houston is compressing delivered costs for inland buyers previously captive to single-mode supply.
Industry Challenges
- Process Control Engineering Talent:The specialized skill set for advanced process control in continuous catalytic crackers is concentrating at integrated Verbund operators, constraining independent producers' optimization capabilities.
- Cracker Retrofit Capex Intensity:Post-combustion carbon capture integration at existing naphtha crackers requires capital commitments that strain project IRR thresholds under current carbon price trajectories.
- PFAS Reformulation Timelines:Impending EU restrictions on per- and polyfluoroalkyl substances are forcing adhesive and solvent formulators to compress multi-year R&D cycles into 18-month compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commodity Chemicals Market |
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $2.72 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylics, Ethylene, Propylene, Methanol End Use Industry: Agriculture, Automotive, Construction, Textiles Delivery Mode: Bulk, Liquid, Powder, Granule Application: Solvents, Adhesives, Foams, Fillers |
| Companies Covered | ExxonMobil, SABIC, BASF, Wanhua Chemical Group, INEOS, SINOPEC, LyondellBasell Industries, Formosa Plastics, PetroChina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commodity Chemicals Market Emerging Trajectories
Electrification of thermal processes and molecular recycling pathways are restructuring production economics while digital twins compress optimization cycles. These shifts are redrawing competitive moats around data infrastructure and clean power offtake agreements.
Electrified cracking furnaces using renewable power input are rendering obsolete the historical linkage between olefin production and onsite combustion emissions. European operators at Rotterdam and Antwerp clusters are piloting 100-megawatt electrode configurations. This technology is compressing the carbon intensity gap between naphtha and ethane feedstock economics.
China's MEE enforcement of dual carbon targets is tightening emissions permits for coal-to-chemicals complexes in Inner Mongolia and Shaanxi. Provincial regulators are withholding operating licenses for expansion projects lacking verified carbon capture commitments. Methanol and ammonia producers in these regions are redirecting capital toward electrolytic hydrogen integration.
Automotive OEMs are consolidating polymer procurement under single-source framework agreements with mass-balance certification requirements. Tier-1 suppliers in Germany and Japan are displacing spot-market resin purchases with multi-year offtake contracts tied to ISCC PLUS verification. This concentration is visible most acutely in battery enclosure and interior trim applications where Scope 3 reporting obligations cascade down supply chains.
Global Commodity Chemicals Market Segmentation
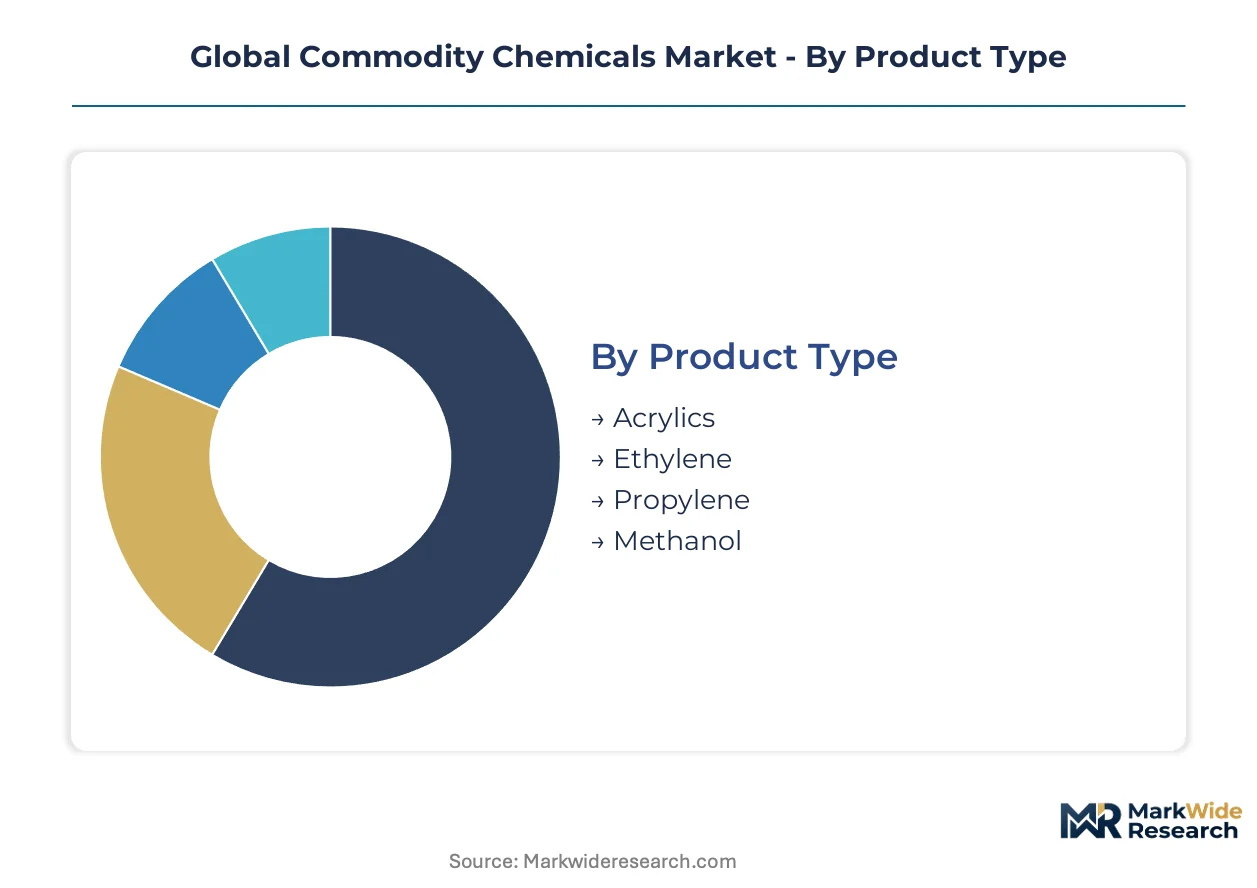
Commodity chemicals fragment across four structural axes that reshape competitive access and margin capture. Product chemistry determines feedstock exposure and carbon intensity. Delivery mode locks in logistics economics and customer switching costs.
Product Type:
Mature olefins dominate volume flows while methanol emerges as the fastest-climbing chemistry on decarbonization tailwinds.
- Ethylene:Polymer-grade specifications above 99 percent purity serve polyethylene resin production. Construction procurement in India and automotive packaging in Germany concentrate demand as lightweighting mandates tighten.
- Propylene:Precursor to polypropylene and acrylonitrile with strict catalyst selectivity requirements. Battery enclosure applications in Japan and interior trim contracts in South Korea are displacing spot-market purchases with mass-balance certified offtake.
- Methanol:Hydrogen carrier and marine fuel blendstock gaining structural importance under IMO decarbonization timelines.
- Acrylics:Concentrate margin in specialty coatings and superabsorbent polymers with reformulation pressure from EU PFAS restrictions.
Ethylene handles the majority of throughput; methanol is the fastest mover on share.
End Use Industry:
Application concentration spans construction materials, mobility solutions, crop protection, and fiber processing with diverging regulatory exposure.
- Construction:Methanol-based adhesives and solvents face tightening green building codes across Germany and California. Procurement is tilting toward lower-carbon formulations as LEED and BREEAM certification thresholds rise.
- Automotive:Acrylics consumption for coatings concentrates in Gujarat and Maharashtra industrial corridors under India's PLI scheme. OEM framework agreements now require ISCC PLUS verification for polymer inputs.
- Agriculture:Ethylene-derived agrochemical formulations serve crop protection with exposure to EPA and REACH registration burdens.
- Textiles:Acrylic fiber treatments and dye intermediates operate under divergent chemical safety regimes between EU REACH and China's GB standards.
Construction absorbs the largest volume share; automotive is climbing fastest on electrification-driven lightweighting demand.
Delivery Mode:
Logistics configuration directly shapes delivered cost structures and regional competitive moats through infrastructure lock-in effects.
- Bulk:Pipeline and marine terminal flows dominate ethylene and propylene movements between Rotterdam, Antwerp, and Houston clusters. New intermodal infrastructure is compressing costs for inland buyers previously captive to single-mode supply.
- Liquid:Railcar and tank truck distribution serves methanol and solvent applications with flexibility for smaller batch sizes.
- Powder:Packaged acrylics and specialty additives for adhesives formulations with higher handling costs but lower minimum order thresholds.
- Granule:Polyethylene and polypropylene resin formats optimized for automated plastics processing equipment.
Bulk handles the majority of throughput; liquid is gaining share fastest on methanol marine fuel logistics expansion.
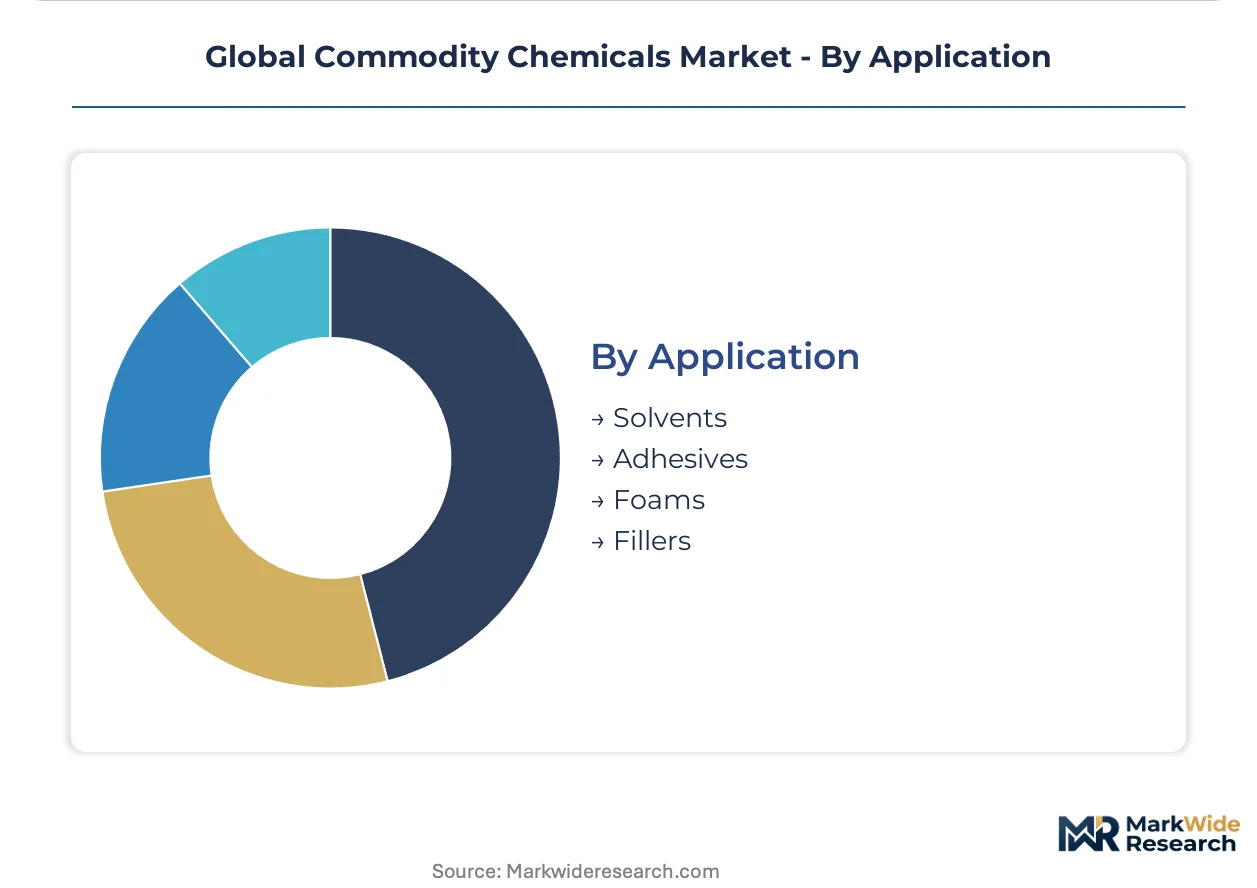
Application:
Functional chemistry requirements split between process solvents, bonding systems, cellular structures, and reinforcement additives with distinct formulation complexity.
- Solvents:Methanol and ethylene-derived carriers for industrial cleaning and coating applications. EU REACH and EPA Clean Air Act standards are forcing reformulation toward lower-VOC chemistries with compressed R&D timelines.
- Adhesives:Acrylic and ethylene-vinyl acetate systems for construction and automotive assembly. Impending EU PFAS restrictions are redirecting R&D spending toward compliant chemistries with 18-month compliance windows.
- Foams:Polyurethane precursors and polystyrene systems for insulation and packaging with carbon intensity disclosure requirements under EU ETS.
- Fillers:Calcium carbonate and talc extenders for plastics reinforcement with supply concentration in China and India.
Solvents carry the largest volume base; adhesives are expanding most quickly on green building code adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU ETS carbon pricing and China's MEE enforcement of dual carbon targets are redirecting capital toward lower-carbon ethylene production pathways across major chemical-producing economies. Project finance tied to emissions-abatement milestones favors producers with balance-sheet depth for retrofit investments. Demand concentration is accelerating in India where the PLI scheme and infrastructure build-out are expanding acrylics consumption.
China
Coal-to-chemicals complexes in Inner Mongolia and Shaanxi face tightening emissions permits under MEE enforcement of dual carbon goals. Provincial regulators withhold operating licenses for expansion projects lacking verified carbon capture commitments. Methanol and ammonia producers in these regions redirect capital toward electrolytic hydrogen integration at facilities near Ordos and Yulin industrial zones.
United States
Ethane feedstock advantages at Gulf Coast crackers support margin positions against naphtha-based European competitors. EPA emissions standards under the Clean Air Act raise compliance costs for conventional production configurations. The Houston Ship Channel and Corpus Christi clusters anchor ethylene and propylene export capacity serving Asian derivative demand.
Germany
REACH registration requirements and impending EU PFAS restrictions force reformulation in adhesives and solvent applications. BASF leverages integrated Verbund sites at Ludwigshafen to capture process efficiencies across ethylene and propylene chains. The country's chemical sector redirects R&D spending toward compliant chemistries with compressed 18-month compliance windows.
India
The PLI scheme and national infrastructure pipeline concentrate acrylics demand for automotive coatings and textile treatments. BIS standards and DGFT trade policies shape import substitution dynamics for propylene derivatives. Gujarat and Maharashtra industrial corridors absorb the fastest-climbing chemicals consumption as per-capita plastics use converges toward East Asian levels.
Saudi Arabia
Captive feedstock access at Jubail and Yanbu clusters gives SABIC structural cost advantages that limit margin recovery for European and Asian competitors. The country's national industrial development strategy prioritizes downstream derivative expansion beyond basic olefins. Petrochemical integration at these sites captures economies of scale in polyethylene and polypropylene resin production.
Global Commodity Chemicals Market Vendor Landscape
Channel-controlling players compete with product-specialist players across differentiated feedstock access and carbon-intensity positioning. The vendor base concentrates around integrated petrochemical majors with captive supply advantages and mid-scale regional operators dependent on spot-market feedstock procurement. Two strategic archetypes dominate: Gulf-based producers leveraging low-cost ethane access and European operators pursuing bio-attributed certification premiums. Competitive moves center on cracker retrofit investments for carbon capture integration and mass-balance chain-of-custody certification for polymer offtake contracts.
Among integrated petrochemical majors, SABIC anchors the Gulf-based archetype through its position at Jubail and Yanbu. BASF occupies a position exemplifying European Verbund integration with balance-sheet capacity for electrified furnace pilot programs. LyondellBasell Industries represents scale-driven competitiveness through large single-train cracker operations. Wanhua Chemical Group sits within the Asia-Pacific expansion archetype with Chinese domestic market access.
| Leading Market Players |
|---|
| ExxonMobil |
| SABIC |
| BASF |
| Wanhua Chemical Group |
| INEOS |
| SINOPEC |
| LyondellBasell Industries |
| Formosa Plastics |
| PetroChina |
| Others |
Supply Flow & Price Mechanics
Middle Eastern ethane supply concentration at Jubail and Yanbu directly determines where margin pools accumulate in polyethylene and polypropylene derivatives. European naphtha crackers face structural cost disadvantages that compress their pricing power in export markets.
Pricing Analysis
Certification level creates the primary spread across polymer-grade ethylene and propylene markets. Mass-balance ISCC PLUS verification commands premium positioning over conventional spot-market material. Cost compression in standard-grade naphtha-derived olefins is intensifying because of EU ETS carbon pricing and crude-linked feedstock volatility. Processors in automotive and packaging segments show highest price sensitivity, while battery enclosure OEMs prioritize certified supply security over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated Verbund operators at Ludwigshafen, Rotterdam-Antwerp cluster facilities, and Gulf Coast steam crackers. Feedstock supply draws from Saudi ethane, US shale gas, and Northwest European naphtha. Single-source vulnerability runs through Middle Eastern supply concentration at SABIC's Jubail complex. Distribution runs through pipeline networks linking Rotterdam, Antwerp, and Houston with rail and barge terminals serving inland derivative processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against bio-attributed polymer substitution as automotive OEMs consolidate procurement under mass-balance certification requirements. Electrified cracking and molecular recycling pathways threaten conventional naphtha-based economics.
For Market Incumbents: Entrench position through captive feedstock access and electrified furnace retrofits at core production sites. BASF's Verbund integration model demonstrates how process efficiency across ethylene and propylene chains defends margin against ethane-advantaged Gulf competitors. Prioritize ISCC PLUS certification investment to secure automotive framework agreements before reformulation windows close. For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors represent the most penetrable entry point for localized propylene derivatives. The country's PLI scheme and infrastructure build-out concentrate acrylics demand for automotive coatings. Target bio-attributed polymer certification gaps in European adhesive and solvent formulations as a go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale European crackers lacking carbon capture retrofit capital. Long-term viability hinges on feedstock flexibility and clean power offtake agreements across the analysis window. Watch for EU ETS price inflection above cracker retrofit IRR thresholds as the signal to accelerate consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Cracker Retrofit | Rotterdam and Antwerp pilot programs compress carbon intensity gaps between naphtha and ethane economics. |
| Backward Integration into Bio-feedstock | Mass-balance chain-of-custody certification secures premium positioning for polymer offtake contracts with German OEMs. |
| Long-term Supply Agreement | Multi-year offtake contracts with ISCC PLUS verification displace spot-market resin purchases in battery enclosure applications. |
| Joint Venture in India | PLI scheme incentives and infrastructure build-out accelerate acrylics consumption for automotive coatings in Gujarat corridors. |
| Green Manufacturing Transition | Electrolytic hydrogen integration at Ordos and Yulin methanol facilities satisfies MEE emissions permit requirements. |
Methodological Framework
Desk research of customs and trade flow databases, ACC and Cefic industry reports, and SEC 10-K filings preceded structured interviews with plant managers at integrated crackers, procurement leads at downstream automotive OEMs, distribution channel partners in Rotterdam and Houston, and technical R&D directors overseeing adhesive reformulation. Primary fieldwork with these stakeholders combined with secondary validation through regulatory filing analysis. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Assumptions around EU ETS price trajectories, crude-to-ethane spread persistence, and India's PLI scheme implementation pace were held fixed while feedstock mix and certification adoption rates varied across scenarios. Segmentation dimensions modeled include product chemistry grade, end-use industry concentration, delivery mode logistics configuration, and regional production hub carbon intensity. CAGRs were derived from production capacity expansion timelines and demand elasticity estimates tied to per-capita plastics consumption convergence.
Macroeconomic conditions sit as an overlay; deviation in crude benchmark volatility, carbon price enforcement intensity, or infrastructure investment execution would shift the trajectory. Forecasts reflect these documented assumptions and acknowledge that regulatory divergence between REACH, EPA Clean Air Act, and China's MEE enforcement could strand high-carbon production configurations. Quarterly review of EU ETS auction results, Indian BIS standard updates, and IMO marine fuel adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Azide Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
1, 4 Butanediol Market
Chemicals
Fireworks Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Paint Stripper Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Flooring Chemicals Market
Chemicals
Anhydrides Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Europe Tertiary Amines Market