
 Glutathione Market | 2026-2036
Glutathione Market Size, Share, and Industry Trends Forecast 2026-2036
Glutathione Market Analysis
Buyer concentration among wellness centers and hospital networks is restructuring procurement patterns across the glutathione supply base. Kyowa Hakko Bio Co., Ltd. leverages decades of fermentation expertise to anchor its position in pharmaceutical-grade supply. Shenzhen GSH Bio-Technology Co., Ltd. competes aggressively on manufacturing scale, while KOHJIN Life Sciences Co., Ltd. differentiates through biotechnology leadership in yeast-derived production methods.
Glutathione is a tripeptide composed of cysteine, glutamic acid, and glycine, synthesized industrially through microbial fermentation or enzymatic catalysis with purity grades ranging from food-grade to injectable pharmaceutical standards; it functions primarily as an intracellular antioxidant and detoxification agent across therapeutic, cosmetic, and nutritional applications. The oral form segment dominates volume throughput due to accessibility through health stores and online retail channels, while the injectable form commands premium positioning in clinical settings where bioavailability requirements are stringent. Skin lightening applications within cosmetic dermatology represent the fastest-expanding demand pool, whereas antioxidant therapy maintains mature, steady consumption in hospital and homecare environments.
FDA oversight of injectable glutathione products and EMA pharmacovigilance requirements for antioxidant therapies shape formulation standards and market access conditions in North America and Europe. China's NMPA and Japan's PMDA enforce distinct purity and manufacturing practice rules that determine which suppliers qualify for regulated clinical channels. Stakeholders must monitor evolving regulatory divergence between cosmetic and pharmaceutical classification pathways as jurisdictions reassess glutathione's therapeutic status.
Market Dynamics
Fermentation technology advances in microbial synthesis are compressing production costs while pharmaceutical-grade certification requirements from cosmetic dermatology clinics are restructuring procurement patterns across the glutathione supply base.
Growth Catalysts
- Cosmetic dermatology expansion:Skin lightening applications within clinical settings are generating premium demand for injectable-grade glutathione, pulling supply chains toward higher-purity manufacturing standards.
- East Asian manufacturing scale:Capacity expansion across China, Japan, and South Korea is lowering unit economics through economies of scale in microbial fermentation infrastructure.
- EMA pharmacovigilance pathways:Clearer antioxidant therapy classification frameworks in Europe are enabling faster market access for pharmaceutical-grade formulations.
Market Restraints
- Raw material input volatility:Cysteine supply fluctuations create cost instability for fermentation-based producers dependent on amino acid feedstock markets.
- East Asian supply concentration:Overreliance on Chinese and Japanese fermentation capacity exposes buyers to geographic disruption risks and trade policy friction.
- FDA injectable oversight:Stringent approval requirements for parenteral glutathione products create regulatory friction limiting US clinical market penetration.
Strategic Opportunities
- Homecare antioxidant therapy:Oral formulation demand from aging populations in Germany and France represents underpenetrated volume potential outside clinical channels.
- Nutraceutical e-commerce expansion:Direct-to-consumer platforms are bypassing traditional pharmacy distribution, capturing margin previously allocated to intermediaries.
- Biotechnology convergence:Integration of CRISPR-edited yeast strains with continuous fermentation systems promises step-change yield improvements.
Industry Challenges
- Pharmaceutical-grade certification timelines:cGMP compliance audits and injectable-grade validation protocols extend facility qualification periods by 18-24 months.
- Fermentation specialist scarcity:Shortage of microbial process engineers with glutathione-specific bioreactor expertise constrains capacity expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glutathione Market |
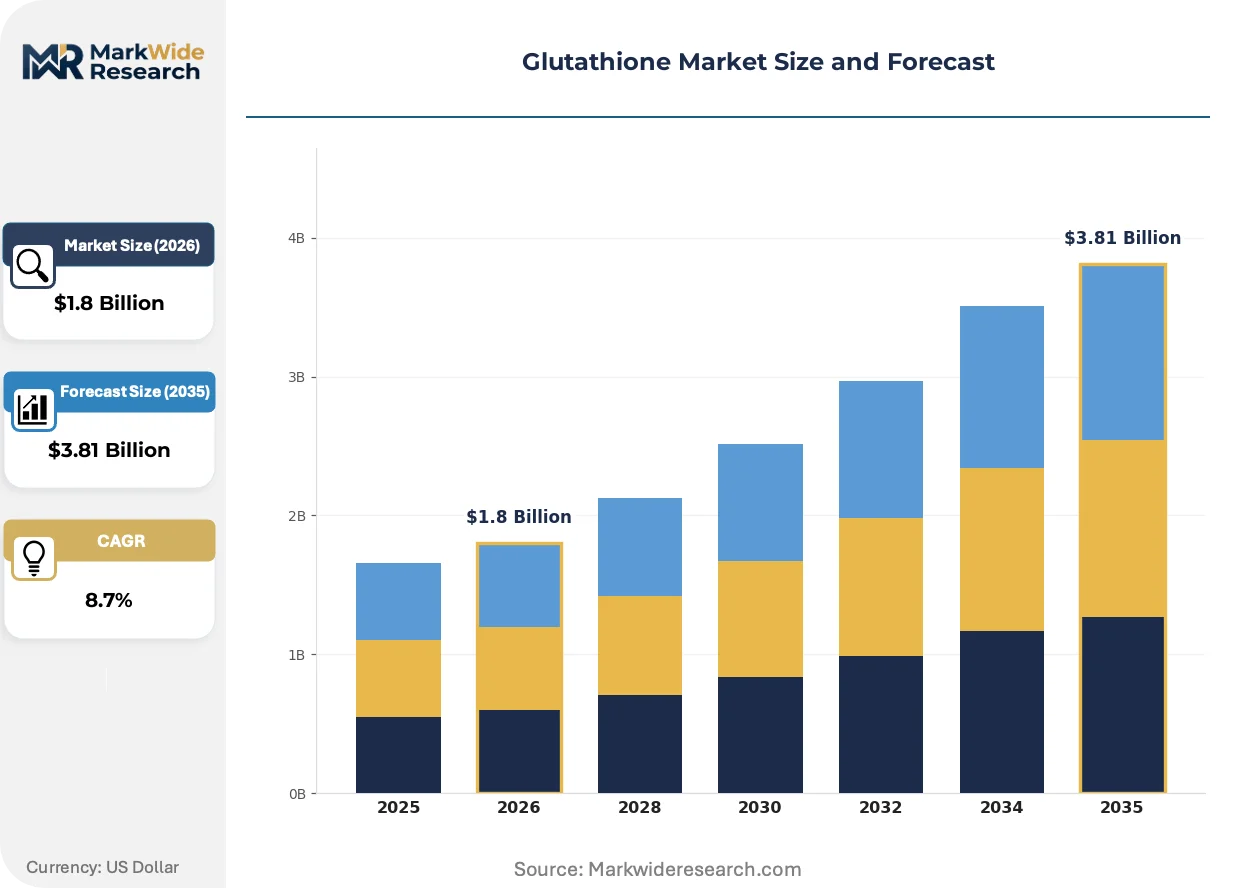
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduction Form, Injectable Form, Oral Form, Topical Form Application: Antioxidant Therapy, Detoxification, Skin Lightening, Cellular Health End User: Hospitals, Clinics, Wellness Centers, Homecare Distribution Channel: Online Retail, Pharmacies, Direct Sales, Health Stores |
| Companies Covered | Showa Denko K.K., Shenzhen GSH Bio-Technology Co., Ltd., Kyowa Hakko Bio Co., Ltd., Mitsubishi Tanabe Pharma Corporation, Kyungdong Pharmaceutical Co., Ltd., Shandong Jincheng Biological Pharmaceutical Co., Ltd., Kaiping Genuine Biochemical Pharmaceutical Co., Ltd., NOW Health Group, Inc., KOHJIN Life Sciences Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glutathione Market Emerging Trajectories
Continuous processing technologies and regulatory pathway clarification are compressing cost structures while buyer behavior shifts toward direct sourcing models. These forces are redrawing competitive boundaries between fermentation specialists and downstream formulators.
CRISPR-edited yeast strains are absorbing incremental production volume as Kyowa Hakko Bio and KOHJIN Life Sciences deploy genetically optimized microbial platforms. Cosmetic dermatology clinics in Seoul and Tokyo are adopting these higher-purity inputs at accelerated procurement cycles. The technology is absorbing market share from conventional fermentation methods by delivering pharmaceutical-grade consistency at reduced batch-to-batch variation.
REACH registration requirements for novel enzymatic catalysts are forcing reformulation investments among European suppliers seeking cosmetic-grade certification. Industrial consequence includes delayed product launches and elevated compliance spending for manufacturers lacking existing dossier portfolios. Skin lightening serum producers in Italy and Spain are responding by consolidating supplier relationships toward pre-registered fermentation houses with established ECHA filings.
Wellness center networks are consolidating procurement through centralized buying cooperatives, displacing fragmented distributor relationships that historically dominated glutathione supply. Hospital networks in Brazil and Mexico are piloting direct contracts with Shenzhen GSH Bio-Technology, bypassing regional pharmaceutical wholesalers. This concentration is most visible in Latin American markets where buyer scale now commands volume pricing previously reserved for East Asian domestic purchasers.
Glutathione Market Segmentation
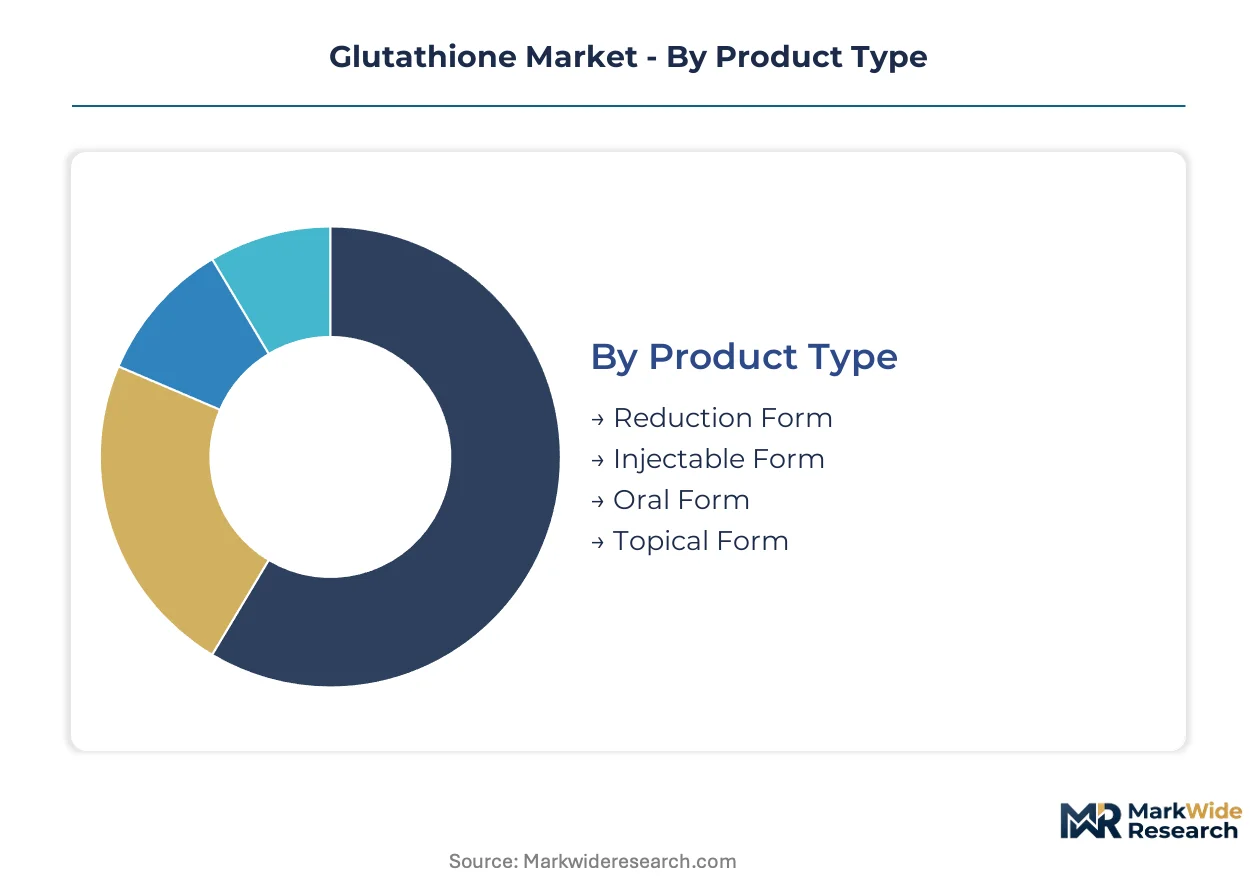
Glutathione's regulatory fragmentation demands precise segment targeting. Certification requirements diverge sharply between injectable pharmaceutical channels and cosmetic-grade distribution, reshaping supplier qualification priorities across every category.
Product Type:
Injectable-grade glutathione demands FDA, EMA, or PMDA pharmaceutical manufacturing certification, while oral and topical forms navigate cosmetic-nutritional classification pathways with lighter regulatory burdens.
- Injectable Form:Parenteral-grade glutathione requires sterile manufacturing under cGMP protocols with endotoxin testing and pyrogen validation. Demand concentrates in Seoul and Tokyo cosmetic dermatology clinics where bioavailability requirements are stringent. PMDA oversight in Japan and FDA injectable regulations in the United States create dual-approval barriers that limit supplier qualification.
- Oral Form:Capsule and tablet formulations dominate volume throughput through reduced regulatory friction. Wellness centers in Germany and France drive steady procurement of food-grade and dietary supplement-classified products. SAMR registration in China and FSSAI compliance in India determine market access for imported finished goods.
- Reduction Form:Active reduced L-glutathione (GSH) serves as the bioactive input for downstream formulation across all delivery routes.
- Topical Form:Serum and cream formulations targeting skin lightening applications require cosmetic-grade purity with dermatological safety testing.
Leading the category by volume: Oral Form. Growing fastest: Injectable Form.
Application:
Clinical reimbursement pathways favor antioxidant therapy and detoxification protocols, while skin lightening operates predominantly through out-of-pocket cosmetic expenditure with minimal insurance coverage.
- Skin Lightening:Melanin-inhibiting applications in cosmetic dermatology command premium pricing for pharmaceutical-grade injectable supply. Clinics in South Korea and Japan absorb the highest per-patient glutathione volumes globally. Regulatory divergence between cosmetic and pharmaceutical classification creates market access complexity across jurisdictions.
- Antioxidant Therapy:Intravenous and oral protocols for oxidative stress management maintain mature, hospital-validated demand. Homecare environments in aging European populations sustain steady consumption of maintenance-dose oral formulations. EMA pharmacovigilance requirements shape formulation standards for clinical channel access.
- Detoxification:Hepatic support and heavy metal chelation applications concentrate in hospital and specialized clinic settings.
- Cellular Health:General wellness and anti-aging positioning targets direct-to-consumer channels with reduced clinical oversight.
Dominating by revenue concentration: Skin Lightening. Expanding most quickly: Skin Lightening.
End User:
Procurement scale and certification requirements separate institutional buyers from fragmented consumer-facing channels, with hospital networks commanding volume pricing unavailable to smaller wellness operators.
- Hospitals:Inpatient and outpatient departments require injectable-grade supply with full pharmaceutical dossier documentation. Brazilian and Mexican hospital networks are piloting direct contracts with East Asian manufacturers, bypassing regional wholesalers. ANVISA registration in Brazil determines supplier eligibility for public procurement channels.
- Clinics:Cosmetic dermatology and specialized infusion centers drive premium demand for high-purity parenteral products. Seoul and Tokyo clinic clusters set quality benchmarks that propagate to Southeast Asian and Latin American markets.
- Wellness Centers:Preventive health and aesthetic service providers consolidate procurement through buying cooperatives.
- Homecare:Self-administered oral supplementation represents the most price-sensitive demand pool with minimal regulatory oversight.
Highest certification burden: Hospitals. Fastest procurement consolidation: Clinics.
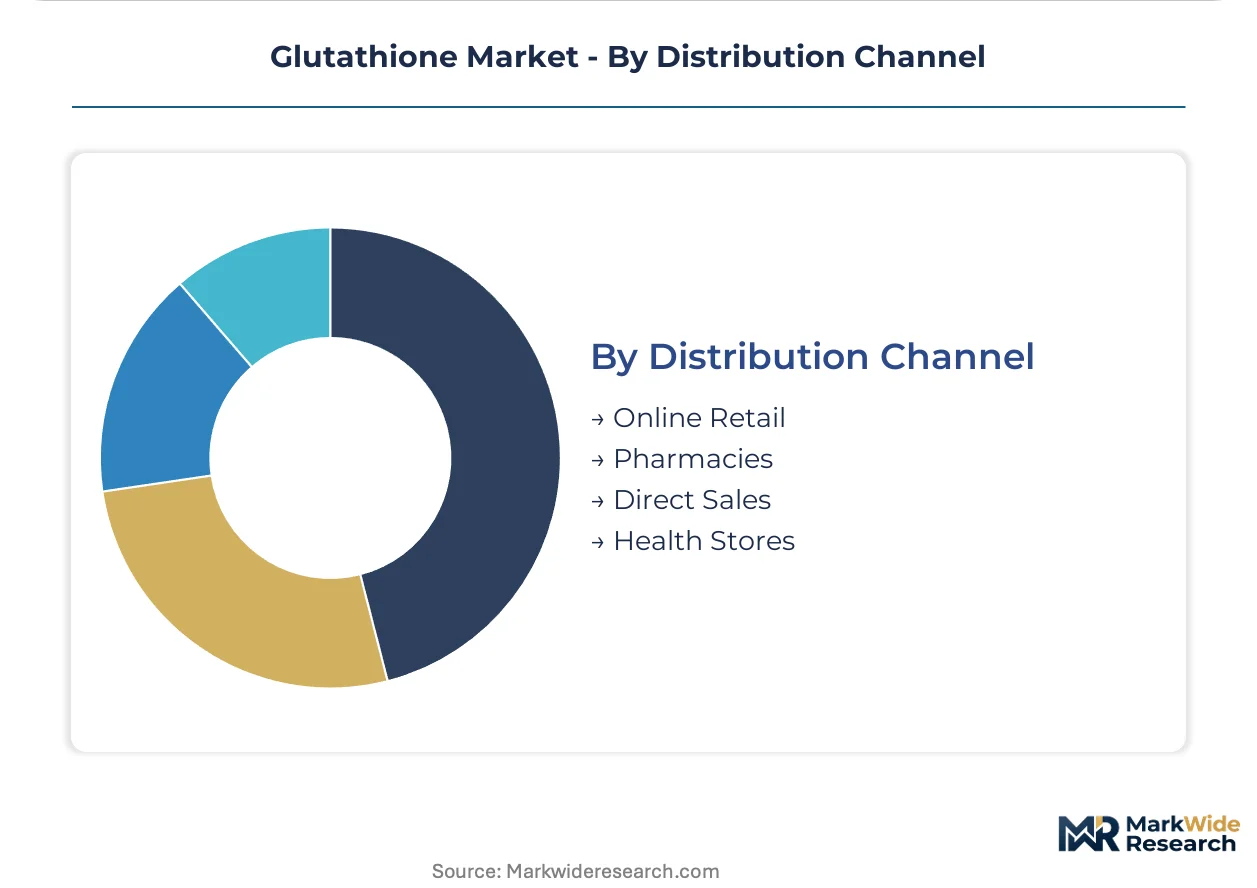
Distribution Channel:
Channel selection determines margin capture, with direct sales and online retail displacing traditional pharmacy intermediaries that historically dominated glutathione distribution.
- Direct Sales:Manufacturer-to-institution contracts capture margin previously allocated to wholesale distributors. Shenzhen GSH Bio-Technology and Kyowa Hakko Bio are expanding direct relationships with Latin American hospital networks. Channel control enables customized formulation and packaging for large-volume buyers.
- Online Retail:E-commerce platforms bypass geographic distribution constraints for oral and topical consumer products. Direct-to-consumer models in North America and Europe capture first-party data and repeat purchase loyalty. FDA and FTC dietary supplement advertising regulations govern marketing claims in the United States.
- Pharmacies:Traditional retail and hospital pharmacy channels maintain dominance for prescription-classified injectable products.
- Health Stores:Specialty retail positions glutathione within broader antioxidant and detoxification supplement assortments.
Largest volume throughput: Online Retail. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic dermatology clinics in Seoul and Tokyo absorb the highest per-patient glutathione volumes globally, while fermentation capacity expansion concentrates in Chinese coastal provinces. Regulatory divergence between pharmaceutical and cosmetic classification pathways shapes market access conditions across every major jurisdiction.
China
Shenzhen and Shandong province manufacturers drive microbial fermentation scale-up for both export and domestic consumption. NMPA oversight of injectable products determines which suppliers qualify for hospital procurement channels. The Yangtze River Delta cluster hosts multiple cGMP-certified facilities serving pharmaceutical-grade demand.
Japan
PMDA pharmaceutical manufacturing rules enforce stringent purity standards that limit qualified supplier pools for clinical applications. Tokyo and Osaka cosmetic dermatology clinics set quality benchmarks that propagate to Southeast Asian markets. Fermentation specialists with decades of operational history anchor the domestic supply base.
South Korea
Seoul's aesthetic clinic corridor generates concentrated demand for high-purity injectable formulations. MFDS regulates both pharmaceutical and cosmetic product classifications, creating dual compliance requirements for market participants. Busan-Ulsan manufacturing zones support active ingredient production for regional export.
United States
FDA injectable oversight creates regulatory friction that limits parenteral product market penetration despite strong antioxidant therapy demand. Wellness centers and direct-to-consumer platforms drive oral formulation consumption through reduced regulatory pathways. California and New York health store networks represent the primary distribution infrastructure.
Brazil
Hospital networks in São Paulo and Rio de Janeiro pilot direct procurement contracts with East Asian manufacturers, bypassing traditional pharmaceutical wholesalers. ANVISA registration requirements determine supplier eligibility for public procurement channels. Latin American buyer concentration now commands volume pricing previously reserved for domestic East Asian purchasers.
Glutathione Market Vendor Landscape
Japanese producers anchor one tier; Chinese specialists hold manufacturing scale advantages. The supplier base organizes around fermentation expertise versus downstream formulation capabilities. Three archetypes dominate: legacy fermentation houses with decades of bioreactor experience, scale-driven manufacturers optimizing unit economics, and biotechnology-led specialists deploying genetically optimized platforms. Competitive moves concentrate on capacity expansion in microbial synthesis infrastructure and direct sales channel development bypassing traditional distribution.
Within the legacy fermentation tier, Kyowa Hakko Bio Co., Ltd. and KOHJIN Life Sciences Co., Ltd. occupy positions reflecting decades of operational specialization in yeast-derived production methods. Shenzhen GSH Bio-Technology Co., Ltd. exemplifies the scale-driven archetype, with geographic naming indicating concentrated manufacturing presence in China's southern coastal province. These three entities represent the structural segmentation between biotechnology-led premium positioning and volume-oriented supply expansion.
| Leading Market Players |
|---|
| Showa Denko K.K. |
| Shenzhen GSH Bio-Technology Co., Ltd. |
| Kyowa Hakko Bio Co., Ltd. |
| Mitsubishi Tanabe Pharma Corporation |
| Kyungdong Pharmaceutical Co., Ltd. |
| Shandong Jincheng Biological Pharmaceutical Co., Ltd. |
| Kaiping Genuine Biochemical Pharmaceutical Co., Ltd. |
| NOW Health Group, Inc. |
| KOHJIN Life Sciences Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Cysteine feedstock price volatility cascades through glutathione manufacturing tiers, compressing margins for fermentation-based producers while pharmaceutical-grade certification requirements sustain premium pricing for qualified suppliers. The interaction between amino acid input costs and cGMP compliance investments creates three distinct pricing bands that separate injectable-grade supply from cosmetic and nutritional grades.
Pricing Analysis
Volume throughput concentrates in oral formulations where reduced regulatory friction enables commodity-like pricing, while injectable-grade supply commands substantial premiums tied to PMDA and FDA certification tiers. Price differentiation hinges on endotoxin testing protocols and pyrogen validation standards that extend facility qualification timelines. Pricing pressure stems from Chinese manufacturing scale expansion that is compressing unit economics for standard-grade material. Wellness centers and homecare consumers exhibit highest price sensitivity, whereas Seoul and Tokyo cosmetic dermatology clinics absorb premium markups with minimal volume elasticity.
Supply Chain Analysis
Regional distribution centers in Busan and Shanghai coordinate hub-and-spoke patterns that feed Southeast Asian and Latin American clinic networks. Manufacturing gravity centers on China, Japan, and South Korea, where microbial fermentation infrastructure draws from cysteine, yeast extract, and specialized enzyme catalyst inputs. Single-source vulnerability concentrates in East Asian fermentation capacity, exposing buyers to geographic disruption risks and trade policy friction. Distribution runs through direct sales channels that bypass traditional pharmaceutical wholesalers, with hospital networks in Brazil and Mexico piloting manufacturer contracts that capture margin previously allocated to intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation specialist scarcity constrains capacity expansion velocity, propping pricing for qualified suppliers across all grade tiers. This supply-constrained structure rewards early certification investments and long-term offtake commitments.
For Market Incumbents: Anticipate margin compression from CRISPR-edited yeast strain deployment by biotechnology-led competitors. Defensive moves center on backward integration into amino acid feedstock supply and capacity addition in cGMP-certified facilities serving PMDA and FDA channels. Certification investment in dual-jurisdiction dossiers protects against regulatory divergence between cosmetic and pharmaceutical classification pathways. For New Entrants and Emerging Players: Capture underpenetrated homecare antioxidant therapy demand in Germany and France where aging populations sustain oral formulation consumption outside clinical channels. The most penetrable segment lies in nutraceutical e-commerce platforms that bypass traditional pharmacy distribution. Go-to-market execution should prioritize direct-to-consumer models with first-party data capture and subscription-based replenishment. For Investors and Strategic Acquirers: Distressed-cycle entries favor scale-driven manufacturers with established SAMR and ANVISA registrations in China's coastal provinces and Brazil's hospital procurement corridors. Long-term viability over the projection horizon hinges on continuous fermentation technology integration and genetically optimized microbial platform deployment. The signal to watch is CRISPR-edited yeast strain adoption rates among Seoul and Tokyo cosmetic dermatology clinics as inflection indicator for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Facility Qualification | PMDA and FDA certification unlocks injectable-grade pricing tiers in clinical channels. |
| CRISPR Yeast Strain Integration | Genetically optimized platforms from KOHJIN Life Sciences reduce batch-to-batch variation. |
| Direct Hospital Contracting | São Paulo and Rio de Janeiro networks bypass wholesalers to capture volume pricing. |
| Cysteine Feedstock Integration | Backward control over amino acid supply buffers cost volatility for fermentation operations. |
| E-commerce Platform Launch | Direct-to-consumer models in North America capture repeat purchase loyalty and margin. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among fermentation process engineers, cosmetic dermatology clinic procurement managers, pharmaceutical regulatory affairs leads, and nutraceutical distribution channel partners. NMPA, PMDA, and FDA submission databases combined with EMA pharmacovigilance reports and ANVISA registration records provided validation layers. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end user dimensions.
Granularity-level modeling captured injectable, oral, and topical form segments alongside skin lightening, antioxidant therapy, and detoxification applications, with hospital, clinic, wellness center, and homecare end users tracked separately. CAGRs derived from regression analysis of historical capacity expansion, regulatory approval timelines, and procurement pattern shifts. Forecast inputs incorporated CRISPR-edited yeast strain adoption curves, continuous fermentation technology deployment rates, and direct sales channel penetration metrics.
The model holds under stable cysteine feedstock availability and sustained East Asian manufacturing concentration; deviation in trade policy friction or regulatory reclassification of cosmetic-grade glutathione would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification timeline durations and clinic procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Food Grade Paraffin Market