
 Lanolin Market | 2026-2036
Lanolin Market Size, Share, and Industry Trends Forecast 2026-2036
Lanolin Market Analysis
Skilled refining technicians in lanolin fractionation is rotating toward biopharmaceutical-grade production, tightening supply for traditional cosmetic applications. Croda International leverages backward integration into wool grease sourcing to secure feedstock continuity. Deutsche Lanolin Gesellschaft anchors European pharmaceutical supply chains with dedicated anhydrous lanolin capacity. Nippon Fine Chemical specializes in ultra-high-purity grades for sensitive dermatological markets.
Lanolin is a complex lipid mixture derived from sheep wool grease, comprising esters, diesters, hydroxy esters, and free alcohols with melting points typically between 36°C and 42°C; it functions primarily as an emollient, emulsifier, and moisture-retention agent across cosmetic and pharmaceutical formulations. Anhydrous lanolin commands premium positioning due to its superior occlusive properties in wound-care ointments and nipple creams, while lanolin alcohol serves as the workhorse emulsifier base in mass-market moisturizers. Refined lanolin occupies the volume tier, though margin compression intensifies as Asian processors scale hydrous-to-anhydrous upgrading capacity.
REACH registration requirements in Europe and USP-NF monograph standards in the United States constrain market entry by imposing heavy analytical documentation and batch-to-batch consistency protocols. EMA guidelines on topical excipient quality and FDA oversight of over-the-counter drug-cosmetic hybrids further segment competitive terrain by certification burden. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate reformulation costs and qualification timelines.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating volume among refiners capable of USP-NF and EP compliance, fundamentally restructuring competitive access in lanolin derivatives.
Growth Catalysts
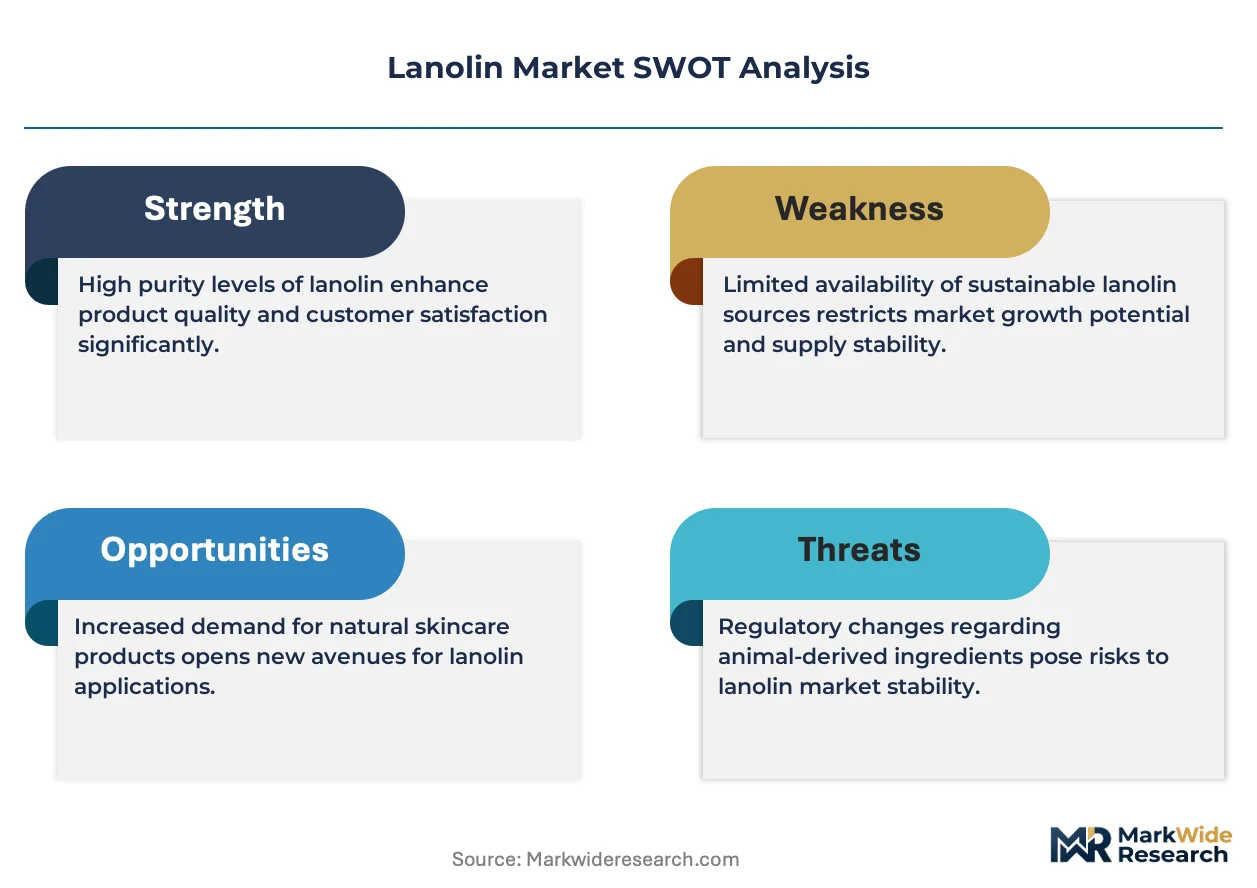
- REACH registration tiering:ECHA's differentiated dossier requirements for pharmaceutical versus cosmetic grades are accelerating investment in analytical infrastructure among European processors, widening the capability gap against non-compliant importers.
- Topical drug formulation expansion:Hydrocortisone and antifungal ointment pipelines are incorporating anhydrous lanolin as a primary excipient, pulling volume from cosmetic applications into higher-margin pharmaceutical channels.
- German refining cluster specialization:Concentrated technical expertise in Hamburg and Bremen corridors enables just-in-time pharmaceutical supply to continental European formulators, reducing qualification timelines for new drug submissions.
Market Restraints
- Wool grease feedstock volatility:Sheep flock reductions in Australia and New Zealand are tightening raw material availability, forcing refiners to absorb price swings or pass through to contract customers with 90-day lags.
- Substitution by synthetic emollients:Petrolatum and silicone alternatives are capturing mid-tier cosmetic formulations where occlusive performance requirements permit lower-cost inputs, pressuring refined lanolin volumes.
- Batch-to-batch consistency protocols:USP-NF monograph testing for acid value, saponification number, and pesticide residues imposes analytical burdens that exclude smaller Asian processors from pharmaceutical qualification.
Strategic Opportunities
- Biopharmaceutical-grade fractionation:Ultra-high-purity cholesterol and lanosterol derivatives for liposomal drug delivery systems command 4-6x refined lanolin pricing, rewarding capital deployment into molecular distillation capacity.
- Direct-to-formulator digital channels:Specialized chemical marketplaces are disintermediating traditional distributors for certified pharmaceutical grades, enabling margin capture and customer data ownership for mid-size refiners.
- EMA topical excipient quality guidelines:Evolving GMP expectations for wound-care and dermatological formulations are creating first-mover advantage for refiners with dedicated pharmaceutical production lines and dedicated quality systems.
Industry Challenges
- Skilled chromatography analyst shortage:Gas chromatography and HPLC expertise for sterol profiling and residual solvent verification is concentrating among aging technician cohorts in European refining hubs, constraining capacity expansion.
- Pharmacopeial harmonization delays:Divergent USP, EP, and JP specifications for peroxide value and water content force triple qualification runs for global pharmaceutical customers, extending time-to-revenue for new grades.
- Anhydrous upgrading capex intensity:Molecular sieve and thin-film evaporator investments for hydrous-to-anhydrous conversion require 18-24 month payback periods at current margin levels, freezing capacity decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lanolin Market |
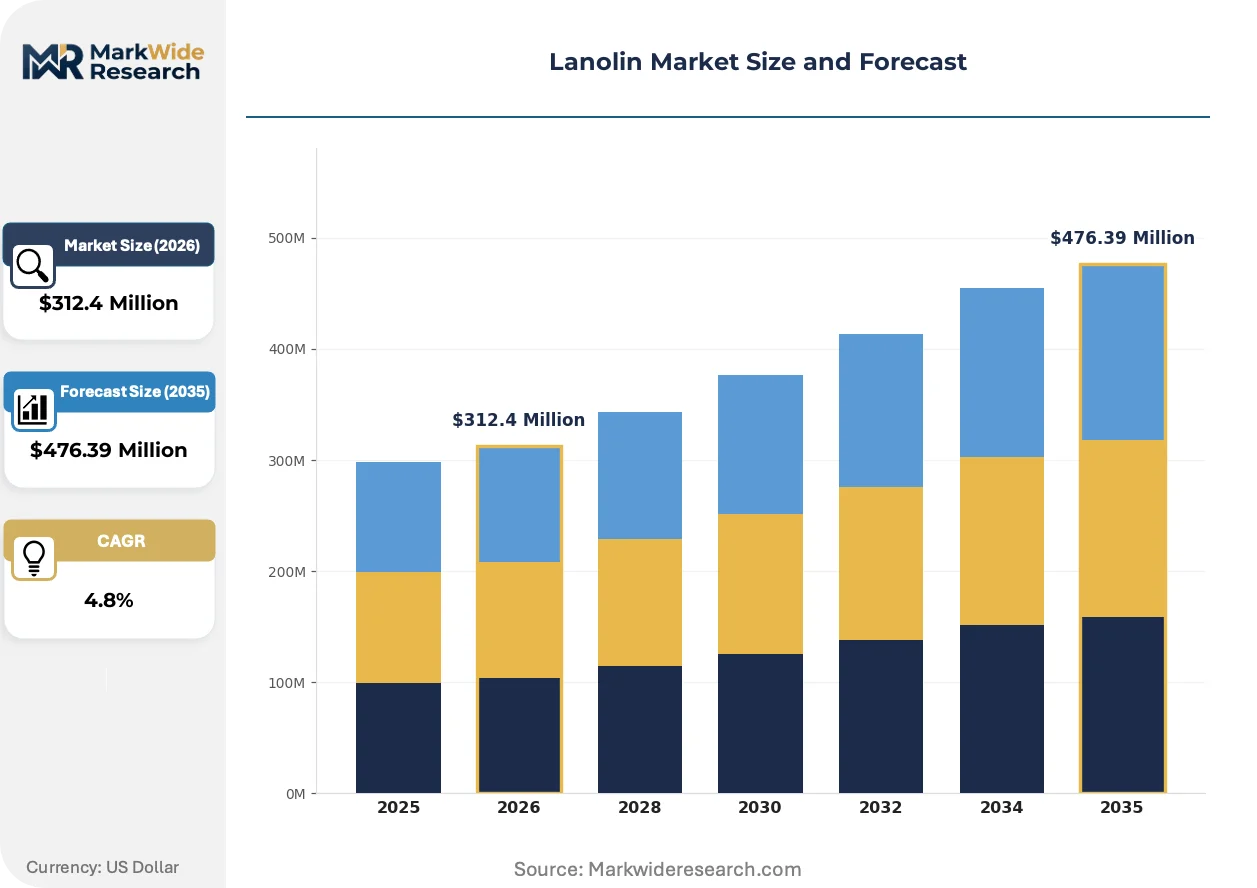
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lanolin Alcohol, Anhydrous Lanolin, Lanolin Oil, Refined Lanolin End User: Cosmetics Industry, Pharmaceutical Sector, Personal Care, Textile Industry Application: Moisturizers, Ointments, Creams, Lip Balms Form: Liquid, Cream, Paste, Powder |
| Companies Covered | Zhejiang Garden Biochemical High-Tech, Lanotec, Croda International, Rolex Lanolin Products Limited, Weleda, The Lubrizol Corporation, NK Chemicals, Deutsche Lanolin Gesellschaft, Nippon Fine Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lanolin Market Emerging Trajectories
Supercritical CO2 extraction and enzymatic interesterification are displacing traditional solvent-based refining, enabling pesticide-free certification while reducing thermal degradation of heat-sensitive sterol fractions.
Supercritical CO2 extraction technology is bifurcating the premium segment from commodity grades by eliminating hexane residues and enabling organic certification. Pharmaceutical formulators in Germany and Switzerland are specifying CO2-derived lanolin for pediatric and mucosal applications, compressing demand for conventional solvent-refined material in sensitive-use categories.
EMA's 2023 revision to topical excipient GMP guidance is mandating dedicated production lines for pharmaceutical versus cosmetic grades, forcing capital reallocation among multi-purpose refiners. German and French processors with existing pharmaceutical infrastructure are capturing qualification-driven switching from competitors lacking segregated capacity, while Italian and Spanish facilities face 12-18 month upgrade timelines.
Formulator procurement is consolidating annual volumes among fewer qualified suppliers to secure batch consistency and reduce audit burden. Mid-size European cosmetics houses are abandoning spot purchasing for pharmaceutical-grade material, instead negotiating 24-36 month supply agreements with German and Dutch refiners holding dual USP-EP certification, concentrating volume among proven performers.
Lanolin Market Segmentation
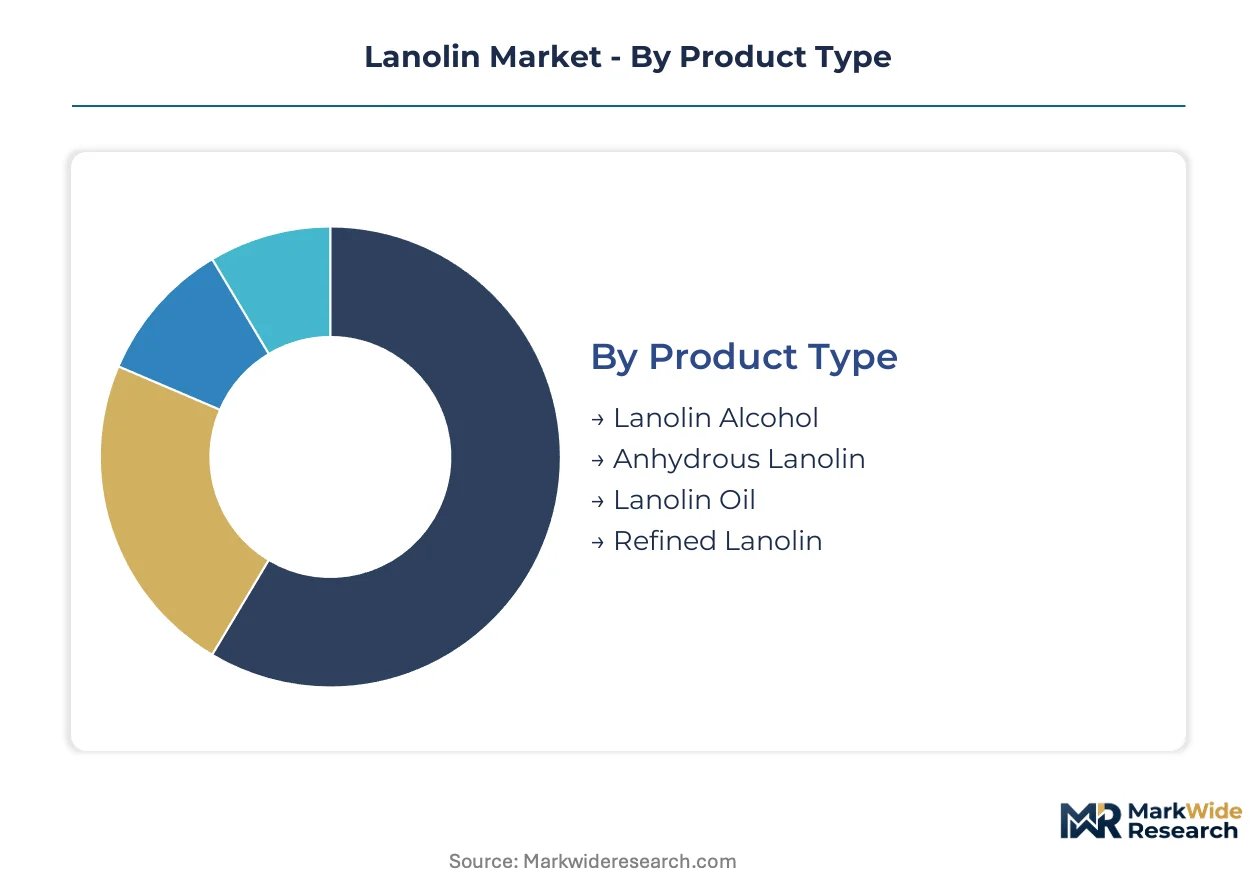
Segmentation in lanolin markets tracks how regulatory certification tiers split demand across price-performance bands. Pharmaceutical-grade specifications from USP-NF and EP monographs create rigid qualification boundaries that reshape competitive positioning within each category.
Product Type:
REACH registration tiering and USP-NF monograph standards impose divergent purity benchmarks that stratify product categories by analytical documentation burden and batch-to-batch consistency protocols.
- Anhydrous Lanolin:This ultra-refined grade contains less than 0.25% water content and delivers superior occlusive properties for wound-care ointments and nipple creams. Demand concentrates in German pharmaceutical corridors serving continental European formulators, driven by EMA topical excipient quality guidelines mandating dedicated production lines.
- Lanolin Alcohol:A fractionated derivative comprising primarily aliphatic alcohols with emulsifying properties, this segment functions as the workhorse base in mass-market moisturizers. Volume clusters in cosmetics applications where cost-performance ratios favor multi-functional emulsifiers over premium-grade alternatives.
- Refined Lanolin:Standard-grade material occupies the volume tier with broader specification tolerances.
- Lanolin Oil:Lower-viscosity liquid fraction serves specialized lubrication and conditioning applications.
Anhydrous lanolin handles the majority of throughput in pharmaceutical channels; lanolin alcohol is expanding most quickly as cosmetics formulators seek multi-functional emulsifier solutions.
End User:
Customer procurement patterns diverge sharply between spot purchasing for cosmetic applications and long-term supply agreements for pharmaceutical qualification.
- Pharmaceutical Sector:Formulators of hydrocortisone and antifungal ointments specify anhydrous lanolin as a primary excipient, pulling volume into higher-margin channels with 24-36 month supply agreements. German and Dutch refiners with dual USP-EP certification capture this consolidated procurement.
- Cosmetics Industry:Mass-market moisturizers and emulsion products drive volume demand for lanolin alcohol and refined grades. Asian processors scaling hydrous-to-anhydrous upgrading capacity are compressing margins in this segment through cost-competitive supply.
- Personal Care:Consumer-facing balms and conditioning products utilize lower-specification grades.
- Textile Industry:Fiber conditioning and finishing applications represent a specialized niche with distinct technical requirements.
Pharmaceutical sector procurement commands the steepest pricing tier; cosmetics industry volume is climbing the fastest as Asian capacity expansion reshapes supply dynamics.
Application:
Functional performance requirements in finished formulations determine grade selection and supplier qualification pathways.
- Ointments:Occlusive performance demands drive specification toward anhydrous grades with superior moisture-retention characteristics for wound-care and dermatological applications. Pediatric and mucosal formulations in Switzerland and Germany increasingly specify supercritical CO2-derived material.
- Moisturizers:Mass-market emulsion products favor lanolin alcohol for its dual emollient-emulsifier functionality, with procurement consolidating among fewer qualified suppliers to reduce audit burden.
- Creams:Intermediate viscosity requirements accommodate broader grade flexibility.
- Lip Balms:Small-format applications prioritize sensory properties and stability.
Ointments anchor pharmaceutical-grade demand; moisturizers represent the steepest expansion trajectory as formulators seek cost-optimized emulsifier solutions.
Form:
Physical state determines handling infrastructure, formulation compatibility, and processing economics across manufacturing environments.
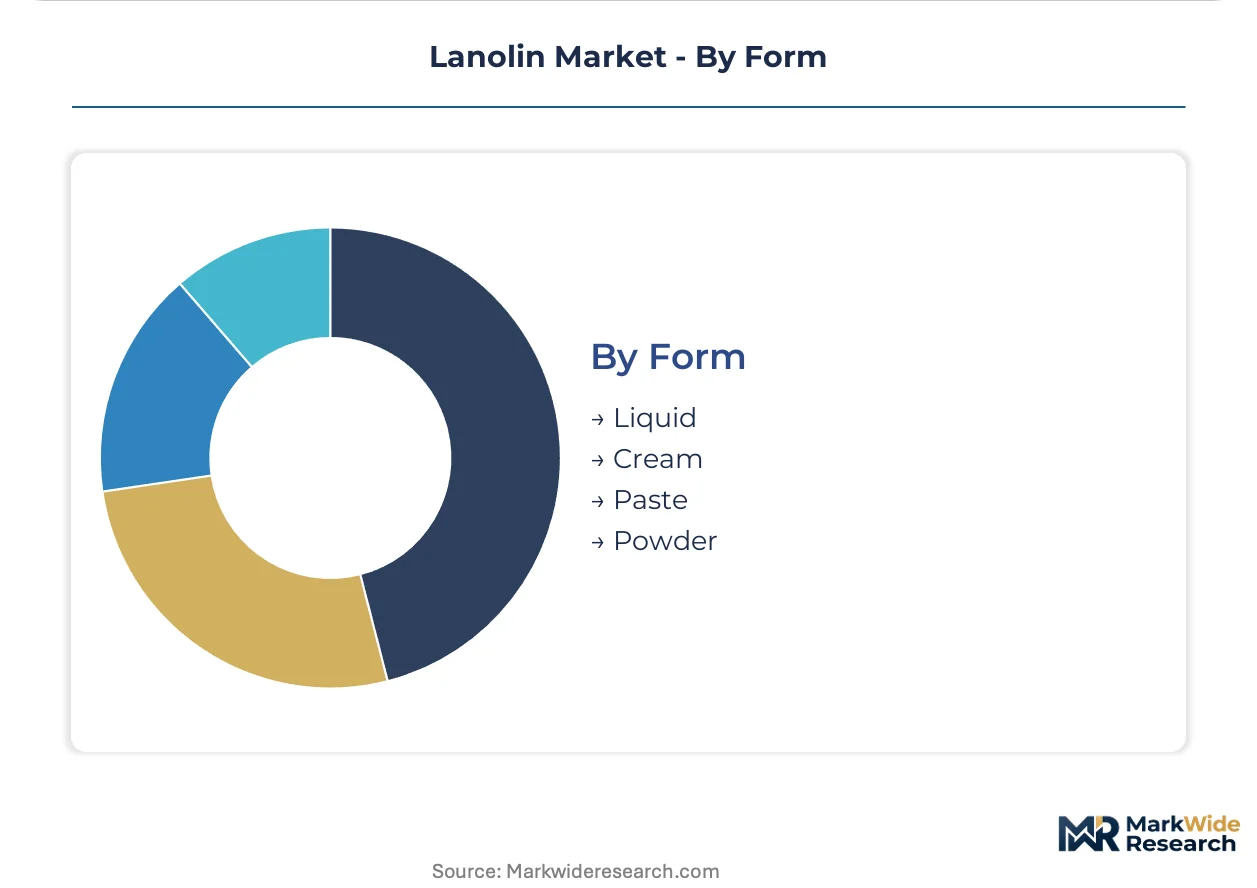
- Paste:Semi-solid consistency at ambient temperature suits traditional compounding operations and batch processing. German refining clusters in Hamburg and Bremen corridors optimize just-in-time paste supply to continental European formulators.
- Liquid:Reduced viscosity enables pumpable handling and continuous processing, with demand concentrating in high-throughput cosmetic manufacturing. Enzymatic interesterification technologies are displacing conventional refining for liquid-grade production.
- Cream:Pre-emulsified formats reduce manufacturing complexity for mid-tier formulators.
- Powder:Solid-state handling suits specialized dry-blend applications with extended shelf stability.
Paste form handles the majority of pharmaceutical throughput; liquid form is gaining share fastest as continuous processing adoption accelerates in cosmetics manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's topical excipient guidelines anchor pharmaceutical-grade demand in Germany, while REACH tiering and USP-NF standards create divergent compliance pathways across major processing economies. Supply chain configuration concentrates in refining clusters with dual-certification capability.
Germany
Hydrocortisone and antifungal ointment pipelines pull anhydrous lanolin into higher-margin pharmaceutical channels. REACH registration tiering accelerates investment in analytical infrastructure among Hamburg and Bremen processors. Deutsche Lanolin Gesellschaft anchors continental European supply with dedicated pharmaceutical-grade capacity serving Swiss and French formulators.
United States
Over-the-counter drug-cosmetic hybrids drive USP-NF monograph compliance demand for wound-care and nipple cream formulations. FDA oversight of topical excipients segments competitive terrain by certification burden. New Jersey and Pennsylvania refining corridors specialize in just-in-time supply to domestic pharmaceutical contract manufacturers.
China
Asian processors scale hydrous-to-anhydrous upgrading capacity, compressing margins in refined lanolin tiers. NMPA standards for pharmaceutical excipients are tightening import requirements for domestic formulators. Zhejiang biochemical clusters dominate feedstock processing for regional cosmetic manufacturers.
Japan
Pediatric and mucosal applications specify supercritical CO2-derived grades, eliminating hexane residues for sensitive-use categories. PMDA guidelines on topical drug quality align with evolving USP-EP-JP pharmacopeial harmonization pressures. Osaka-based refiners specialize in ultra-high-purity cholesterol derivatives for liposomal delivery systems.
Australia
Sheep flock reductions tighten wool grease feedstock availability for Asia-Pacific refiners. TGA oversight of therapeutic goods creates qualification pathways for anhydrous grades in dermatological applications. Victorian wool processing corridors face raw material volatility forcing 90-day price lag contracts.
Lanolin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in lanolin fractionation. Croda International leverages backward integration into wool grease sourcing to secure feedstock continuity, while Deutsche Lanolin Gesellschaft anchors European pharmaceutical supply chains with dedicated capacity. Competitive moves concentrate on dual USP-EP certification acquisition and molecular distillation capacity deployment for biopharmaceutical-grade derivatives.
Within the integrated leader tier, Croda International, Deutsche Lanolin Gesellschaft, and Nippon Fine Chemical exemplify divergent geographic anchoring strategies. The British specialty chemicals multinational represents backward integration into captive wool grease supply. The German GmbH occupies dedicated anhydrous pharmaceutical capacity serving EMA-compliant formulators. The Japanese specialist sits within ultra-high-purity dermatological positioning for sensitive mucosal applications.
| Leading Market Players |
|---|
| Zhejiang Garden Biochemical High-Tech |
| Lanotec |
| Croda International |
| Rolex Lanolin Products Limited |
| Weleda |
| The Lubrizol Corporation |
| NK Chemicals |
| Deutsche Lanolin Gesellschaft |
| Nippon Fine Chemical |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German pharmaceutical refiners and continental European formulators lock in both supply access and price visibility across the anhydrous lanolin tier, insulating qualified suppliers from spot market volatility while compressing margins for non-compliant processors.
Pricing Analysis
Geographic price spreads widen between Hamburg-Bremen pharmaceutical corridors and Asian hydrous upgrading hubs, with three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels. Certification burden under USP-NF and EP monographs drives price differentiation, while cost compression in refined lanolin intensifies as Zhejiang processors scale molecular sieve capacity. Cosmetic formulators exhibit highest price sensitivity; pediatric pharmaceutical buyers accept premium positioning for supercritical CO2-derived material.
Supply Chain Analysis
Ninety-day inventory buffers at Australian wool grease collection points extend lead times for Asia-Pacific refiners facing sheep flock reductions. Supply concentrates in Germany, China, and Australia, with feedstock sourcing drawn from Victorian wool processing corridors and Zhejiang biochemical clusters. Wool grease availability volatility represents the dominant supply chain risk. Distribution runs through specialized chemical marketplaces disintermediating traditional pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified chromatography analysts capable of sterol profiling and residual solvent verification represent the critical capability gap, with aging technician cohorts in European refining hubs constraining capacity expansion and batch-to-batch consistency protocols.
For Market Incumbents: Compound analytical infrastructure investments to widen the compliance gap against non-certified importers. Secure backward integration into wool grease sourcing to neutralize Australian feedstock volatility. Deploy molecular distillation capacity for biopharmaceutical-grade cholesterol derivatives before substitution by synthetic liposomal excipients accelerates.
For New Entrants and Emerging Players: Anchor in direct-to-formulator digital channels for certified pharmaceutical grades, bypassing distributor margin capture. Target cosmetics manufacturers in mid-tier European markets abandoning spot purchasing for 24-36 month supply agreements. Qualify under REACH registration tiering for cosmetic-grade entry before attempting USP-NF pharmaceutical compliance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among German and Dutch refiners holding dual USP-EP certification with dedicated pharmaceutical production lines. Long-term viability hinges on pharmacopeial harmonization progress between USP, EP, and JP standards. Monitor EMA topical excipient guideline revisions as inflection indicator for qualification-driven switching among formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wool Grease Sourcing | Croda International secures feedstock continuity against Australian flock reductions. |
| Molecular Distillation Capacity Deployment | Enables biopharmaceutical-grade fractionation commanding 4-6x refined lanolin pricing. |
| Dual USP-EP Certification Acquisition | Deutsche Lanolin Gesellschaft captures consolidated pharmaceutical procurement from cosmetics houses. |
| Supercritical CO2 Extraction Adoption | Eliminates hexane residues for pediatric formulations in Swiss and German markets. |
| Dedicated Pharmaceutical Production Lines | EMA GMP compliance mandates segregated capacity, freezing Italian and Spanish competitors. |
Methodological Framework
Initial hypotheses were tested against primary input from refining plant managers, pharmaceutical procurement leads at German formulators, cosmetic R&D directors, and wool grease sourcing specialists, and refined through secondary validation against REACH registration databases, USP-NF monograph revisions, EMA topical excipient guidelines, and customs trade data. Bottom-up capacity modeling triangulated against top-down demand segmentation.
Variance decomposition across grade tier, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity expansion timelines, pharmacopeial harmonization progress, and substitution elasticity parameters for synthetic emollients. Segmentation splits tracked anhydrous versus hydrous upgrading economics and pharmaceutical versus cosmetic qualification pathways.
Decision-makers should treat outputs as directional under assumptions of stable wool grease feedstock availability and continued EMA GMP enforcement; material deviation in Australian flock dynamics or pharmacopeial standard convergence would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Ethyl Polysilicate Market