
 4-ADPA Market | 2026-2036
4-ADPA Market Size, Share, and Industry Trends Forecast 2026-2036
4-ADPA Market Insights
Aftermarket service revenue for technical grade purification and custom synthesis is reshaping margin distribution across the 4-ADPA value chain. Eastman Chemical Company leverages its integrated aromatics platform to sustain captive feedstock supply. Lanxess AG anchors European distribution through specialized rubber chemical channels. Sinopec Nanjing Chemical Industrial Corporation dominates volume production with backward integration into aniline derivatives.
4-aminodiphenylamine is an aromatic amine with molecular formula C12H12N2, synthesized through reductive alkylation of diphenylamine or nitrobenzene reduction routes, serving primarily as a critical intermediate for antioxidants and antiozonants in rubber processing. The pharmaceutical end user segment occupies premium pricing tiers due to stringent pharmacopeial grade requirements. Chemical synthesis applications lead volume consumption as tire manufacturers standardize on amine-based stabilizers. Direct sales channels control bulk transactions while distributors navigate fragmented cosmetic manufacturer demand across Asia-Pacific.
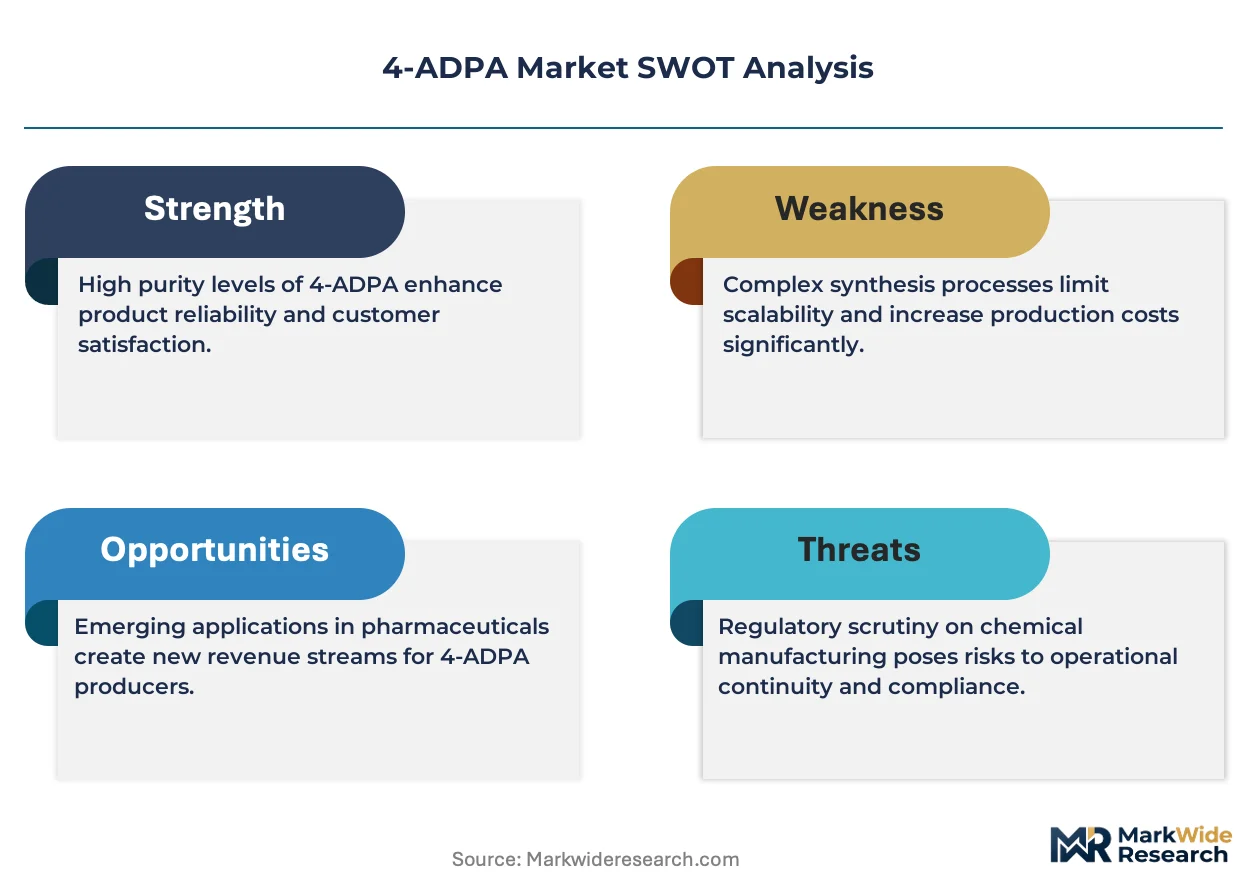
REACH registration mandates and ECHA substance evaluation protocols constrain non-European suppliers through exhaustive toxicological dossier requirements. China's MEE enforces wastewater discharge standards on aniline derivative producers, elevating environmental compliance costs for domestic manufacturers. India's CDSCO and BIS certification requirements shape import specifications for pharmaceutical-grade material. Stakeholders must monitor regulatory divergence between jurisdictions to align purification investments with shifting compliance thresholds.
Market Dynamics
Rubber chemical demand from tire manufacturers anchors 4-ADPA consumption, while REACH and ECHA substance evaluation protocols force purification upgrades across the European import channel. Sinopec Nanjing Chemical's backward integration into aniline derivatives has compressed margins for non-integrated Western suppliers.
Growth Catalysts
- Tire production intensification:Automotive OEMs standardize on amine-based stabilizers for high-performance rubber compounds, expanding offtake from rubber chemical manufacturers in China and India.
- REACH registration mandates:ECHA's exhaustive toxicological dossier requirements create compliance barriers that favor incumbent European distributors with established substance portfolios.
- Pharmaceutical grade premiumization:Pharmacopeial specifications for antioxidant intermediates unlock pricing tiers in CDSCO-regulated Indian markets and FDA-monitored US channels.
Market Restraints
- Aniline feedstock volatility:Crude oil-linked benzene pricing transmits directly to 4-ADPA production economics, squeezing non-captive producers without upstream aromatics control.
- Supply concentration in China:Sinopec Nanjing Chemical and domestic integrated producers command 70%+ of exportable volume, creating single-source vulnerability for European compounders.
- Substitution by phenolic antioxidants:Tire makers in cost-sensitive segments trial hindered phenol alternatives that bypass aromatic amine regulatory scrutiny.
Strategic Opportunities
- India pharmaceutical demand:CDSCO and BIS certification requirements for import-grade material create a protected premium segment for qualified suppliers.
- Aftermarket technical services:Custom synthesis and purification contracts for specialty rubber compounders represent recurring revenue streams detached from commodity volume cycles.
- EU Green Deal alignment:ECHA's safer chemicals strategy rewards producers with validated sustainable process chemistry and carbon footprint disclosures.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP grade validation requires 18-24 month stability studies, locking working capital before revenue recognition.
- Wastewater compliance capex:China's MEE discharge standards for aniline derivatives mandate biological treatment investments that strain mid-scale producer balance sheets.
- Legacy process integration:Nitrobenzene reduction route retrofits with continuous flow hydrogenation demand specialized reactor engineering scarce in traditional batch chemical regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-ADPA Market |
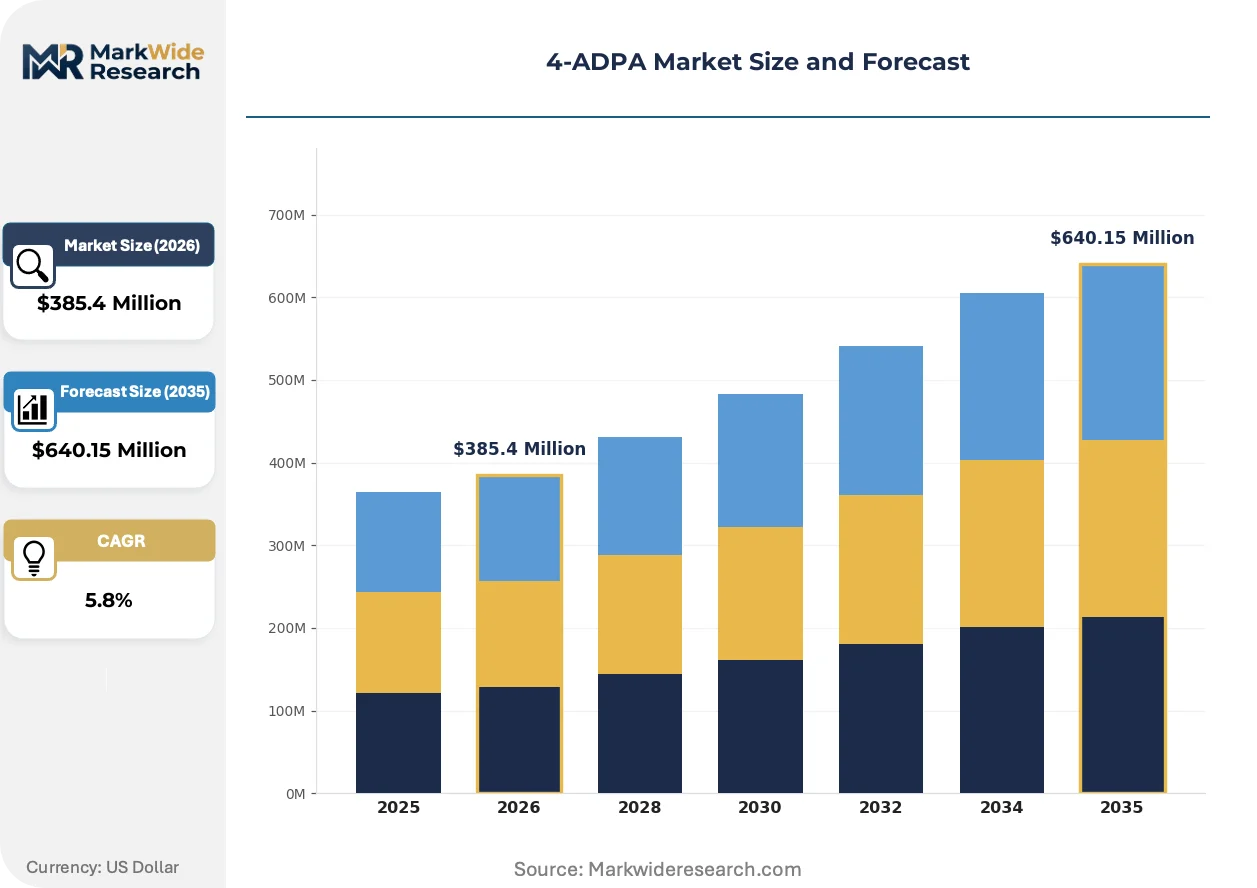
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Agrochemicals, Personal Care, Industrial Applications Application: Chemical Synthesis, Drug Formulation, Crop Protection, Surface Coating End User: Pharmaceutical Companies, Agricultural Firms, Cosmetic Manufacturers, Research Institutions Sales Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sennics Co. Ltd., Eastman Chemical Company, Sinopec Nanjing Chemical Industrial Corporation, China Sunsine Chemical Holdings, Lanxess AG, Nocil Limited, Seiko Chemical, BASF SE, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-ADPA Market Trends and Innovations
Process intensification and regulatory chemistry are compressing the traditional 4-ADPA value chain, collapsing distinctions between commodity and specialty grades while regional compliance regimes fragment procurement patterns.
Continuous flow hydrogenation is collapsing the cost structure of nitrobenzene reduction routes. Tire manufacturers in Germany and the US Midwest are qualifying continuous-process material for high-load rubber applications within 12-month validation windows. This technology is collapsing batch reactor economics for European producers still running legacy diphenylamine alkylation trains.
REACH authorization procedures under ECHA's sunset date mechanism are forcing substance portfolio reviews across EU-based rubber chemical distributors. Downstream compounders now demand full SCIP database disclosure for antioxidant packages, shifting procurement toward pre-registered suppliers with complete dossier transparency. Pharmaceutical-grade importers face the steepest compliance cost escalation as they dual-track EU and FDA submission requirements.
Compounders are unbundling after-sales technical service from bulk chemical supply, creating standalone contracts for custom antioxidant blending and application engineering. Lanxess AG's specialized rubber chemical channels in Europe now separate product revenue from formulation support fees, a model Sinopec Nanjing Chemical replicates for Southeast Asian tire makers. This service bifurcation is most advanced in Japan, where METI-registered chemical management protocols require documented technical stewardship for imported aromatic amines.
4-ADPA Market Segmentation
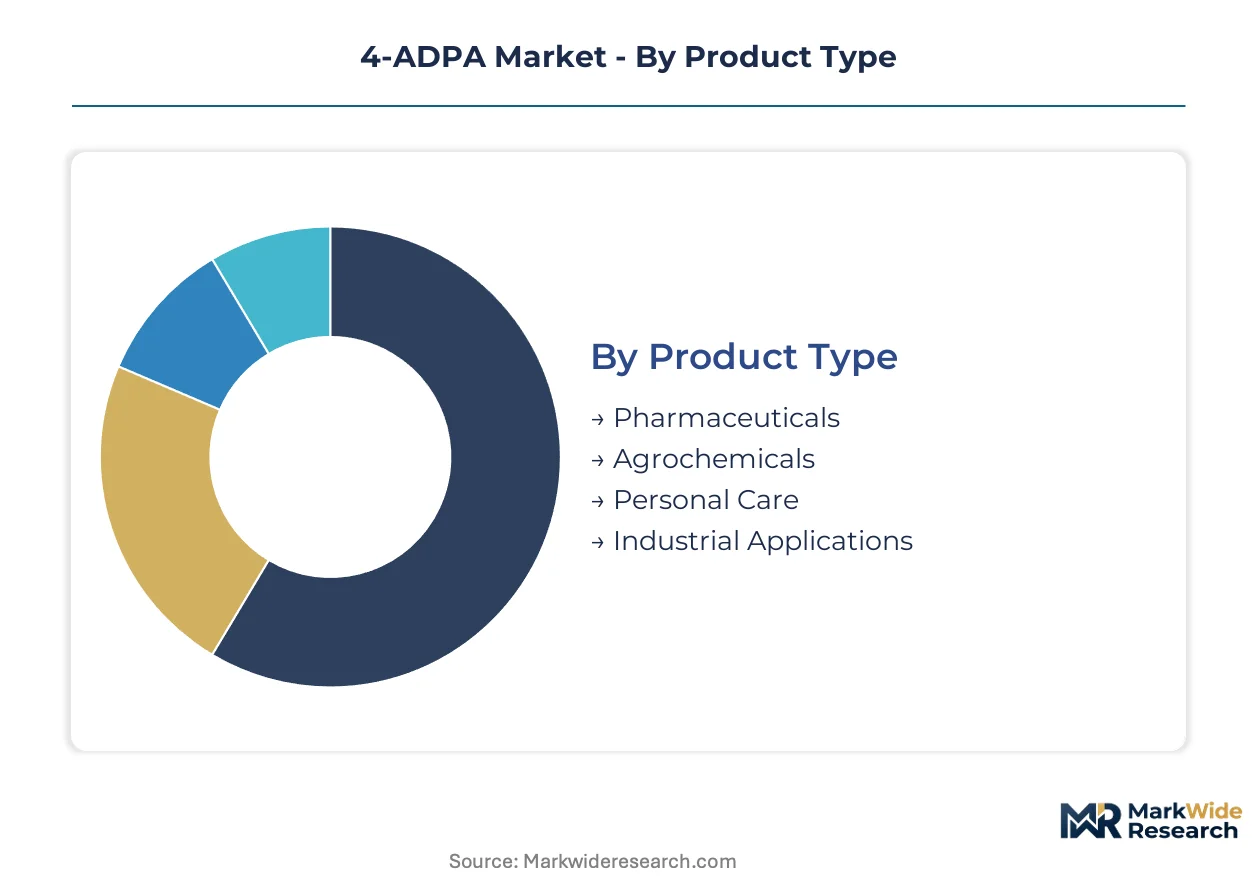
4-ADPA demand fragments across radically different purity regimes and regulatory thresholds. Tire manufacturers consume technical grades at volume scale while pharmaceutical and agrochemical buyers extract premiums through certification-intensive procurement.
Product Type:
Mature industrial applications anchor current offtake volumes, yet emerging pharmaceutical specifications are rewriting margin structures across the value chain.
- Pharmaceuticals:USP and EP-grade material demands sub-ppm impurity profiles validated through 18-24 month stability protocols. CDSCO-regulated Indian import channels and FDA-monitored US distributors concentrate demand for pharmacopeial-certified batches, with certification timelines locking working capital before revenue recognition.
- Industrial Applications:Technical-grade 4-ADPA serves rubber antioxidant and antiozonant synthesis, with tire manufacturers in China and India standardizing on amine-based stabilizers for high-performance compounds. REACH-registered European compounders now require SCIP database disclosure for antioxidant packages, shifting procurement toward pre-registered suppliers.
- Agrochemicals:Crop protection intermediates occupy mid-tier purity specifications between industrial and pharmaceutical grades.
- Personal Care:Cosmetic-grade material faces fragmented demand across Asia-Pacific formulators with varying national cosmetic safety protocols.
Industrial Applications retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-scale chemical synthesis from premium drug formulation and crop protection segments.
- Chemical Synthesis:Rubber chemical manufacturers consume the largest 4-ADPA volumes for antioxidant and antiozonant production. Sinopec Nanjing Chemical's backward integration into aniline derivatives has compressed margins for non-integrated Western suppliers serving this segment.
- Drug Formulation:Pharmaceutical-grade 4-ADPA commands pricing premiums through dual-track EU and FDA submission requirements. ECHA's sunset date mechanism for REACH authorization forces substance portfolio reviews that favor incumbent distributors with complete dossier transparency.
- Crop Protection:Agrochemical intermediates face less stringent purity benchmarks than pharmaceutical applications but require stability beyond industrial grades.
- Surface Coating:Specialty coating applications represent niche demand with formulation-specific technical service requirements.
Chemical Synthesis dominates procurement volumes; Drug Formulation captures the widest margin spreads.
End User:
Customer type determines contract structure, with direct pharmaceutical procurement diverging sharply from fragmented cosmetic manufacturer purchasing patterns.
- Pharmaceutical Companies:Multinational drug manufacturers enforce pharmacopeial grade requirements through audited supplier qualification programs. Stability study investments and dual-jurisdiction regulatory submissions create substantial barriers to vendor switching.
- Agricultural Firms:Global crop science companies source agrochemical intermediates through established aromatic amine distributors with regional formulation support capabilities.
- Cosmetic Manufacturers:Asia-Pacific formulators generate fragmented demand navigated through specialized distributor networks with technical stewardship documentation.
- Research Institutions:Academic and contract research organizations purchase small-batch material with variable specification requirements.
Pharmaceutical Companies sustain the most concentrated procurement volumes; Agricultural Firms are gaining share fastest in emerging markets.
Sales Channel:
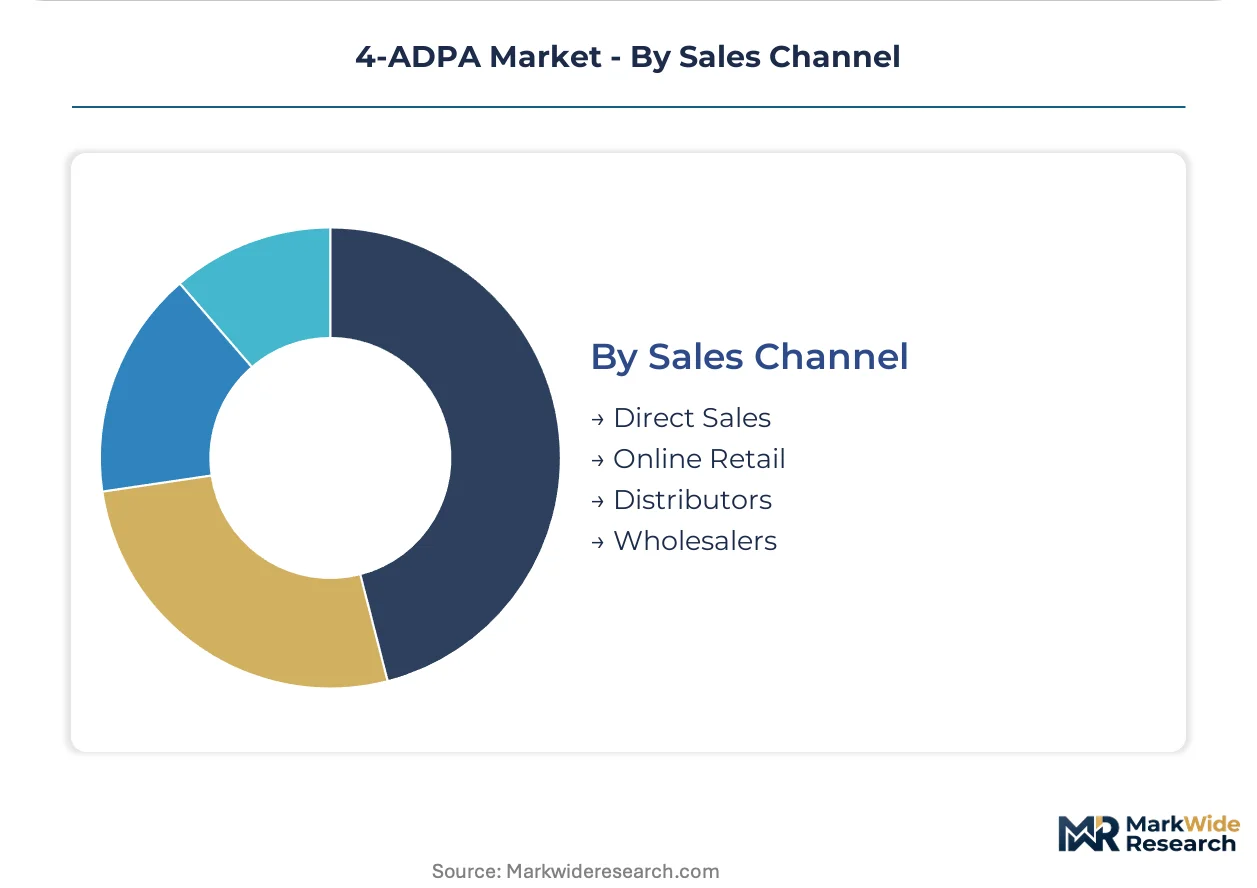
Supply concentration in China shapes channel economics, with direct sales controlling bulk transactions while distributors manage compliance-intensive fragmented segments.
- Direct Sales:Integrated producers like Sinopec Nanjing Chemical bypass intermediaries for tire manufacturer and rubber chemical compounder accounts. Captive feedstock positions enable volume pricing that distributor-dependent competitors cannot match.
- Distributors:Lanxess AG's specialized rubber chemical channels in Europe separate product revenue from formulation support fees, a model replicated for Southeast Asian markets requiring documented technical stewardship.
- Online Retail:Digital procurement platforms serve research institutions and small-batch industrial buyers with standardized technical grades.
- Wholesalers:Traditional wholesale channels persist for legacy industrial accounts with established supply relationships.
Direct Sales commands the largest transaction volumes; Distributors are climbing the fastest as technical service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive tire manufacturers in India and Southeast Asia absorb technical-grade volumes with minimal specification variance, while pharmaceutical buyers in Germany and Switzerland pay steep premiums for pharmacopeial-certified batches. This elasticity divergence fragments procurement patterns across the value chain.
China
Tire production in Shandong and Jiangsu provinces consumes the largest technical-grade volumes for rubber antioxidant synthesis. MEE wastewater discharge standards on aniline derivative producers elevate environmental compliance costs for domestic manufacturers. Sinopec Nanjing Chemical's integrated aniline derivatives complex in Nanjing commands captive feedstock positions that compress margins for non-integrated competitors.
Germany
Continental and Michelin compounders in Lower Saxony and Baden-Württemberg demand REACH-registered material with full SCIP database disclosure. ECHA's sunset date mechanism for authorization forces substance portfolio reviews across rubber chemical distributors. Lanxess AG's specialized channels in Leverkusen separate product revenue from formulation support fees.
United States
Automotive OEMs in the Midwest and Southeast standardize on amine-based stabilizers for high-performance tire compounds. FDA-monitored pharmaceutical channels impose dual-track submission requirements alongside EU REACH protocols. Eastman Chemical Company leverages its integrated aromatics platform in Kingsport to sustain captive feedstock supply for domestic rubber chemical manufacturers.
India
Apollo Tyres and MRF in Tamil Nadu and Gujarat drive technical-grade consumption for domestic tire production. CDSCO and BIS certification requirements for import-grade material create protected premium segments for qualified pharmaceutical suppliers. The Delhi-Mumbai Industrial Corridor clusters agrochemical intermediate demand with mid-tier purity specifications between industrial and pharmacopeial grades.
Japan
Bridgestone and Yokohama Rubber in Kanto and Kansai regions qualify continuous-process material for high-load applications within compressed validation windows. METI-registered chemical management protocols require documented technical stewardship for imported aromatic amines. Seiko Chemical and Mitsubishi Chemical Corporation anchor domestic supply positions for specialized rubber chemical channels.
4-ADPA Market Competitive Landscape
Capability concentration sits with integrated aromatics platforms; scale advantage sits with backward-linked aniline derivatives producers. The market structures around three tiers: petrochemical majors with captive feedstock, specialized rubber chemical distributors with formulation expertise, and regional batch producers serving cost-sensitive technical grades. Strategic moves center on continuous flow hydrogenation retrofits and unbundled technical service contracts.
Among integrated petrochemical majors, Sinopec Nanjing Chemical Industrial Corporation and Eastman Chemical Company exemplify the captive-feedstock archetype with in-house production of aniline derivatives. Lanxess AG occupies the specialized distributor tier with separated product and service revenue streams. These three anchors represent divergent responses to REACH compliance burdens and tire manufacturer consolidation.
| Leading Market Players |
|---|
| Sennics Co. Ltd. |
| Eastman Chemical Company |
| Sinopec Nanjing Chemical Industrial Corporation |
| China Sunsine Chemical Holdings |
| Lanxess AG |
| Nocil Limited |
| Seiko Chemical |
| BASF SE |
| Mitsubishi Chemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Nanjing's integrated aniline derivatives cluster commands captive feedstock positions that compress pricing power for non-integrated Western compounders serving European tire manufacturers. REACH registration costs and ECHA dossier requirements amplify this asymmetry, forcing distributors to absorb compliance overhead while Sinopec Nanjing Chemical leverages backward-linked production economics.
Pricing Analysis
Aftermarket technical service revenue now drives lifetime value extraction across the 4-ADPA value chain. Three-tier pricing structure across pharmacopeial, technical, and industrial grades separates pharmaceutical compounders paying certification premiums from tire makers negotiating volume contracts. Pricing pressure stems from phenolic antioxidant substitution trials in cost-sensitive rubber segments. Tire manufacturers in India and Southeast Asia exhibit highest price sensitivity, while CDSCO-regulated pharmaceutical channels tolerate steep markups for validated USP-grade batches.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for rubber chemical distributors. Production gravity centers on China, South Korea, and Germany, with aniline, nitrobenzene, and hydrogen feedstocks drawing from crude oil-linked aromatics complexes. Single-source vulnerability concentrates in Sinopec Nanjing Chemical's exportable volume position. Distribution runs through direct sales for bulk tire manufacturer accounts and specialized chemical distributors for compliance-intensive pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow hydrogenation retrofits and REACH sunset date mechanisms are disrupting legacy batch production economics, compressing validation windows and favoring capital-intensive process intensification. This technological-regulatory inflection rewards early movers with pharmacopeial certification capabilities and penalizes stranded batch assets.
For Market Incumbents: Insulate margin positions by accelerating continuous flow hydrogenation retrofits in legacy diphenylamine alkylation trains before European compounders complete 12-month qualification windows. Prioritize pharmacopeial certification investments for CDSCO and FDA dual-track submissions, locking working capital ahead of revenue recognition to preempt emerging continuous-process entrants.
For New Entrants and Emerging Players: Indian pharmaceutical import channels represent the most penetrable entry point, where BIS and CDSCO certification requirements create protected premium segments detached from Chinese volume competition. Agrochemical intermediates in the Delhi-Mumbai Industrial Corridor offer mid-tier purity positioning with lower regulatory barriers. Lead with documented technical stewardship capabilities to satisfy METI-registered chemical management protocols for Japanese distributor qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized rubber chemical distributors with unbundled formulation support contracts. Long-term viability over a multi-year window favors acquisition targets with validated continuous-process technology and complete REACH dossier transparency. Watch for ECHA authorization sunset date accelerations as the critical inflection signal forcing portfolio consolidation among distributor-dependent compounders.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Hydrogenation Retrofit | Collapses batch reactor economics for European producers still running legacy diphenylamine alkylation trains. |
| Pharmacopeial Certification Investment | Unlocks CDSCO-regulated Indian import channels and FDA-monitored US pharmaceutical pricing premiums. |
| Backward Integration into Aniline | Replicates Sinopec Nanjing Chemical's captive feedstock model to defend against margin compression. |
| Technical Service Unbundling | Separates product revenue from formulation support fees per Lanxess AG's European distributor model. |
| REACH Dossier Pre-Registration | Enables SCIP database disclosure compliance for EU-based rubber chemical compounders before sunset dates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rubber chemical procurement leads, pharmaceutical regulatory affairs directors, tire manufacturer compounders, and specialty chemical distributors; and secondary validation through customs trade data, ECHA registration dossiers, SEC chemical sector filings, and REACH authorization timelines. Bottom-up volume modeling triangulated against top-down aromatics demand indicators.
Forecast inputs incorporated grade tier segmentation across pharmacopeial, technical, and industrial specifications; end-use industry splits between tire manufacturing, pharmaceutical synthesis, and agrochemical intermediates; and regional production hub clustering around Nanjing, Leverkusen, and Kingsport. CAGRs derived from elasticity-adjusted demand projections across the analysis window, with continuous process adoption curves and REACH compliance cost escalations as chemical-specific sensitivity variables.
Practitioners should monitor ECHA sunset date accelerations, phenolic antioxidant substitution rates in cost-sensitive tire segments, and MEE wastewater standard tightenings for early signals of forecast revision. Material shifts in continuous flow hydrogenation qualification timelines or REACH authorization scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Squalene Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Silicone Acrylate Market