
 Hydration Packs Market | 2026-2036
Hydration Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Hydration Packs Market Foresight
Modular reservoir-to-vest attachment systems is rebalancing how endurance athletes configure their gear for race-day conditions. CamelBak leverages its reservoir engineering heritage to sustain leadership in military and civilian crossover designs. Osprey anchors its position through anatomically framed back panels that differentiate load distribution across multi-hour efforts. Source Tactical Gear specializes in battlefield-proven durability standards that extend its appeal into law enforcement and emergency response channels.
Hydration packs are portable fluid delivery systems comprising a flexible reservoir, drinking tube, and bite valve, typically constructed from TPU or food-grade vinyl with antimicrobial treatments to prevent biofilm accumulation; their primary purpose is to enable hands-free hydration during continuous physical activity where bottle access proves impractical. Backpack configurations dominate volume sales among casual hikers and day-trippers, while hydration vests capture the fastest expansion among trail runners and ultramarathon participants who prioritize minimal bounce and front-pocket nutrition storage. Polyester shell fabrics occupy the largest material share due to cost-efficient abrasion resistance, though nylon weaves command premium positioning in alpine and expedition-grade applications.
REACH compliance in Europe restricts phthalate plasticizers in TPU bladder production, elevating testing costs for manufacturers serving EU distribution channels. FDA food-contact material standards govern reservoir and tube compositions in the United States, creating a dual-certification burden for brands operating transatlantically. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that threaten to impose end-of-life collection obligations on soft-goods manufacturers.
Market Dynamics
Modular attachment architectures and REACH-mandated material substitutions are compressing product development cycles while elevating compliance costs for reservoir manufacturers serving European distribution channels.
Growth Catalysts
- Trail running participation:Ultramarathon and skyrunning event calendars in Colorado and Chamonix are pulling recreational athletes toward vest-style hydration systems with front-mounted soft flasks.
- REACH chemical safety mandates:Phthalate restrictions in TPU bladder production are accelerating adoption of bio-based polyurethane alternatives certified for EU food-contact applications.
- Alpine manufacturing clustering:Technical outdoor gear production concentrates in Germany's Bavarian corridor, creating supplier density that reduces lead times for specialized reservoir components.
Market Restraints
- Petrochemical input volatility:TPU resin prices fluctuate with crude oil benchmarks, compressing margin stability for bladder manufacturers without long-term polymer supply contracts.
- Single-source geographic concentration:Precision-molded bite valve production clusters in southern China, exposing brands to port congestion and tariff uncertainty.
- Hydrogen peroxide degradation:Antimicrobial treatments in reservoir linings degrade under UV exposure, limiting product lifespan in high-altitude expedition use cases.
Strategic Opportunities
- India outdoor retail expansion:Himalayan trekking operators in Uttarakhand and Himachal Pradesh represent underpenetrated demand for expedition-grade reservoir systems.
- Extended Producer Responsibility tailwinds:California's SB 54 packaging mandates create first-mover advantage for brands with closed-loop bladder recycling programs.
- Smart hydration convergence:Integration of flow-rate sensors with mobile fitness apps is opening premium pricing tiers among data-driven endurance athletes.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for food-grade TPU with antimicrobial properties concentrates among aging technical specialists in European material science programs.
- Dual-certification timeline compression:Simultaneous FDA food-contact and REACH compliance testing extends product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Packs Market |
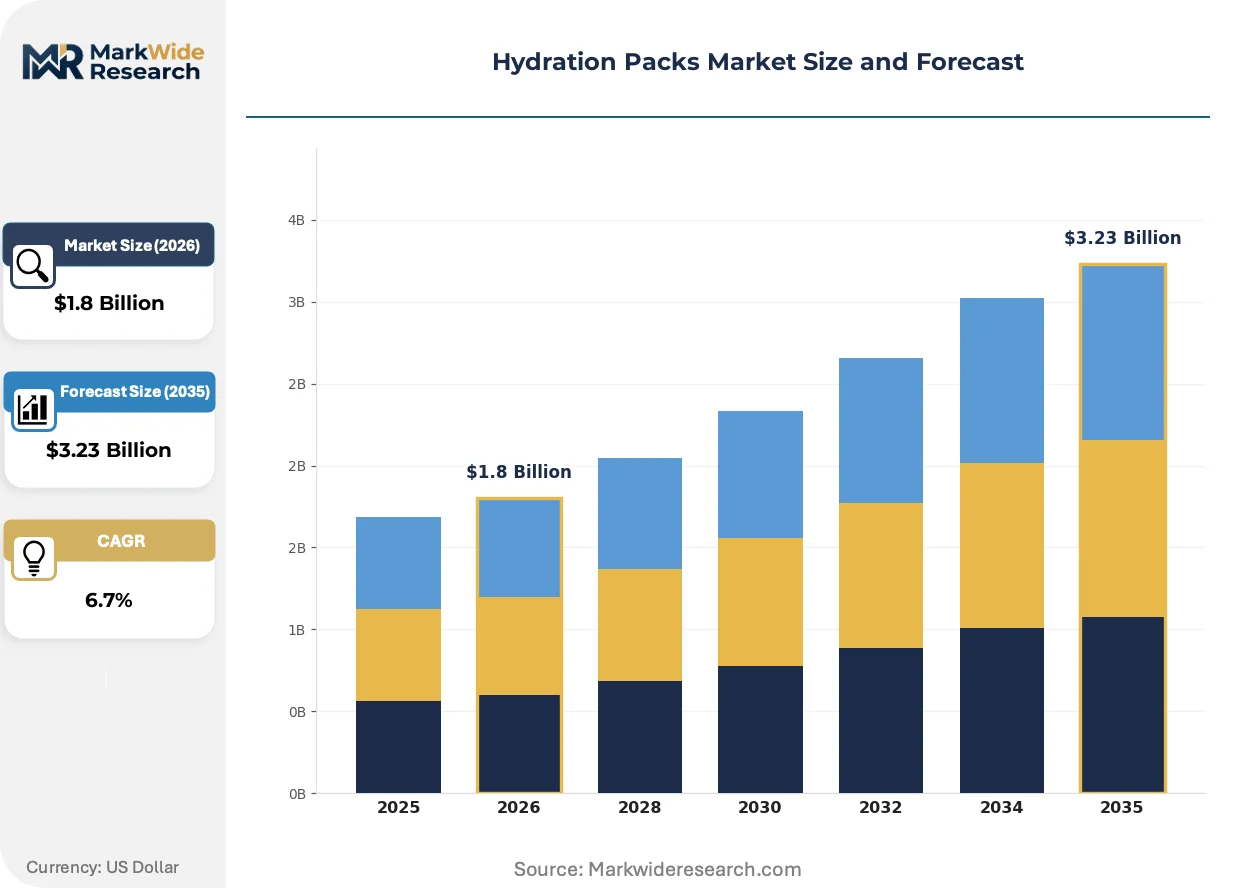
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Waist Packs, Hydration Vests, Bottle Packs Material: Polyester, Nylon, TPU, Vinyl End User: Outdoor Enthusiasts, Athletes, Casual Users, Tourists Capacity: 1L, 2L, 3L, 4L |
| Companies Covered | Hydrapak, Salomon, CamelBak, Ultimate Direction, Nathan, Osprey, Platypus, Source Tactical Gear, Gregory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Packs Market Shifts & Advancements
Reservoir engineering is pivoting toward modularity and sensor integration as endurance sports fragment into specialized disciplines with divergent gear requirements.
Quick-disconnect hose systems with magnetic retention mechanisms are expanding into ultrarunning and fastpacking segments where mid-race reservoir swaps determine competitive outcomes. Elite athletes in Utah's Wasatch Range and France's UTMB circuit are adopting these systems at accelerating rates. This expansion is compressing the addressable market for fixed-reservoir backpack designs while elevating R&D investment in magnetic coupling durability.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of TPU bladder compounds across EU-serving production lines. Manufacturers are migrating toward bio-based polyether formulations that maintain flexibility at sub-zero temperatures. Alpine expedition suppliers targeting Norway's Jotunheimen and Austria's Ötztal regions are absorbing elevated testing costs to secure ECHA-compliant material certifications ahead of competitors.
Direct-to-consumer configuration tools are displacing traditional retail assortment models among digitally native endurance brands. Custom vest-fit algorithms using torso measurement databases are replacing in-store fitting sessions for trail runners in Colorado's Front Range and California's Sierra Nevada foothills. This channel rotation is most visible among subscription-based outdoor gear platforms that bundle seasonal reservoir replacements with membership tiers.
Hydration Packs Market Segmentation
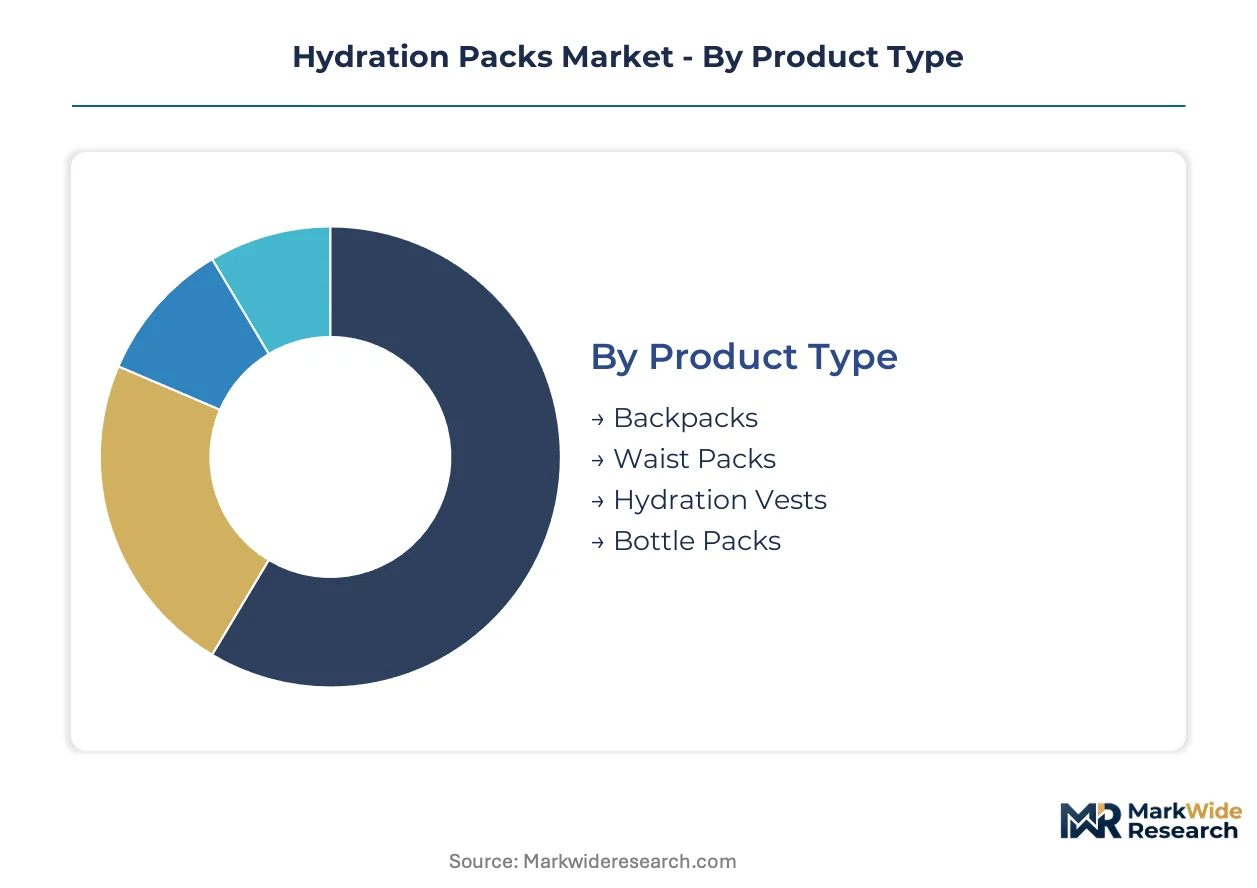
Hydration pack manufacturers configure product architectures around four intersecting dimensions. Each segmentation axis reveals distinct margin profiles, certification burdens, and channel access requirements that determine competitive viability.
Product Type:
Standardized backpack platforms dominate mass retail, while vest-style systems command customization premiums for race-day optimization.
- Backpacks:Traditional dual-strap configurations with integrated reservoirs target day-hikers and casual outdoor users. Volume concentrates in Germany's Alpine manufacturing corridor where technical shell production clusters reduce component lead times.
- Hydration Vests:Anatomically contoured vest systems with front-mounted soft flasks minimize bounce during high-output efforts. Demand is climbing fastest among Colorado trail runners and Chamonix skyracing participants who prioritize mid-race nutrition access.
- Waist Packs:Lumbar-mounted alternatives for cyclists and Nordic skiers seeking lower center-of-gravity fluid carriage. Popular in Scandinavian cross-country skiing circuits.
- Bottle Packs:Minimalist hip-belt systems holding rigid bottles for short-duration training runs. Entry-level positioning in Southeast Asian outdoor retail.
Most installed capacity flows through Backpacks. Expansion is steepest in Hydration Vests.
Material:
Cost tiers stratify sharply between commodity synthetics and expedition-grade compounds requiring dual-certification testing.
- Polyester:Cost-efficient 600D-900D weaves with PU coatings dominate volume production for casual hiking segments. Abrasion resistance satisfies day-trip durability expectations without premium positioning.
- TPU:Thermoplastic polyurethane bladders with antimicrobial linings constitute the technical core of reservoir systems. REACH Annex XVII phthalate restrictions are accelerating bio-based polyether formulation adoption among EU-serving manufacturers.
- Nylon:High-tenacity ripstop weaves with silicone-PU hybrid coatings command alpine and expedition-grade price tiers. Preferred by Norwegian Jotunheimen operators for sub-zero flexibility retention.
- Vinyl:Food-grade PVC alternatives in budget reservoir construction face declining share amid regulatory pressure from ECHA substance restrictions.
Polyester carries the largest production footprint. Nylon is gaining share fastest in premium channels.
End User:
Application intensity determines replacement frequency and attachment system complexity across user cohorts.
- Outdoor Enthusiasts:Multi-day backpackers and technical climbers requiring expedition-grade durability with modular component replacement. Concentrated in Himalayan trekking corridors of Uttarakhand and Himachal Pradesh.
- Athletes:Trail runners, ultramarathoners, and skyracers prioritizing minimal weight and bounce suppression. This cohort drives sensor-integrated smart hydration adoption.
- Casual Users:Weekend hikers and fitness walkers with lower technical demands and price sensitivity. Dominates big-box retail velocity.
- Tourists:Disposable or rental-oriented systems for guided day-trip markets. Emerging demand in India's expanding outdoor tourism infrastructure.
Athletes generate the highest revenue per unit. Outdoor Enthusiasts show the steepest expansion trajectory in underpenetrated Asian markets.
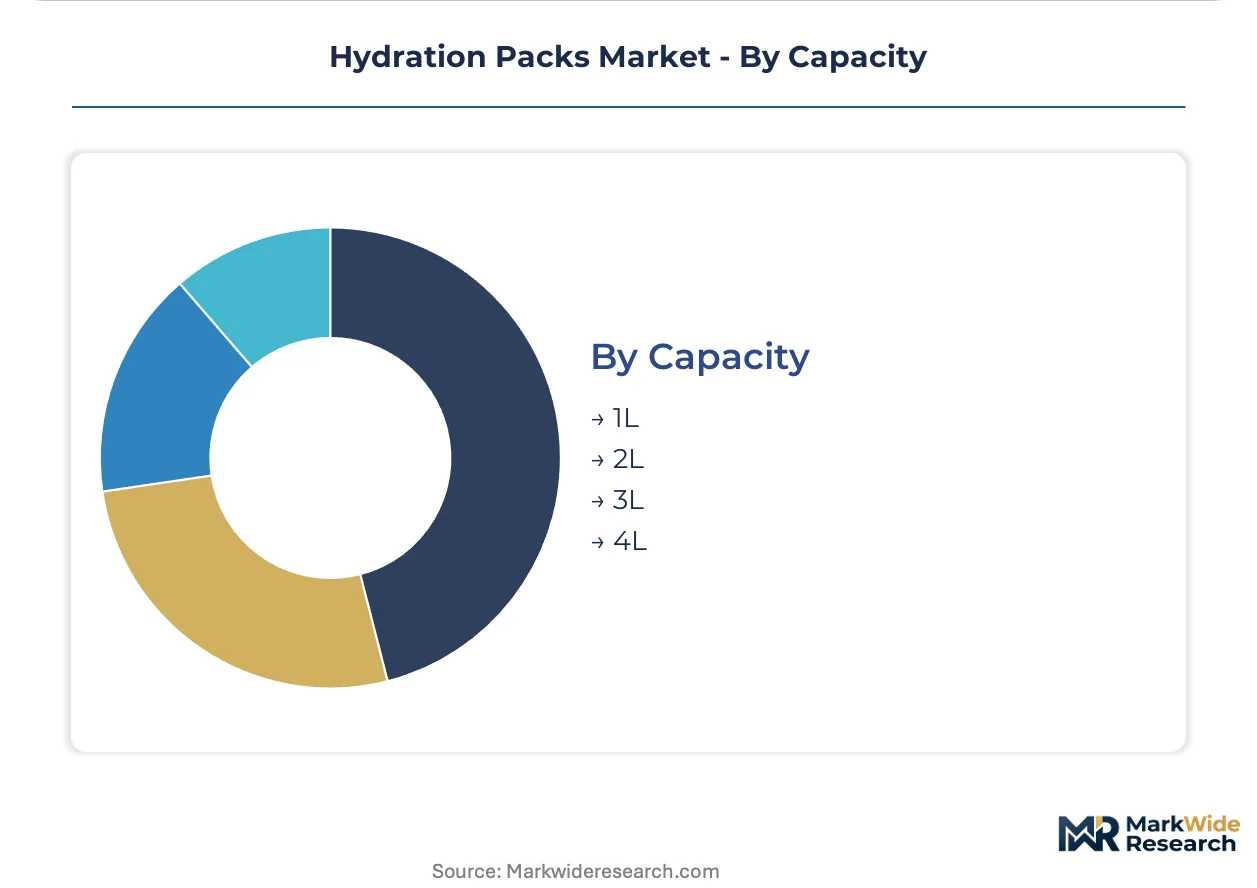
Capacity:
Volume selection correlates directly with event duration and refill point spacing in target use cases.
- 1L:Minimalist race-legal configurations for sub-four-hour efforts where aid station density permits frequent refills. Standard in UTMB qualifying events.
- 2L:Versatile mid-range capacity balancing weight and autonomy for half-day trail outings. Dominates European retail assortment.
- 3L:Full-day expedition standard with sufficient buffer for remote terrain without water sources. Preferred by Wasatch Range fastpackers.
- 4L:Extended autonomy for desert ultras and unsupported multi-day pushes. Niche positioning with highest per-liter manufacturing cost.
2L systems anchor production planning. 3L configurations are climbing fastest in alpine expedition channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydration pack manufacturing traces its commercial roots to military and cycling applications developed in the United States during the late twentieth century. Technical outdoor gear production subsequently migrated toward European alpine corridors and Asian manufacturing hubs. Distribution networks now span specialized retail channels across North America, Europe, and Asia-Pacific.
United States
Trail running participation in Colorado's Front Range and Utah's Wasatch Range drives vest-style system adoption among ultramarathon athletes. FDA food-contact material standards govern reservoir and tube compositions, creating certification requirements for domestic distribution. Manufacturing concentrates in Pacific Northwest outdoor gear clusters where technical shell production supports modular hydration architectures.
Germany
Alpine trekking and skyrunning events in Bavaria and Baden-Württemberg sustain demand for expedition-grade reservoir systems. ECHA REACH Annex XVII restrictions on phthalate plasticizers in TPU bladder production elevate compliance costs for EU-serving manufacturers. The Alpine manufacturing corridor around Munich hosts technical outdoor gear production clusters that reduce lead times for specialized reservoir components.
France
UTMB circuit events in Chamonix and the broader Auvergne-Rhône-Alpes region attract international trail runners toward premium vest configurations. EU Green Deal sustainability frameworks pressure manufacturers toward bio-based polyurethane alternatives in reservoir construction. Manufacturing activity clusters in the Grenoble-Annecy corridor where alpine equipment specialists maintain close supplier relationships.
China
Precision-molded bite valve production concentrates in southern Chinese manufacturing zones, supplying global brands with critical reservoir components. GB standards for food-contact materials provide domestic regulatory baselines alongside export-oriented FDA and REACH compliance. Industrial capacity in Guangdong and Zhejiang provinces supports both component fabrication and finished goods assembly for international distribution.
India
Himalayan trekking operators in Uttarakhand and Himachal Pradesh represent expanding demand for expedition-grade reservoir systems among domestic and international tourists. BIS certification requirements for imported outdoor equipment create entry barriers for foreign brands without local testing partnerships. Manufacturing presence remains limited, with distribution running through outdoor retail networks in Delhi-NCR and Bangalore.
Hydration Packs Market Competitive Landscape
The competitive structure tilts toward heritage reservoir engineering specialists with crossover military-civilian expertise. Market concentration remains moderate, with established outdoor gear conglomerates competing against focused hydration technology firms. Two strategic archetypes dominate: integrated outdoor equipment manufacturers leveraging distribution scale, and specialized reservoir engineering houses competing on technical performance. Capacity expansion and portfolio diversification toward smart sensor integration represent the dominant competitive moves.
Within the heritage engineering tier, CamelBak occupies a position exemplifying military-to-civilian technology transfer, while Osprey anchors the integrated outdoor equipment archetype through anatomically framed load distribution systems. Source Tactical Gear represents the battlefield-durability specialization vector, extending appeal into law enforcement and emergency response channels. These three companies illustrate how technical differentiation in reservoir construction and vest architecture shapes competitive positioning across endurance sports and professional use cases.
| Leading Market Players |
|---|
| Hydrapak |
| Salomon |
| CamelBak |
| Ultimate Direction |
| Nathan |
| Osprey |
| Platypus |
| Source Tactical Gear |
| Gregory |
| Others |
Supply & Pricing Matrix
TPU resin feedstock costs transmit directly from petrochemical benchmarks through bladder manufacturing to final vest and backpack price points, with REACH-compliant bio-based polyether formulations commanding material premiums that stratify finished goods across premium alpine, standard trail, and economy day-hike tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates expedition-grade nylon-TPU systems with dual FDA-REACH certification from mass-market polyester configurations. Price differentiation hinges on antimicrobial lining complexity and geographic delivery cost from Germany's Alpine manufacturing corridor. Cost compression in economy tiers is intensifying because vinyl alternatives face ECHA substance restrictions. Casual users in Southeast Asian retail channels exhibit highest price sensitivity; ultramarathon athletes in Colorado and Chamonix show lowest.
Supply Chain Analysis
Bladder refurbishment and end-of-life collection programs remain nascent, though California's SB 54 packaging mandates are forcing pilot reverse-logistics trials among brands with closed-loop ambitions. Precision-molded bite valve production concentrates in southern China, while TPU compounding clusters in Germany and shell fabrication localizes in Vietnam and Bangladesh. Supply chains draw from petrochemical feedstocks, antimicrobial additive suppliers, and magnetic quick-disconnect component specialists. Single-source geographic concentration in Guangdong bite valve manufacturing exposes brands to port congestion risk. Distribution runs through specialty outdoor retail, direct-to-consumer configuration platforms, and big-box sporting goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe run substantially higher than FDA-only certification burdens in the United States, creating margin expansion opportunities for brands with transatlantic regulatory efficiency.
For Market Incumbents: Anticipate bio-based TPU formulation mandates spreading beyond EU borders by securing ECHA-compliant material certifications ahead of regulatory harmonization. Defend margin position through backward integration into antimicrobial lining production rather than relying on aging European polymer chemist networks. Channel control via direct-to-consumer vest-fit algorithms displaces traditional retail assortment models fastest in Colorado's Front Range and California's Sierra Nevada foothills. For New Entrants and Emerging Players: Subscription-based outdoor gear platforms represent the most penetrable channel partner type for digital-native brands lacking heritage retail relationships. White-space targets include Himalayan trekking operators in Uttarakhand and Himachal Pradesh where expedition-grade reservoir demand outpaces established brand presence, plus smart hydration sensor integration for data-driven endurance athletes. A direct-to-consumer configuration tool with torso measurement databases bypasses capital-intensive retail footprint requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized reservoir engineering houses with military-civilian crossover expertise because technical differentiation in bladder construction creates durable moats against commodity competitors. Long-term viability over the five-to-ten year window favors targets with dual FDA-REACH certification capabilities and established supplier relationships in Germany's Alpine manufacturing corridor. Monitor ECHA substance restriction expansion timelines as the critical inflection indicator for bio-based polyurethane adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based TPU Formulation Investment | REACH Annex XVII phthalate restrictions in Europe are forcing material transitions ahead of regulatory enforcement deadlines. |
| Smart Hydration Sensor Integration | Flow-rate sensors with mobile fitness app connectivity open premium pricing tiers among data-driven ultramarathon athletes. |
| Direct-to-Consumer Configuration Platform | Custom vest-fit algorithms using torso measurement databases displace traditional retail fitting sessions in trail running segments. |
| Closed-Loop Bladder Recycling Program | California SB 54 packaging mandates create first-mover advantage for brands with established end-of-life collection infrastructure. |
| Alpine Manufacturing Corridor Expansion | Supplier density around Munich reduces lead times for specialized reservoir components serving EU distribution channels. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with reservoir product managers, outdoor retail category buyers, polymer formulation specialists, and regulatory compliance officers at brands serving dual FDA-REACH markets. Secondary validation drew from ECHA substance restriction databases, FDA food-contact material guidance, customs trade records for TPU resin flows, and SEC filings of publicly traded outdoor equipment conglomerates. Bottom-up demand modeling across trail running participation rates and top-down market sizing through manufacturer production capacity triangulated volume estimates.
Granularity-level framing applied separate modeling tracks for vest-style versus backpack architectures, antimicrobial versus standard TPU linings, and EU-certified versus non-certified production lines. CAGRs were derived from segment-level growth rate reconciliation across product type, material, end user, and capacity dimensions. Forecast inputs incorporated REACH regulatory timeline assumptions, petrochemical price volatility scenarios, and sensor integration adoption curves among endurance athletes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction expansion, bio-based polyurethane scale-up economics, and smart hydration technology convergence rates. Practitioners should monitor UTMB circuit athlete gear selection patterns and California extended producer responsibility rulemaking for early signals of channel and material shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Global Personal Watercraft Market