
 Global Climbing Holds Market | 2026-2036
Global Climbing Holds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Climbing Holds Market Analysis
Market Context
European polyurethane suppliers is recalibrating output schedules to match the cadence of climbing gym construction across Germany and France. Metolius Climbing leverages its long-standing domestic manufacturing base to sustain rapid fulfillment for North American gym operators. So iLL anchors its position through distinctive aesthetic design that commands premium placement in boutique fitness concepts. Atomik Climbing Holds competes on volume scale, operating one of the largest resin-pour facilities serving the commercial gym segment.
Technical Definition and Segments
Climbing holds are three-dimensional grip fixtures manufactured from polyurethane resin, fiberglass-reinforced polyester, or laminated hardwood, shaped to simulate natural rock features and rated by load-bearing capacity measured in kilonewtons for safe attachment to artificial climbing structures. Their primary commercial purpose is to create standardized, repeatable movement sequences for training, recreation, and sanctioned competition across controlled indoor environments. Plastic and resin types dominate volume shipments due to lower unit cost and color consistency demanded by route-setting teams, while wood variants command niche margin pools among high-end training facilities prioritizing skin-friendly texture. Jug and sloper forms lead in absolute unit sales because they suit beginner-friendly terrain, though crimp and pinch geometries represent the fastest-growing form category as advanced bouldering and competition formats proliferate.
Regulatory Framework
REACH in Europe and OSHA workplace safety guidelines in the United States govern chemical composition and installation protocols for climbing holds used in commercial settings, with ECHA periodically reviewing phthalate content in flexible polyurethane formulations. The EU AI Act and broader product safety directives are beginning to influence smart-wall integrations where sensor-equipped holds track climber performance data. Stakeholders must monitor how emerging fire-retardancy standards for indoor recreation equipment in jurisdictions like California and Bavaria reshape material specifications and testing certification timelines.
Market Dynamics
Climbing gym operators are compressing hold replacement cycles from 36 months to 18-24 months as route-setting teams refresh walls to sustain member engagement, creating a structural pull on polyurethane resin supply chains calibrated for longer industrial refresh periods.
Growth Catalysts
- REACH phthalate reviews:ECHA's tightening scrutiny on flexible polyurethane additives is accelerating reformulation R&D, opening premium positioning for compliant European suppliers.
- Competition formats:IFSC-sanctioned bouldering and speed climbing disciplines are mandating standardized hold geometries, driving volume procurement from certified manufacturers.
- German gym density:Purpose-built bouldering halls in Berlin, Munich, and Hamburg are expanding wall capacity faster than any other national cluster, concentrating equipment demand.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate feedstock costs swing with crude oil indices, squeezing margin predictability for resin-pour facilities.
- Asia-Pacific supply concentration:Mold-making and fiberglass-reinforced polyester substrate production clusters in Zhejiang province create single-source vulnerability for European hold brands.
- Fire-retardancy retrofit costs:California and Bavaria indoor recreation standards are forcing material reformulation and retesting, extending certification timelines.
Strategic Opportunities
- Sensor-integrated smart walls:EU AI Act compliance frameworks for performance-tracking holds create first-mover advantage for polyurethane suppliers with embedded electronics partnerships.
- France construction wave:Paris-region climbing gym permits issued since 2023 exceed prior decade totals, opening underpenetrated distribution channels.
- Direct-to-gym digital platforms:Route-setting teams are bypassing traditional distributors via manufacturer portals, compressing channel margin capture.
Industry Challenges
- Route-setter certification bottlenecks:IFSC and national federation credentialing programs cannot train setters fast enough to match gym construction velocity.
- Legacy wall retrofit compatibility:New hold attachment standards for competition-grade load ratings require drilling patterns incompatible with 2015-era wall structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Climbing Holds Market |
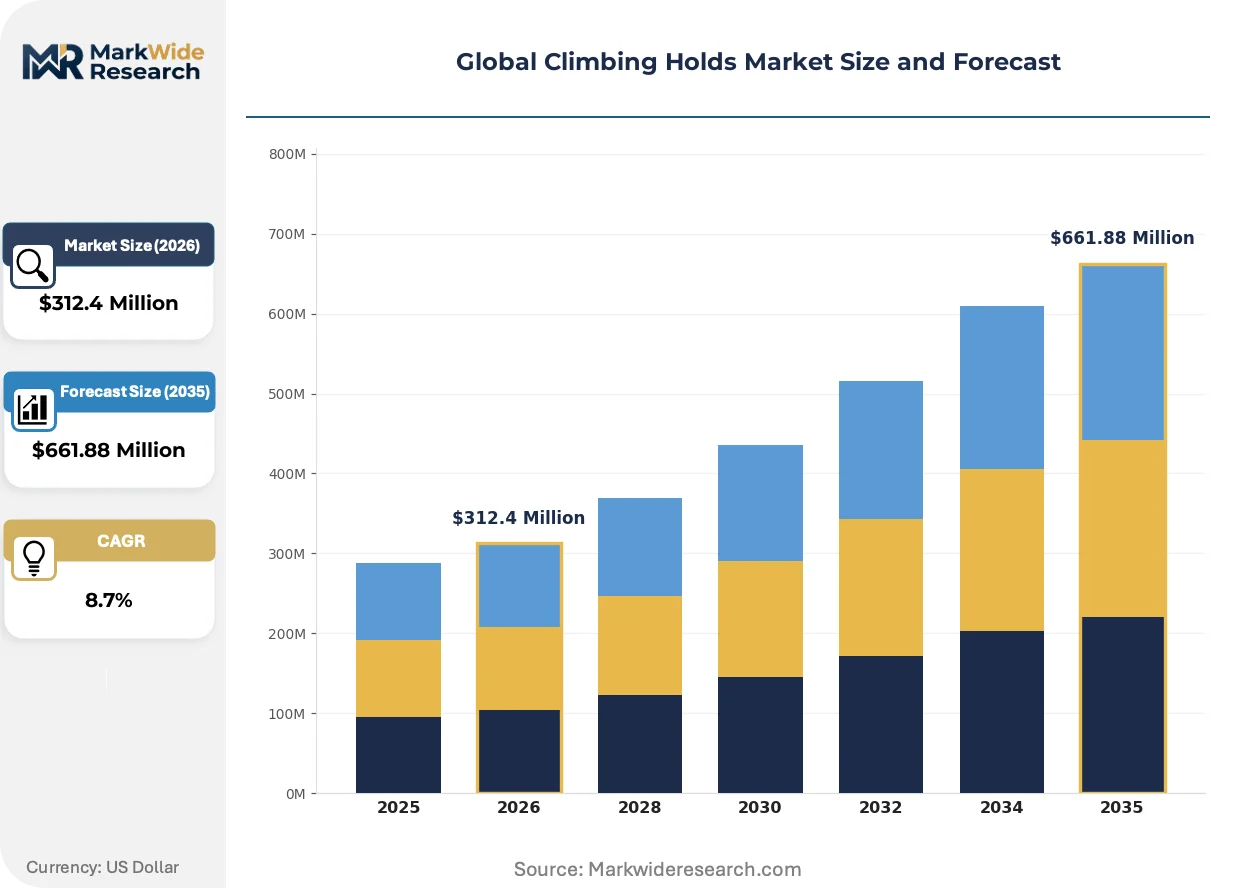
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Plastic, Resin, Wood Form: Jug, Crimp, Sloper, Pinch Usage: Indoor Climbing, Outdoor Climbing, Bouldering, Competition Customer Type: Climbing Gyms, Schools, Fitness Centers, Individuals |
| Companies Covered | So iLL, Rock Candy Holds, Metolius Climbing, Rockcity Climbing Holds, Three Ball Climbing, Atomik Climbing Holds, Nicros, Greenholds, Escape Climbing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Climbing Holds Market Emerging Trajectories
Digital fabrication and material science are converging to compress design-to-wall timelines while regulatory pressure on chemical composition is forcing supplier specialization.
3D-printed hold prototypes are unifying design iteration speed with final polyurethane casting fidelity, allowing route-setting teams to test geometries before resin-pour production. Boutique fitness concepts in London and Los Angeles are piloting these rapid-turnaround workflows. The technology is unifying aesthetic customization with volume manufacturing economics previously reserved for mass-market holds.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing European polyurethane formulators to validate alternative flame-retardant chemistries. Hold manufacturers serving commercial gyms must resubmit technical files to notified bodies. German and French suppliers with in-house polymer labs are responding fastest, capturing specification authority from commodity resin blenders.
Route-setting teams are consolidating procurement through cooperative buying groups rather than individual gym purchasing. Independent climbing facilities in the Netherlands and Belgium are pooling volume to negotiate direct manufacturer relationships. This channel disintermediation is most visible in the Benelux corridor, where distributor margins are compressing 8-12 percentage points.
Global Climbing Holds Market Segmentation
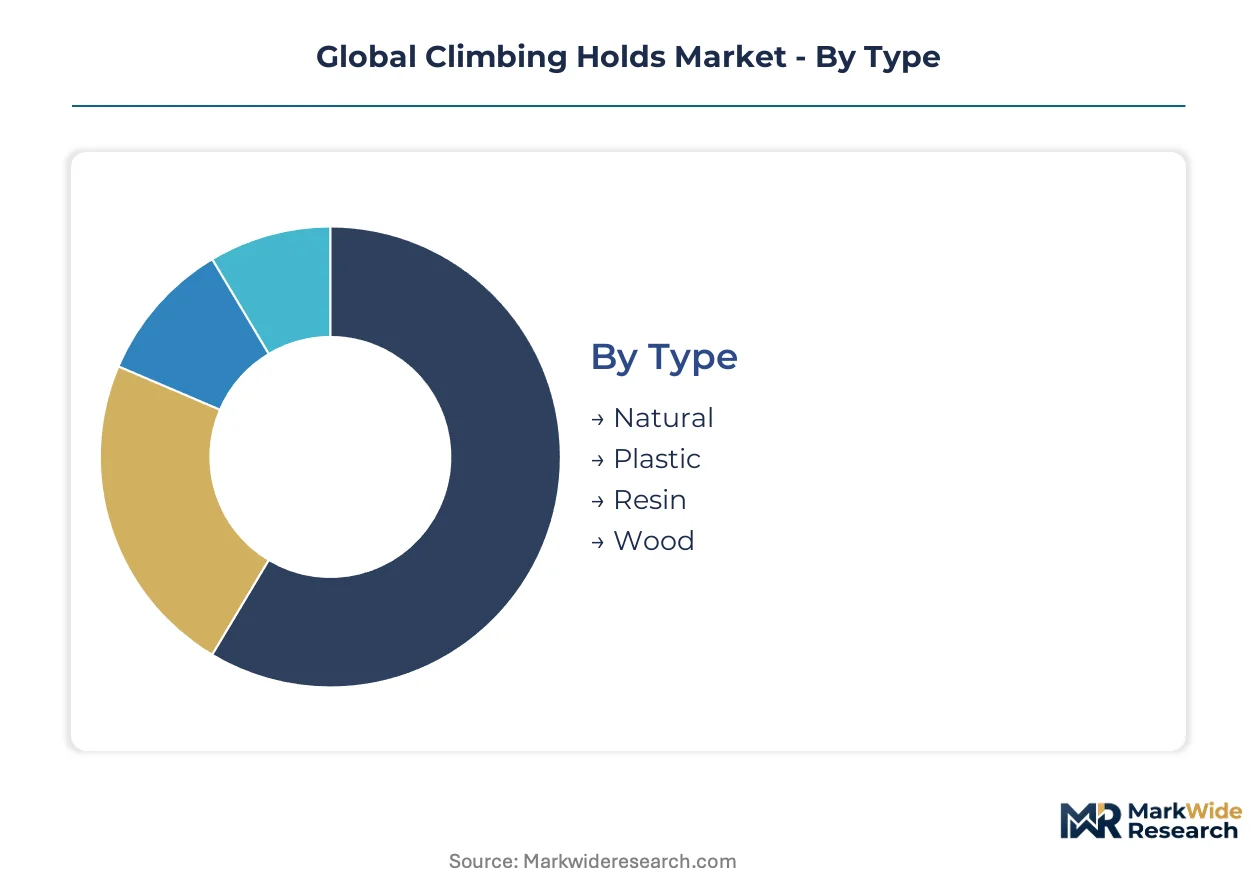
Climbing holds serve distinct functional and aesthetic requirements across training, recreation, and competition contexts. Material composition, grip geometry, and end-use environment each create separate procurement workflows and margin structures for manufacturers.
Type:
Volume shipments concentrate in synthetic formulations, while premium positioning clusters in specialized natural materials.
- Plastic:Polyurethane resin dominates unit economics through color consistency and mold reproducibility. German bouldering halls in Berlin and Munich specify plastic holds for high-traffic circuits where replacement frequency exceeds 18-month cycles.
- Resin:Fiberglass-reinforced polyester achieves superior load-bearing ratings for competition-grade installations. French gym operators in the Paris region prioritize resin formulations meeting REACH Annex XVII flame-retardancy standards.
- Natural:Laminated hardwood and stone variants serve boutique training facilities prioritizing skin-friendly texture.
- Wood:CNC-carved wooden holds command niche margins among high-end home wall builders in California and Bavaria.
Mature deployment sits with Plastic. Newer deployment is concentrated in Wood.
Form:
Grip geometry determines movement difficulty and user progression pathways across facility types.
- Jug:Deep, incut profiles enable beginner-friendly vertical terrain. Schools and recreational fitness centers in the United States specify jug-dominant route packages for introductory programming.
- Sloper:Smooth, rounded surfaces demand open-hand strength and technique. Advanced bouldering halls in Hamburg and London deploy slopers for overhanging circuits targeting experienced members.
- Crimp:Small edge profiles stress finger tendon conditioning. Competition setters at IFSC-sanctioned events mandate standardized crimp geometries for consistent athlete evaluation.
- Pinch:Dual-sided compression grips represent the steepest expansion trajectory as pinch-dominant problems proliferate in World Cup bouldering formats.
Established route libraries favor Jug. Technical innovation is accelerating in Pinch.
Usage:
Environmental exposure and performance tracking requirements split procurement specifications.
- Indoor Climbing:Climate-controlled walls drive color-coded route setting and rapid rotation schedules. Commercial gyms in France and Germany compress hold replacement to 18-month cycles.
- Bouldering:Low-height, mat-protected formats prioritize dense hold placement and frequent reset demands. Purpose-built bouldering halls concentrate equipment procurement volume.
- Competition:Standardized geometries and sensor-integrated smart walls require certified load ratings and EU AI Act compliance for performance data capture.
- Outdoor Climbing:UV-stabilized formulations resist weathering on fixed artificial structures.
Volume concentration aligns with Indoor Climbing. Format evolution is fastest in Competition.
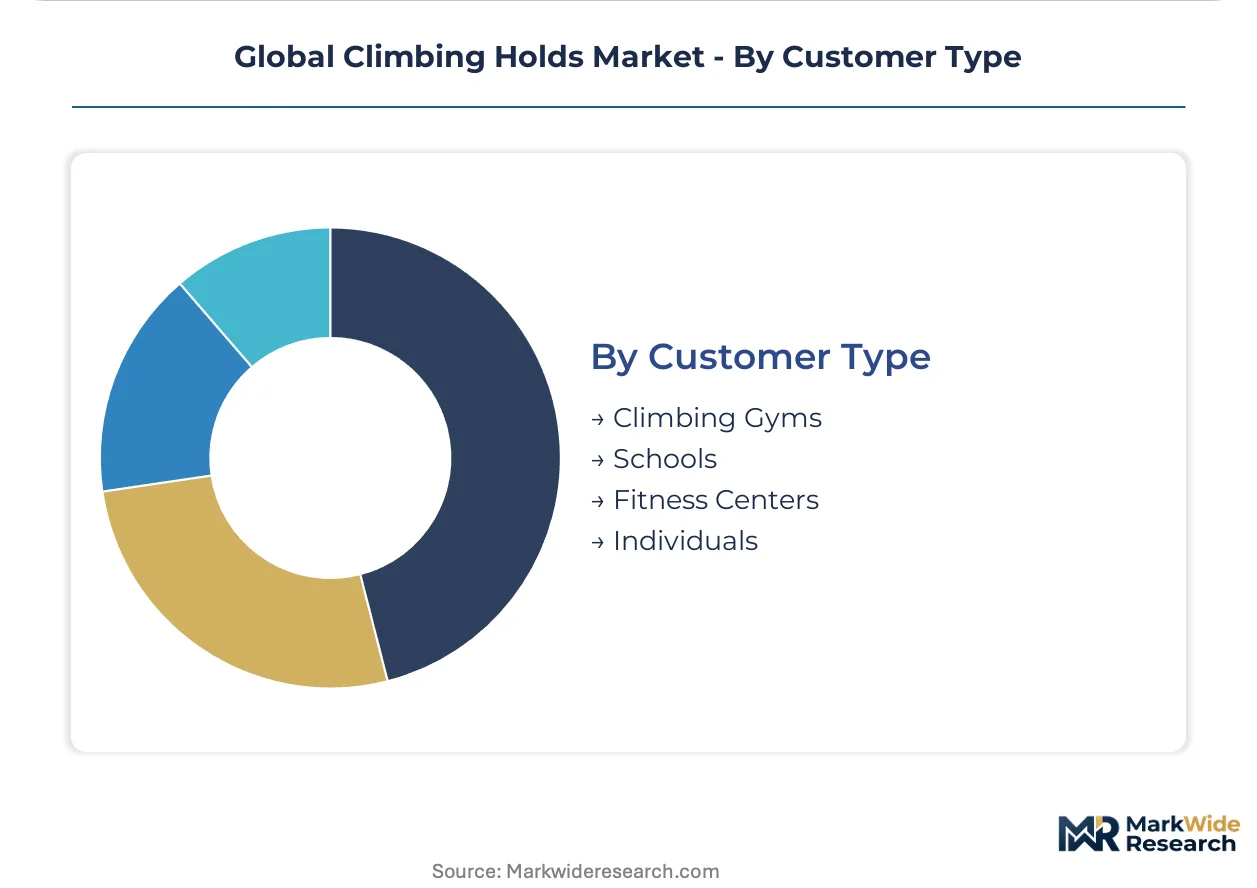
Customer Type:
Procurement scale and technical sophistication vary sharply across buyer categories.
- Climbing Gyms:Commercial operators purchase through cooperative buying groups or direct manufacturer portals. Benelux independent facilities pool volume to bypass traditional distributors.
- Fitness Centers:Multi-purpose recreation chains integrate climbing walls as amenity differentiators with lower route-setting frequency.
- Schools:Institutional buyers prioritize liability-compliant installation and beginner-accessible hold selections.
- Individuals:Home wall builders source through specialty retailers with emphasis on aesthetic customization.
Contract consolidation is most advanced among Climbing Gyms. Fragmented purchasing persists with Individuals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyol and isocyanate feedstock availability near the US Gulf Coast anchors North American polyurethane resin production for climbing hold manufacturing. European formulators concentrate around the Rhine-Ruhr chemical corridor, while Asian mold-making clusters serve as critical supply nodes for fiberglass-reinforced substrates.
United States
Commercial climbing gym construction in Austin, Denver, and Portland drives polyurethane hold procurement at compressed replacement cycles. OSHA workplace safety guidelines govern installation protocols and chemical exposure limits for gym employees. California fire-retardancy standards for indoor recreation equipment are forcing material reformulation among West Coast suppliers.
Germany
Berlin, Munich, and Hamburg host the densest concentration of purpose-built bouldering halls globally, creating sustained equipment demand. REACH Annex XVII restrictions on short-chain chlorinated paraffins mandate alternative flame-retardant chemistries for polyurethane formulations. The Rhine-Ruhr chemical corridor houses specialized resin blenders with in-house polymer laboratories responding fastest to regulatory shifts.
France
Paris-region climbing gym permits issued since 2023 exceed prior decade totals, opening underpenetrated distribution channels for hold manufacturers. ECHA phthalate reviews under REACH accelerate reformulation R&D for flexible polyurethane additives. Lyon and Grenoble climbing clusters prioritize resin formulations meeting competition-grade load ratings for IFSC-sanctioned events.
United Kingdom
London boutique fitness concepts pilot 3D-printed hold prototypes unifying design iteration with final casting fidelity. The UK's product safety regulations align with EU REACH standards post-Brexit, maintaining chemical compliance requirements for imported holds. Birmingham and Manchester gym operators consolidate procurement through cooperative buying groups bypassing traditional distributors.
China
Zhejiang province mold-making and fiberglass-reinforced polyester substrate production clusters create single-source vulnerability for European hold brands. GB standards govern product safety for domestically consumed climbing equipment, though export-oriented manufacturers prioritize REACH and OSHA compliance. Shenzhen and Guangzhou logistics hubs facilitate resin component shipment to Southeast Asian gym construction projects.
Global Climbing Holds Market Vendor Landscape
Global majors compete with regional champions across material formulation expertise and route-setting relationships. The vendor base organizes around three tiers: domestic manufacturers with rapid fulfillment capabilities, European specialists with in-house polymer laboratories, and scale-driven resin-pour facilities serving volume procurement. Strategic moves concentrate on geographic expansion through distributor partnerships and backward integration into captive polyurethane blending capacity.
Among North American fabricators, Metolius Climbing and So iLL occupy distinct positioning archetypes. Metolius Climbing exemplifies the domestic manufacturing anchor with rapid fulfillment infrastructure for commercial gym operators. So iLL represents the design-premium vector where distinctive aesthetic positioning commands placement in boutique fitness concepts. Atomik Climbing Holds sits within the scale-driven tier, operating resin-pour capacity serving high-volume commercial gym segments.
| Leading Market Players |
|---|
| So iLL |
| Rock Candy Holds |
| Metolius Climbing |
| Rockcity Climbing Holds |
| Three Ball Climbing |
| Atomik Climbing Holds |
| Nicros |
| Greenholds |
| Escape Climbing |
| Others |
Supply Flow & Price Mechanics
3D-printed prototyping workflows are compressing design-to-production timelines while simultaneously fragmenting procurement power across cooperative buying groups in the Netherlands and Belgium. This dual shift rewards agile formulators with in-house polymer labs while squeezing margin capture for distributors caught between bulk-purchasing gyms and resin-pour facilities.
Pricing Analysis
Warranty and route-setting consultation bundling separates premium European suppliers from unbundled commodity resin blenders serving high-volume gym chains. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and REACH Annex XVII compliance status, with German bouldering halls absorbing premium tiers for rapid replacement cycles. Cost compression in standard-tier holds is intensifying because petrochemical feedstock volatility transmits directly to polyurethane resin costs. Schools and institutional buyers exhibit highest price sensitivity, while competition-grade gym operators prioritize load-rating certification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang province mold-making clusters that anchor fiberglass-reinforced polyester substrate production for European hold brands. Polyol and isocyanate feedstocks draw from US Gulf Coast and Rhine-Ruhr chemical corridor concentrations, creating dual-hemisphere dependency for polyurethane resin formulators. Regulatory restriction risk concentrates in REACH phthalate reviews and California fire-retardancy retrofit mandates, which extend certification timelines. Distribution runs through direct-to-gym digital portals and cooperative buying groups that bypass traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII compliance costs and petrochemical input volatility are forcing consolidation among commodity resin blenders without in-house polymer laboratories. Surviving players will capture specification authority from distressed competitors.
For Market Incumbents: Lock in route-setting team relationships through embedded design consultation and rapid-turnaround prototyping capabilities. Backward integration into captive polyurethane blending capacity secures margin control against feedstock volatility. Prioritize ECHA pre-registration for alternative flame-retardant chemistries ahead of short-chain chlorinated paraffin restrictions. For New Entrants and Emerging Players: Launch via direct-to-gym digital platforms targeting independent climbing facilities in the Paris region, where permit issuance since 2023 has outpaced distribution infrastructure. White-space sits with sensor-integrated smart wall partnerships requiring EU AI Act compliance expertise. Avoid competing on jug and sloper volume; instead, specialize in pinch geometries for World Cup bouldering formats. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by fitness equipment conglomerates seeking climbing vertical integration. Long-term viability favors formulators with REACH-certified resin portfolios and embedded electronics partnerships for performance-tracking holds. Watch ECHA phthalate review timelines as inflection indicator for premium supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Blending | Captive resin production insulates margin from polyol and isocyanate price swings. |
| EU AI Act Compliance Partnership | Sensor-integrated hold certification opens first-mover positioning for smart wall deployments. |
| Direct-to-Gym Digital Platform Launch | Route-setting team portals compress distributor margin capture in Benelux and UK markets. |
| REACH Annex XVII Reformulation Investment | Alternative flame-retardant validation secures specification authority for German gym operators. |
| Cooperative Buying Group Engagement | Pooled procurement volume from Dutch and Belgian independents offsets channel disintermediation pressure. |
Methodological Framework
Multi-period observation of gym construction permits, hold replacement cycle compression, and REACH regulatory filing volumes anchored the trend analysis, supplemented by interviews with climbing gym operators, route-setting team leads, polyurethane formulators, and distributor channel managers. Secondary validation drew from customs trade data for resin component shipments, ECHA substance restriction notifications, and municipal planning records for bouldering hall permits. Bottom-up facility count modeling and top-down chemical consumption estimates were triangulated against manufacturer production disclosures.
Segment-weighting across material type, grip geometry, end-use environment, and customer procurement scale structured the analytical framework. CAGRs were derived from facility expansion trajectories and per-wall hold density assumptions, cross-referenced against polyol consumption patterns reported by Rhine-Ruhr chemical producers. Competition format standardization by IFSC and sensor-integration adoption curves for smart walls informed scenario-based projections across the analysis window.
Petrochemical price volatility, ECHA regulatory timeline delays, and route-setter certification bottlenecks are the dominant revision risks that could compress or extend projected replacement cycle velocities. Forecasts reflect documented assumptions about gym construction cadence and material compliance trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Leisure Centers Market