
 United States and Europe Horse Racing Market | 2026-2036
United States and Europe Horse Racing Market Size, Share, and Industry Trends Forecast 2026-2036
United States and Europe Horse Racing Market Analytics
Digital streaming integration is narrowing the gap between live track attendance and remote wagering participation across the United States and Europe. Churchill Downs Incorporated leverages its proprietary streaming infrastructure to sustain year-round engagement beyond the Kentucky Derby. The Stronach Group anchors West Coast racing operations through controlled real estate and broadcast assets. Arena Racing Company dominates British and Irish racecourse management, operating forty percent of UK fixtures.
United States and Europe horse racing comprises organized competitive equine events where thoroughbreds, standardbreds, or jumpers compete on dirt, turf, or synthetic surfaces at distances from five furlongs to four miles, with pari-mutuel or fixed-odds wagering constituting the primary revenue mechanism. Flat racing commands the largest wagering pool across both geographies, though jump racing sustains premium margins in the United Kingdom and Ireland through heritage events like the Grand National. Exchange betting represents the fastest-growing betting type as peer-to-peer platforms displace traditional bookmaker margins, while tote systems retain structural importance in France and parts of the United States through statutory monopoly frameworks.
The Federal Trade Commission and state racing commissions in the United States enforce wagering integrity and anti-money-laundering protocols, while the United Kingdom Gambling Commission and France's national gaming authority impose affordability checks and advertising restrictions that reshape operator business models. The European Union's Digital Services Act and country-level GDPR enforcement add compliance layers for cross-border betting platforms. Stakeholders must monitor regulatory divergence between American state-by-state frameworks and European harmonization pressures when allocating platform development resources.
Market Dynamics
The convergence of mobile wagering platforms and real-time streaming infrastructure is compressing the traditional racing calendar into year-round engagement cycles, forcing operators to rebuild asset-light digital distribution models alongside fixed track real estate.
Growth Catalysts
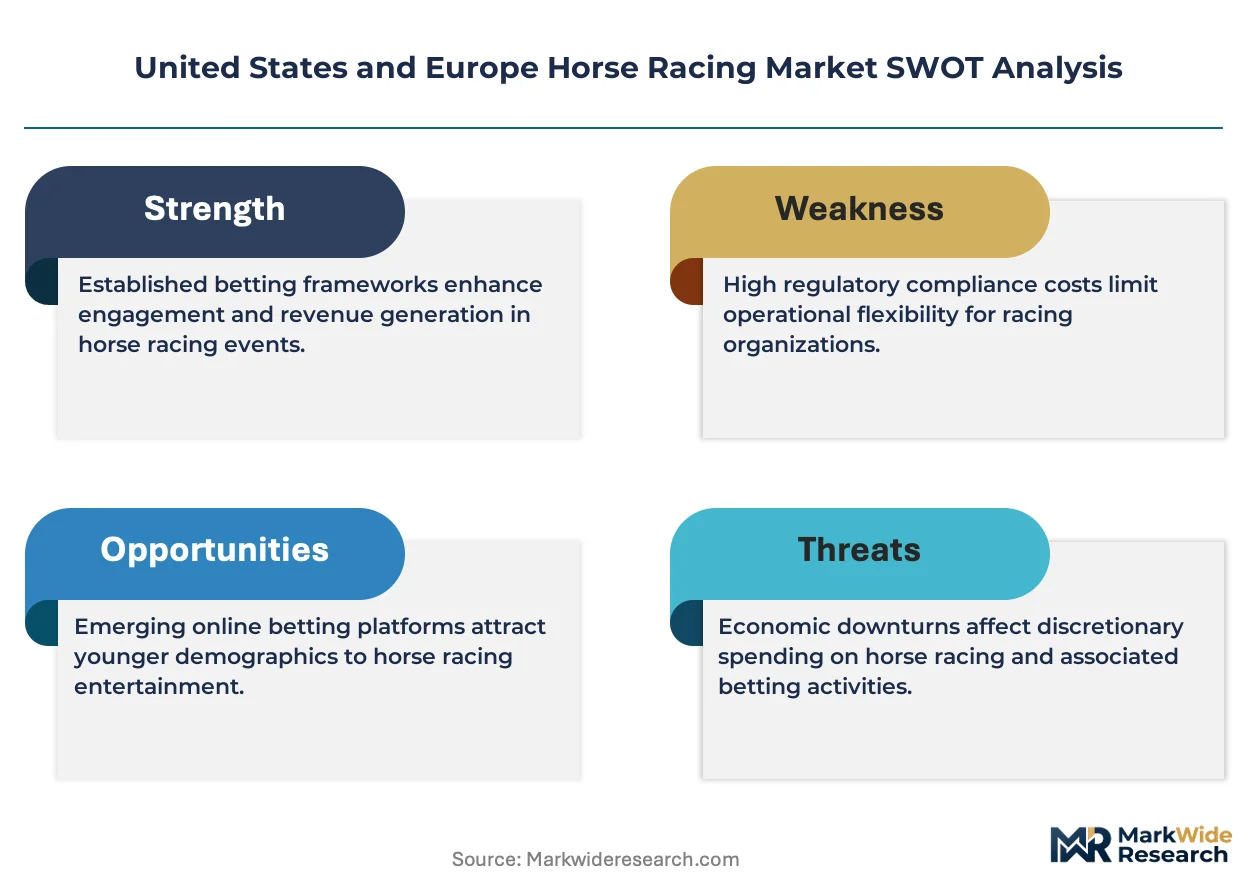
- GDPR-compliant data frameworks:The European Union's data protection regime enables cross-border platform expansion by standardizing consumer consent protocols across member states.
- Exchange betting algorithms:Peer-to-peer matching engines reduce bookmaker takeout rates and attract price-sensitive bettors from conventional fixed-odds channels.
- Kentucky Derby wagering pools:Concentrated heritage events in the United States generate liquidity spikes that subsidize operational costs across regional circuits.
Market Restraints
- Thoroughbred supply concentration:Breeding operations cluster in Kentucky and Ireland, creating bloodstock price volatility when disease outbreaks disrupt foal crops.
- Affordability check mandates:The United Kingdom Gambling Commission's financial vulnerability screening extends onboarding friction and increases customer acquisition costs.
- Fixed-odds substitution:Sports betting platforms capture casual wagering budgets through instant-settlement products that racing cannot replicate.
Strategic Opportunities
- French tote monopoly liberalization:Proposed reforms to the Pari Mutuel Urbain framework would open exchange betting licensing to international operators.
- Synthetic surface conversion:All-weather track installations in the United Kingdom extend racing calendars into winter months previously lost to turf closure.
- Streaming-wagering bundling:Integrated video and betting interfaces reduce customer leakage to third-party broadcasters.
Industry Challenges
- Veterinary talent scarcity:Equine regulatory veterinarians face recruitment gaps as training programs contract across Ireland and the United States.
- Anti-money-laundering integration:Suspicious transaction monitoring systems require costly retrofitting of legacy tote platforms that predate real-time surveillance mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and Europe Horse Racing Market |
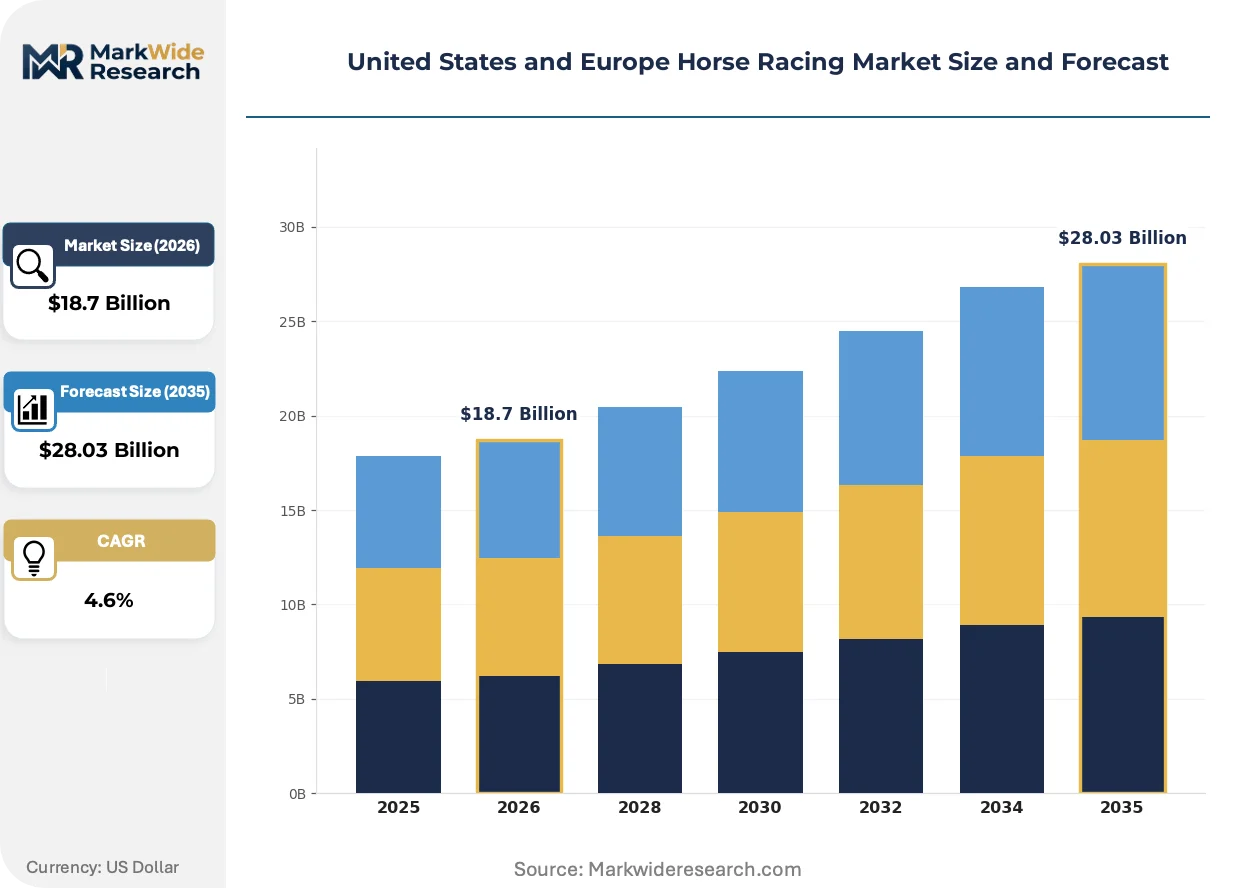
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Betting Type: Fixed Odds, Tote, Exchange, In-Play Race Type: Flat Racing, Jump Racing, Harness Racing, Steeplechase Event Size: Local, Regional, National, International Customer Segment: Casual Betters, Professional Gamblers, Syndicates, Corporate Entities |
| Companies Covered | Churchill Downs Incorporated, The Stronach Group, New York Racing Association, Arena Racing Company, Keeneland Association, William Hill, Bet365, Betfair, Ladbrokes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and Europe Horse Racing Market Evolving Landscape
Digital infrastructure investments are fragmenting the traditional track-operator-bettor relationship into modular service layers where streaming rights, wagering liquidity, and customer data circulate through separate commercial channels.
Blockchain-based provenance tracking is migrating from pedigree documentation into wagering integrity applications. Kentucky breeding farms and Irish sales houses are adopting distributed ledger systems for bloodstock verification. This technology compression is reducing fraud disputes while creating new data monetization streams for auction houses.
The Digital Services Act enforcement timeline is reshaping platform liability frameworks across European Union member states. Intermediary service obligations now require real-time content moderation and algorithmic transparency disclosures. Cross-border operators serving British and Irish bettors must rebuild compliance architectures around Brussels-mandated audit trails.
Younger demographics are abandoning telephone and retail wagering in favor of mobile-native interfaces with social features. In-play betting on overseas fixtures through Singapore and Hong Kong race feeds displaces traditional domestic card loyalty. This channel rotation concentrates liquidity in late-night programming slots that strain United States and European broadcast infrastructure.
United States and Europe Horse Racing Market Segmentation
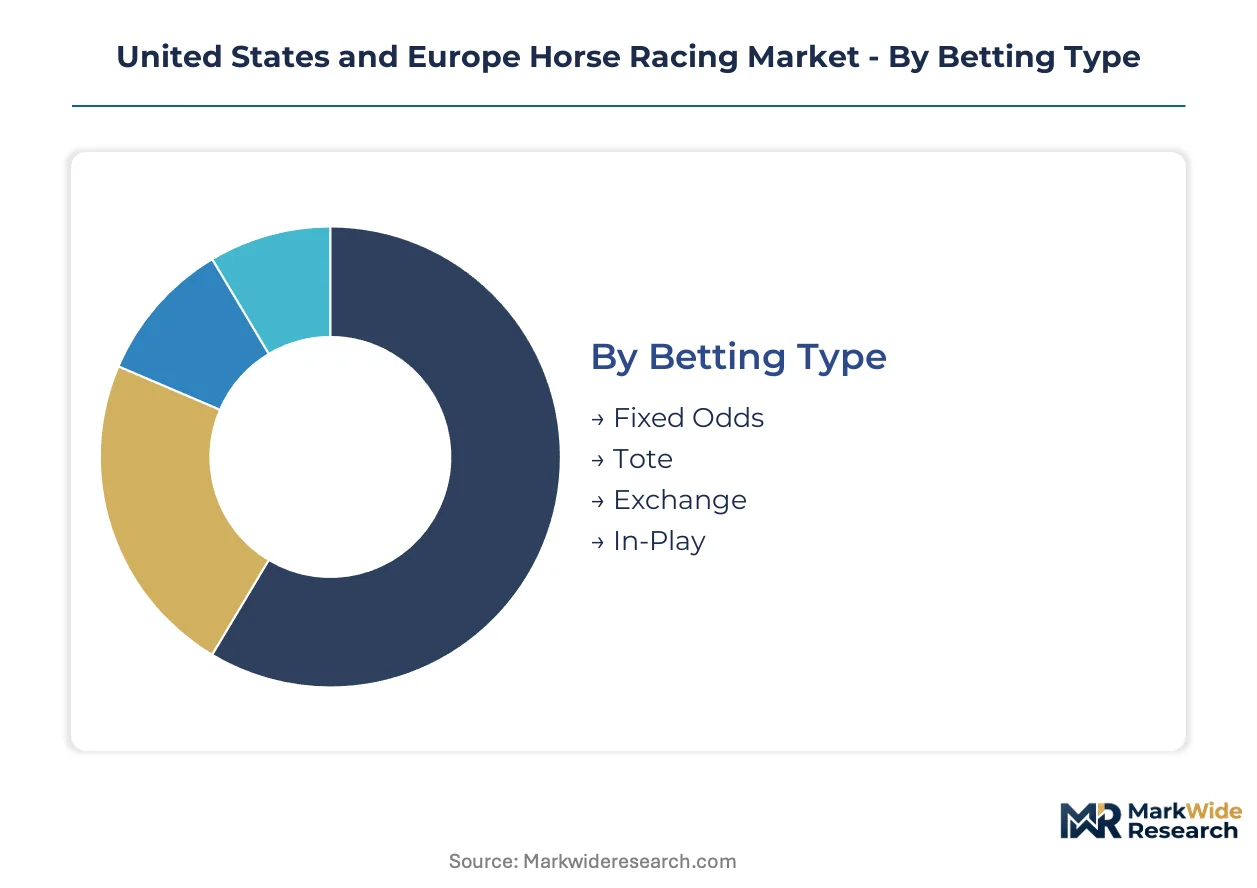
Segmentation in horse racing reveals how wagering behavior, race formats, and customer economics fragment across digital and physical channels. Understanding these divisions exposes where platform investments yield engagement returns versus where legacy infrastructure constrains margin expansion.
Betting Type:
After-sales service intensity varies sharply across betting mechanisms, with exchange platforms demanding continuous algorithmic support while tote systems require regulatory maintenance partnerships.
- Fixed Odds:Traditional bookmaker-set prices dominate retail and early mobile adoption. UK and Irish operators concentrate fixed-odds liquidity around Saturday heritage cards, though margin compression from exchange competition is accelerating price-sensitive customer migration.
- Tote:Pari-mutuel pool betting operates through statutory monopolies in France and select US jurisdictions. The PMU framework in France requires extensive regulatory compliance infrastructure that international operators struggle to replicate without local partnerships.
- Exchange:Peer-to-peer matching platforms like Betfair pioneered this format. Commission-based revenue models attract professional bettors who provide liquidity that sustains tighter spreads than conventional bookmakers can offer.
- In-Play:Real-time wagering during races demands sub-second latency infrastructure. Singapore and Hong Kong race feeds drive US and European in-play volume during overnight programming slots.
By volume, Fixed Odds leads. By growth pace, Exchange is expanding most quickly.
Race Type:
Application context determines infrastructure requirements, with jump racing demanding specialized veterinary and course maintenance protocols that flat racing avoids.
- Flat Racing:Thoroughbred competitions on level surfaces constitute the largest wagering pool across both geographies. Kentucky Derby weekend and Royal Ascot generate liquidity spikes that subsidize year-round operational costs for track operators.
- Jump Racing:Hurdle and steeplechase events command premium margins in the UK and Ireland through heritage fixtures like the Grand National. Seasonal turf closures limit calendar expansion without synthetic surface conversion investments.
- Harness Racing:Standardbred pacing and trotting competitions sustain dedicated regional circuits in the United States, particularly in New York and Pennsylvania markets where state racing commissions maintain statutory support.
- Steeplechase:The most technically demanding jump format requires specialized course architecture. Irish and English fixtures like the Cheltenham Gold Cup attract international ownership investment that elevates bloodstock prices.
Flat Racing captures the majority of wagering volume. Jump Racing delivers the highest margin per race due to heritage event pricing power.
Event Size:
Customer acquisition economics stratify sharply by event tier, with international fixtures justifying platform marketing spend that local cards cannot support.
- Local:County-level fixtures at minor UK and Irish tracks or US fair circuit meetings. These events rely on on-track attendance and retail wagering with minimal digital streaming investment.
- Regional:Multi-track circuits like the Stronach Group's West Coast operations or Arena Racing Company's northern UK cluster. Shared broadcast infrastructure spreads production costs across venue networks.
- National:Championship series and Breeders' Cup qualifiers in the United States, or British Champions Series events. National broadcast partnerships require exclusive content windows that fragment streaming rights.
- International:Breeders' Cup World Championships, Dubai World Cup night, and Royal Ascot's global simulcast reach. These events command the highest wagering liquidity and bloodstock valuation premiums.
National events anchor operator revenue stability. International fixtures are gaining share fastest as simulcast networks expand.
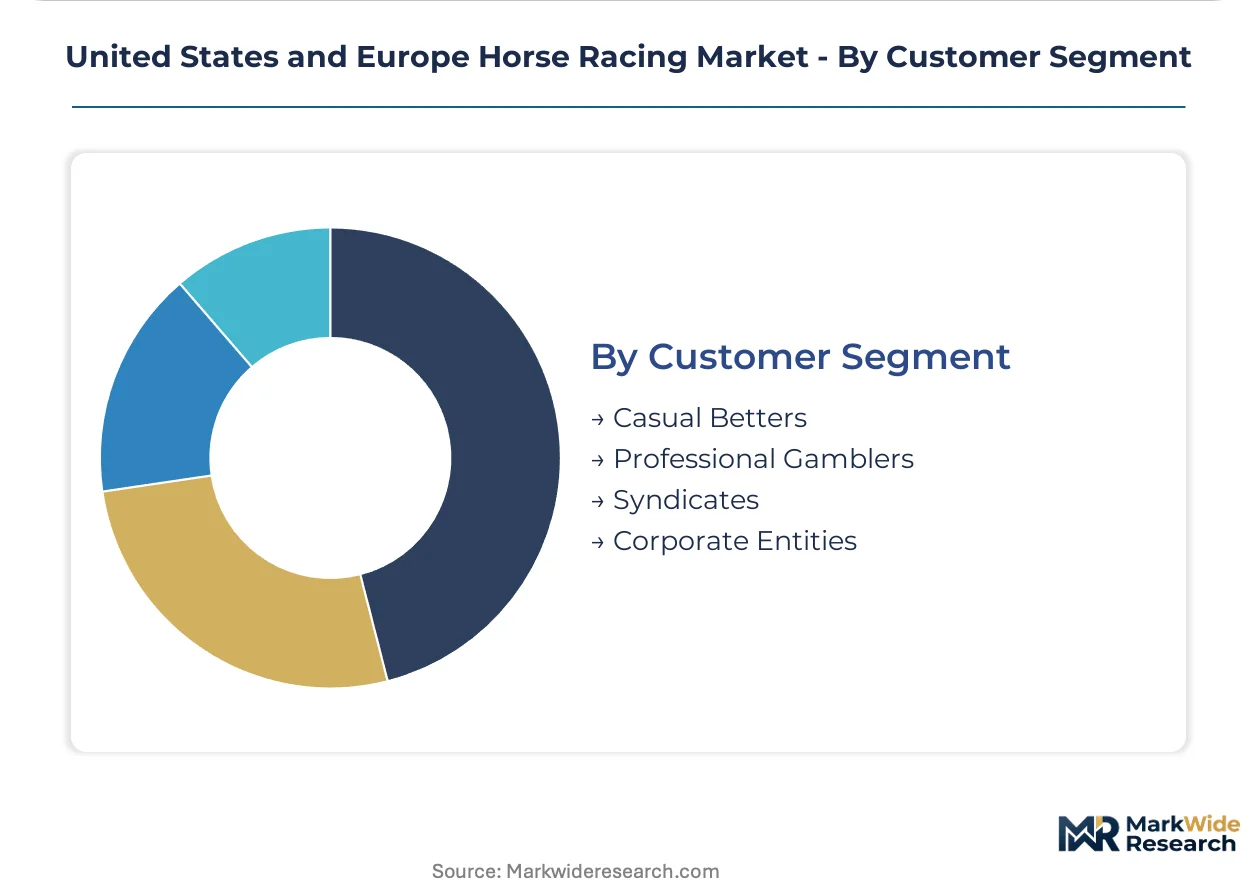
Customer Segment:
Margin structure depends entirely on customer composition, with professional and syndicate accounts demanding price efficiency that casual bettors do not require.
- Casual Betters:Occasional wagering focused on heritage events like the Kentucky Derby or Grand National. Mobile-native interfaces with social features capture this segment from telephone and retail channels.
- Professional Gamblers:Full-time betting operations utilizing exchange platforms and algorithmic price monitoring. This segment concentrates liquidity in specific pools but pressures operator margins through sophisticated arbitrage.
- Syndicates:Pooled investment vehicles for bloodstock ownership and wagering stakes. UK and Irish racing clubs have expanded this format to lower entry barriers for middle-market participants.
- Corporate Entities:Sponsorship-driven hospitality packages and ownership structures. Churchill Downs Incorporated leverages this segment through premium seating and entertainment bundling at flagship venues.
Casual Betters provide the largest customer count base. Professional Gamblers and Syndicates together drive the steepest handle growth as exchange penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Casual bettors cluster around heritage events in Kentucky and the British Isles, while professional syndicates concentrate liquidity in Irish bloodstock auctions and French tote pools. This buyer-archetype split drives divergent infrastructure investments across the United States and Europe.
United States
Kentucky Derby weekend generates liquidity spikes that subsidize year-round regional circuit operations. The Federal Trade Commission enforces wagering integrity protocols alongside state racing commissions. Churchill Downs Incorporated anchors the Kentucky cluster through proprietary streaming infrastructure and controlled real estate assets.
United Kingdom
Heritage jump racing fixtures like the Grand National command premium margins from corporate hospitality and exchange betting liquidity. The UK Gambling Commission imposes affordability checks and advertising restrictions that reshape operator onboarding economics. Arena Racing Company dominates northern and southern racecourse clusters through forty percent fixture control.
Ireland
Steeplechase bloodstock valuations attract international syndicate investment at Dublin and Kildare sales houses. National gaming authority frameworks align with EU Digital Services Act compliance timelines. The Curragh and Leopardstown clusters concentrate veterinary talent and training facilities for jump racing preparation.
France
Pari Mutuel Urbain statutory monopoly sustains pool betting liquidity through exclusive retail and digital channels. Proposed PMU liberalization reforms would open exchange betting licensing to international platform operators. The Chantilly and ParisLongchamp clusters maintain premium flat racing infrastructure for international fixture hosting.
United States and Europe Horse Racing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across track operations, wagering platforms, and streaming distribution. The vendor base stratifies between integrated real estate operators and modular digital service providers. Three archetypes dominate: track-owning incumbents with broadcast assets, exchange-based wagering specialists, and cross-sport betting conglomerates. Competitive moves concentrate on streaming-wagering bundling and synthetic surface calendar extension.
Within the track-owning incumbent tier, Churchill Downs Incorporated and The Stronach Group exemplify real estate-anchored strategies that leverage proprietary infrastructure for year-round engagement. Arena Racing Company occupies a parallel position across British and Irish fixtures. Among wagering specialists, Betfair and Bet365 represent divergent models—peer-to-peer exchange liquidity versus integrated sportsbook cross-selling. William Hill and Ladbrokes sit within the conglomerate tier where horse racing serves as heritage content within broader betting portfolios.
| Leading Market Players |
|---|
| Churchill Downs Incorporated |
| The Stronach Group |
| New York Racing Association |
| Arena Racing Company |
| Keeneland Association |
| William Hill |
| Bet365 |
| Betfair |
| Ladbrokes |
| Others |
Value Network & Pricing Analysis
Atlantic shipping corridors connecting Irish bloodstock auctions to Kentucky breeding farms transmit cost volatility directly into yearling price tiers, with freight rate spikes compressing margins for mid-market buyers while premium syndicates absorb logistics premiums without demand elasticity.
Pricing Analysis
Cost-plus contracts for stallion nominations index to prior-year auction averages, creating automatic pass-through of bloodstock inflation. Three-tier pricing structure across premium, standard, and economy levels segments buyers by syndicate scale and racing ambition. Pricing pressure stems from exchange betting margin compression as peer-to-peer platforms displace traditional bookmaker spreads. Casual bettors exhibit highest price sensitivity, migrating rapidly toward lowest-takeout pools, while corporate hospitality clients show minimal elasticity.
Supply Chain Analysis
Extended payment terms from French PMU tote operators to regional track operators stabilize cash flow across seasonal revenue troughs. Bloodstock supply concentrates in Ireland, Kentucky, and New South Wales, with veterinary pharmaceutical inputs and racing surface materials feeding from specialized German and Dutch manufacturers. Single-source vulnerability in equine semen logistics threatens breeding season scheduling. Distribution runs through auction house networks and direct farm-to-farm private treaty sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile wagering penetration remains below saturation across both geographies, with streaming-wagering bundling representing an early-cycle adoption tailwind that expands addressable digital engagement beyond traditional track attendance.
For Market Incumbents: Build data moats through proprietary streaming infrastructure that locks in year-round engagement beyond heritage events. Churchill Downs Incorporated exemplifies this through controlled real estate and broadcast asset integration. Consolidate regional circuit operations to spread fixed production costs across venue networks. Defend against exchange platform margin erosion by tightening direct-to-consumer app experiences.
For New Entrants and Emerging Players: Pursue synthetic surface conversion partnerships with UK winter tracks seeking calendar extension without turf maintenance costs. Target in-play betting infrastructure gaps during overnight Asian race feeds where latency-sensitive liquidity concentrates. Deploy supply-chain finance facilities to bloodstock auction houses as entry wedge into ownership syndicate formation.
For Investors and Strategic Acquirers: Exchange-technology specialists with regulatory licensing in multiple EU jurisdictions present asymmetric upside exposure to PMU liberalization reforms. Long-term viability hinges on platform operators capturing professional gambler liquidity without margin destruction. Monitor French parliamentary committee progress on tote monopoly restructuring as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Streaming-Wagering Bundling | Integrated video and betting interfaces reduce customer leakage to third-party broadcasters like ESPN and Sky Sports Racing. |
| Synthetic Surface Conversion | All-weather track installations at UK venues extend racing calendars into winter months previously lost to turf closure. |
| Exchange Betting Licensing | PMU framework liberalization would open French pools to international peer-to-peer platform operators. |
| Bloodstock Provenance Tracking | Blockchain verification systems at Irish sales houses reduce fraud disputes and create data monetization streams. |
| Affordability Check Automation | UK Gambling Commission compliance tooling lowers customer acquisition friction while maintaining regulatory coverage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of state racing commission wagering reports, bloodstock auction transaction databases, and EU regulatory filing repositories. Interviews with track operations directors, wagering platform product managers, bloodstock auction house executives, and veterinary pharmaceutical procurement leads inform demand-side validation. Customs records for equine pharmaceutical imports and breeding stock movements provide supply-side triangulation. Bottom-up fixture-level handle estimates and top-down national gambling commission aggregates converge through iterative reconciliation.
Forecast inputs incorporate betting type migration rates, streaming subscription attach rates, and regulatory liberalization probability weighting across the projection horizon. Segmentation dimensions span betting mechanism, race format, event tier, and customer archetype. CAGRs derive from logistic adoption curves fitted to mobile wagering penetration benchmarks. Bloodstock price indices and tote pool liquidity trajectories supply industry-specific forecast anchors.
Sensitivities concentrate around Digital Services Act enforcement intensity and Kentucky foal crop disease outbreaks. Forecasts embed assumptions regarding exchange betting regulatory acceptance and synthetic surface capital deployment timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market