
 Nano RAM Market | 2026-2036
Nano RAM Market Size, Share, and Industry Trends Forecast 2026-2036
Nano RAM Market Foresight
REACH compliance is decoupling European market access from legacy fabrication methods. Samsung Electronics leverages captive wafer capacity to anchor its NRAM roadmap in Hwangju. Nantero specializes in carbon nanotube deposition techniques that differentiate its intellectual property portfolio. SK Hynix competes through stacked memory architectures that extend its DRAM dominance into emerging non-volatile categories.
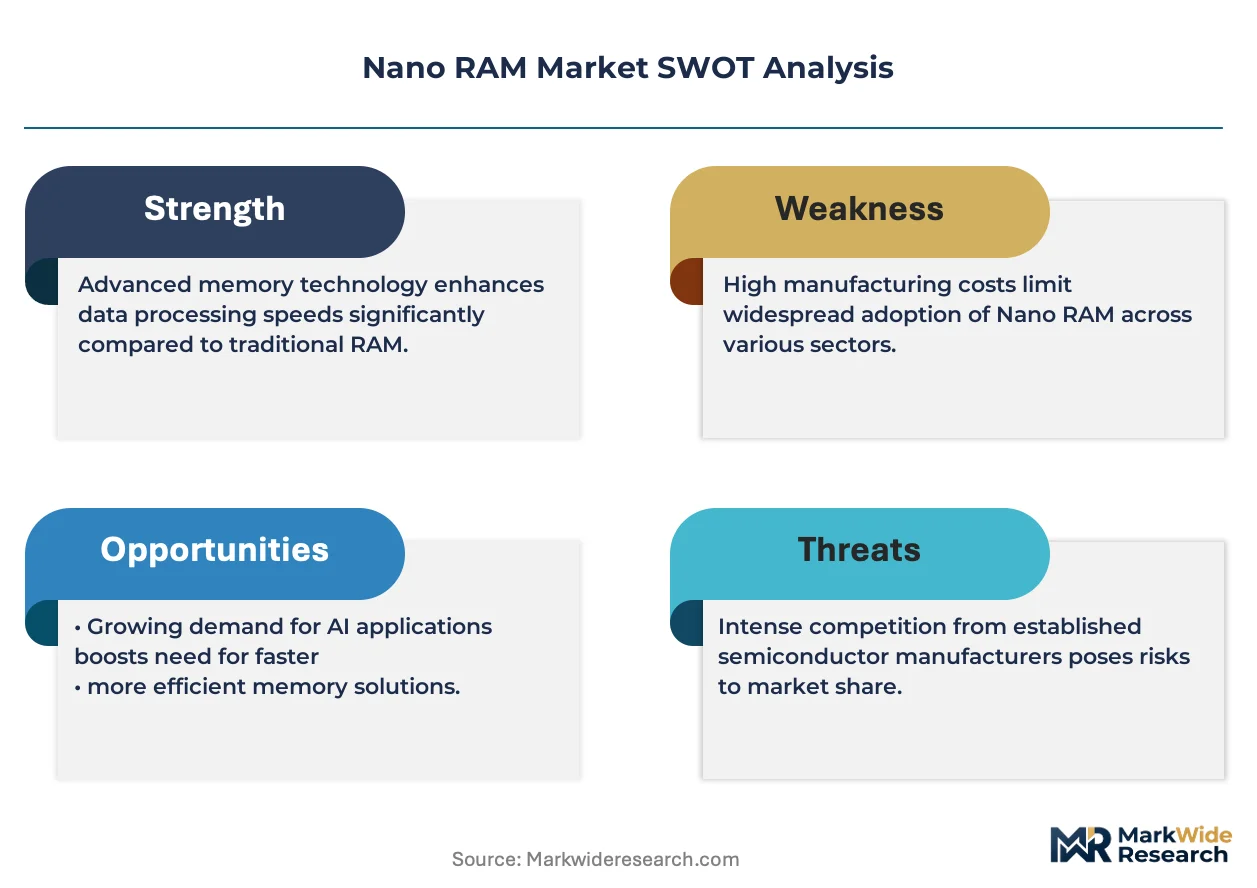
Nano RAM denotes resistive random-access memory cells fabricated at nanometer-scale nodes, typically employing carbon nanotube crossbar arrays or metal-oxide memristive junctions operating below 10nm feature sizes with sub-microsecond switching speeds and retention exceeding ten years. The technology serves applications requiring instant-on computing, persistent cache layers, and radiation-hardened storage for aerospace and automotive systems. Phase Change technology leads in industrial temperature tolerance and endurance cycling, while Magnetoresistive variants occupy premium aerospace and defense slots where radiation immunity commands margin premiums. Flash-derived Nano RAM approaches dominate consumer electronics cost structures, though EEPROM-compatible form factors in SO-DIMM and BGA packages are gaining fastest in automotive telematics modules.
FDA scrutiny of nanomaterial biocompatibility is expanding to cover implantable medical devices employing Nano RAM for persistent patient monitoring data. EPA reporting obligations for carbon nanotube manufacturing are raising baseline compliance costs for US-based fabrication facilities. The EU AI Act's data persistence requirements for audit trails are creating structural demand for non-volatile memory in edge inference hardware. Stakeholders must resolve whether to prioritize backward integration into carbon nanotube synthesis or secure multi-source supply agreements as material constraints tighten.
Market Dynamics
Automotive ECU manufacturers are accelerating their shift from Flash to non-volatile alternatives as autonomous driving systems demand sub-microsecond write endurance at industrial temperatures. This demand pull is restructuring foundry allocation priorities across East Asian semiconductor clusters.
Growth Catalysts
- EU AI Act data persistence mandates:Edge inference hardware deployed in European markets must maintain auditable non-volatile storage for algorithmic decision trails. Nano RAM satisfies this requirement without battery backup systems.
- Carbon nanotube crossbar maturation:Deposition techniques achieving sub-10nm feature sizes now enable ten-year retention at sub-microsecond switching speeds, opening aerospace and satellite applications previously reserved for magnetoresistive technologies.
- REACH compliance decoupling:European material purity standards for nanotechnology fabrication are excluding legacy wet-etch processes, advantaging dry-deposition specialists with pre-qualified supply chains.
Market Restraints
- Carbon nanotube feedstock concentration:High-purity single-walled nanotube supply concentrates among three Asian chemical conglomerates, creating single-source vulnerability for deposition equipment operators.
- EEPROM form factor lock-in:Automotive telematics module sockets remain physically and electrically constrained by legacy Flash pinouts, forcing bridge-controller costs onto Nano RAM adopters.
- Phase Change endurance superiority:Industrial temperature applications above 125°C still favor chalcogenide-based cells, compressing Nano RAM addressable market in factory automation and downhole instrumentation.
Strategic Opportunities
- Implantable medical device data persistence:FDA nanomaterial biocompatibility pathways for carbon-based memory cells remain underdeveloped, creating first-mover advantage for submitters with complete toxicology dossiers.
- South Korea Hwangju cluster proximity:Captive wafer capacity at Samsung and SK Hynix facilities enables co-location of Nano RAM fabrication with DRAM foundry operations, reducing logistics costs for hybrid memory-module assemblers.
- Memristive-carbon convergence:Metal-oxide memristive junctions integrated with nanotube crossbar arrays promise unified memory-logic architectures for neuromorphic computing accelerators.
Industry Challenges
- Carbon nanotube metrology expertise scarcity:Industrial-scale Raman spectroscopy and electron microscopy for batch consistency verification requires specialists trained at fewer than twelve global facilities.
- Radiation-hardening certification timelines:Aerospace-grade qualification under ESA and NASA standards demands 18-24 month test cycles for single-event upset characterization, delaying revenue recognition for defense contractors.
- Legacy automotive ECU software stacks:Tier-1 suppliers maintain proprietary Flash translation layers that resist abstraction without substantial firmware revalidation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano RAM Market |
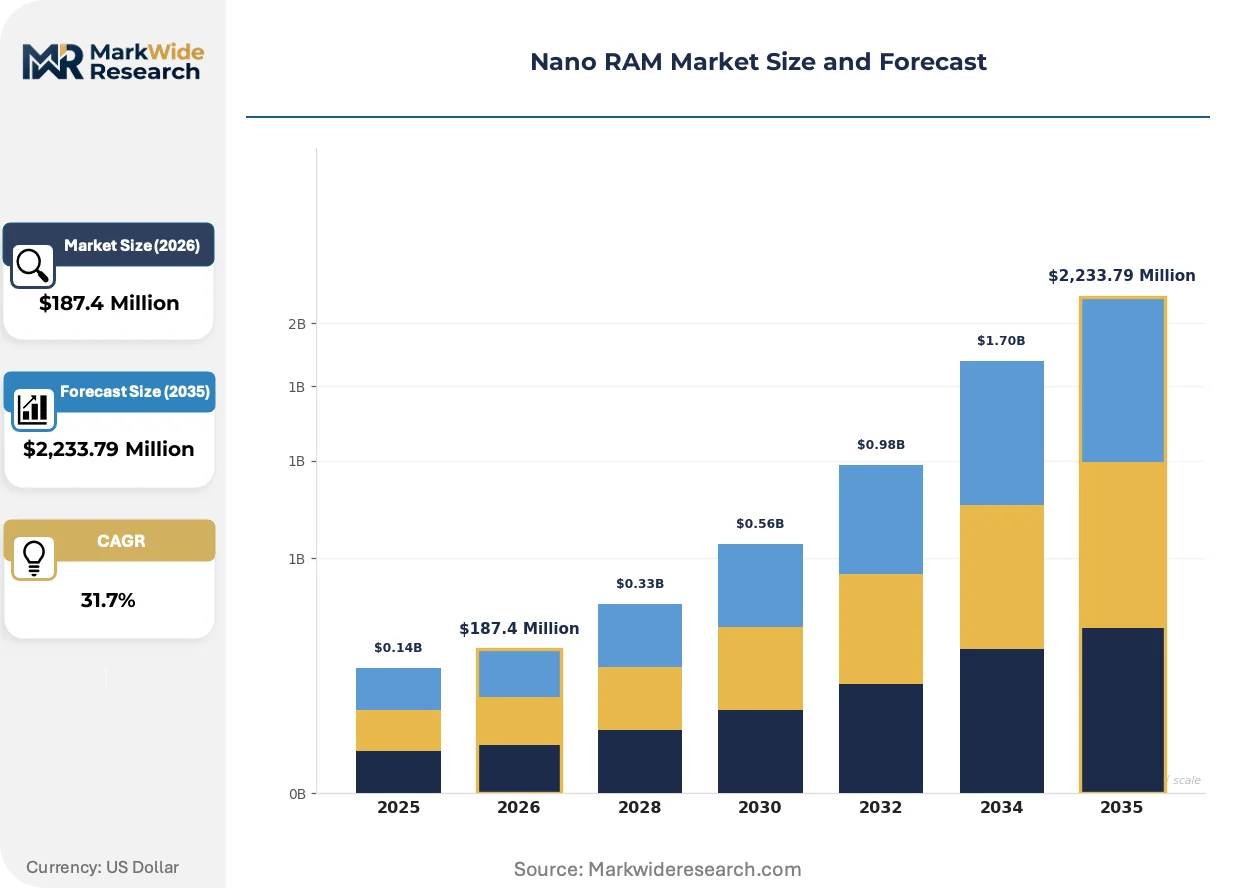
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,233.79 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR, SDRAM, SRAM, DRAM Technology: Flash, EEPROM, Magnetoresistive, Phase Change End User: Consumer Electronics, Automotive, Industrial, Telecommunication Form Factor: DIMM, SO-DIMM, LGA, BGA |
| Companies Covered | TetraMem Inc, Samsung Electronics, Nantero, SK Hynix, Micron Technology, Weebit Nano Ltd, 4DS Memory Limited, TSMC, Crossbar Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano RAM Market Shifts & Advancements
Carbon nanotube deposition equipment is migrating from centralized R&D cleanrooms to production-line integration, compressing development cycles and enabling foundry-specific process optimization. This equipment democratization is reshaping competitive entry barriers.
Carbon nanotube crossbar arrays are decentralizing memory architecture design authority from centralized DRAM foundries toward automotive ECU and aerospace subsystem integrators. Tier-1 suppliers in Germany and Japan now specify cell geometries directly to deposition equipment vendors, bypassing traditional memory semiconductor procurement channels. This shift compresses specification-to-silicon lead times from 24 months to 14 months for qualified integrators.
REACH substance authorization requirements for multi-walled carbon nanotubes are forcing European equipment manufacturers to segregate production lines between legacy and nanomaterial-qualified processes. ECHA's 2024 update to Annex XIV added reporting thresholds that triggered reformulation of conductive adhesives used in BGA packaging. German automotive suppliers now demand pre-certified nanotube grades, transferring compliance verification upstream to Japanese and South Korean material suppliers.
Automotive OEMs are consolidating memory procurement under systems-integration contracts rather than component-level purchasing, unbundling traditional semiconductor distributor relationships. BMW and Volkswagen now specify persistent cache requirements at the autonomous driving platform level, forcing memory suppliers to certify through Tier-1 module assemblers rather than direct sales. This channel compression is most visible in Bavaria and Lower Saxony, where Continental and Bosch have absorbed supplier qualification functions previously performed by independent distributors.
Nano RAM Market Segmentation
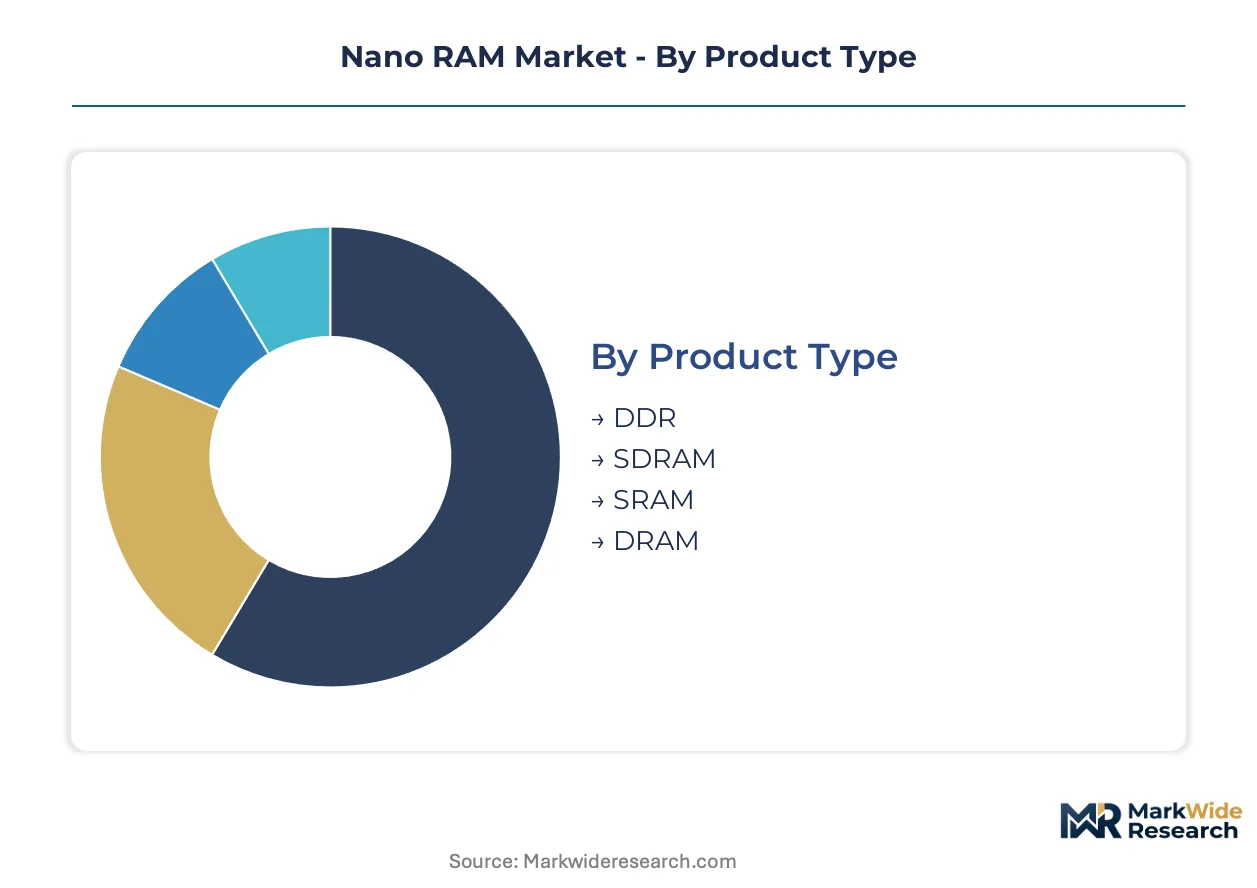
Memory cell architecture and interface specifications determine Nano RAM deployment feasibility across divergent thermal, endurance, and form-factor constraints. Segmentation reveals how carbon nanotube crossbar arrays compete against legacy non-volatile technologies through specification-matched substitution rather than universal displacement.
Product Type:
Interface protocol compatibility governs adoption velocity in socket-constrained automotive and aerospace modules.
- DDR:Double data rate synchronous interfaces support burst-mode transfers for persistent cache layers in autonomous driving compute nodes. Demand concentrates in German Tier-1 ECU programs where sub-microsecond latency requirements override legacy Flash endurance limitations.
- SDRAM:Synchronous dynamic random-access memory protocols enable clock-synchronized operation with existing DRAM controllers, reducing bridge-controller costs for hybrid memory subsystems. South Korean Hwangju cluster assemblers favor this protocol for co-packaged modules combining volatile and non-volatile layers.
- SRAM:Static cell architectures eliminate refresh cycles for radiation-hardened aerospace applications. NASA and ESA qualification programs drive specification rigor for single-event upset immunity in satellite bus controllers.
- DRAM:Dense cell arrays target cost-sensitive consumer electronics where instant-on computing requirements intersect with aggressive bill-of-materials targets. Japanese consumer electronics OEMs specify these variants for gaming console persistent storage.
Mature deployment sits with DRAM-compatible interfaces. Newer deployment is concentrated in DDR-class synchronous protocols for automotive compute.
Technology:
Physical switching mechanisms differentiate endurance, retention, and temperature tolerance for mission-specific selection.
- Flash:Floating-gate charge storage dominates consumer electronics cost structures through mature foundry processes. South Korean and Taiwanese fabrication facilities supply the majority of consumer-grade Nano RAM employing Flash-derived cell architectures.
- EEPROM:Electrically erasable programmable read-only memory cells support byte-addressable writes for automotive telematics firmware updates. REACH-compliant dry-deposition processes from German equipment vendors are displacing legacy wet-etch methods in European supply chains.
- Magnetoresistive:Magnetic tunnel junctions deliver radiation immunity for aerospace and defense applications commanding margin premiums. ESA and NASA certification timelines extend 18-24 months, concentrating demand among defense contractors with pre-qualified supplier relationships.
- Phase Change:Chalcogenide material phase transitions achieve industrial temperature tolerance above 125°C for factory automation and downhole instrumentation. SK Hynix stacked memory architectures extend DRAM dominance into this endurance-superior category.
Mature deployment sits with Phase Change cells for industrial temperature extremes. Newer deployment is concentrated in Magnetoresistive variants for radiation-hardened satellite systems.
End User:
Application-specific endurance and environmental requirements drive technology-protocol matching.
- Consumer Electronics:Gaming consoles and wearable devices specify instant-on persistent storage with ten-year retention. Japanese and South Korean OEMs dominate procurement volume for Flash-derived form factors.
- Automotive:Autonomous driving ECUs demand sub-microsecond write endurance at industrial temperatures without battery backup. BMW and Volkswagen platform-level specifications now bypass traditional semiconductor distributors.
- Industrial:Factory automation and downhole instrumentation favor Phase Change endurance above 125°C. German automotive suppliers demand pre-certified nanotube grades transferring compliance upstream.
- Telecommunication:Edge inference hardware requires EU AI Act-compliant data persistence for algorithmic audit trails. Nano RAM satisfies this without battery backup systems in European deployments.
Mature deployment sits with Industrial process control systems. Newer deployment is concentrated in Automotive autonomous driving platforms.
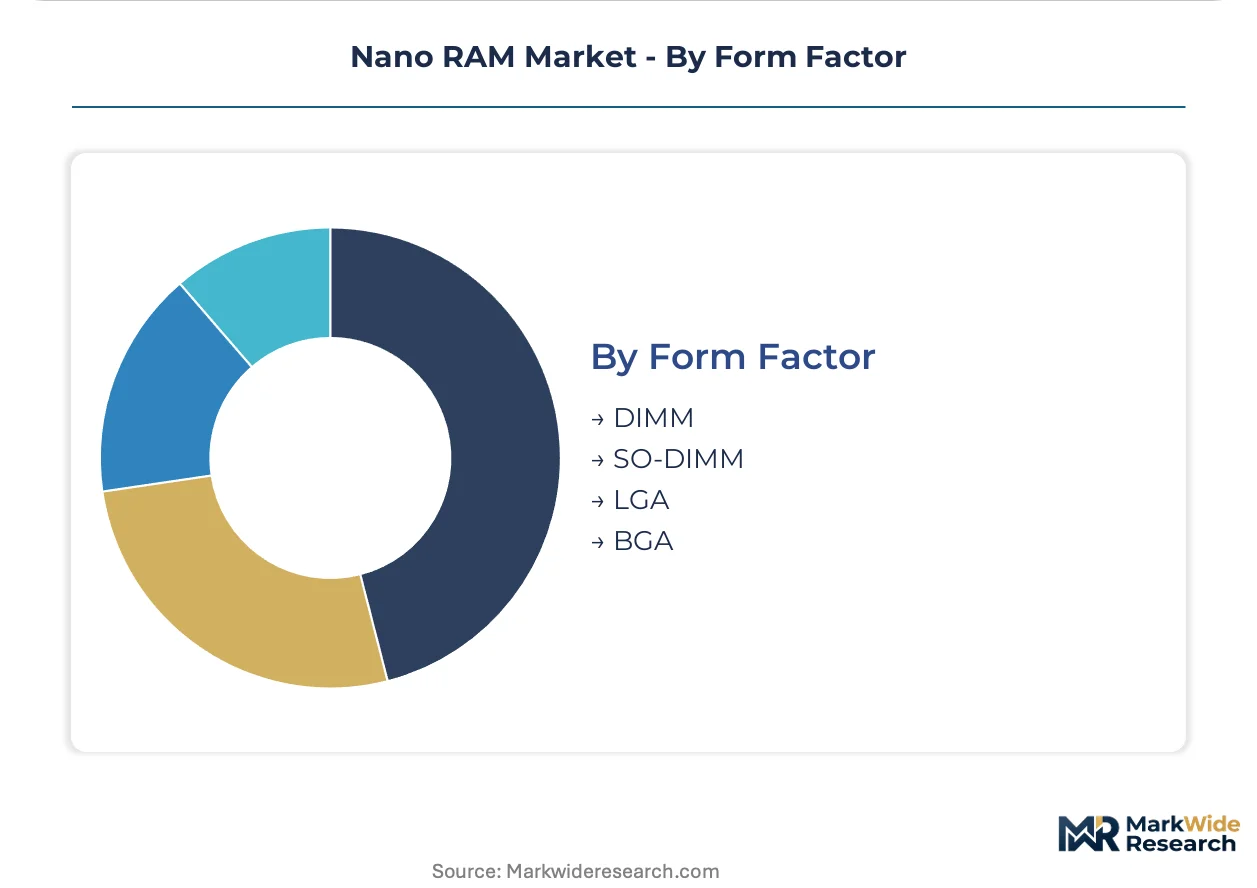
Form Factor:
Physical packaging determines socket compatibility and thermal management in space-constrained modules.
- DIMM:Dual in-line memory modules support server-grade persistent memory expansion. Data center operators in the United States specify these for audit-trail compliance under SEC record-keeping obligations.
- SO-DIMM:Small outline variants enable laptop and embedded system integration. Automotive telematics modules in German OEM programs increasingly specify this form factor for firmware update persistence.
- LGA:Land grid array packages minimize profile height for aerospace avionics where volumetric efficiency commands design priority. NASA satellite bus implementations favor this packaging for radiation-hardened subsystems.
- BGA:Ball grid array interconnects support high-density routing for smartphone and tablet persistent storage. ECHA 2024 Annex XIV updates forced reformulation of conductive adhesives used in this packaging category.
Mature deployment sits with BGA packaging for consumer mobile devices. Newer deployment is concentrated in LGA variants for aerospace volumetric constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Nano RAM concentrates in semiconductor manufacturing clusters where captive wafer capacity and automotive ECU integration converge. South Korea's Hwangju corridor anchors volume production through Samsung and SK Hynix co-location advantages. Regulatory frameworks in Europe and the United States are reshaping material qualification pathways for carbon nanotube fabrication.
United States
Defense contractors drive radiation-hardened specifications for satellite bus controllers under NASA and ESA qualification timelines. EPA reporting obligations for carbon nanotube manufacturing raise baseline compliance costs for domestic fabrication facilities. Aerospace concentration clusters in Southern California and Colorado Springs sustain demand for magnetoresistive variants commanding margin premiums.
South Korea
Automotive autonomous driving platforms from Hyundai and Kia demand sub-microsecond write endurance without battery backup systems. MFDS nanomaterial safety guidelines intersect with industrial chemical controls for fabrication facility licensing. The Hwangju semiconductor cluster enables co-location of Nano RAM production with DRAM foundry operations, reducing logistics costs for hybrid memory-module assemblers.
Germany
Tier-1 suppliers Continental and Bosch specify persistent cache requirements at the autonomous driving platform level, bypassing traditional semiconductor distributors. REACH substance authorization for multi-walled carbon nanotubes forces segregation between legacy and nanomaterial-qualified production lines. Bavarian automotive OEMs consolidate memory procurement under systems-integration contracts, compressing supplier qualification functions.
Japan
Consumer electronics OEMs specify Flash-derived Nano RAM variants for gaming console persistent storage with instant-on computing requirements. METI industrial standards govern carbon nanotube deposition equipment qualification for production-line integration. Tokyo-Osaka corridor assemblers favor SDRAM protocols for co-packaged modules combining volatile and non-volatile memory layers.
China
Domestic semiconductor self-sufficiency programs accelerate non-volatile memory foundry investments for edge inference hardware. MIIT nanotechnology fabrication standards align with GB technical regulations for industrial chemical purity. Yangtze River Delta equipment vendors migrate carbon nanotube deposition systems from R&D cleanrooms to production-line integration.
Nano RAM Market Competitive Landscape
South Korean producers anchor one tier through captive wafer capacity and DRAM foundry co-location; United States specialists hold defense-aerospace positioning through radiation-hardening certification relationships. Market structure tilts toward consolidated supply among memory conglomerates with backward integration into carbon nanotube synthesis, while deposition equipment vendors compete on process customization for automotive ECU specifications. Strategic archetypes include captive foundry operators, carbon nanotube deposition specialists, and bridge-controller firmware providers. Dominant competitive moves center on multi-source supply agreements for high-purity single-walled nanotube feedstock and co-location partnerships with Tier-1 automotive module assemblers.
Within the captive foundry tier, Samsung Electronics and SK Hynix occupy positions defined by Hwangju cluster proximity and hybrid memory-module assembly integration. Among deposition specialists, Nantero exemplifies the carbon nanotube crossbar array archetype with intellectual property differentiation in sub-10nm feature size achievement. TetraMem Inc represents the neuromorphic computing convergence vector where memristive-carbon integration promises unified memory-logic architectures. These three anchors illustrate how competitive positioning separates scale-driven conglomerates from technology-specialized licensors.
| Leading Market Players |
|---|
| TetraMem Inc |
| Samsung Electronics |
| Nantero |
| SK Hynix |
| Micron Technology |
| Weebit Nano Ltd |
| 4DS Memory Limited |
| TSMC |
| Crossbar Inc |
| Others |
Supply & Pricing Matrix
Radiation-hardened certification tiers create a three-tier pricing structure across premium, standard, and economy levels in Nano RAM procurement, with ESA and NASA qualification timelines concentrating margin capture among defense contractors while automotive telematics modules face cost compression from legacy Flash translation layer requirements. This bifurcation between aerospace-grade magnetoresistive variants and consumer-oriented Flash-derived cells manifests in divergent supply chain configurations: premium tiers anchor in captive foundry relationships with backward integration into carbon nanotube synthesis, while economy tiers fragment across deposition equipment vendors competing on process customization.
Pricing Analysis
Volume-vs-margin split separates automotive ECU procurement from satellite bus controller demand. Three-tier pricing structure across premium, standard, and economy levels dominates: radiation-hardened magnetoresistive cells command certification premiums under ESA and NASA timelines, Flash-derived variants compete on bill-of-materials targets for gaming consoles, and EEPROM-compatible SO-DIMM form factors occupy the mid-market for telematics modules. Pricing pressure stems from REACH compliance costs transferring upstream to Japanese and South Korean material suppliers. Automotive Tier-1 suppliers exhibit highest price sensitivity due to systems-integration contract consolidation, while aerospace defense contractors show lowest sensitivity given mission-critical qualification requirements.
Supply Chain Analysis
High-purity single-walled carbon nanotube feedstock rests on three Asian chemical conglomerates, creating single-source vulnerability for deposition equipment operators in the United States, Germany, and South Korea. Raw material dependencies center on carbon nanotube synthesis precursors, conductive adhesives for BGA packaging, and specialized Raman spectroscopy equipment for batch consistency verification. Tariff exposure concentrates in wet-etch process chemicals subject to ECHA Annex XIV updates. Distribution runs through Tier-1 automotive module assemblers in Bavaria and Lower Saxony who have absorbed qualification functions from independent distributors, compressing channel margins for memory semiconductor vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon nanotube metrology expertise scarcity props pricing power for qualified suppliers, constraining capacity expansion across fewer than twelve global training facilities capable of industrial-scale Raman spectroscopy and electron microscopy certification.
For Market Incumbents: Anticipate deposition equipment democratization eroding process customization premiums by migrating carbon nanotube systems from R&D cleanrooms to production-line integration. Consolidate through captive supply of high-purity single-walled nanotube feedstock to offset single-source vulnerability from Asian chemical conglomerates. Deepen co-location partnerships with Hwangju cluster DRAM foundries to defend hybrid memory-module assembly margins against emerging neuromorphic computing convergence threats. For New Entrants and Emerging Players: Begin with FDA nanomaterial biocompatibility pathway development for implantable medical device applications, where carbon-based memory cell toxicology dossiers remain underdeveloped and first-mover advantage persists. Target automotive telematics firmware update persistence as the most penetrable segment given EEPROM form factor lock-in forcing bridge-controller costs onto legacy Flash adopters. Pursue direct equipment vendor relationships with German Tier-1 suppliers specifying cell geometries, bypassing traditional memory semiconductor procurement channels compressed under BMW and Volkswagen systems-integration contracts. For Investors and Strategic Acquirers: Re-rating potential sits with carbon nanotube deposition specialists given EU AI Act data persistence mandates creating structural demand for non-volatile memory in edge inference hardware without battery backup systems. Long-term viability across the analysis window favors intellectual property holders in sub-10nm feature size achievement over scale-driven conglomerates facing REACH compliance cost inflation. Watch carbon nanotube crossbar array maturation milestones as the inflection indicator for aerospace and satellite application expansion previously reserved for magnetoresistive technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Synthesis | Captive feedstock supply mitigates single-source concentration risk among Asian chemical conglomerates. |
| Co-Location Partnership with DRAM Foundries | Hwangju cluster proximity reduces logistics costs for hybrid memory-module assemblers serving automotive platforms. |
| FDA Nanomaterial Biocompatibility Submission | Complete toxicology dossiers create first-mover advantage in implantable medical device data persistence applications. |
| REACH-Compliant Dry-Deposition Process Qualification | Pre-certified nanotube grades satisfy German automotive supplier demands transferring compliance upstream. |
| Neuromorphic Computing Architecture Development | Memristive-carbon convergence enables unified memory-logic architectures for edge inference accelerators under EU AI Act mandates. |
Research Methodology
Document review covered SEC filings from memory semiconductor vendors, ECHA substance authorization databases, and NASA ESA qualification standards, complemented by interviews with carbon nanotube deposition equipment engineers, automotive ECU procurement managers at Continental and Bosch, and regulatory affairs specialists navigating REACH Annex XIV updates. Primary fieldwork included discussions with Hwangju cluster foundry operations directors and aerospace subsystem integrators specifying radiation-hardened memory requirements. Secondary validation drew from customs trade data for carbon nanotube precursor chemicals, MFDS nanomaterial safety guidelines, and METI industrial standards for production-line equipment qualification. Bottom-up cell geometry demand modeling triangulated against top-down autonomous driving platform memory content forecasts.
Output modeling produced segment-level volume and value trajectories across memory cell architectures, interface protocols, and end-use applications throughout the forecast period. Segmentation dimensions included physical switching mechanisms, form factor specifications, and regional regulatory clusters governing nanomaterial fabrication licensing. CAGRs derived from automotive ECU specification velocity, EU AI Act implementation timelines, and carbon nanotube deposition equipment production-line migration rates. Industry-specific inputs encompassed ESA NASA 18-24 month qualification cycle durations and REACH substance authorization threshold triggers.
Underlying measurement precision varies by segment; radiation-hardened aerospace applications carry tighter precision than consumer electronics given defined certification timelines, while automotive telematics module forecasts reflect greater uncertainty from legacy Flash translation layer abstraction resistance. Forecasts embed assumptions regarding carbon nanotube feedstock concentration persistence and deposition equipment democratization velocity. A small set of triggers warrants ongoing watch: ECHA Annex XIV expansion to additional carbon nanotube grades, FDA nanomaterial biocompatibility pathway rulings for implantable devices, and automotive OEM consolidation of memory procurement under systems-integration contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
In-Memory Computing Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Memory Module Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
DDR SDRAM Market
Memory Chips
DDR RAM Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Static RAM Market
Memory Chips
New RAM Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market