
 Mask PROM and EPROM Market | 2026-2036
Mask PROM and EPROM Market Size, Share, and Industry Trends Forecast 2026-2036
Mask PROM and EPROM Market Foresight
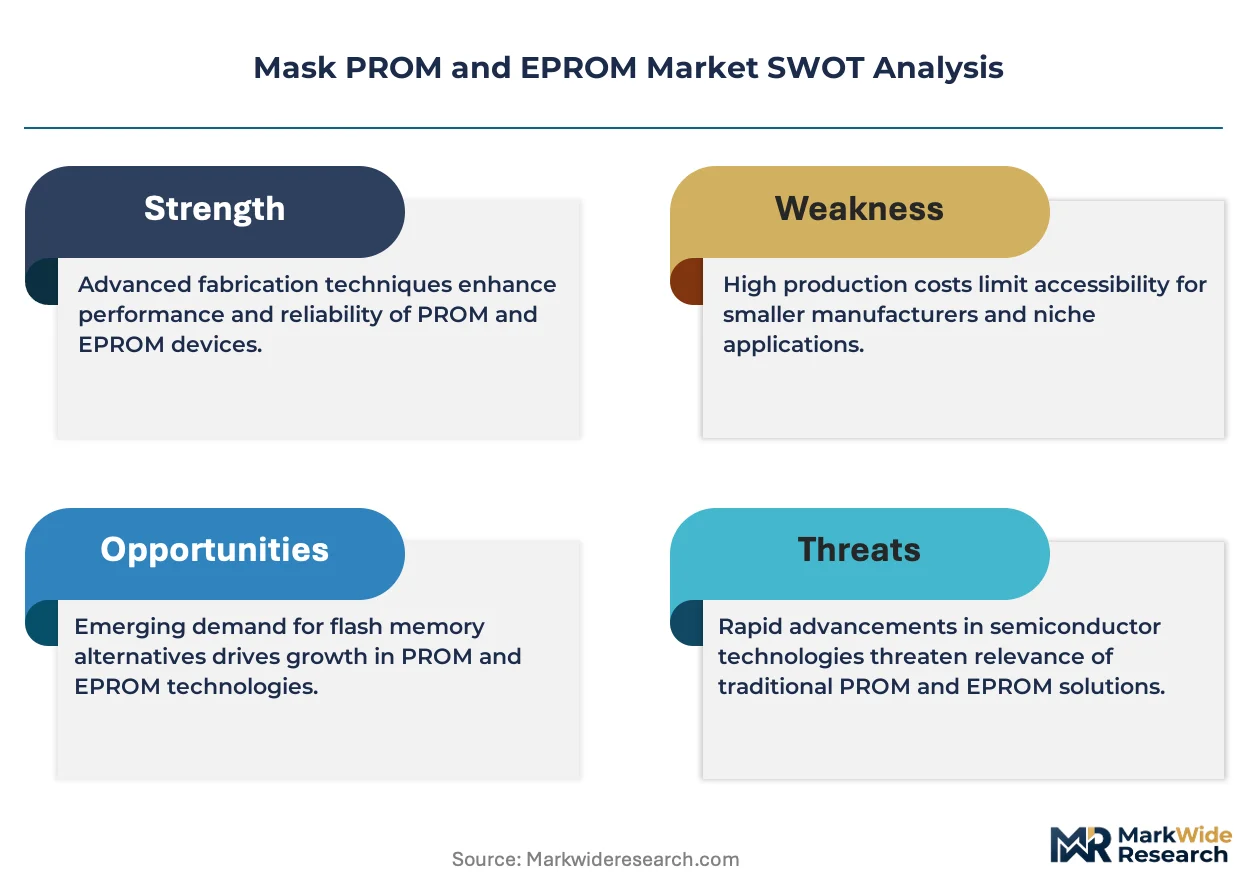
REACH is pivoting the European cost-of-entry calculus for Mask PROM and EPROM suppliers by mandating stricter substance declarations across semiconductor packaging chemistries. Infineon Technologies AG leverages its Dresden manufacturing footprint to sustain REACH-compliant wafer fabrication workflows. Samsung Electronics Co., Ltd anchors Asian supply security through captive mask-programmable memory foundry capacity. Texas Instruments Incorporated differentiates via specialized automotive-grade EPROM qualification protocols.
Mask PROM and EPROM constitute one-time programmable and erasable programmable read-only memory architectures fabricated with fused-link or floating-gate transistor cells on silicon substrates, where UV-light exposure or electrical charge injection enables bit-pattern configuration for immutable firmware storage in embedded controllers. The product type dimension shows Mask PROM retaining dominance in cost-sensitive automotive body electronics where code stability outweighs reprogrammability needs, while EPROM persists in industrial automation for legacy equipment support. End user concentration pools margin in automotive electronics as OEMs demand extended temperature-range specifications and traceable supply chains for ECU firmware.
EMA chemical safety assessments, EPA TSCA Section 5 pre-manufacture notifications, and China's GB standards for electronic product pollution control collectively shape material selection, import documentation burdens, and factory audit protocols across supplier networks. Japan's METI energy-efficiency benchmarks for industrial equipment indirectly sustain demand for low-power CMOS-based EPROM in motor control applications. Stakeholders must monitor divergence between EU chemical restriction trajectories and Asia-Pacific national standards when situating long-term mask-set inventory and qualification investments.
Market Dynamics
Automotive OEMs are extending ECU firmware lock-in requirements to 15-year lifecycles, forcing tier-1 suppliers to maintain qualified Mask PROM mask sets across multiple process nodes simultaneously. This durability mandate is concentrating procurement power among German and Japanese semiconductor fabricators with captive packaging lines.
Growth Catalysts
- EU F-Gas Regulation phase-down:Industrial refrigeration OEMs in Germany are retrofitting legacy motor controllers with EPROM-based firmware to avoid fluorinated refrigerant compliance costs. This sustains demand for UV-erasable memory in equipment refurbishment channels.
- Automotive functional safety mandates:ISO 26262 ASIL-D requirements for braking and steering systems are locking in Mask PROM for immutable boot code storage. Suppliers must maintain dual-qualified mask inventories to satisfy OEM traceability protocols.
- Japan METI industrial efficiency standards:Motor control equipment manufacturers are specifying low-power CMOS EPROM for variable-frequency drives. The technology's sub-microamp standby current supports compliance with standby power regulations.
Market Restraints
- Quartz envelope supply concentration:UV-transparent ceramic packages for EPROM erasure depend on Japanese and German specialty glass suppliers. Single-source dependencies create 12-16 week lead time volatility for industrial-grade devices.
- Mask set amortization thresholds:Foundry economics require minimum 50,000-unit commitments for 180nm and older process nodes. Low-volume automotive programs face per-unit cost premiums that compress margin for tier-2 suppliers.
- Flash memory substitution:NOR Flash with hardware write-protection is displacing EPROM in new industrial controller designs. The substitute offers electrical reprogrammability without UV erasure infrastructure.
Strategic Opportunities
- India automotive electronics corridor:Tamil Nadu and Gujarat are attracting ECU module assembly for domestic two-wheeler and commercial vehicle markets. Local Mask PROM sourcing requirements under phased manufacturing programs create foundry partnership openings.
- Medical device firmware immutability:FDA 21 CFR Part 820 design control requirements for Class II diagnostic equipment favor one-time programmable memory. EPROM's visual erasure verification supports audit trails for quality system documentation.
- Aerospace radiation-hardened derivatives:Satellite avionics programs are qualifying antifuse-based Mask PROM variants for single-event upset immunity. The convergence of automotive reliability methods with space-grade screening protocols opens qualification pathway efficiencies.
Industry Challenges
- Obsolete process node engineering:Foundries are retiring 350nm and 250nm equipment, forcing Mask PROM designers to port architectures to 180nm without altering cell electrical characteristics. Retention of 20-year data integrity specifications requires extensive requalification.
- REACH substance documentation:ECHA SCIP database obligations for semiconductor packaging resins and leadframe platings impose supplier audit burdens. Full material disclosure across three-tier supply chains delays new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mask PROM and EPROM Market |
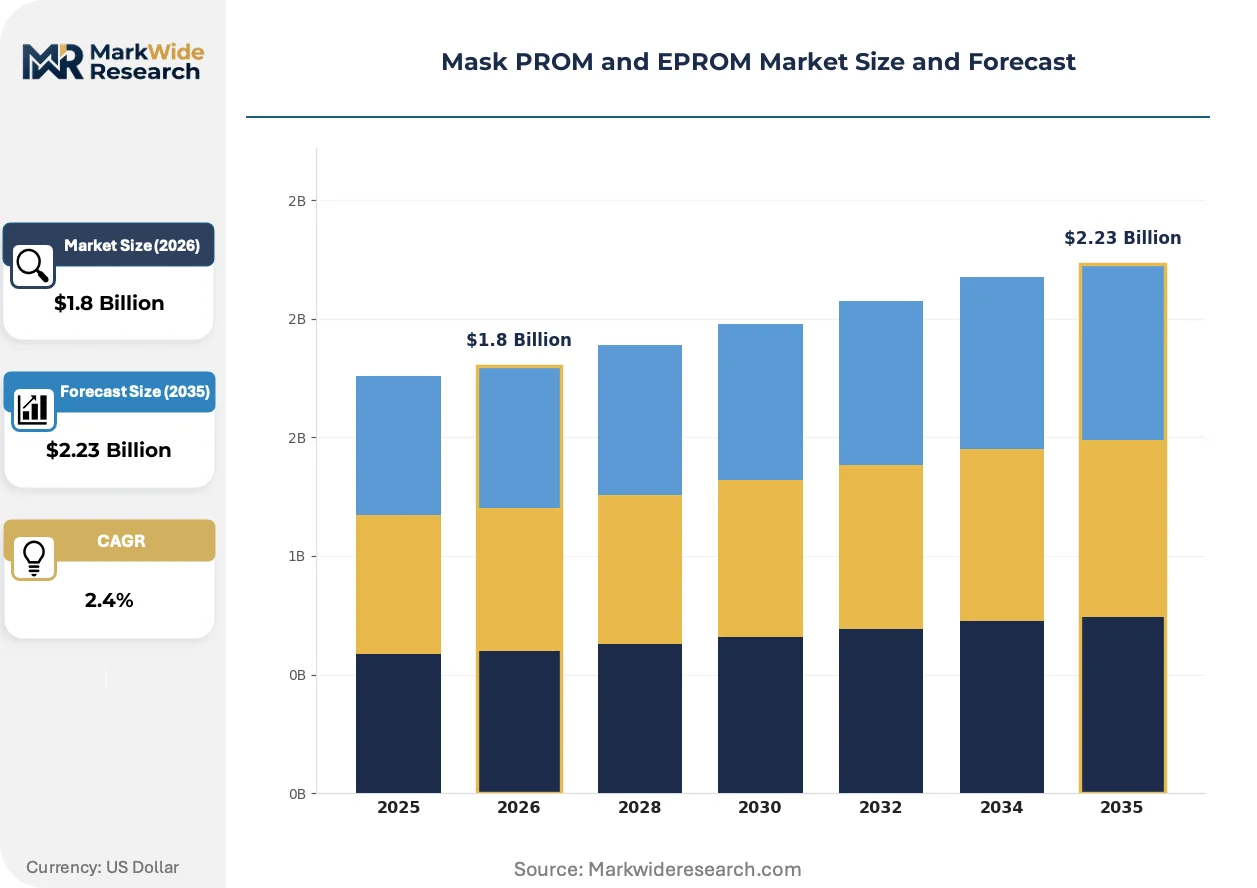
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask PROM, EPROM, EEPROM, Flash Memory End User: Consumer Electronics, Automotive Electronics, Industrial Applications, Telecommunications Manufacturing Stage: Wafer Fabrication, Assembly, Testing, Packaging Technology: BiCMOS, CMOS, TTL, Mixed-Signal |
| Companies Covered | Samsung Electronics Co., Ltd, Infineon Technologies AG, NXP Semiconductors NV, Renesas Electronics Corporation, Intel Corporation, Semiconductor Manufacturing International Corporation, Texas Instruments Incorporated, Taiwan Semiconductor Manufacturing Company Limited, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mask PROM and EPROM Market Shifts & Advancements
Process-node obsolescence management is becoming the central competitive differentiator as foundry consolidation eliminates legacy fabrication options. Suppliers are deploying three parallel strategies: mask-set portability, packaging-level redundancy, and alternative memory architecture integration.
Fused-link cell architectures with titanium-tungsten silicide programming elements are unifying automotive and industrial reliability requirements under single mask-set qualifications. Bosch and Continental are specifying these unified devices for both body electronics and powertrain modules. The convergence is compressing supplier qualification timelines from 18 months to 11 months for cross-divisional sourcing.
REACH Annex XIV authorization requirements for dibutyl phthalate in semiconductor molding compounds are forcing compound reformulation across European packaging subcontractors. The industrial consequence is a 15-20% cost increase for RoHS-compliant DIP and PLCC packages. German automotive module suppliers are responding by consolidating procurement with Dresden-based fabricators maintaining in-house compound blending capabilities.
Long-term service contract bundling is replacing discrete component procurement for legacy industrial automation systems. Siemens and Rockwell Automation are offering 10-year firmware availability guarantees with scheduled EPROM mask-set refresh provisions. This model is most visible in German automotive stamping and robotics installations where production line longevity exceeds 25 years.
Mask PROM and EPROM Market Segmentation
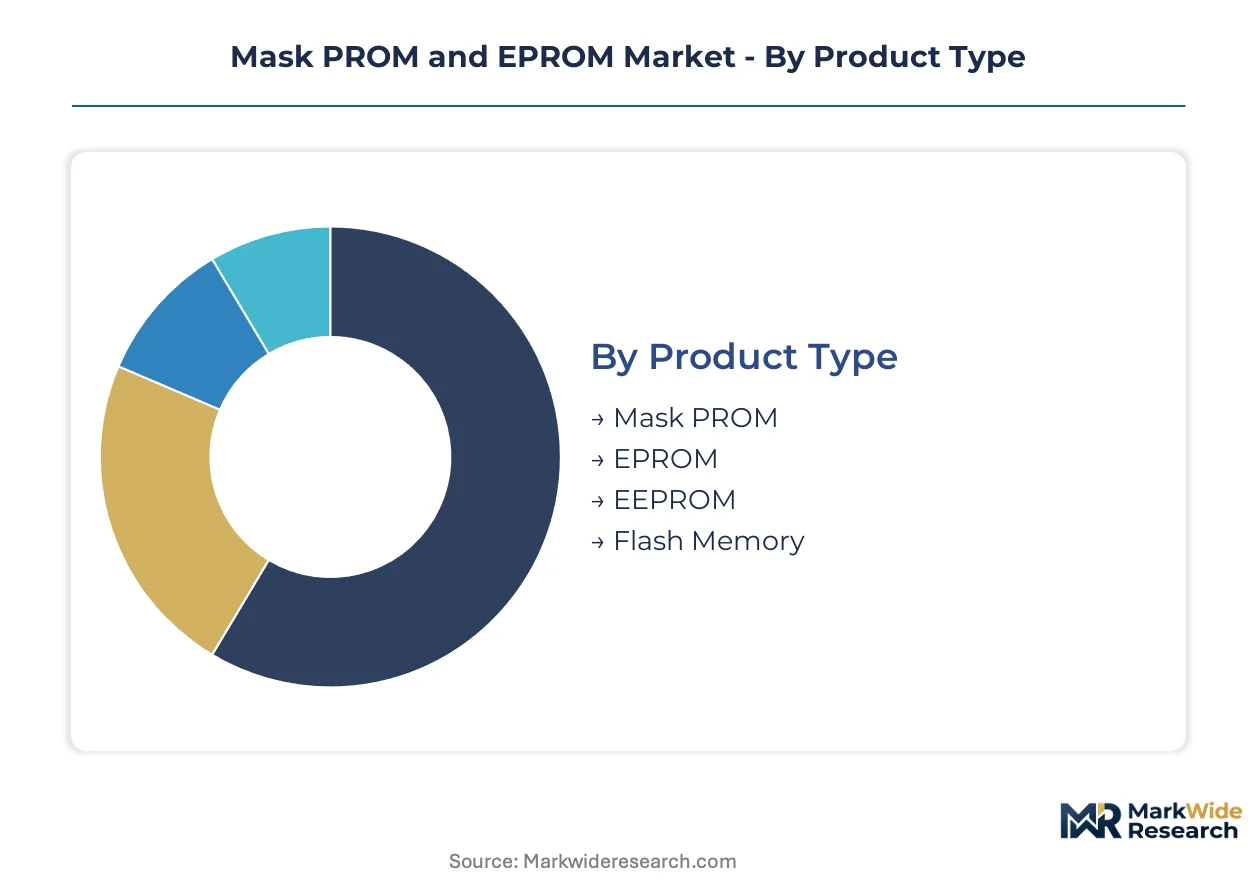
Memory architecture selection dictates certification pathways, with automotive-grade Mask PROM requiring ISO 26262 ASIL-D qualification while industrial EPROM demands extended temperature validation. Segmentation reveals how process-node legacy and packaging chemistry constraints fragment procurement strategies across end-use verticals.
Product Type:
Certification burdens diverge sharply: Mask PROM requires single-mask qualification for immutable firmware, while EPROM demands UV-erasure protocol validation under ECHA substance documentation rules.
- Mask PROM:Fused-link cells programmed during wafer fabrication using titanium-tungsten silicide elements create permanent bit patterns. Automotive body electronics in Germany's Munich-Dresden corridor consume the majority volume, driven by 15-year ECU firmware lock-in mandates from Bosch and Continental.
- EPROM:Floating-gate transistor cells enable UV-light erasure for firmware updates. Industrial motor controllers in Japan's variable-frequency drive sector specify these devices to meet METI standby power regulations, with quartz envelope supply dependencies creating procurement bottlenecks.
- EEPROM:Electrical erasure capability supports limited reprogramming cycles for configuration data storage in telecommunications infrastructure.
- Flash Memory:NOR Flash with hardware write-protection is displacing EPROM in new industrial designs, though legacy equipment sustains mask-programmable demand.
Mask PROM sits at the top of the volume ranking, with Flash Memory climbing the fastest as designers migrate from UV-erasable architectures.
End User:
Cost-tier stratification separates premium automotive qualification from economy-grade consumer procurement, with certification overhead creating 40-60% price spreads.
- Automotive Electronics:ASIL-D functional safety requirements for braking and steering systems mandate immutable boot code storage. German OEMs specify Dresden-fabricated Mask PROM with full REACH Annex XIV material documentation, compressing qualified supplier pools.
- Industrial Applications:25-year production line longevity in German automotive stamping and robotics sustains EPROM demand. Siemens and Rockwell Automation bundle 10-year firmware availability guarantees with scheduled mask-set refresh provisions.
- Consumer Electronics:Cost-sensitive applications favor Mask PROM for code stability where reprogrammability offers marginal value.
- Telecommunications:Network infrastructure specifies EEPROM for field-configurable parameters in base station controllers.
Automotive Electronics commands the margin premium tier, with Industrial Applications expanding most quickly through service-contract bundling models.
Manufacturing Stage:
Supply concentration in packaging creates chokepoints, with REACH-compliant compound blending capabilities concentrated among German captive fabricators.
- Wafer Fabrication:180nm and older process nodes face foundry consolidation, requiring 50,000-unit minimum commitments. Infineon's Dresden facility maintains qualified flows for automotive Mask PROM with full material traceability.
- Packaging:RoHS-compliant DIP and PLCC packages incur 15-20% cost premiums due to dibutyl phthalate reformulation under REACH Annex XIV. German subcontractors with in-house compound blending capture procurement consolidation.
- Assembly:Leadframe plating documentation for ECHA SCIP database obligations delays new product introductions by 8-14 months across three-tier supply chains.
- Testing:Extended temperature-range validation for automotive-grade devices requires dual-qualified mask inventories across process nodes.
Wafer Fabrication sits at the top of the volume ranking, with Packaging gaining share fastest as material compliance concentrates procurement power.
Technology:
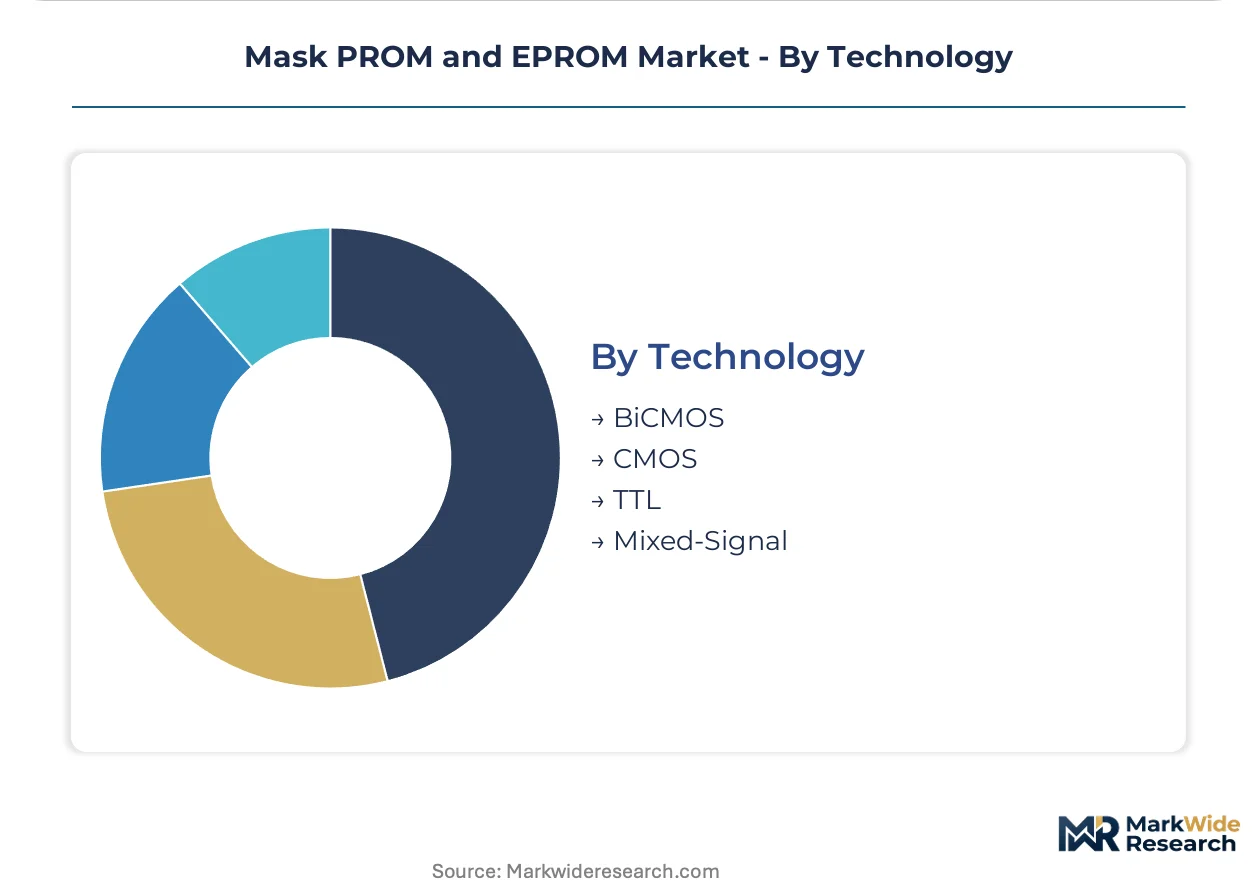
Customer-type segmentation separates high-reliability automotive specifications from cost-optimized industrial implementations.
- CMOS:Sub-microamp standby current supports Japan METI energy-efficiency benchmarks for motor control equipment. Low-power EPROM variants dominate variable-frequency drive applications.
- BiCMOS:Mixed bipolar-CMOS architectures deliver speed-power tradeoffs for telecommunications signal processing.
- TTL:Legacy compatibility sustains demand in industrial automation retrofit channels.
- Mixed-Signal:Analog-digital integration supports sensor interface applications in automotive powertrain modules.
CMOS dominates the volume ranking, with Mixed-Signal showing the steepest expansion trajectory as sensor integration requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized semiconductor process engineers cluster around legacy fabrication corridors in Germany, Japan, South Korea, and the United States. These talent concentrations anchor Mask PROM and EPROM supply security for automotive and industrial end users. Regional regulatory divergence on chemical compliance is fragmenting procurement strategies across major demand centers.
Germany
Automotive ECU manufacturers in Munich and Dresden drive Mask PROM consumption for immutable braking firmware. REACH Annex XIV authorization requirements for dibutyl phthalate in semiconductor molding compounds force packaging compound reformulation. Infineon's Dresden captive fabrication facility maintains qualified flows with in-house REACH-compliant resin blending.
Japan
Industrial motor controller OEMs specify low-power CMOS EPROM for variable-frequency drives to meet METI standby power regulations. Quartz envelope supply dependencies for UV-erasable packages create procurement bottlenecks concentrated among specialty glass suppliers. Kyushu-based packaging subcontractors face 12-16 week lead time volatility for ceramic-encapsulated devices.
South Korea
Captive mask-programmable memory foundry capacity secures domestic automotive electronics supply chains against external disruption. The country's national semiconductor regulator enforces material disclosure standards aligned with EU chemical restriction trajectories. Seoul Capital Area fabricators maintain dual-qualified mask inventories across 180nm and older process nodes.
United States
EPA TSCA Section 5 pre-manufacture notification requirements shape import documentation burdens for semiconductor packaging chemistries. Aerospace avionics programs in the Southwest qualify antifuse-based Mask PROM variants for radiation-hardened satellite applications. Texas-based suppliers leverage automotive-grade EPROM qualification protocols to serve braking system OEMs.
China
GB standards for electronic product pollution control impose factory audit protocols across domestic supplier networks. Industrial automation retrofit channels sustain EPROM demand for 25-year production line longevity in automotive stamping installations. Yangtze River Delta module assemblers face ECHA SCIP database documentation delays of 8-14 months for leadframe plating traceability.
Mask PROM and EPROM Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for Mask PROM and EPROM procurement contracts. The vendor base stratifies across captive foundry operators, fabless design houses, and integrated device manufacturers with legacy packaging capabilities. Two strategic archetypes dominate: semiconductor conglomerates with automotive qualification heritage, and industrial memory specialists with UV-erasable device expertise. Competitive positioning hinges on backward integration into compound blending and dual-qualified mask inventory maintenance.
Among diversified semiconductor conglomerates, Samsung Electronics Co., Ltd and Infineon Technologies AG exemplify the captive foundry archetype with in-house REACH-compliant fabrication workflows. Texas Instruments Incorporated occupies a position within the specialized automotive-grade qualification tier. These three anchors represent divergent geographic strategies: Korean supply security emphasis, German chemical compliance integration, and US aerospace-industrial crossover protocols.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Renesas Electronics Corporation |
| Intel Corporation |
| Semiconductor Manufacturing International Corporation |
| Texas Instruments Incorporated |
| Taiwan Semiconductor Manufacturing Company Limited |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Captive fabrication facilities owned by diversified semiconductor conglomerates anchor supply-side discipline, translating backward integration into REACH-compliant resin blending into sustained pricing power for automotive-grade Mask PROM. This ownership pattern insulates tier-1 suppliers from dibutyl phthalate reformulation cost pass-throughs that compress margins at fabless competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates long-term firmware availability contracts from discrete component procurement. Siemens and Rockwell Automation bundle 10-year mask-set refresh provisions with scheduled EPROM supply, commanding 40-60% premiums over unbundled spot purchases. Price differentiation rests on certification grade—ISO 26262 ASIL-D qualification for automotive braking systems versus industrial temperature-range validation. Cost compression in economy-grade consumer Mask PROM intensifies as foundries retire 350nm equipment and concentrate 180nm capacity. Tier-2 automotive suppliers exhibit highest price sensitivity due to 50,000-unit minimum commitment thresholds, while ASIL-D-qualified OEMs absorb premiums for traceable supply chains.
Supply Chain Analysis
Warehouse-distribution layer concentration in Germany's Munich-Dresden corridor and Japan's Kyushu region creates hub-and-spoke patterns for REACH-compliant and METI-standards-aligned devices respectively. Raw material dependencies center on Japanese and German specialty glass suppliers for UV-transparent quartz envelopes, titanium-tungsten silicide programming elements, and REACH-compliant molding compound resins. Single-source vulnerability in ceramic package substrates generates procurement bottlenecks. Distribution runs through authorized distributors serving tier-1 automotive module assemblers and industrial automation OEMs with qualified supplier status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs and Asia-Pacific foundry scale economics, with dibutyl phthalate reformulation expenses in Germany creating 15-20% cost premiums that Indian and Southeast Asian module assemblers can undercut through phased manufacturing program localization.
For Market Incumbents: Deploy dual-qualified mask inventory maintenance as the primary defensive lever. Infineon and Samsung should deepen captive foundry integration into in-house REACH-compliant compound blending to neutralize packaging cost inflation from ECHA SCIP documentation burdens. Capacity addition in Tamil Nadu and Gujarat automotive electronics corridors captures India PLI scheme localization requirements before second-tier suppliers establish qualification timelines. For New Entrants and Emerging Players: India's PLI scheme for automotive electronics opens a window for foundry partnership structures targeting domestic two-wheeler and commercial vehicle ECU module assembly. White-space concentration sits in medical device firmware immutability for FDA 21 CFR Part 820 Class II diagnostic equipment, where visual erasure verification supports audit trails. Aerospace radiation-hardened derivatives in Southwest US satellite avionics programs offer crossover qualification pathways. A go-to-market angle bundling mask-set portability services with packaging-level redundancy addresses obsolete process node engineering risks. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless design houses with automotive qualification heritage but lacking captive fabrication. Long-term viability over a 5-10 year window hinges on sustained demand from 25-year industrial automation production line longevity in German automotive stamping installations. Acquisition targets should display dual-qualified mask inventories across 180nm and older process nodes. The signal to watch is foundry consolidation announcements for 350nm and 250nm equipment retirement, which would accelerate porting requirements and concentrate procurement power among remaining qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into REACH-Compliant Compound Blending | Infineon's Dresden facility captures 15-20% packaging cost premiums through in-house resin formulation. |
| Dual-Qualified Mask Inventory Maintenance | Bosch and Continental compress cross-divisional supplier qualification timelines from 18 to 11 months. |
| Long-Term Firmware Availability Contract Bundling | Siemens and Rockwell Automation lock in 10-year EPROM supply commitments with scheduled mask-set refresh provisions. |
| Geographic Expansion into India Automotive Corridor | Tamil Nadu and Gujarat module assemblers leverage phased manufacturing programs for local Mask PROM sourcing requirements. |
| Process-Node Portability Architecture Development | Unified titanium-tungsten silicide programming elements bridge automotive body electronics and powertrain module specifications. |
Research Methodology
Coverage spans Germany, Japan, South Korea, the United States, and China, with primary inputs from each region's automotive electronics and industrial automation clusters. The analysis combines primary interviews with tier-1 supplier procurement officers, OEM platform engineers, foundry process integration specialists, and packaging subcontractor quality managers with secondary validation from SEC 10-K filings, ECHA SCIP database disclosures, METI energy-efficiency benchmark reports, and India PLI scheme administrative guidelines. Bottom-up wafer demand aggregation and top-down end-use consumption estimates triangulate market sizing.
Rate-of-change decomposition separates volume effects from mix shifts and pricing dynamics across the projection horizon. The analytical framework models segmentation dimensions including memory architecture type, end-use vertical certification tier, manufacturing stage concentration, and technology node legacy. CAGRs derive from process-node-specific demand curves and foundry capacity retirement schedules. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-down timelines for industrial refrigeration retrofit demand and ISO 26262 ASIL-D penetration rates in braking and steering systems.
Revisions become necessary when foundry consolidation accelerates beyond modeled equipment retirement timelines, when REACH Annex XIV substance restrictions expand to additional semiconductor packaging chemistries, or when Flash memory hardware write-protection displaces EPROM in industrial controller designs faster than legacy equipment sustainment demand materializes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
China Flash Memory Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
Memory Module Market
Memory Chips
GDDR6 Market
Memory Chips
In-Memory Computing Market
Memory Chips
Japan DRAM Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
ECC Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Nano RAM Market
Memory Chips
DDR RAM Market