
 Europe Dynamic Random Access Memory (DRAM) Market | 2026-2036
Europe Dynamic Random Access Memory (DRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dynamic Random Access Memory (DRAM) Market Insights
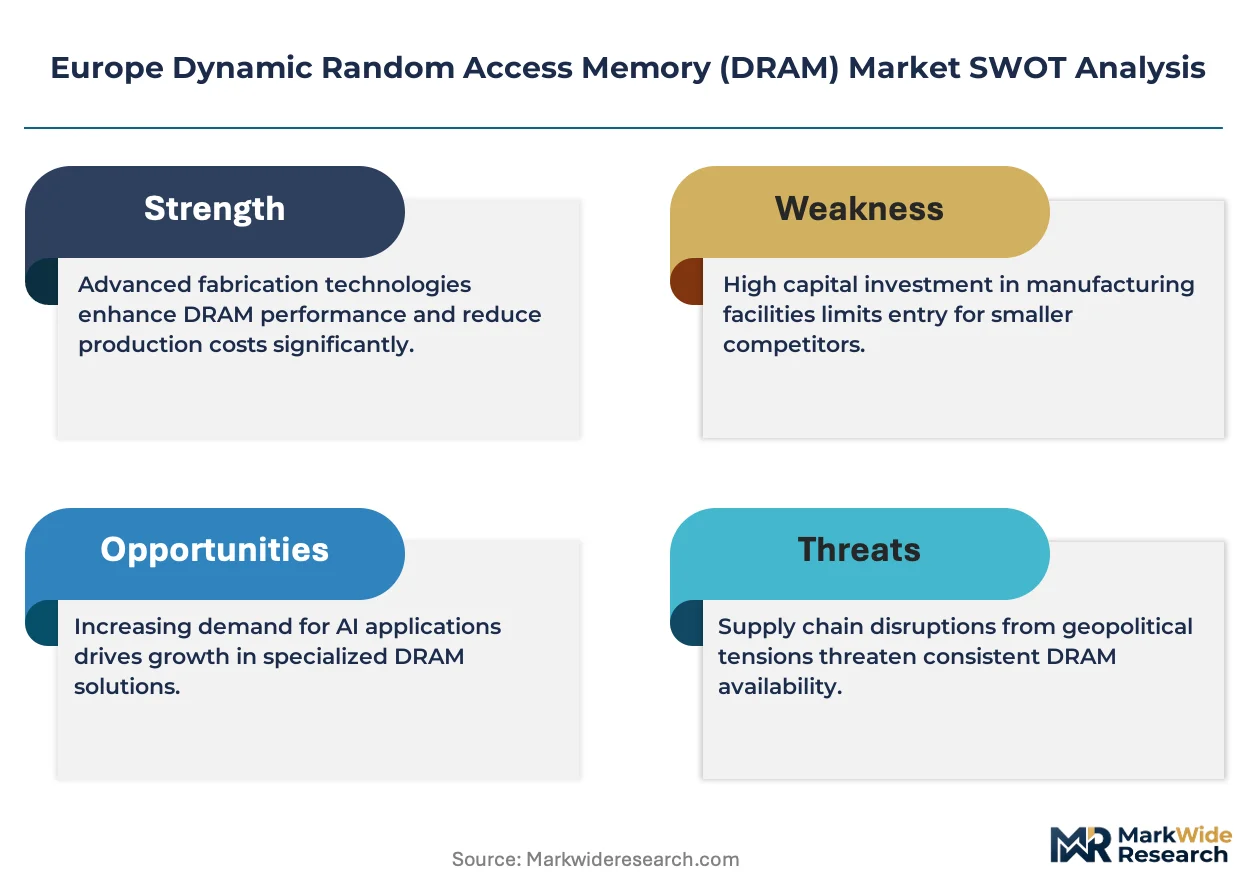
The EU Green Deal is decoupling memory procurement from carbon-intensive supply chains, compelling European data center operators to source DRAM with verified low-emission fabrication footprints. Samsung Electronics Co. Ltd leverages its EUV lithography leadership to sustain premium positioning across German automotive qualification programs. Infineon Technologies anchors industrial-grade memory supply through captive back-end facilities in Dresden and Villach. Micron Technology Inc. competes on advanced packaging density for AI accelerator boards bound for French cloud campuses.
Dynamic Random Access Memory (DRAM) stores each data bit within an integrated circuit capacitor paired with a transistor, requiring continuous electrical refresh to retain information; cells typically organize in rectangular arrays addressed by multiplexed row and column selectors, with contemporary modules operating at transfer rates exceeding several gigabits per second per pin. DDR3 maintains volume dominance in legacy industrial controllers across European automation networks, while DDR commands expanding share in AI training servers where bandwidth-per-watt determines rack economics. Embedded Systems applications concentrate margin pools where ATP Electronics and Winbond Electronics Corporation specialize in extended-temperature modules for railway signaling and medical imaging.
REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging, forcing reformulation of lead-based interconnects and flame-retardant substrates across European-bound shipments. The EU AI Act imposes transparency requirements on high-risk systems that embed DRAM-dependent inference engines, shaping verification protocols for automotive and healthcare deployments. ECHA substance-of-very-high-concern listings continue expanding, adding compliance layers to etching chemistry supply chains serving Dresden and Leuven fabs. Stakeholders must monitor how the F-Gas Regulation phases affect thermal management refrigerants in memory test facilities, as replacement technologies alter equipment amortization schedules and foundry location decisions.
Market Dynamics
EU Green Deal carbon-accounting mandates are decoupling memory procurement from carbon-intensive supply chains, compelling European data center operators to source DRAM with verified low-emission fabrication footprints.
Growth Catalysts
- AI server deployment:French and German cloud campuses are scaling memory-intensive training workloads, driving qualification programs for high-bandwidth modules.
- REACH substance restrictions:Reformulation mandates for lead-based interconnects are accelerating adoption of advanced packaging technologies across European-bound shipments.
- Automotive edge computing:German OEM qualification programs for autonomous systems are pulling industrial-grade memory through captive back-end facilities in Dresden and Villach.
Market Restraints
- EUV equipment concentration:Lithography tool dependency on single-source suppliers creates capacity bottlenecks for advanced node migration.
- F-Gas phase-down schedule:Thermal management refrigerant restrictions under the EU F-Gas Regulation are extending equipment amortization timelines at memory test facilities.
- Legacy DDR3 lock-in:Industrial automation networks across European manufacturing bases maintain volume dominance of older protocols, compressing upgrade cycles.
Strategic Opportunities
- Netherlands lithography cluster:ASML ecosystem proximity enables advanced packaging density for AI accelerator boards serving French cloud campuses.
- EU AI Act transparency mandates:Verification protocol requirements for high-risk inference engines create certified-memory premiums in automotive and healthcare deployments.
- Railway signaling modernization:Extended-temperature module demand from ATP Electronics and Winbond Electronics Corporation concentrates margin pools in transportation infrastructure.
Industry Challenges
- EUV technician scarcity:Specialized lithography maintenance skill gaps constrain fab utilization rates at Dresden and Leuven facilities.
- Multi-node qualification timelines:Automotive-grade certification cycles spanning 18-24 months delay revenue recognition for new memory architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dynamic Random Access Memory (DRAM) Market |
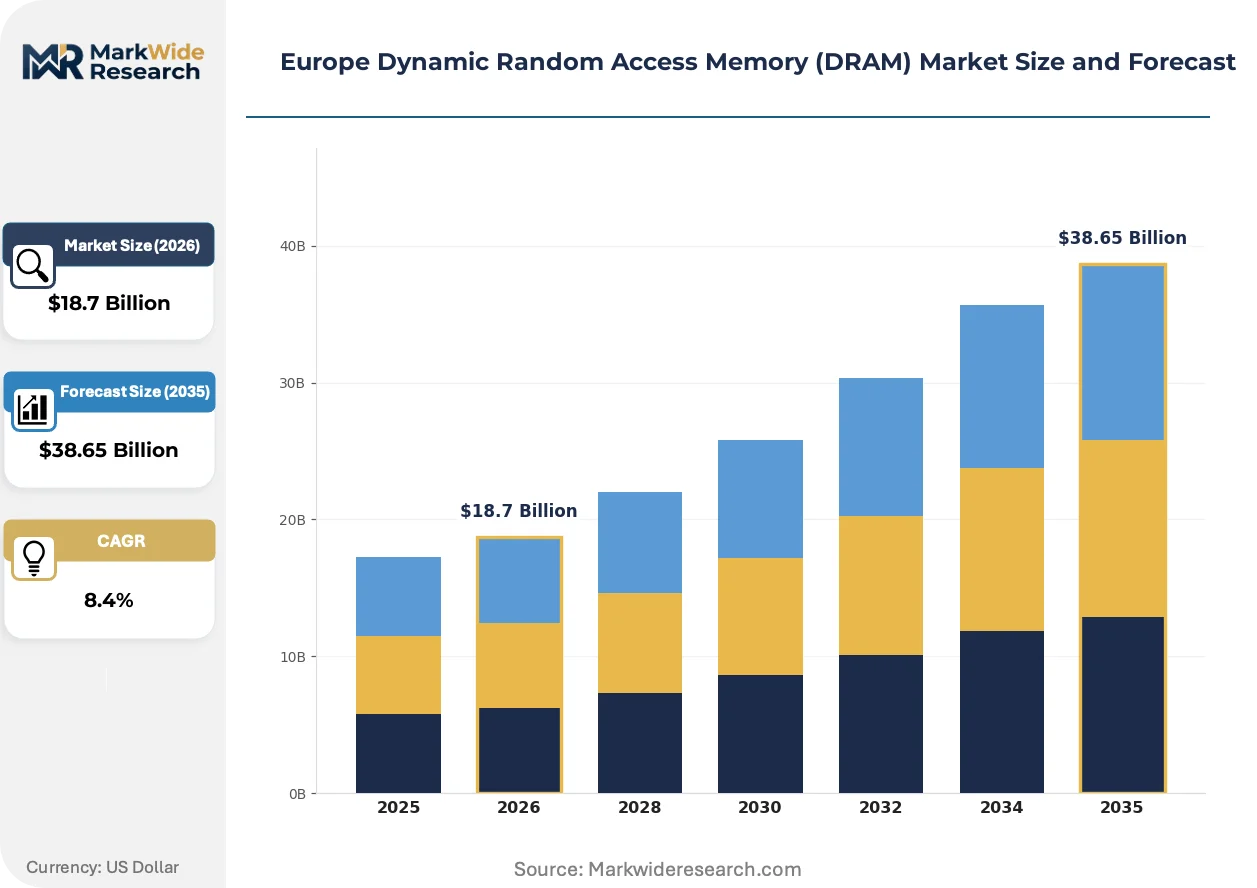
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SDRAM, DDR, DDR2, DDR3 Application: Computers, Servers, Mobile Devices, Embedded Systems End User: Consumer Electronics, Data Centers, Automotive, Industrial Technology: Flash Memory, Non-Volatile, 3D NAND, CMOS |
| Companies Covered | Nanya Technology Corporation, Infineon Technologies, Samsung Electronics Co. Ltd, Transcend Information, Kingston Technology, Micron Technology Inc., Winbond Electronics Corporation, ATP Electronics, SK Hynix Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dynamic Random Access Memory (DRAM) Market Trends and Innovations
Memory architecture is bifurcating between bandwidth-optimized AI accelerators and power-constrained industrial controllers, with packaging density and thermal management emerging as the decisive competitive vectors.
EUV lithography is automating patterning precision for sub-10nm DRAM cells, enabling German automotive suppliers to qualify modules for autonomous driving systems within compressed development windows. The technology is compressing die shrink timelines while elevating capital intensity barriers for second-tier fabricators.
The EU AI Act imposes transparency requirements on high-risk systems embedding DRAM-dependent inference engines, forcing memory suppliers to document supply chain provenance and fabrication emissions. Automotive and healthcare deployments face the steepest compliance burdens, with verification protocols extending procurement cycles by 4-6 months.
Cloud operators in France and Germany are consolidating memory procurement through direct foundry relationships, bypassing traditional distributor channels for high-volume AI server builds. This channel compression is concentrating negotiating leverage among hyperscale buyers while margin pressure propagates upstream to module assemblers serving mid-tier industrial accounts.
Europe Dynamic Random Access Memory (DRAM) Market Segmentation
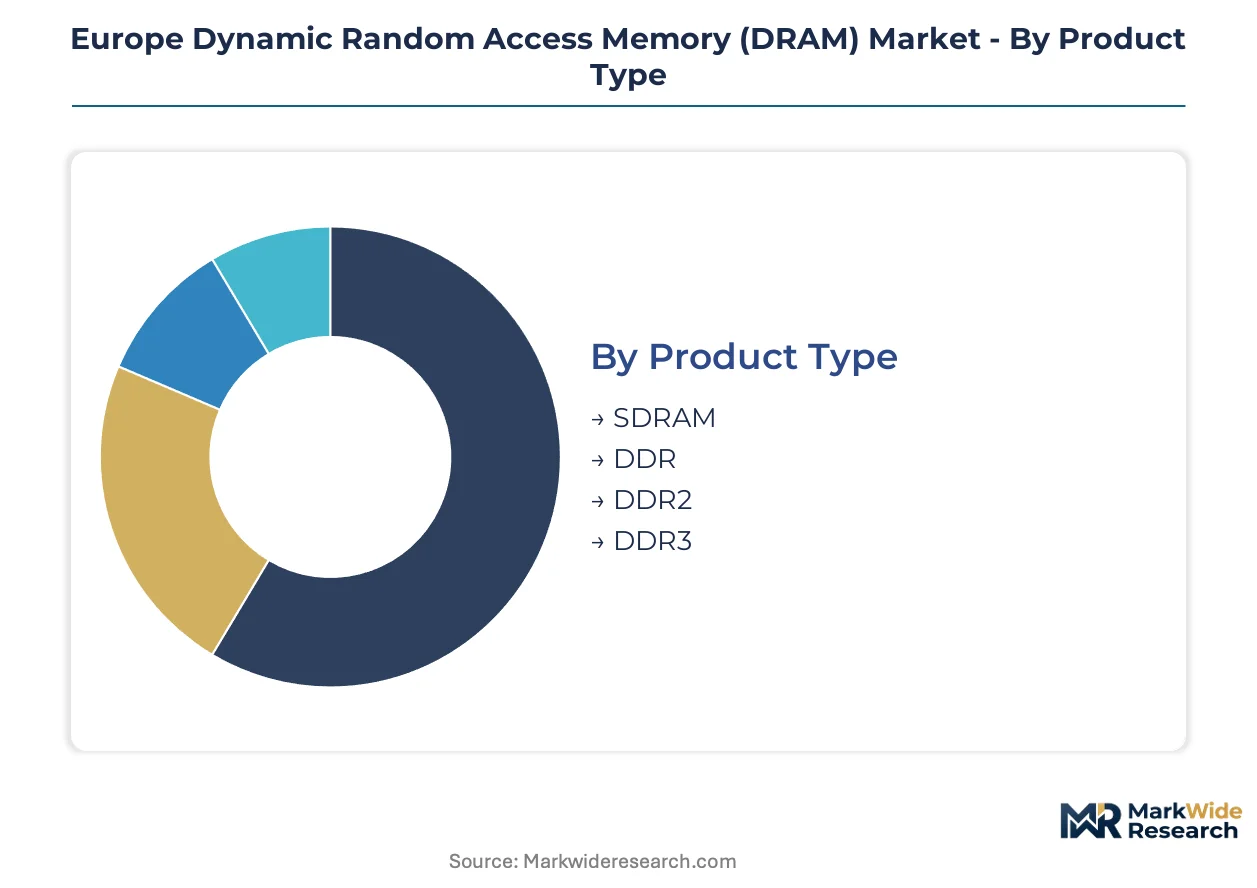
European DRAM procurement splits sharply between standalone memory modules for data center expansion and embedded solutions for automotive qualification programs. Segmentation clarity matters because EU Green Deal carbon-accounting rules apply differentially to discrete versus integrated supply chains.
Product Type:
Integration depth varies dramatically across generations, with newer protocols embedding directly into AI accelerator boards while legacy standards persist in standalone industrial controllers.
- DDR3:Maintains volume dominance across European automation networks where legacy industrial controllers require stable, proven memory architectures. German manufacturing bases continue standardizing on this protocol, compressing upgrade cycles as REACH reformulation mandates force module redesigns regardless of protocol generation.
- DDR:Commands expanding share in French and German AI training servers where bandwidth-per-watt determines rack economics. Cloud campuses are consolidating procurement through direct foundry relationships for high-volume builds, bypassing traditional distributor channels.
- SDRAM:Serves legacy telecommunications infrastructure and medical imaging equipment requiring deterministic latency characteristics.
- DDR2:Persists in specialized railway signaling and extended-temperature industrial applications where qualification costs block migration.
DDR3 leads volumes today; DDR is gaining share fastest.
Application:
Cost tier stratification separates high-volume server deployments from premium-priced embedded qualifications.
- Servers:French and German cloud campuses are scaling memory-intensive training workloads, driving demand for high-bandwidth modules with verified low-emission fabrication footprints under EU Green Deal mandates. Hyperscale buyers concentrate negotiating leverage through direct foundry relationships.
- Embedded Systems:Concentrates margin pools where extended-temperature modules serve railway signaling and medical imaging. ATP Electronics and Winbond Electronics Corporation specialize in this segment, with qualification cycles spanning 18-24 months.
- Computers:Faces margin compression as consumer demand concentrates in entry-level configurations.
- Mobile Devices:European-bound shipments declining as assembly shifts to other regions.
Servers lead volumes today; Embedded Systems is expanding most quickly.
End User:
Customer type determines procurement channel structure, with automotive and data center buyers operating entirely separate qualification ecosystems.
- Data Centers:French and German operators source DRAM with verified low-emission fabrication footprints, decoupling procurement from carbon-intensive supply chains under EU Green Deal carbon-accounting mandates. Direct foundry relationships are consolidating memory procurement for AI server builds.
- Automotive:German OEM qualification programs for autonomous systems pull industrial-grade memory through captive back-end facilities in Dresden and Villach. EU AI Act transparency requirements extend procurement cycles by 4-6 months for high-risk inference engines.
- Industrial:Automation networks maintain volume dominance of older DDR3 protocols, compressing upgrade cycles.
- Consumer Electronics:Price-sensitive demand with limited European manufacturing presence.
Data Centers lead volumes today; Automotive is climbing the fastest.
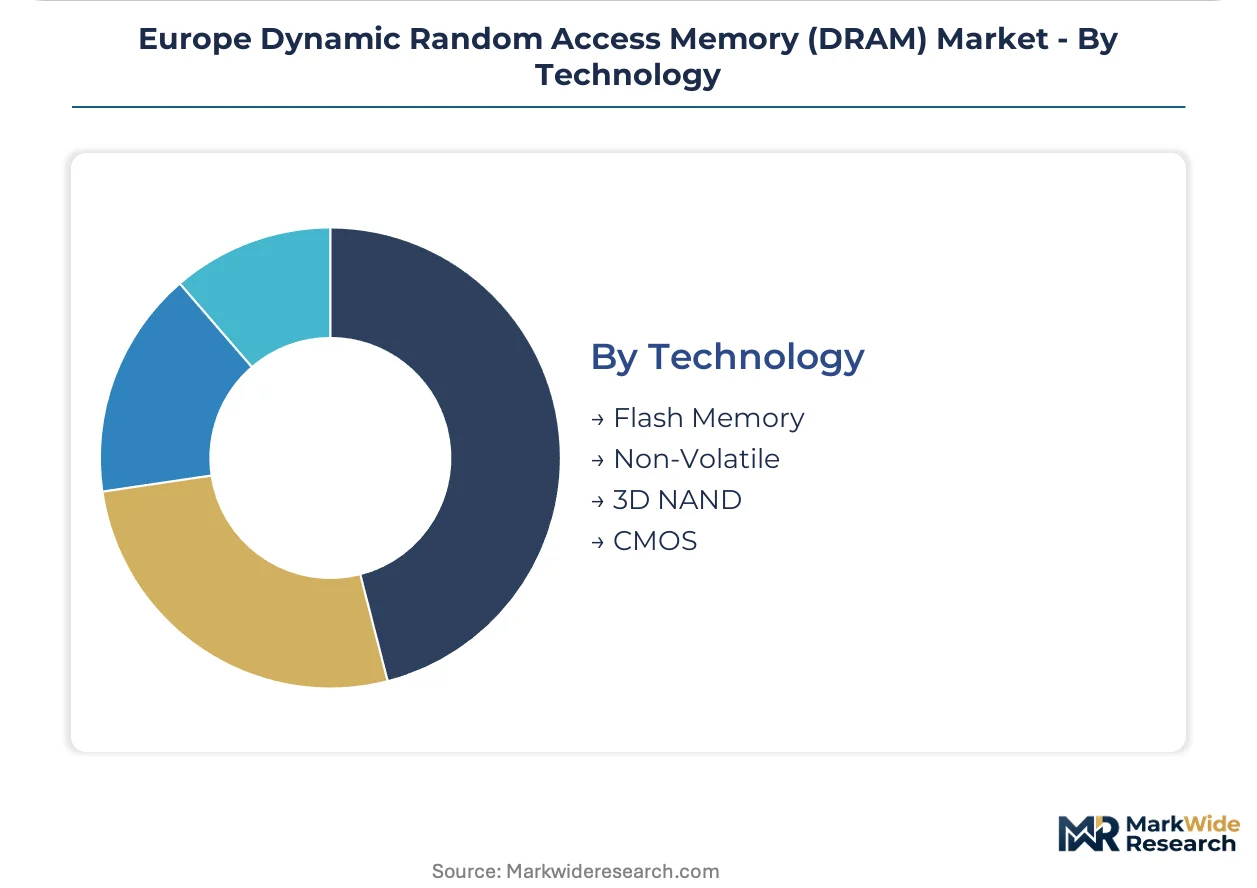
Technology:
Maturity curves separate established CMOS fabrication from emerging non-volatile architectures competing for embedded applications.
- CMOS:Underpins all mainstream DRAM production, with EUV lithography automating patterning precision for sub-10nm cells at Dresden and Leuven facilities. EUV equipment concentration on single-source suppliers creates capacity bottlenecks for advanced node migration.
- 3D NAND:Enables advanced packaging density for AI accelerator boards bound for French cloud campuses, leveraging Netherlands lithography cluster proximity.
- Flash Memory:Competes for embedded storage applications in automotive edge computing.
- Non-Volatile:Emerging architectures targeting power-constrained industrial controllers with zero-refresh requirements.
CMOS leads volumes today; 3D NAND is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DRAM manufacturing in Europe traces its industrial lineage to German precision engineering traditions and Dutch lithography expertise, with contemporary production clustering around advanced fabrication corridors in the continent's northwestern manufacturing belt.
Germany
Automotive OEMs in Stuttgart and Munich are scaling memory-intensive autonomous driving qualification programs. The EU AI Act imposes transparency mandates on high-risk inference engines, extending procurement cycles for German suppliers. Dresden anchors captive back-end fabrication through industrial-grade memory facilities serving Villach-linked automotive networks.
Netherlands
French cloud campuses are sourcing advanced packaging density for AI accelerator boards through ASML ecosystem proximity. REACH substance restrictions force reformulation of lead-based interconnects across Dutch-bound shipments. Eindhoven lithography clusters enable sub-10nm patterning precision for bandwidth-optimized server modules.
France
Hyperscale data center operators in Île-de-France are consolidating memory procurement through direct foundry relationships for AI training workloads. The EU Green Deal carbon-accounting mandates compel verified low-emission fabrication footprints for Paris-region cloud expansions. Grenoble semiconductor research corridors feed qualification protocols for automotive-edge computing deployments.
Austria
Villach industrial-grade memory facilities anchor captive supply for German automotive qualification programs. F-Gas Regulation phase-down schedules are extending equipment amortization timelines at thermal management test facilities. Graz automation networks maintain DDR3 protocol dominance in legacy manufacturing controllers.
Belgium
Leuven EUV lithography facilities face technician scarcity constraints on fab utilization rates. ECHA substance-of-very-high-concern listings add compliance layers to etching chemistry supply chains. Antwerp logistics corridors channel packaged modules toward French cloud campus destinations.
Europe Dynamic Random Access Memory (DRAM) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automotive qualification and data center certification tiers. The vendor base separates into three strategic archetypes: EUV lithography leaders, captive back-end industrial specialists, and advanced packaging density competitors. Consolidation pressures concentrate around direct foundry relationships with hyperscale buyers. Dominant competitive moves include strategic partnerships for carbon-accounting compliance and capacity expansion near Netherlands lithography clusters.
Among Asia-Pacific-based fabricators, Samsung Electronics Co. Ltd and SK Hynix Inc. occupy positions shaped by EUV equipment access and bandwidth-optimized module development. Nanya Technology Corporation represents the specialist tier focused on legacy protocol continuity. Micron Technology Inc. and Infineon Technologies exemplify divergent archetypes: the former sits within advanced packaging density competition for AI accelerators, while the latter anchors captive industrial-grade supply through European back-end integration. Kingston Technology and Transcend Information occupy module assembly tiers where margin pressure propagates from upstream consolidation.
| Leading Market Players |
|---|
| Nanya Technology Corporation |
| Infineon Technologies |
| Samsung Electronics Co. Ltd |
| Transcend Information |
| Kingston Technology |
| Micron Technology Inc. |
| Winbond Electronics Corporation |
| ATP Electronics |
| SK Hynix Inc. |
| Others |
Pricing and Supply Chain Analysis
EUV lithography equipment depreciation feeds directly into module cost structures, with ASML tool amortization driving premium-tier pricing for sub-10nm DRAM bound for French cloud campuses while legacy DDR3 modules face cost compression from REACH-mandated interconnect reformulation.
Pricing Analysis
Contract-based long-term offtake dominates procurement between hyperscale data center operators and foundry partners, with price differentiation anchored in certification grade for automotive qualification programs and volume scale for AI server builds. EU Green Deal carbon-accounting premiums widen spreads between verified low-emission fabrication footprints and standard supply chains. Cost compression in industrial-grade segments intensifies because captive back-end facilities at Dresden and Villach propagate fixed-cost absorption advantages. Automotive OEMs exhibit lowest price sensitivity due to 18-24 month qualification lock-ins, while mid-tier industrial accounts face acute margin pressure from distributor channel compression.
Supply Chain Analysis
Single-source vulnerability sits with ASML for EUV lithography tools, constraining advanced node migration timelines at Dresden and Leuven facilities. Front-end fabrication concentrates in South Korea, Taiwan, and the United States, while European-bound modules draw from etching chemistry supply chains serving Belgian and German fabs. Raw material dependencies span silicon wafers, high-purity gases, and lead-free solder interconnects. Tariff exposure on Chinese-packaged components elevates risk for module assemblers serving mid-tier industrial accounts. Distribution runs through direct foundry relationships for hyperscale buyers and specialized distributors for embedded systems qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in European DRAM hinge on EU AI Act certification premiums for high-risk inference engines and carbon-accounting compliance cost-downs for Green Deal-aligned data center operators.
For Market Incumbents: Anticipate channel compression pressure from hyperscale direct procurement by deepening captive back-end integration at Villach and Dresden facilities. Counter emerging packaging density competitors through accelerated EUV node migration and automotive qualification program pre-emption. Certification investment in EU AI Act transparency protocols represents the critical defensive lever against margin erosion in healthcare and autonomous driving segments.
For New Entrants and Emerging Players: The 40-60% price-point gap between automotive-grade extended-temperature modules and commodity server DRAM opens white-space targeting for railway signaling modernization programs across German and Austrian networks. France's Île-de-France cloud expansion offers penetrable geography for bandwidth-optimized module specialists lacking incumbent foundry relationships. A go-to-market angle through carbon-accounting verification services for Green Deal-compliant procurement addresses unmet buyer need.
For Investors and Strategic Acquirers: Consolidation pressure builds where EUV equipment access scarcity and automotive qualification timeline barriers strand sub-scale module assemblers. Long-term viability favors vertically integrated players with captive back-end facilities and ASML ecosystem proximity. Acquisition target archetypes include industrial-grade memory specialists with extended-temperature certification portfolios. The signal to watch is F-Gas Regulation phase-down acceleration at thermal management test facilities, which would compress equipment amortization timelines and force distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| EUV Node Migration Investment | Sub-10nm patterning precision sustains premium positioning in German automotive qualification programs. |
| Carbon-Accounting Verification Program | Verified low-emission fabrication footprints unlock EU Green Deal-compliant data center procurement. |
| Captive Back-End Facility Expansion | Dresden and Villach integration secures industrial-grade memory supply for autonomous systems. |
| Extended-Temperature Module Certification | Railway signaling and medical imaging qualifications concentrate margin pools in embedded systems. |
| Direct Foundry Relationship Formation | Hyperscale buyer channel compression bypasses traditional distributor economics. |
Research Methodology
Direct dialogue with foundry operations executives, data center procurement officers, automotive Tier 1 supplier quality engineers, and EU regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from ECHA substance restriction filings, EU AI Act implementation guidance, ASML equipment delivery disclosures, and SEC filings of publicly traded memory suppliers. Bottom-up triangulation across module shipment data and top-down reconciliation against cloud infrastructure capex trajectories anchored volume estimates.
Segment-level projections across the analysis window integrated product type splits between DDR3 legacy protocols and DDR bandwidth-optimized architectures, application tiers separating server volumes from embedded systems margins, and technology distinctions between CMOS mainstream and 3D NAND packaging density alternatives. CAGRs derived from elasticity-adjusted demand curves for AI training workloads and automotive edge computing penetration. Forecast inputs incorporated EU Green Deal carbon-accounting mandate compliance timelines and F-Gas Regulation phase-down schedules affecting test facility capacity.
Caveats apply where EUV equipment delivery delays, REACH substance restriction expansion, or EU AI Act transparency protocol revisions could materially shift the outlook. Forecasts reflect assumptions about lithography tool availability, automotive qualification cycle stability, and hyperscale cloud expansion commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Static RAM Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
DDR SDRAM Market
Memory Chips
DRAM Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Memory Chip Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Mobile DRAM Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
Japan DRAM Market
Memory Chips
Memory IC Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market