
 High Bandwidth Memory Market | 2026-2036
High Bandwidth Memory Market Size, Share, and Industry Trends Forecast 2026-2036
High Bandwidth Memory Market Outlook
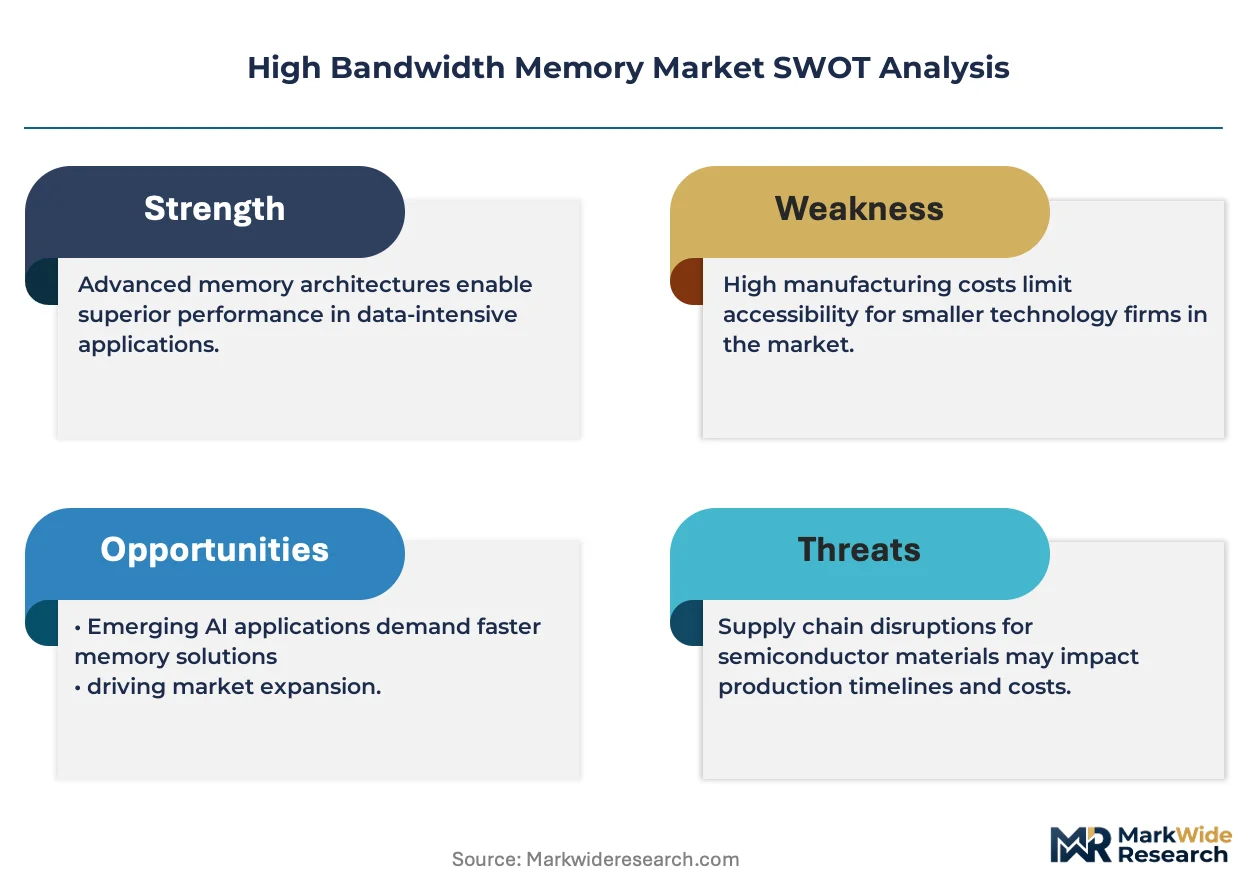
The gap between premium HBM3E stacks and legacy HBM2 modules is restructuring procurement economics for AI accelerator vendors. SK Hynix dominates the bleeding-edge layer stack with in-house TSV and advanced packaging control. Samsung Electronics leverages its captive DRAM capacity to sustain volume supply across both training and inference tiers. Micron Technology differentiates through aggressive yield engineering on 1-beta process nodes.
High Bandwidth Memory refers to 3D-stacked DRAM dies interconnected through through-silicon vias (TSVs) on an interposer substrate, delivering bandwidth exceeding 1 TB/s per stack for processor-attached memory pools. HBM3 and HBM3E product types command the dominant margin pools as NVIDIA and AMD accelerator cards standardize on 12-high and future 16-high configurations. Data center end users absorb the majority of volume, while graphics and gaming applications occupy a mature, price-sensitive niche with slower refresh cycles.
US Commerce Department export controls, South Korean Ministry of Trade industrial policy, and EU REACH chemical compliance frameworks collectively shape wafer sourcing, packaging location decisions, and material substitution pathways. The US CHIPS Act funding conditions require domestic advanced packaging capacity expansion, redirecting some HBM interposer fabrication toward Arizona and Texas greenfield sites. Stakeholders must monitor which regulatory jurisdiction ultimately governs the HBM-to-GPU bond assembly step, as this determines tariff exposure and licensing requirements for China-bound shipments.
Market Dynamics
Layer stack escalation from 8-high to 12-high and 16-high configurations is compressing refresh cycles and concentrating procurement power among AI accelerator vendors with sufficient volume commitments.
Growth Catalysts
- US CHIPS Act funding conditions:Domestic advanced packaging capacity expansion in Arizona and Texas is redirecting interposer fabrication, creating localized supply corridors for GPU-HBM bond assembly.
- Data center AI training clusters:Hyperscale operators are standardizing on HBM3E for next-generation accelerator deployments, pulling forward volume commitments.
- Through-silicon via yield improvements:Advanced TSV formation techniques are reducing stack defect rates and enabling thicker die configurations without proportional cost increases.
Market Restraints
- DRAM wafer supply concentration:Front-end capacity for 1-alpha and 1-beta process nodes concentrates in South Korean and Taiwanese fabs, creating single-source exposure for stack suppliers.
- Advanced packaging equipment lead times:Thermocompression bonders and hybrid bonding tools face 18-24 month delivery windows from Japanese and Dutch equipment vendors.
- EU REACH chemical compliance:Restrictions on specific etching chemistries and underfill materials are forcing material qualification cycles that extend product development timelines.
Strategic Opportunities
- India's semiconductor PLI scheme:Assembly and test capacity expansion under production-linked incentives creates a secondary packaging location outside East Asian concentration zones.
- Inference-optimized 8-high stacks:Lower-power HBM3 configurations for edge data centers represent underserved demand between premium training accelerators and legacy GDDR solutions.
- Hybrid bonding technology convergence:Copper-to-copper direct bond interfaces combined with existing microbump architectures enable heterogeneous integration paths for custom AI silicon.
Industry Challenges
- Advanced packaging process engineering talent:The shortage of specialists in hybrid bonding, wafer-level underfill, and thermal management is constraining yield ramp rates at new facilities.
- Interposer-to-GPU bond certification timelines:Reliability qualification for thermal cycling and electromigration under JEDEC standards extends product validation by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Bandwidth Memory Market |
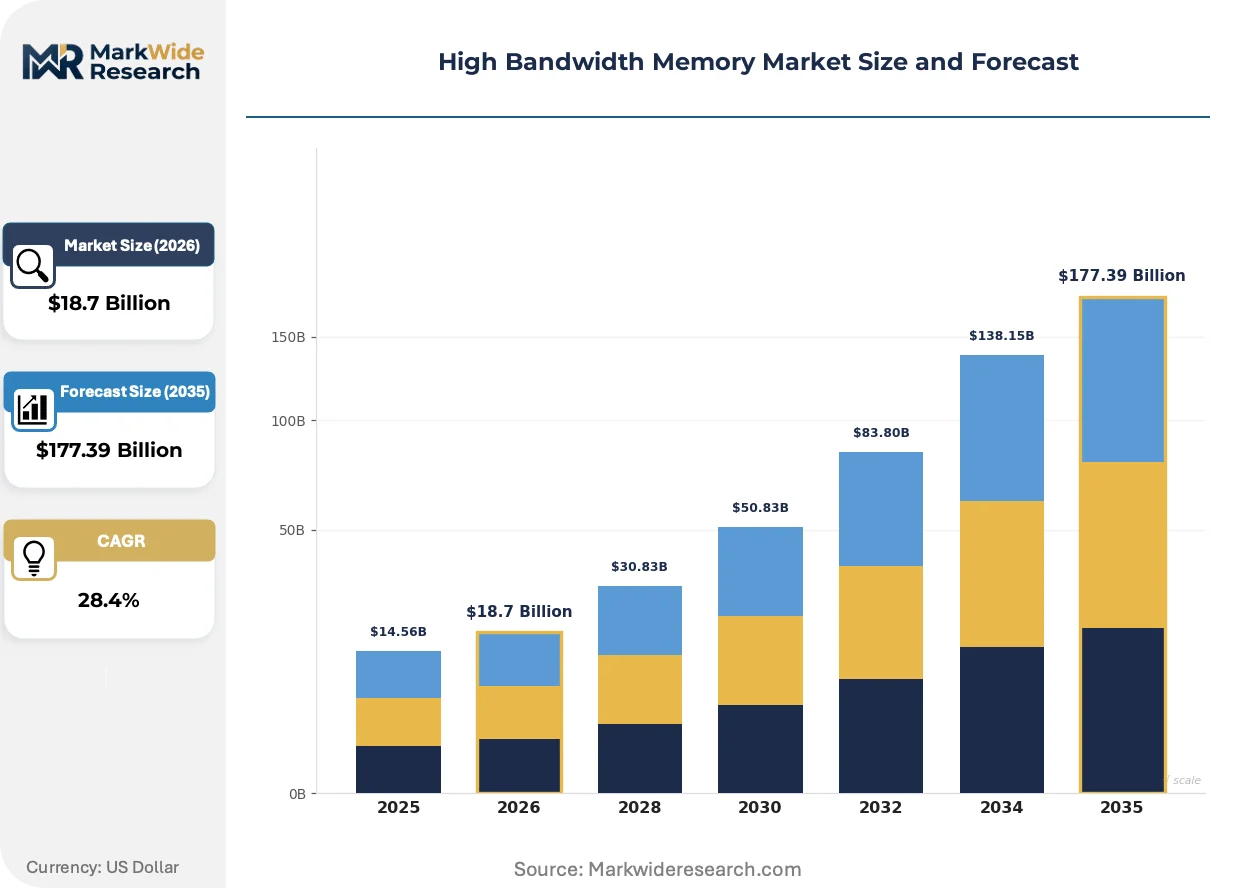
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HBM2, HBM2E, HBM3, HBM3E End User: Data Centers, AI & Machine Learning, Graphics & Gaming, High-Performance Computing Technology: 3D Stacking, TSV, Interposer, DDR Compatibility Application: GPU, FPGA, ASIC, Network Processing |
| Companies Covered | Samsung Electronics Co., Ltd., SK Hynix Inc., Micron Technology, Inc., Intel Corporation, Advanced Micro Devices, Inc., NVIDIA Corporation, Broadcom Inc., Fujitsu Limited, Taiwan Semiconductor Manufacturing Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Bandwidth Memory Market Strategic Shifts
Memory-processor integration depth is accelerating as bandwidth walls force architectural redesigns. Three converging developments are restructuring how HBM stacks are designed, qualified, and deployed.
Hybrid bonding with sub-10 micron pitch is automating the transition from microbump-based stack assembly to direct copper-to-copper interfaces. SK Hynix and Samsung Electronics are qualifying this process for 16-high configurations. The technology is automating the elimination of underfill layers and reducing stack z-height, enabling denser accelerator card layouts.
The EU AI Act risk classification framework is imposing documentation and traceability requirements on high-performance computing components deployed in critical infrastructure applications. Memory suppliers must now maintain batch-level material records and failure mode databases. Data center operators in Germany and France are demanding enhanced supply chain transparency as a procurement precondition.
Accelerator vendors are consolidating memory procurement under direct long-term supply agreements rather than distributor-mediated spot purchasing. NVIDIA and AMD are negotiating 24-36 month volume commitments with binding layer-stack specifications. This pattern is most visible in North American hyperscale deployments, where guaranteed HBM3E allocation has become a competitive differentiator in cloud AI service pricing.
High Bandwidth Memory Market Segmentation
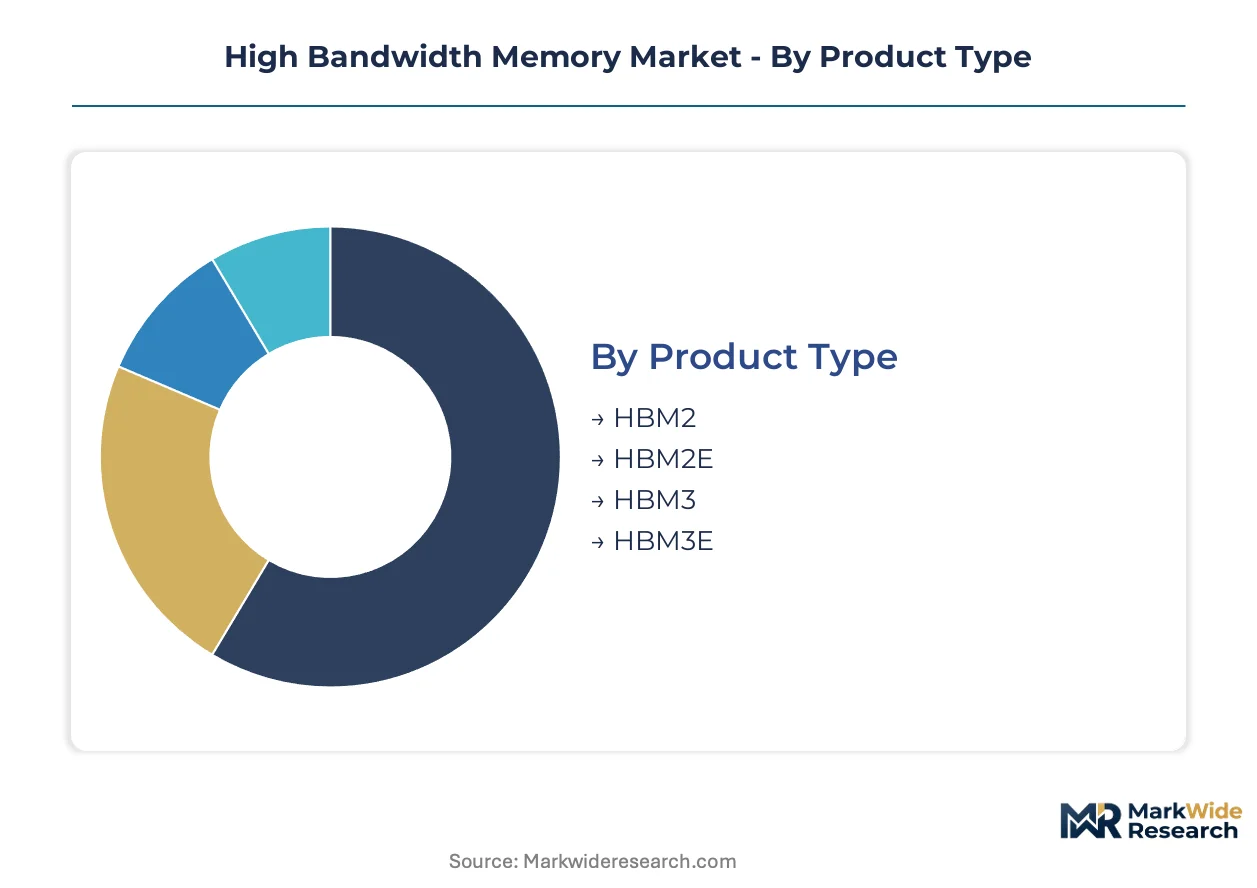
HBM procurement patterns diverge sharply between AI training clusters demanding bleeding-edge bandwidth and inference deployments optimizing for power efficiency. Understanding these segment boundaries clarifies where technology premiums command sustainable margins versus commodity pricing pressure.
Product Type:
Standardization dominates at the interface level through JEDEC specifications, yet customization proliferates in layer-stack height and thermal design power configurations tailored to accelerator card form factors.
- HBM3E:12-high and emerging 16-high die stacks deliver bandwidth exceeding 1.2 TB/s through advanced TSV interconnects. Data center AI training clusters in South Korea and the United States absorb the majority of volume as NVIDIA H100 and AMD MI300 series accelerators standardize on this tier, though supply constraints limit allocation to hyperscale operators with direct supplier relationships.
- HBM3:8-high configurations balance bandwidth density against thermal envelope for inference-optimized accelerators. Cloud service providers in Germany and France are deploying these stacks for medium-scale model serving where per-watt performance outweighs absolute throughput requirements.
- HBM2E:Mature 8-high stacks serve legacy GPU refresh cycles and cost-sensitive HPC installations.
- HBM2:End-of-life products sustain graphics card aftermarket supply and industrial visualization systems with minimal refresh requirements.
Leading the category by volume: HBM3E. Expanding most quickly: HBM3E 16-high configurations.
End User:
Volume concentration follows capital deployment cycles in hyperscale infrastructure, with procurement power consolidating among operators commanding multi-billion-dollar accelerator commitments.
- Data Centers:Hyperscale operators deploy HBM3E stacks in training clusters exceeding 10,000 GPU equivalents. Microsoft, Amazon Web Services, and Google Cloud negotiate direct allocation agreements with SK Hynix and Samsung Electronics, bypassing distributor channels to secure 24-36 month supply visibility.
- AI & Machine Learning:Specialized research institutions and national laboratories consume high-margin custom stacks for scientific computing workloads. Lawrence Livermore National Laboratory and Forschungszentrum Jülich represent concentrated demand nodes with bespoke thermal and reliability specifications.
- Graphics & Gaming:Consumer GPU vendors face margin compression as GDDR6X alternatives satisfy mainstream bandwidth requirements.
- High-Performance Computing:Weather modeling and molecular simulation facilities sustain demand for HBM2E and early HBM3 generations.
Dominating procurement scale: Data Centers. Steepest expansion trajectory: AI & Machine Learning specialized deployments.
Technology:
Process maturity varies dramatically across the integration stack, with front-end DRAM fabrication achieving yield stability while advanced packaging remains capacity-constrained.
- TSV:Through-silicon via formation at sub-10 micron pitch enables vertical die interconnects with signal integrity matching traditional wirebond alternatives. Yield engineering at this node concentrates in South Korean fabs where Samsung Electronics and SK Hynix have accumulated proprietary etch and fill process knowledge.
- 3D Stacking:Thermocompression bonding of thinned wafers creates the physical architecture enabling bandwidth density. Japanese equipment vendors including Tokyo Electron and Hitachi High-Tech control critical bonder supply with 18-24 month delivery backlogs constraining capacity expansion timelines.
- Interposer:Silicon bridge substrates route signals between HBM stacks and host processors.
- DDR Compatibility:Interface standardization enables modular procurement across supplier bases.
Widest deployment base: TSV. Gaining share fastest: 3D Stacking with hybrid bonding migration.
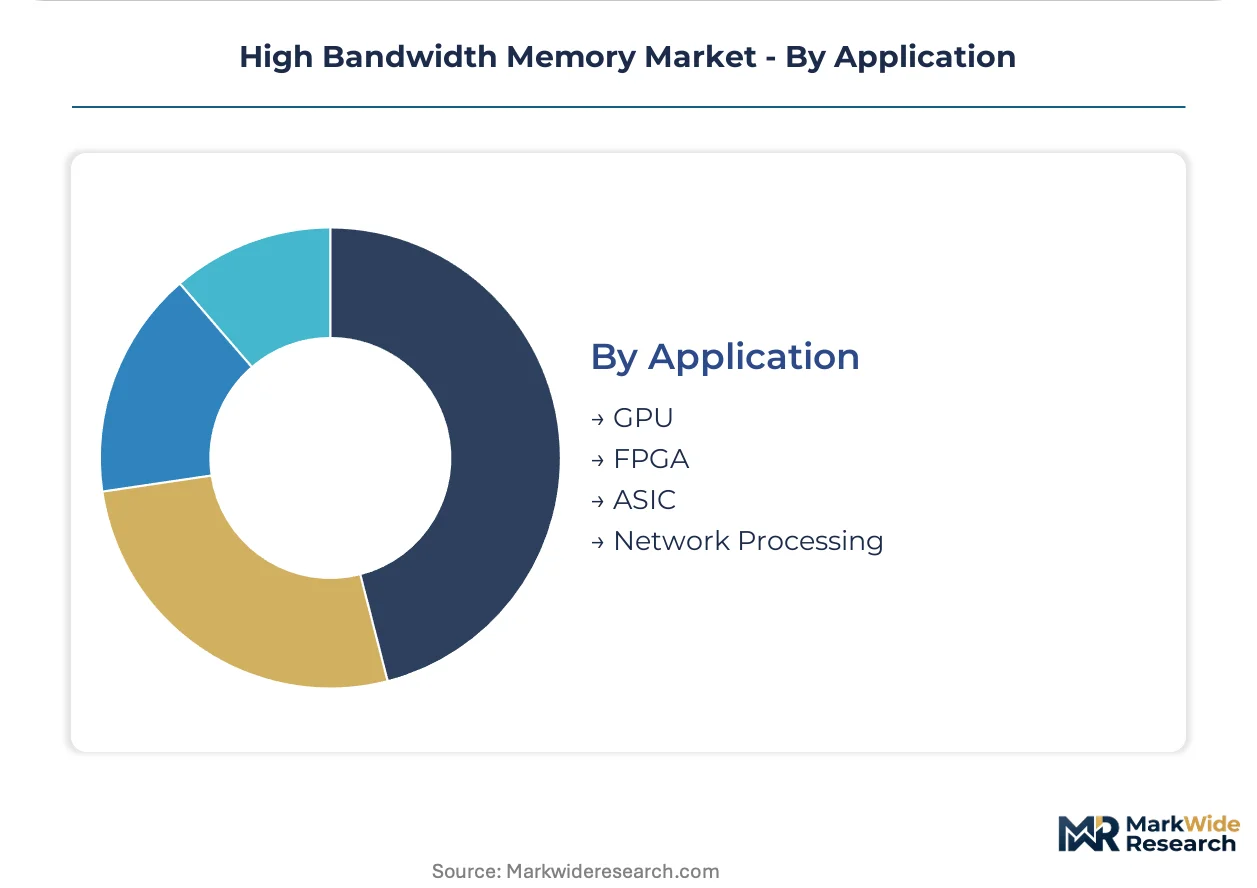
Application:
Host processor architecture dictates stack configuration requirements, with discrete accelerators driving highest layer counts and integrated solutions optimizing for z-height constraints.
- GPU:Discrete graphics processing units from NVIDIA and AMD consume the dominant HBM volume, with H100, MI300X, and successor architectures standardizing on 12-high HBM3E as baseline configuration. Thermal design power budgets exceeding 700W necessitate advanced packaging with liquid cooling integration.
- ASIC:Custom AI accelerators from Google TPU, Amazon Trainium, and Microsoft Maia 100 adopt HBM for on-chip memory bandwidth. These designs optimize stack count and placement for specific model architectures, creating fragmented demand patterns compared to GPU standardization.
- FPGA:Adaptive computing platforms from Xilinx and Intel serve network infrastructure and financial acceleration with moderate bandwidth requirements.
- Network Processing:SmartNICs and data processing units deploy HBM2E for packet buffer applications.
Commanding maximum stack volume: GPU. Climbing the fastest: ASIC custom accelerator deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the global HBM production ecosystem, with the Seoul Capital Area housing Samsung Electronics and SK Hynix headquarters alongside their primary advanced packaging facilities. This concentration shapes supply chain decisions for AI accelerator vendors worldwide.
South Korea
SK Hynix and Samsung Electronics command bleeding-edge HBM3E volume through captive TSV and interposer capacity. The Ministry of Trade, Industry and Energy coordinates industrial policy under the K-Semiconductor Belt initiative. Pyeongtaek and Icheon host the dominant DRAM wafer fabs feeding stack assembly lines.
United States
Hyperscale data center operators in Virginia and Oregon drive HBM3E procurement through direct allocation agreements with Korean suppliers. The CHIPS Act conditions require domestic advanced packaging expansion, redirecting some interposer fabrication toward Arizona greenfield sites. Phoenix and Austin emerge as competing locations for GPU-HBM bond assembly capacity.
China
Domestic AI accelerator vendors face sourcing constraints under US Commerce Department export controls on advanced semiconductors. The MIIT coordinates substitution efforts through national integrated circuit investment funds. Shanghai and Beijing clusters concentrate design activity while advanced packaging remains import-dependent.
Japan
Thermocompression bonder and hybrid bonding equipment vendors face 18-24 month order backlogs from Korean and US packaging facilities. METI coordinates supply chain resilience initiatives under the Economic Security Promotion Act. Tokyo and Osaka house the precision equipment manufacturers constraining global HBM capacity expansion.
Germany
Data center operators in Frankfurt and Berlin demand enhanced supply chain transparency under EU AI Act risk classification frameworks. The KBA and federal economic ministry coordinate critical infrastructure protection standards. Bavaria hosts specialized research institutions consuming custom HBM configurations for scientific computing workloads.
High Bandwidth Memory Market Competitive Environment
Premium-margin players sit above commodity-margin players across layer-stack complexity and thermal design power specifications. The vendor base concentrates around three Korean and US memory fabricators controlling TSV yield and advanced packaging capacity. Two strategic archetypes dominate: captive DRAM suppliers with in-house stack integration, and fabless AI accelerator vendors securing long-term allocation agreements. Capacity expansion and direct supply agreement negotiation represent the dominant competitive moves as procurement power consolidates among hyperscale operators.
Among Korean-based fabricators, Samsung Electronics Co., Ltd. and SK Hynix Inc. occupy positions within the premium-tier memory supply chain, exemplifying the captive DRAM-to-stack integration archetype. Micron Technology, Inc. represents the US-based yield-engineering alternative, anchoring the non-Korean sourcing option for accelerator vendors diversifying supply exposure. These three entities sit within a structure where direct long-term agreements have displaced spot market procurement for bleeding-edge configurations.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| SK Hynix Inc. |
| Micron Technology, Inc. |
| Intel Corporation |
| Advanced Micro Devices, Inc. |
| NVIDIA Corporation |
| Broadcom Inc. |
| Fujitsu Limited |
| Taiwan Semiconductor Manufacturing Company Limited |
| Others |
Value Chain & Pricing Dynamics
TSV etch chemistry costs cascade through HBM stack fabrication, with South Korean wafer processing premiums translating into three-tier pricing separation across training-optimized 16-high, inference-balanced 12-high, and legacy 8-high configurations. Accelerator vendors absorb these input cost structures through direct long-term offtake agreements that lock layer-stack specifications 24-36 months forward.
Pricing Analysis
Throughput-per-watt benchmarks anchor value-based pricing for HBM3E stacks, with hyperscale operators paying premiums for guaranteed allocation over spot-market sourcing. Price differentiation separates JEDEC-qualified 12-high configurations from custom thermal-specification stacks for national laboratory deployments. Cost compression in legacy HBM2E tiers intensifies as GDDR6X alternatives capture mid-range inference workloads. Cloud service providers exhibit highest price sensitivity, while AI training cluster operators prioritize supply certainty over unit economics.
Supply Chain Analysis
JEDEC reliability qualification and US Commerce Department export licensing create dual gating mechanisms that filter supplier participation. Front-end DRAM fabrication concentrates in South Korea and Taiwan, while advanced packaging capacity expands in Arizona and Texas under CHIPS Act conditions. The supply chain draws from silicon wafer feedstock, fluorinated etching chemistries, and thermocompression bonding equipment. Single-source vulnerability concentrates in Japanese precision equipment vendors facing 18-24 month delivery backlogs. Distribution runs through direct allocation agreements rather than distributor-mediated spot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive TSV yield control and in-house advanced packaging capacity determine margin capture. Players are pursuing backward integration into DRAM wafer fabrication to secure stack supply.
For Market Incumbents: Extend interposer fabrication footprints into Arizona and Texas greenfield sites to satisfy CHIPS Act domestic content requirements. Deepen TSV yield engineering investments at Pyeongtaek and Icheon facilities to maintain stack defect rate advantages against emerging packaging competitors. SK Hynix and Samsung Electronics must defend against Micron's 1-beta process node yield improvements by accelerating 16-high hybrid bonding qualification timelines. For New Entrants and Emerging Players: Hybrid bonding equipment specialization represents a technology-first wedge for precision automation vendors seeking entry. Target inference-optimized 8-high HBM3 configurations for edge data center deployments where NVIDIA and AMD standardization has not yet locked procurement patterns. A go-to-market angle through India's PLI scheme assembly and test capacity creates geographic differentiation outside East Asian supply concentration. For Investors and Strategic Acquirers: Binding 24-36 month volume commitments from Microsoft, Amazon Web Services, or Google Cloud is the leading indicator that a stack supplier has secured viable long-term revenue visibility. Over a multi-year horizon, vertically integrated memory fabricators with captive DRAM-to-stack control will outcompete fabless packaging houses dependent on wafer spot markets. Acquisition targets should display proprietary TSV etch-and-fill process knowledge or hybrid bonding equipment relationships with Tokyo Electron and Hitachi High-Tech.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRAM Wafer Fabrication | Captive 1-alpha and 1-beta node supply secures stack input cost control against wafer spot volatility. |
| Hybrid Bonding Technology Qualification | Sub-10 micron pitch copper-to-copper interfaces enable 16-high stack z-height reduction for denser accelerator layouts. |
| Domestic Advanced Packaging Expansion | Arizona and Texas interposer fabrication satisfies US CHIPS Act conditions for GPU-HBM bond assembly localization. |
| Direct Long-Term Supply Agreements | Binding 24-36 month volume commitments with hyperscale operators displace spot procurement for HBM3E allocation certainty. |
| EU REACH Chemical Compliance Investment | Material qualification for etching chemistries and underfill alternatives extends product development timelines but unlocks German and French data center procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced against primary interviews with DRAM process engineers, advanced packaging equipment specialists, hyperscale data center procurement officers, and AI accelerator platform architects. SEC 10-K disclosures from memory fabricators, US Commerce Department export control determinations, and South Korean Ministry of Trade industrial policy documents supplied quantitative foundations. Bottom-up stack volume estimates triangulated against top-down AI accelerator deployment forecasts across the analysis window.
Segment-level granularity modeled product type across HBM3E, HBM3, HBM2E, and HBM2 generations; end user across data center, AI and machine learning, graphics and gaming, and high-performance computing; and application across GPU, ASIC, FPGA, and network processing. CAGRs derived from layer-stack height migration curves and TSV yield improvement trajectories. Forecast inputs incorporated thermocompression bonder delivery backlogs, EU AI Act documentation requirements, and hyperscale capex disclosure patterns for training cluster deployments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under US export control expansion or Japanese equipment supply disruption. Forecasts reflect documented assumptions regarding TSV defect rate improvement curves and hybrid bonding adoption timelines. A model refresh is warranted upon material change in CHIPS Act funding disbursement velocity or EU REACH chemical restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Memory Chip Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
China Flash Memory Market
Memory Chips
Next Generation Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Automotive Memory Market
Memory Chips
ECC Memory Market
Memory Chips
In-Memory Computing Market