
 Static Random-Access Memory (SRAM) Market | 2026-2036
Static Random-Access Memory (SRAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Static Random-Access Memory (SRAM) Market Analytics
FinFET-to-GAAFET transistor architecture migration is reconfiguring SRAM bitcell design rules and foundry qualification timelines. Infineon Technologies leverages its automotive-certified fabs to anchor high-reliability supply contracts. Texas Instruments sustains broad portfolio coverage across industrial and communications segments. Winbond Electronics Corporation specializes in low-power pseudo SRAM for IoT endpoints.
Static Random-Access Memory (SRAM) stores data in cross-coupled inverter latch structures with access transistors, requiring six transistors per bitcell and delivering sub-nanosecond access latencies without refresh cycles. It serves as cache memory, register files, and buffer storage where speed outweighs density or cost constraints. Embedded SRAM dominates total bit volume by residing on logic dies alongside processors and ASICs. Synchronous SRAM retains premium positioning in networking line cards where clocked interfaces match FPGA and ASIC timing domains. Automotive-grade asynchronous SRAM occupies a defensible margin pool under AEC-Q100 qualification requirements.
EU REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging materials, compelling foundries to reformulate underfill and interconnect chemistries. EPA and OSHA standards govern US fab emissions and worker exposure limits during etch and deposition processes. ISO 26262 functional safety mandates shape automotive SRAM verification protocols across Tier 1 module suppliers. Stakeholders must monitor foundry capacity allocation between leading-edge logic and mature-node specialty memory as GAAFET ramp-up strains EUV lithography availability.
Market Dynamics
FinFET-to-GAAFET transistor architecture migration is compressing SRAM bitcell qualification timelines while Taiwan's foundry cluster concentrates advanced logic capacity allocation decisions. This structural tension between process node advancement and specialty memory access defines competitive positioning.
Growth Catalysts
- Automotive ADAS Integration:AEC-Q100 qualification mandates are pulling high-reliability asynchronous SRAM into camera modules and sensor fusion units across Tier 1 suppliers.
- EU F-Gas Regulation:Tightening fluorinated gas restrictions are accelerating fab equipment upgrades that favor SRAM-compatible mature-node processes with lower etch chemistry footprints.
- Networking Line Card Refresh:Synchronous SRAM with clocked interfaces is matching FPGA timing domains in terabit router backplanes.
Market Restraints
- EUV Lithography Bottleneck:GAAFET ramp-up is constraining EUV scanner availability for mature-node SRAM production at leading foundries.
- REACH Compliance Costs:ECHA-mandated underfill reformulation is raising packaging material qualification expenses for automotive-grade devices.
- DRAM Price Compression:Low-power DRAM substitutes are displacing pseudo SRAM in cost-sensitive IoT endpoints where latency tolerance permits.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly are creating captive demand for industrial SRAM in automation controllers.
- ISO 26262 Functional Safety:ASIL-D verification protocols are opening premium pricing tiers for fault-tolerant SRAM in steer-by-wire systems.
- Chiplets and 3D Integration:SRAM-on-logic die disaggregation is hybridizing with advanced packaging to enable cache expansion without monolithic scaling.
Industry Challenges
- GAAFET Bitcell Redesign:Six-transistor cell stability requirements are forcing complete layout rule revisions at 2nm-class nodes.
- Automotive Qualification Timelines:AEC-Q100 Grade 0 temperature cycling protocols extend time-to-revenue for new SRAM designs by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Random-Access Memory (SRAM) Market |
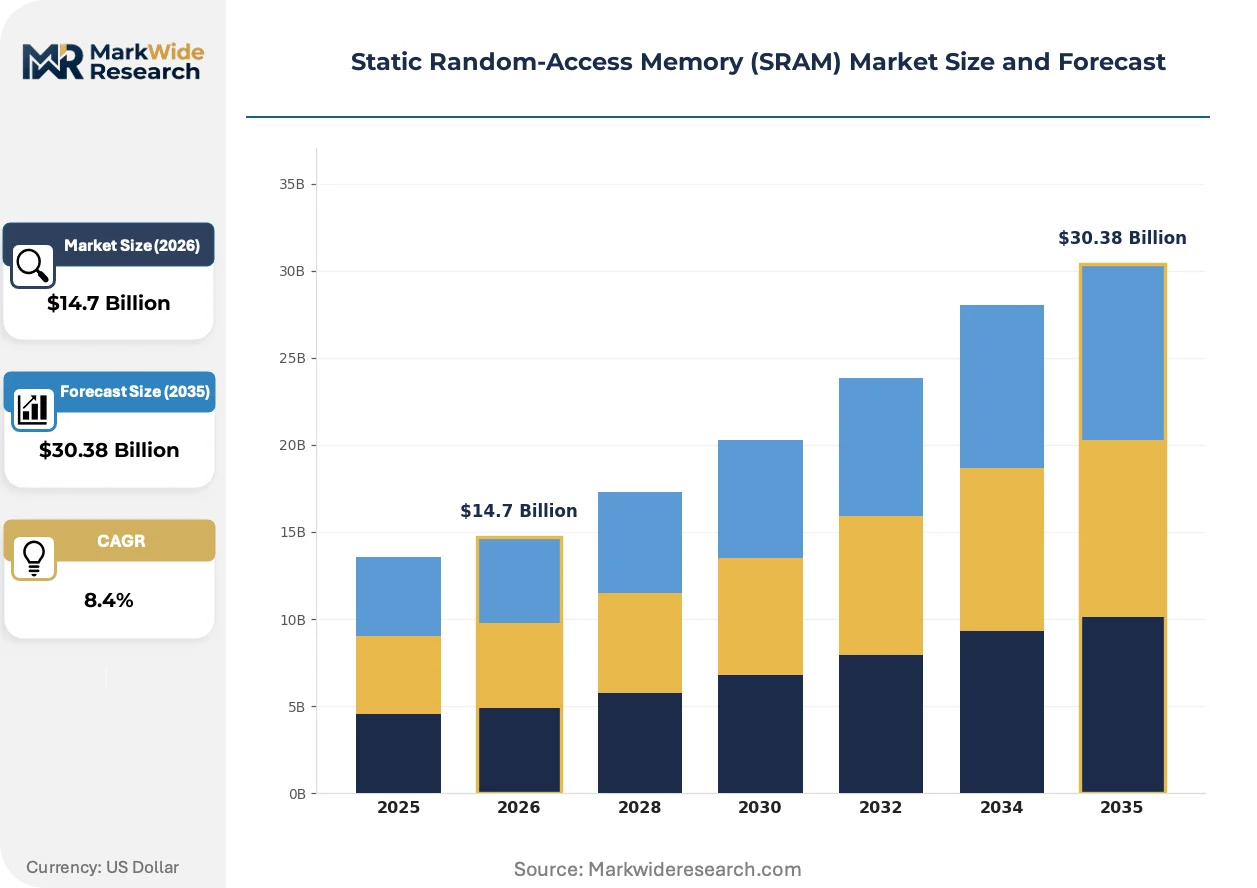
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asynchronous SRAM, Synchronous SRAM, Pseudo SRAM, Embedded SRAM Application: Networking, Computing, Consumer Electronics, Automotive End User: Telecommunications, Data Centers, Healthcare Devices, Industrial Equipment Technology: FPGA, ASIC, SoC, High-Speed Interface |
| Companies Covered | STMicroelectronics NV, Integrated Silicon Solution Inc. (ISSI), Infineon Technologies, Alliance Memory Inc., GSI Technology Inc., Renesas Electronics Corporation, Texas Instruments, Winbond Electronics Corporation, Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Random-Access Memory (SRAM) Market Evolving Landscape
Process-architecture co-optimization is collapsing traditional boundaries between logic and memory design teams. Three developments are reconfiguring how SRAM capabilities are specified, verified, and integrated into system-level solutions.
Gate-all-around transistor structures are hybridizing with backside power delivery networks to reclaim bitcell area lost to increased device count. Foundry customers in high-performance computing are adopting these stacks aggressively. The structural consequence is compressing SRAM macro density targets that previously required full node jumps.
REACH and RoHS frameworks are compelling foundries to eliminate lead-based interconnects and reformulate underfill epoxies. ECHA substance restriction proposals for PFAS are forcing preemptive material qualification programs. Automotive module suppliers in Germany and France are accelerating alternative chemistry validation to avoid supply disruption.
Consolidated procurement by hyperscale data center operators is concentrating SRAM specification power among three to four cloud infrastructure architects. Direct foundry relationships are displacing traditional distribution channels for high-volume cache contracts. This pattern is most visible in US and Chinese server buildouts where custom ASIC programs dominate memory selection criteria.
Static Random-Access Memory (SRAM) Market Segmentation
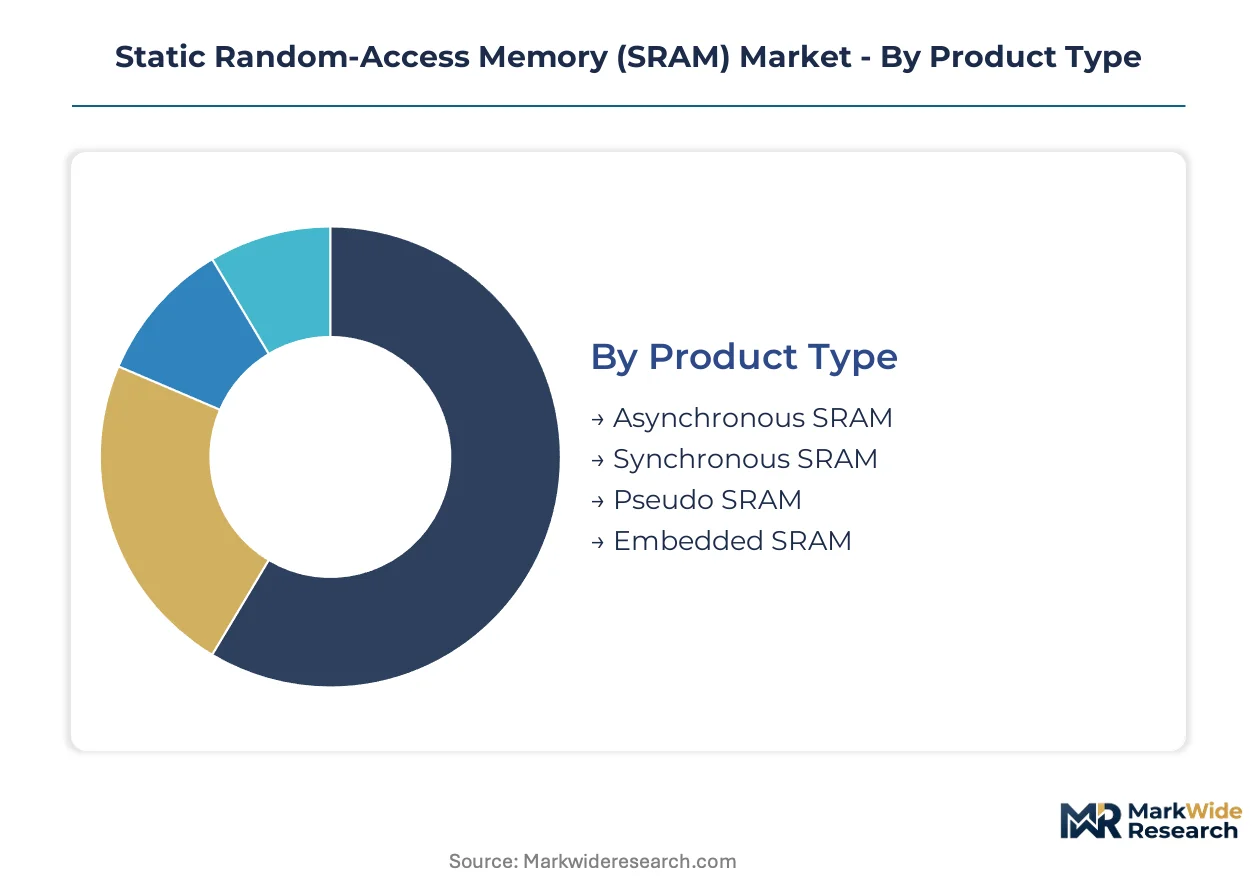
SRAM market segmentation reveals divergent qualification timelines and margin structures across product architectures. Cycle time variations between automotive-grade asynchronous devices and high-volume embedded cache create distinct competitive arenas with incompatible investment profiles.
Product Type:
Refresh cycles span six months for commodity pseudo SRAM to thirty-six months for AEC-Q100 qualified automotive parts, creating tiered inventory risk profiles across the product matrix.
- Embedded SRAM:Six-transistor bitcells integrated directly onto logic dies alongside processors and ASICs, consuming the majority of total bit volume. Taiwan's foundry cluster concentrates production for high-performance computing accelerators where cache density directly determines die economics.
- Asynchronous SRAM:Standalone devices with unclocked interfaces operating across extended temperature ranges. Automotive camera modules and sensor fusion units in Germany and Japan pull Grade 0 qualified devices through extended qualification pipelines.
- Synchronous SRAM:Clocked interfaces match FPGA timing domains in networking equipment. Terabit router backplanes specify these devices for deterministic latency.
- Pseudo SRAM:DRAM-compatible pinouts with SRAM-like refresh-free operation using hidden internal cycles. IoT endpoints in cost-sensitive consumer applications specify these devices where latency tolerance permits.
Embedded SRAM anchors the volume base while Pseudo SRAM gains share at the steepest rate.
Application:
Margin structures stratify sharply between safety-critical automotive systems and commodity consumer electronics, with certification overhead creating irreversible cost tiering.
- Automotive:ADAS camera modules and steer-by-wire systems mandate AEC-Q100 qualification with ISO 26262 functional safety verification. Infineon Technologies and NXP Semiconductors dominate qualification pipelines for Grade 0 temperature cycling.
- Networking:Terabit router line cards and switch fabrics specify synchronous SRAM for deterministic latency matching ASIC timing domains. Hyperscale data center buildouts in the United States and China consolidate procurement specifications.
- Computing:CPU and GPU cache hierarchies rely on embedded SRAM macros with process-node-matched bitcells. GAAFET migration at 2nm-class nodes forces complete layout rule revisions.
- Consumer Electronics:Gaming peripherals and wearable devices drive pseudo SRAM consumption where cost constraints dominate performance requirements.
Computing applications command the highest bit volumes while Automotive applications deliver the steepest margin expansion trajectory.
End User:
Procurement concentration varies from fragmented industrial equipment buyers to consolidated telecommunications operators with captive specification power.
- Telecommunications:5G baseband processing and optical transport systems specify high-reliability synchronous SRAM. Ericsson and Nokia qualification programs lock in multi-year supply agreements.
- Data Centers:Custom ASIC programs at hyperscale operators displace traditional distribution channels. Direct foundry relationships now dominate high-volume cache procurement.
- Industrial Equipment:Programmable logic controllers and motor drives specify industrial-temperature asynchronous devices. India's PLI scheme for electronics manufacturing is expanding captive demand.
- Healthcare Devices:Imaging equipment and patient monitoring systems require extended-temperature operation with long-term supply guarantees.
Telecommunications anchors the volume base while Data Centers climb the fastest in specification influence.
Technology:
Integration depth determines SRAM macro design rules, with standalone devices retaining process flexibility that embedded cache sacrifices for density optimization.
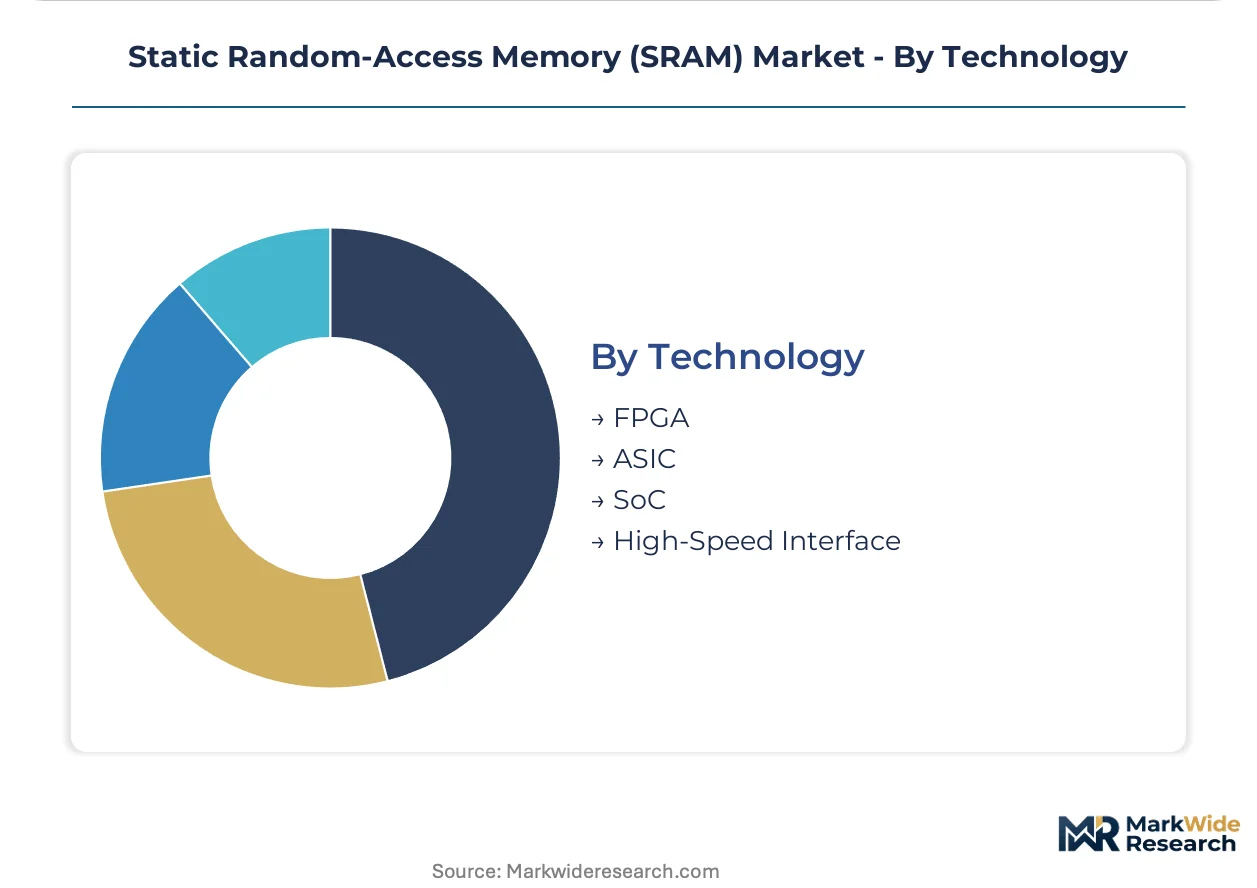
- SoC:System-on-chip integration embeds SRAM alongside processors, accelerators, and I/O subsystems on monolithic dies. Apple and Qualcomm custom programs drive leading-edge bitcell density targets.
- ASIC:Application-specific designs match SRAM macros to precise timing and power constraints. Networking and storage accelerator programs dominate this segment.
- FPGA:Field-programmable gate arrays incorporate distributed SRAM blocks for reconfigurable logic. Xilinx and Intel programmable logic families specify these architectures.
- High-Speed Interface:GDDR and HBM PHY designs integrate SRAM buffers for signal conditioning and data alignment.
SoC integration anchors the volume base while ASIC designs expand most quickly in networking acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports the majority of advanced SRAM bitcells to hyperscale data center operators in the United States and China, while Japan and Germany supply automotive-grade devices to European Tier 1 module suppliers.
United States
Hyperscale cloud infrastructure buildouts in Virginia and Oregon drive cache procurement through direct foundry relationships. EPA emissions standards govern fab construction timelines in Arizona and Texas. Austin anchors Texas Instruments' automotive-qualified production for ADAS camera modules.
Taiwan
The Hsinchu Science Park concentrates EUV lithography capacity for 2nm-class GAAFET SRAM development. Taiwan's foundry cluster allocates wafer starts between leading-edge logic and mature-node specialty memory. TSMC and UMC facilities in Tainan and Taichung throttle embedded SRAM output based on smartphone and AI accelerator demand cycles.
China
Yangtze Memory Technologies and domestic foundries expand pseudo SRAM output for IoT endpoints under MIIT semiconductor self-sufficiency targets. GB standards govern hazardous substance limits in packaging materials. Shanghai and Beijing clusters prioritize 28nm and above processes where equipment sanctions bite less severely.
Germany
Automotive module suppliers in Stuttgart and Munich pull AEC-Q100 Grade 0 SRAM through Infineon Technologies' automotive-certified fabs. EU F-Gas Regulation accelerates etch chemistry transitions in Dresden manufacturing corridors. Bavaria's semiconductor ecosystem specializes in extended-temperature devices for steer-by-wire systems.
Japan
Renesas Electronics and Kioxia anchor synchronous SRAM supply for 5G baseband processing and optical transport. METI semiconductor subsidies support legacy node preservation for industrial-temperature devices. Kyushu and Hiroshima production clusters maintain long-term supply guarantees for healthcare imaging equipment manufacturers.
Static Random-Access Memory (SRAM) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered qualification timelines that separate automotive-grade asynchronous devices from commodity pseudo SRAM. The vendor base stratifies between foundry-integrated memory divisions and fabless design houses. Three archetypes dominate: automotive-certified fabs with AEC-Q100 pipelines, networking-focused synchronous specialists, and low-power IoT endpoint suppliers. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves.
Among European automotive-certified suppliers, STMicroelectronics NV and Infineon Technologies exemplify the high-reliability archetype with extended temperature cycling protocols. Texas Instruments occupies a position spanning industrial and communications segments through broad portfolio coverage. Winbond Electronics Corporation represents the low-power specialization vector for IoT endpoints.
| Leading Market Players |
|---|
| STMicroelectronics NV |
| Integrated Silicon Solution Inc. (ISSI) |
| Infineon Technologies |
| Alliance Memory Inc. |
| GSI Technology Inc. |
| Renesas Electronics Corporation |
| Texas Instruments |
| Winbond Electronics Corporation |
| Microchip Technology Inc. |
| Others |
Value Network & Pricing Analysis
Foundry undercapacity in Taiwan's Hsinchu Science Park is compressing wafer allocation timelines for automotive-grade asynchronous SRAM while simultaneously hardening pricing postures among AEC-Q100 qualified suppliers. This utilization squeeze transmits directly into extended lead-time premiums and selective customer prioritization across Tier 1 module procurement desks.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate automotive-grade SRAM procurement, insulating Infineon Technologies and NXP Semiconductors from spot volatility while embedding pass-through clauses for EU F-Gas Regulation compliance costs. Price differentiation rests on AEC-Q100 certification tier and volume scale, with Grade 0 qualified devices commanding substantial premiums over industrial-temperature equivalents. Cost compression in pseudo SRAM is intensifying because low-power DRAM substitutes are eroding latency-tolerant IoT endpoints. Hyperscale data center operators exhibit the lowest price sensitivity due to direct foundry relationships, while Indian industrial automation buyers under PLI scheme incentives remain most price-sensitive.
Supply Chain Analysis
Upstream silicon wafer and EUV photoresist feedstocks draw from Japan's Shin-Etsu and JSR manufacturing clusters, with specialty gas supplies anchored in Germany's Linde and Air Liquide facilities. Taiwan, South Korea, and the United States concentrate advanced logic capacity, while Japan and Germany supply automotive-grade device finishing. Single-source vulnerability in EUV scanner availability from ASML creates acute bottlenecks for GAAFET bitcell qualification. Distribution runs through direct foundry relationships for hyperscale cache procurement, displacing traditional semiconductor distribution channels for high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SRAM incumbents face a substitution defense against low-power DRAM encroachment in cost-sensitive IoT endpoints, requiring strategic repositioning around latency-critical applications where refresh-free operation sustains irreplaceable value.
For Market Incumbents: Pre-empt pseudo SRAM displacement by accelerating automotive AEC-Q100 Grade 0 pipeline investment, locking Tier 1 sensor fusion contracts before DRAM latency improvements narrow the gap. Deepen backward integration into silicon wafer supply through long-term offtake agreements with Shin-Etsu to secure feedstock priority during foundry allocation crunches.
For New Entrants and Emerging Players: India's underpenetrated industrial automation controller market offers white-space capture under PLI scheme incentives, with captive SRAM demand from domestic electronics assembly expanding faster than indigenous supply. Target healthcare imaging equipment manufacturers in Japan with extended-temperature asynchronous devices, leveraging Renesas Electronics' qualification gaps for long-term supply guarantee contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-certified fab operators with AEC-Q100 pipelines, where multi-year Tier 1 supply agreements generate predictable cash flows across semiconductor cyclicality. Over a five-to-ten-year viability window, prioritize acquisition targets with ISO 26262 ASIL-D verification capabilities and established Infineon or NXP customer relationships. Monitor EU F-Gas Regulation etch chemistry transition timelines as an inflection indicator for foundry equipment upgrade cycles and associated SRAM-compatible mature-node capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Qualification Pipeline | Infineon Technologies' automotive-certified fabs lock multi-year Tier 1 sensor fusion supply agreements. |
| Backward Integration into Silicon Wafers | Long-term Shin-Etsu offtake agreements secure feedstock priority during Taiwan foundry allocation crunches. |
| ISO 26262 ASIL-D Verification Investment | Fault-tolerant SRAM for steer-by-wire systems opens premium pricing tiers above industrial-temperature devices. |
| Direct Foundry Relationship Establishment | Hyperscale data center cache procurement displaces traditional distribution channels for volume concentration. |
| India PLI Scheme Manufacturing Footprint | Domestic electronics assembly incentives create captive industrial SRAM demand from automation controllers. |
Research Methodology
Desk research of SEC semiconductor filings, EU REACH substance restriction databases, and MIIT self-sufficiency policy documents preceded structured interviews with foundry capacity planners, Tier 1 automotive module procurement directors, and hyperscale data center infrastructure architects. Primary fieldwork with Taiwan foundry executives and Germany-based automotive qualification specialists was cross-validated against TSMC and UMC public disclosure patterns. Bottom-up bitcell demand modeling was triangulated with top-down foundry wafer start allocation data.
Assumptions held fixed across the modeling period include EU F-Gas Regulation enforcement timelines and ISO 26262 functional safety mandate adoption curves, while variables included GAAFET ramp-up speed and low-power DRAM substitution elasticity in IoT endpoints. Segmentation dimensions spanned product architecture, application safety-criticality, end-user procurement concentration, and technology integration depth. CAGRs were derived from wafer-equivalent bitcell output trajectories matched to smartphone and AI accelerator demand cycles, with EUV lithography availability constraints explicitly modeled as capacity ceilings.
Practitioners should monitor EU F-Gas Regulation etch chemistry transition compliance deadlines and ASML EUV scanner delivery schedules for early signals of foundry capacity reallocation. Cross-checking against SEMI silicon wafer shipment data and IHS Markit automotive semiconductor consumption indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
DRAM Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Digital RF Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Next Generation Memory Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Automotive Memory Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
New RAM Market
Memory Chips
Memory Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Memory Chip Market
Memory Chips
DDR SDRAM Market