
 In-Memory Grid Market | 2026-2036
In-Memory Grid Market Size, Share, and Industry Trends Forecast 2026-2036
In-Memory Grid Market Outlook
Subscription-based and consumption-oriented financing is narrowing the competitive field for in-memory grid infrastructure, allowing mid-tier enterprises to access enterprise-grade performance without capital-intensive procurement. Hazelcast Inc. leverages its open-source roots to compete aggressively on developer adoption and community-driven feature velocity. Oracle Corporation anchors its position through deep integration with its broader database and cloud ecosystem, while IBM Corporation sustains relevance via mainframe-adjacent deployments in regulated industries.
An in-memory grid distributes data across clustered RAM pools to deliver sub-millisecond access latency for transactional and analytical workloads, typically operating with replication factors of two or three to ensure fault tolerance without disk I/O bottlenecks. Cloud deployment configurations are capturing the fastest expansion as enterprises prioritize elastic scaling and reduced data center overhead. Compute grid solutions concentrate margin pools where specialized processing workloads require tightly coupled memory and CPU affinity, while caching solutions remain the most mature segment with established price-performance benchmarks.
FCC guidelines on telecommunications data handling, HIPAA requirements for healthcare transaction integrity, and SEC expectations for financial market latency and audit trails collectively shape product certification and procurement criteria across the United States. The EU AI Act and GDPR cross-border data flow restrictions add compliance complexity for vendors serving European-headquartered multinationals. Stakeholders must weigh sovereign cloud mandates against the operational simplicity of unified global deployments when selecting architecture partners.
Market Dynamics
Cloud migration mandates under data sovereignty frameworks are accelerating infrastructure refresh cycles across financial services and telecommunications sectors, compressing deployment timelines from 18-month waterfall projects to continuous delivery pipelines.
Growth Catalysts
- Real-time transaction processing:BFSI firms deploy in-memory grids to eliminate disk I/O latency from payment clearing and fraud detection workflows.
- HIPAA audit trail requirements:Healthcare payers and providers invest in sub-millisecond data grids to satisfy transaction integrity mandates for electronic health records.
- Elastic cloud scaling:Enterprises prioritize RAM-pool architectures that auto-scale compute and memory independently during peak load periods.
Market Restraints
- DDR5 memory cost volatility:RAM module pricing fluctuations directly compress margin on hardware-intensive grid deployments.
- EU AI Act cross-border friction:GDPR data flow restrictions complicate unified grid architectures for European-headquartered multinationals.
- SSD-NVMe convergence:High-performance persistent memory substitutes threaten pure RAM-grid value propositions in latency-tolerant workloads.
Strategic Opportunities
- Edge computing integration:Convergence of in-memory grids with 5G MEC nodes creates distributed transaction processing for autonomous systems and industrial IoT.
- India data localization mandates:RBI and SEBI requirements for domestic data storage drive sovereign cloud grid deployments in Mumbai and Hyderabad clusters.
- Outcome-based consumption models:Metered RAM-hour billing replaces perpetual licensing, opening enterprise-grade performance to mid-tier buyers without capital expenditure.
Industry Challenges
- Distributed systems engineering talent scarcity:Shortage of specialists in consensus protocols, partition tolerance, and memory-optimized garbage collection constrains deployment velocity.
- Legacy mainframe integration complexity:Financial institutions struggle to synchronize IMS/DB2 transaction states with modern grid architectures without breaking atomicity guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Memory Grid Market |
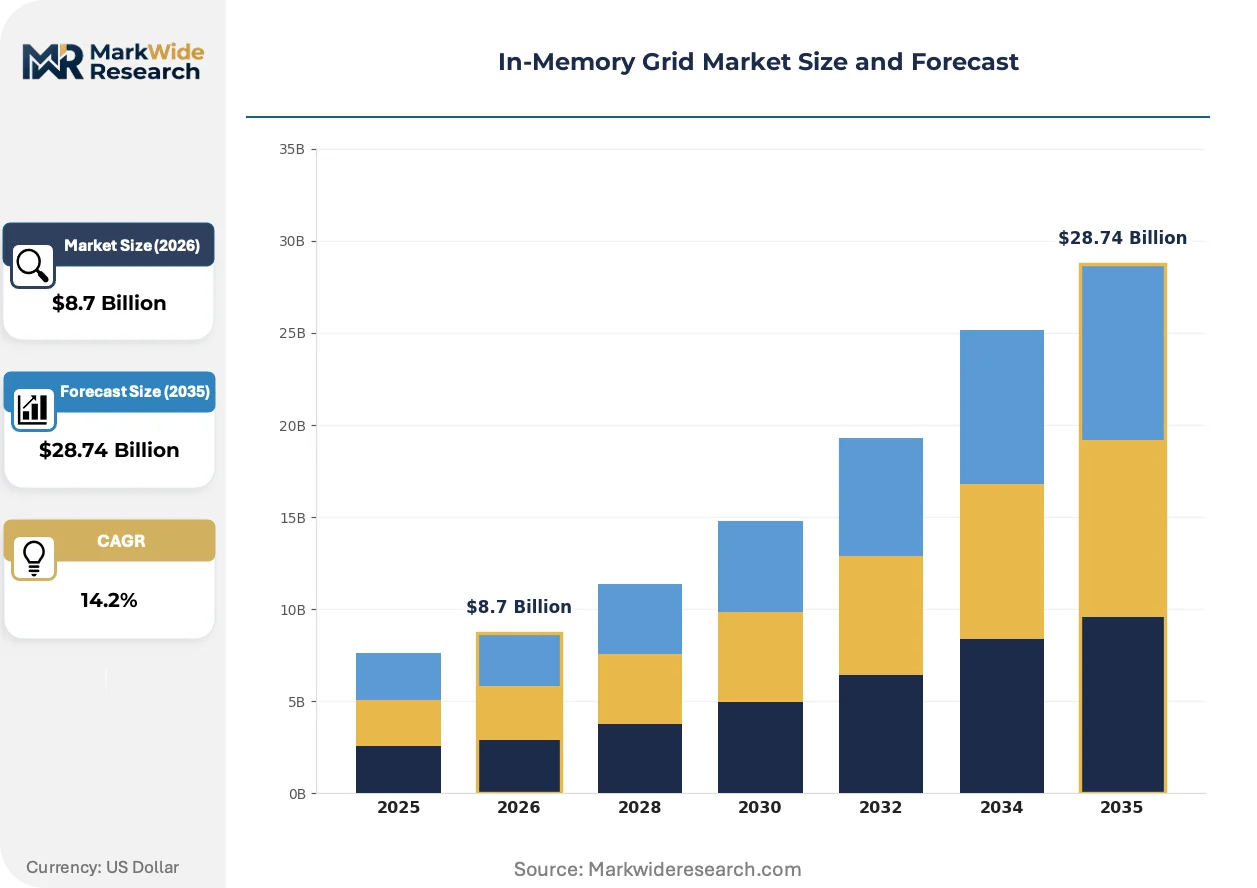
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge Solution Type: Data Grid, Compute Grid, Caching Solution, In-Memory Database End User: Retail, BFSI, Telecommunications, Healthcare Application: Real-Time Analytics, Fraud Detection, Online Transaction Processing, Streaming Data Processing |
| Companies Covered | Hazelcast Inc., GridGain Systems Inc., Oracle Corporation, IBM Corporation, TIBCO Software Inc., Software AG, GigaSpaces Technologies Inc., ScaleOut Software, Red Hat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Memory Grid Market Strategic Shifts
Software-defined memory tiering is collapsing the boundary between DRAM, persistent memory, and NVMe storage, enabling single-address-space architectures that dynamically promote hot data without application rewrites.
Persistent memory modules based on Intel Optane and CXL 2.0 interconnects are collapsing the latency gap between volatile RAM and storage-class memory. Capital markets firms in Chicago and Frankfurt deploy these hybrid tiers for pre-trade risk analytics that demand microsecond consistency. The technology is collapsing traditional database architecture boundaries, allowing transactional and analytical workloads to share identical memory spaces without ETL pipelines.
SEC expectations for market latency and audit trail completeness are forcing trading infrastructure vendors to certify sub-millisecond grid implementations under Regulation SCI. Compliance teams must now document failover testing and capacity thresholds with the same rigor as algorithmic trading systems. Sell-side brokerages in New York and London are responding by consolidating fragmented caching layers into unified grid platforms with embedded compliance telemetry.
Subscription financing for grid infrastructure is displacing perpetual licensing across buy-side asset managers and regional banks. Hazelcast and cloud-native alternatives capture developer preference through community editions that convert to metered enterprise contracts at production scale. This shift is most visible in the United States, where hyperscaler marketplaces simplify procurement for firms lacking dedicated infrastructure procurement functions.
In-Memory Grid Market Segmentation
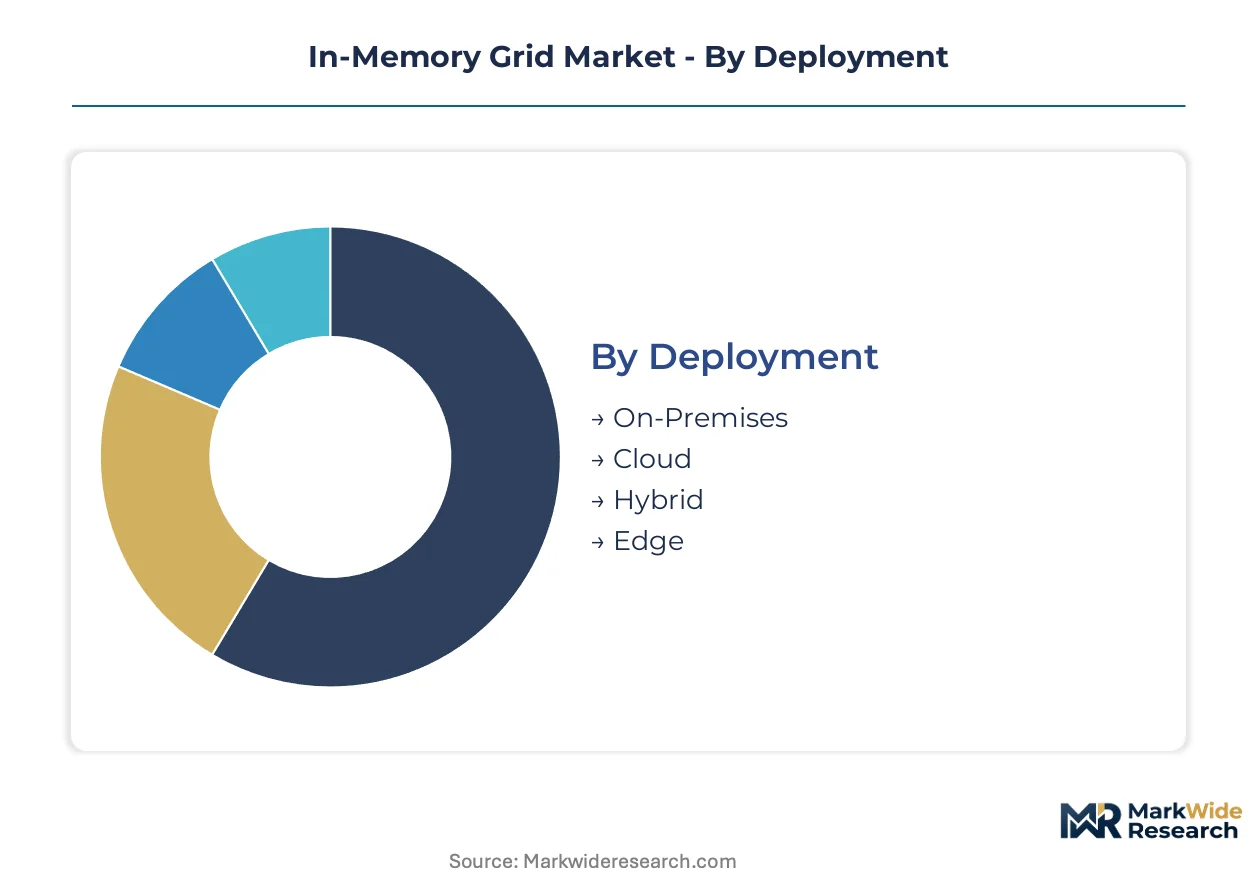
In-memory grid architectures fragment across deployment topologies, workload types, and latency requirements. Procurement teams segment investments by operational sovereignty needs and transaction volume profiles rather than generic infrastructure categories.
Deployment:
After-sales engineering intensity concentrates in hybrid and edge configurations where field deployment teams must reconcile on-premises latency guarantees with cloud orchestration layers.
- On-Premises:Dedicated rack-mounted RAM clusters deliver deterministic sub-millisecond response for trading floors and core banking systems. Financial institutions in Chicago and Frankfurt maintain these deployments to satisfy SEC and national regulator audit trail requirements without third-party infrastructure dependencies.
- Cloud:Elastic RAM pools provisioned through hyperscaler marketplaces auto-scale compute and memory independently during peak load periods. Buy-side asset managers and regional banks in the United States favor metered consumption models that eliminate capital expenditure barriers.
- Hybrid:Split architectures partition sensitive transaction data on-premises while bursting analytical workloads to cloud tiers. This configuration demands intensive integration support to maintain consistency across boundary layers.
- Edge:Distributed grid nodes collocated with 5G MEC infrastructure process autonomous system transactions and industrial IoT telemetry. Deployment complexity rises with geographic dispersion and intermittent connectivity patterns.
By volume, Cloud leads. By growth pace, Edge configurations are climbing the fastest as telecommunications firms expand low-latency infrastructure.
Solution Type:
Cost tiering separates commodity caching layers from premium compute grids where specialized processing workloads command hardware-software bundled pricing.
- Data Grid:Distributed RAM pools replicate data across cluster nodes with configurable consistency models. BFSI firms deploy these for payment clearing workflows requiring fault tolerance without disk I/O bottlenecks.
- Compute Grid:Tightly coupled memory and CPU affinity for specialized processing workloads. Capital markets applications in Frankfurt and Chicago leverage these tiers for pre-trade risk analytics demanding microsecond consistency.
- Caching Solution:Mature segment with established price-performance benchmarks and standardized procurement patterns. Retail and telecommunications sectors favor these for session management and content delivery acceleration.
- In-Memory Database:Unified transactional and analytical storage eliminating ETL pipelines. Healthcare payers invest here to satisfy HIPAA transaction integrity mandates for electronic health records.
By commercial footprint, Caching Solution dominates installed base. By expansion trajectory, In-Memory Database is gaining share fastest as persistent memory technologies collapse latency boundaries.
End User:
Application maturity varies sharply—BFSI demands sub-millisecond certification while retail tolerates millisecond-grade performance at substantially lower price points.
- BFSI:Real-time fraud detection and payment clearing drive the most demanding latency specifications. SEC expectations for market latency and audit trail completeness force trading infrastructure vendors to certify implementations under Regulation SCI.
- Telecommunications:FCC guidelines on data handling shape product certification for subscriber management and billing systems. 5G core network functions increasingly rely on distributed RAM grids for session state replication.
- Healthcare:HIPAA audit trail requirements push payers and providers toward sub-millisecond transaction integrity. Electronic health record systems represent a concentrated demand pocket with stringent compliance overhead.
- Retail:E-commerce personalization and inventory synchronization operate at more tolerant latency thresholds. Price sensitivity here favors open-source and community-edition deployments.
By deployment value, BFSI leads. By contract velocity, Telecommunications is expanding most quickly as 5G infrastructure refresh cycles accelerate.
Application:
Customer type stratification separates capital markets firms with dedicated infrastructure teams from mid-tier enterprises purchasing through managed service channels.
- Real-Time Analytics:Continuous query processing against streaming data feeds without persistence latency. Capital markets risk engines in New York and London represent the premium demand tier.
- Fraud Detection:Pattern recognition across transaction streams requiring immediate decisioning. BFSI investment concentrates here as regulatory pressure intensifies on anti-money-laundering latency.
- Online Transaction Processing:Core banking and payment systems demanding atomic consistency guarantees. Legacy mainframe integration complexity constrains deployment velocity for this application class.
- Streaming Data Processing:Ingestion and transformation of high-velocity event streams for downstream analytics. Industrial IoT and autonomous vehicle telemetry create distributed processing requirements.
By current spend, Online Transaction Processing leads. By adoption momentum, Streaming Data Processing shows the steepest expansion trajectory as edge computing architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for in-memory grid infrastructure tilt toward software licensing and managed service flows rather than physical hardware trade, with the United States running a structural surplus in enterprise-grade grid platforms while India and Germany import specialized compute-tier solutions for capital markets applications.
United States
Hyperscaler partnerships and enterprise data center consolidation drive deployment volume across financial services and telecommunications sectors. SEC expectations for market latency and audit trail completeness under Regulation SCI shape procurement criteria for trading infrastructure vendors. Chicago and New York clusters concentrate pre-trade risk analytics deployments demanding microsecond consistency.
Germany
Automotive and industrial IoT applications propel demand for edge-integrated grid architectures alongside persistent memory hybrid tiers. GDPR cross-border data flow restrictions complicate unified grid architectures for European-headquartered multinationals. Frankfurt maintains dense concentrations of capital markets grid infrastructure serving continental European exchanges.
India
RBI and SEBI data localization mandates accelerate sovereign cloud grid deployments for financial transaction processing. Domestic storage requirements for electronic records push healthcare payers toward sub-millisecond transaction integrity solutions. Mumbai and Hyderabad clusters emerge as primary deployment locations for BFSI and telecommunications grid infrastructure.
United Kingdom
Buy-side asset managers favor metered consumption models eliminating capital expenditure barriers for real-time analytics workloads. FCA expectations for operational resilience influence grid certification requirements for systemically important trading venues. London concentrates sell-side brokerage consolidation of fragmented caching layers into unified grid platforms.
Japan
Manufacturing sector investment in industrial IoT telemetry creates distributed processing requirements for edge computing integration. METI industrial digitization programs subsidize adoption of software-defined memory tiering architectures. Tokyo-Osaka corridor hosts concentrated deployments for autonomous systems and smart factory applications.
In-Memory Grid Market Competitive Environment
On the supply side, the industry is tiered between open-source-rooted challengers, database-ecosystem incumbents, and mainframe-adjacent legacy providers. Strategic archetypes separate developer-community-driven platforms from deeply integrated enterprise stacks and regulated-industry specialists. Competitive moves concentrate on hyperscaler marketplace partnerships and consumption-based financing models displacing perpetual licensing.
Within the open-source-rooted tier, Hazelcast Inc. exemplifies community-driven feature velocity converting to metered enterprise contracts, while Oracle Corporation anchors the database-ecosystem incumbent position through cloud integration depth. IBM Corporation occupies the mainframe-adjacent specialist archetype sustaining relevance in regulated financial services deployments.
| Leading Market Players |
|---|
| Hazelcast Inc. |
| GridGain Systems Inc. |
| Oracle Corporation |
| IBM Corporation |
| TIBCO Software Inc. |
| Software AG |
| GigaSpaces Technologies Inc. |
| ScaleOut Software |
| Red Hat Inc. |
| Others |
Value Chain & Pricing Dynamics
DDR5 memory cost volatility compresses margins across hardware-intensive grid deployments, forcing pricing stratification across premium compute tiers, standard data grid configurations, and economy-grade caching solutions while simultaneously reshaping supplier relationships toward contract-based long-term offtake arrangements.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Premium tiers command hardware-software bundled pricing for compute grids serving capital markets applications, while standard data grids compete on certification grade against open-source alternatives. Cost compression in economy tiers intensifies because hyperscaler marketplace procurement eliminates traditional channel markups. Mid-tier enterprises purchasing through metered consumption models exhibit highest price sensitivity; regulated financial institutions demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for memory module sourcing in grid infrastructure. Manufacturing concentrates in Taiwan, South Korea, and the United States for advanced DRAM fabrication. Component dependencies rest on DDR5 modules, CXL 2.0 interconnects, and persistent memory controllers. Single-source vulnerability threatens Intel Optane discontinuation impacts. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with intensive field engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-memory grid demand tracks infrastructure refresh cycles in financial services, positioning the market for cyclical recovery as SEC audit trail mandates and cloud migration timelines converge.
For Market Incumbents: Pre-empt open-source substitution by embedding compliance telemetry directly into unified grid platforms. Defend against Hazelcast's community-driven conversion funnel through deeper Oracle Cloud Infrastructure integration. Prioritize certification investment for Regulation SCI compliance to lock in sell-side brokerage renewals.
For New Entrants and Emerging Players: Pursue edge computing integration with 5G MEC deployments as the most penetrable white space. Target industrial IoT telemetry applications in Japan's manufacturing corridor where METI subsidies reduce customer acquisition friction. Lead with software-defined memory tiering as the primary go-to-market angle.
For Investors and Strategic Acquirers: EU AI Act cross-border friction reshapes the acquisition landscape toward sovereign cloud specialists with European data residency capabilities. Long-term viability favors vendors with persistent memory IP and CXL ecosystem partnerships. Watch RBI data localization enforcement in Mumbai clusters as the inflection indicator for emerging market grid demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified grid architectures collapsing transactional and analytical boundaries eliminate ETL pipeline costs for healthcare payers. |
| Strategic Partnership | Hyperscaler marketplace listings simplify procurement for asset managers lacking dedicated infrastructure teams. |
| Geographic Expansion | Mumbai and Hyderabad clusters capture RBI-mandated sovereign cloud deployments for domestic transaction processing. |
| Product Launch | Software-defined memory tiering products exploiting Intel Optane and CXL 2.0 collapse latency gaps in Chicago risk engines. |
| Acquisition of Specialist Firm | Edge computing specialists with 5G MEC integration capabilities address autonomous systems telemetry requirements. |
Study Parameters
Cross-validation between CTO interviews at buy-side asset managers and hyperscaler capex disclosures anchors the qualitative findings in this study. Primary fieldwork engaged platform engineers, IT procurement officers, integration specialists, and channel partners across financial services and telecommunications verticals. Secondary validation drew from SEC filings, FERC infrastructure reports, EIA data center energy consumption statistics, and hyperscaler marketplace transaction disclosures. Bottom-up deployment modeling triangulated against top-down addressable market sizing across the analysis window.
Calibration against historical infrastructure refresh cycles and regulatory compliance timelines shaped the analytical framework. Segmentation dimensions modeled include deployment topology, solution type, end-user vertical, application workload, and regional regulatory cluster. CAGRs derived from slope-log regression against normalized adoption curves. Industry-specific forecast inputs incorporated DDR5 pricing futures and persistent memory technology roadmaps from Intel and Samsung.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting capital expenditure cycles or memory commodity spot prices would shift the trajectory. Forecasts reflect documented assumptions on cloud migration velocity and sovereign data residency enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Memory Module Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
DRAM Market
Memory Chips
Global Standalone Memory Market
Memory Chips
DDR SDRAM Market
Memory Chips
Mobile DRAM Market
Memory Chips
Contactless Memory Market
Memory Chips
GDDR6 Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Japan Flash Memory Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Memory Chip Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
DDR RAM Market
Memory Chips
Automotive DRAM Market