
 Asia Pacific Semiconductor Memory Market | 2026-2036
Asia Pacific Semiconductor Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Semiconductor Memory Market Insights
Project finance tied to sovereign semiconductor funds is fragmenting competitive access across the Asia Pacific region. Samsung Electronics leverages vertical integration from wafer fabrication to module assembly, sustaining cost advantages in DRAM scale production. SK Hynix anchors its position through advanced packaging investments in South Korea, while Micron Technology navigates geopolitical constraints by diversifying assembly footprints. Kioxia Corporation specializes in 3D NAND architecture, differentiating through layer-stacking density leadership.
Asia Pacific semiconductor memory encompasses volatile and non-volatile integrated circuit storage devices fabricated through photolithographic processes on silicon substrates, with critical specifications including cell density measured in gigabits per square millimeter and refresh intervals defining data retention integrity. These devices serve as primary working memory and persistent storage across computing systems, enabling data throughput rates essential for real-time processing workloads. Flash Memory commands the largest value pool due to enterprise SSD penetration, while DDR5 transitions represent the fastest-expanding technology segment as server refresh cycles accelerate. Embedded Systems applications concentrate margin premiums where automotive-grade reliability certifications create supply scarcity.
Japan's METI coordinates domestic production subsidies with export control alignment, while China's SAMR enforces antitrust reviews on foreign memory suppliers seeking market access. South Korea's K-Semiconductor Belt initiative channels tax incentives toward domestic R&D intensity, tightening local content requirements for government-linked procurement. Stakeholders must monitor how divergent subsidy regimes and technology sovereignty agendas reshape supplier qualification pathways across the region.
Market Dynamics
AI training clusters are reconfiguring memory procurement specifications across the Asia Pacific region, forcing hyperscale operators to prioritize high-bandwidth modules over commodity DRAM configurations.
Growth Catalysts
- China's dual carbon goals:These national decarbonization mandates are accelerating fab investment into energy-efficient 3D NAND production processes, redirecting capital toward memory corridors in the Yangtze River Delta.
- Hyperscale data center expansion:South Korean and Taiwanese cloud operators are scaling memory procurement volumes to support generative AI infrastructure buildouts, creating sustained demand pull for DDR5 and HBM architectures.
- Japan's METI semiconductor subsidies:This domestic production support framework is channeling public capital into advanced packaging R&D, strengthening Kioxia's position in layer-stacking density leadership.
Market Restraints
- Geopolitical export controls:Technology transfer restrictions between the United States and China are fragmenting equipment supply chains, forcing memory fabs to qualify secondary lithography tool vendors.
- Extreme ultraviolet lithography dependency:Single-sourced EUV scanner availability from ASML creates capacity bottlenecks for sub-7nm DRAM nodes, concentrating yield risk among three equipment-qualified manufacturers.
- Silicon wafer input volatility:Polysilicon price fluctuations and 300mm wafer supply concentration in Japanese and Korean foundries compress margin predictability for memory module assemblers.
Strategic Opportunities
- Southeast Asia assembly diversification:Vietnam and Malaysia are attracting backend packaging investment as manufacturers seek geographic risk distribution outside China and Taiwan.
- Automotive-grade memory certification:AEC-Q100 qualification requirements for autonomous driving systems are creating supply scarcity premiums for temperature-resilient NAND and LPDDR5 components.
- South Korea's K-Semiconductor Belt:This tax incentive and infrastructure program is tightening local content requirements, creating captive demand pools for domestic material and equipment suppliers.
Industry Challenges
- EUV photoresist chemist scarcity:The specialized workforce required for advanced lithography process engineering remains concentrated in Japanese and Korean national labs, constraining fab expansion timelines.
- Multi-die packaging integration complexity:HBM stack bonding and thermal management requirements are extending product qualification cycles, compressing time-to-revenue windows for new memory architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Semiconductor Memory Market |
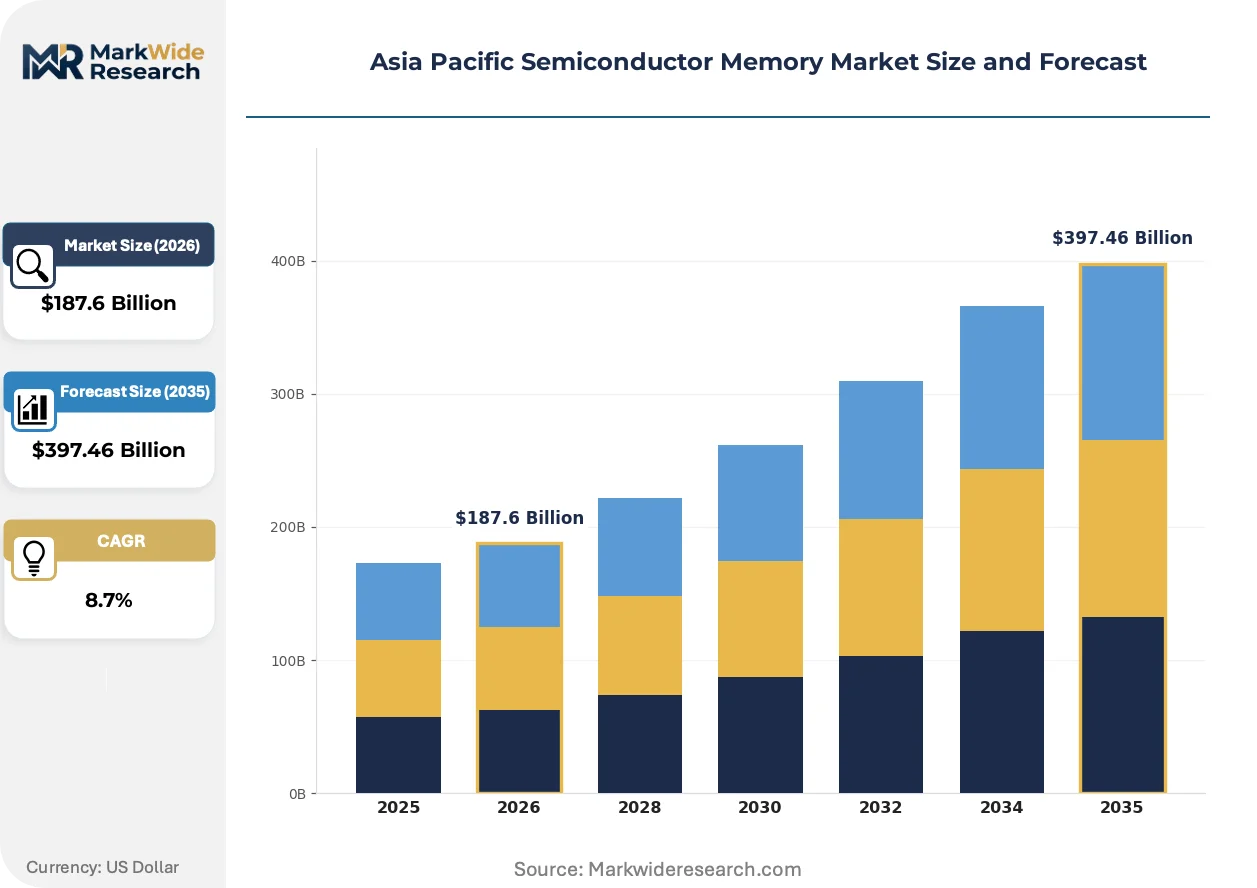
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash Memory, EEPROM Technology: 3D NAND, 2D NAND, DDR4, DDR5 End User: Consumer Electronics, Automotive, Industrial, Telecommunications Application: Data Centers, Mobile Devices, PCs, Embedded Systems |
| Companies Covered | Samsung Electronics Co. Ltd, SK Hynix Inc., Micron Technology Inc., ROHM Co. Ltd., STMicroelectronics NV, Kioxia Corporation, Toshiba Electronic Devices & Storage Corporation, Macronix International, Intel Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Semiconductor Memory Market Trends and Innovations
Memory architecture evolution is accelerating across the Asia Pacific as sovereign technology agendas and AI workload requirements force divergence from established commodity production models.
DDR5 SDRAM is migrating from enterprise server refresh cycles into mainstream data center deployment. Hyperscale operators in Taiwan and South Korea are standardizing on 4800 MT/s modules for training cluster memory subsystems. This transition is compressing DDR4 residual value and forcing module manufacturers to reconfigure test floor capacity.
South Korea's K-Semiconductor Belt initiative is tightening local content requirements for government-linked procurement. Domestic memory manufacturers must now source specified percentages of equipment and materials from Korean suppliers to qualify for tax incentives. Advanced packaging vendors are responding by relocating R&D facilities to Gyeonggi Province.
Memory procurement specifications are consolidating around performance-per-watt metrics rather than raw capacity. Cloud operators in the Yangtze River Delta are embedding power efficiency requirements into supplier scorecards, favoring low-voltage LPDDR derivatives for edge inference workloads. This behavioral shift is most visible in China's AI server procurement tenders.
Asia Pacific Semiconductor Memory Market Segmentation
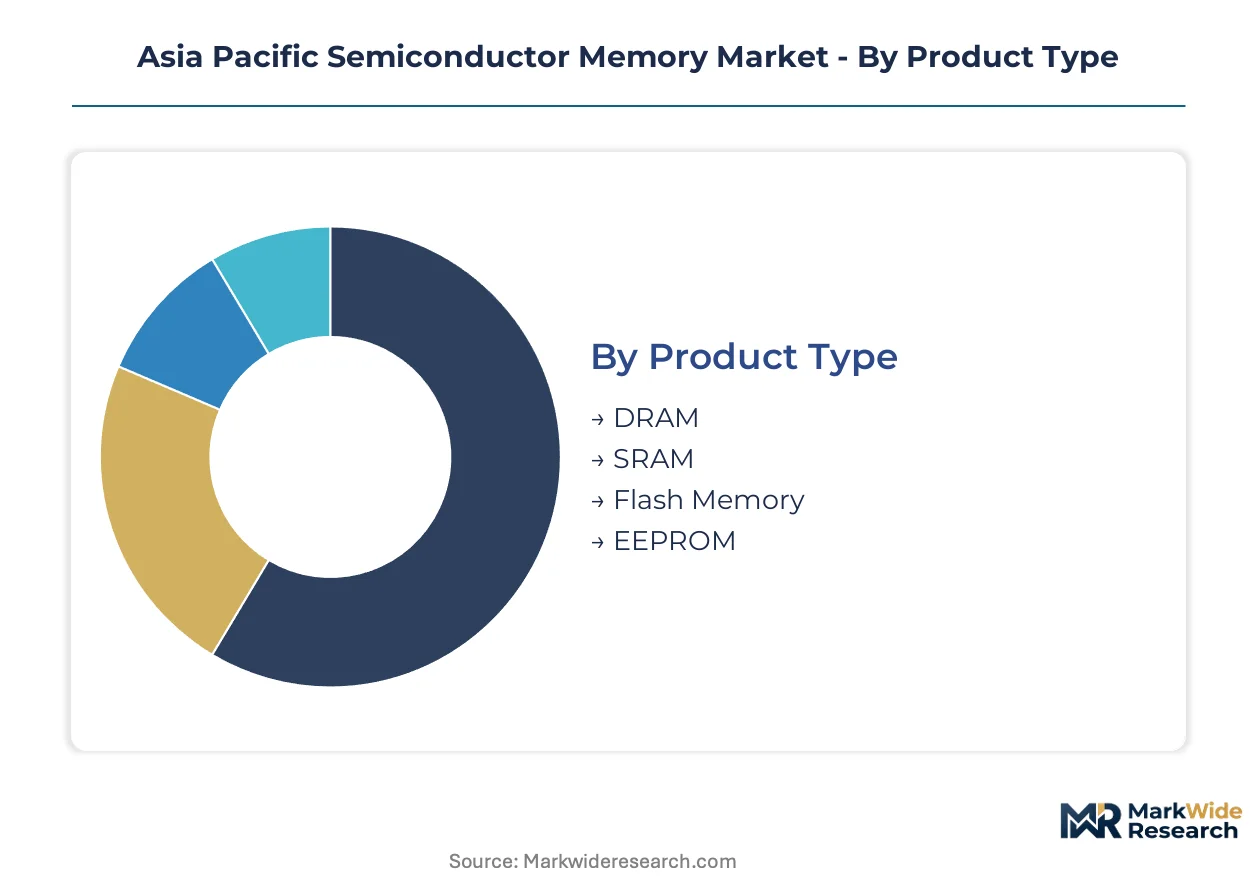
Memory procurement specifications across the Asia Pacific diverge sharply by application workload, creating distinct aftermarket service requirements. Technical support intensity varies from firmware customization for embedded deployments to field replacement programs for hyperscale data center operators.
Product Type:
After-sales service intensity escalates with cell density complexity and data integrity requirements, driving differentiated support contracts across memory categories.
- DRAM:Volatile memory cells requiring constant refresh cycles sustain working memory functions in computing systems. Samsung Electronics and SK Hynix concentrate high-bandwidth module production in South Korea's K-Semiconductor Belt to serve AI training clusters proliferating across the region. Service contracts emphasize rapid field replacement given data loss exposure during refresh failures.
- Flash Memory:Non-volatile storage based on floating-gate transistor technology enables persistent data retention without power. Enterprise SSD penetration in China's Yangtze River Delta memory corridor commands the largest value pool, though wear-leveling firmware support requirements extend technical service obligations across multi-year deployment cycles.
- SRAM:Static random-access memory utilizing bistable latching circuits delivers faster access speeds without refresh overhead. Cache memory applications in network processors and automotive control units drive demand, with limited aftermarket service needs due to embedded deployment patterns.
- EEPROM:Electrically erasable programmable read-only memory permits byte-level write operations for configuration storage. Industrial automation systems and automotive ECUs in Japan's manufacturing corridors represent primary demand concentrations, with firmware update services dominating post-sale technical engagement.
By volume, Flash Memory leads. By growth pace, DRAM is ahead.
Technology:
Process node transitions concentrate capital expenditure among qualified equipment operators, fragmenting competitive access by lithography capability.
- 3D NAND:Vertical layer-stacking architecture achieves density through string-stacking rather than planar shrink, with Kioxia Corporation specializing in layer-stacking density leadership. China's dual carbon goals redirect Yangtze River Delta fab investment toward energy-efficient 3D NAND production processes.
- DDR5:Fifth-generation synchronous dynamic random-access memory operates at 4800 MT/s and beyond, with Taiwanese and South Korean hyperscale operators standardizing modules for training cluster memory subsystems. This transition compresses DDR4 residual value and forces test floor reconfiguration.
- 2D NAND:Planar flash memory architectures persist in cost-optimized storage applications where layer-stacking premiums are uneconomical. Legacy consumer electronics and industrial control systems in Southeast Asian assembly corridors sustain residual demand.
- DDR4:Fourth-generation memory technology faces accelerated obsolescence as server refresh cycles migrate to DDR5 platforms. Module manufacturers are reallocating capacity toward DDR5 test infrastructure, constraining DDR4 supply availability for maintenance-replacement markets.
By installed base, DDR4 dominates. By expansion trajectory, DDR5 climbs the fastest.
End User:
Reliability certification requirements stratify margin structures, with temperature-resilient automotive specifications commanding supply scarcity premiums.
- Automotive:AEC-Q100 qualification mandates temperature cycling resilience for autonomous driving systems. Memory components must sustain operation across -40°C to 125°C thermal envelopes, with Japanese and Korean suppliers concentrating automotive-grade production in METI-subsidized packaging facilities.
- Data Centers:Hyperscale operators in Taiwan and South Korea prioritize performance-per-watt metrics over raw capacity, embedding power efficiency into supplier scorecards. Cloud procurement tenders in the Yangtze River Delta explicitly specify low-voltage LPDDR derivatives for edge inference workloads.
- Consumer Electronics:Smartphone and tablet manufacturers drive volume demand for LPDDR5 and UFS storage modules. Assembly concentration in Vietnam and Malaysia is attracting backend packaging investment as manufacturers seek geographic risk distribution.
- Industrial:Programmable logic controllers and robotics systems require extended temperature operation with deterministic latency guarantees. Japan's manufacturing base sustains demand for EEPROM and ruggedized NAND configurations with decade-long supply continuity commitments.
By revenue concentration, Data Centers lead. By margin expansion, Automotive is ahead.
Application:
Workload-specific throughput requirements fragment memory architecture selection, with real-time processing demands forcing divergence from commodity configurations.
- Embedded Systems:Tight integration of memory with application-specific processors creates margin premiums where automotive-grade reliability certifications constrain qualified supplier pools. Firmware customization services dominate aftermarket relationships.
- Mobile Devices:Smartphones and tablets drive demand for low-power LPDDR derivatives and compact UFS storage. South Korean and Chinese OEMs concentrate procurement specifications around thermal envelope constraints and package-on-package integration.
- PCs:Desktop and notebook systems sustain DDR4 residual demand while DDR5 penetration accelerates in premium segments. Module assemblers face margin compression from silicon wafer input volatility concentrated in Japanese and Korean foundries.
- Data Centers:Training cluster infrastructure buildouts sustain demand pull for HBM architectures and high-capacity DDR5 modules. Multi-die packaging integration complexity extends qualification cycles, compressing time-to-revenue windows.
By unit volume, Mobile Devices lead. By technology premium capture, Embedded Systems is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Taiwanese memory corridors while Chinese fabs absorb margin compression from equipment access constraints. Japan's METI-subsidized packaging facilities capture technology premiums unavailable elsewhere in the region. Southeast Asian assembly nodes in Vietnam and Malaysia arbitrage geographic risk without commanding equivalent value capture.
China
Yangtze River Delta memory corridors absorb the bulk of domestic fab investment as SAMR enforces antitrust reviews on foreign suppliers seeking market access. Dual carbon goals redirect capital toward energy-efficient 3D NAND production processes. Shanghai and Hefei clusters concentrate advanced packaging qualification activity for domestic equipment vendors.
South Korea
K-Semiconductor Belt tax incentives tighten local content requirements for government-linked procurement, channeling demand toward domestic material suppliers. AI training clusters proliferating in Seoul Capital Area and Busan-Ulsan drive hyperscale memory procurement for DDR5 and HBM architectures. Samsung Electronics and SK Hynix anchor wafer-to-module vertical integration in Gyeonggi Province.
Japan
METI coordinates domestic production subsidies with export control alignment, strengthening Kioxia's position in layer-stacking density leadership. Kanto and Kansai industrial corridors sustain concentrated EUV photoresist chemistry expertise. Yokohama and Osaka packaging facilities specialize in automotive-grade reliability certifications for temperature-resilient NAND components.
Taiwan
Hyperscale data center operators standardize on 4800 MT/s DDR5 modules for training cluster memory subsystems, compressing test floor reconfiguration timelines. New Taipei and Hsinchu Science Park concentrate backend packaging investment serving Chinese and Southeast Asian assembly nodes. Power efficiency requirements embedded in supplier scorecards favor low-voltage LPDDR derivatives.
Vietnam
Backend packaging investment accelerates as manufacturers seek geographic risk distribution outside China and Taiwan. Consumer electronics assembly concentration in Bac Ninh and Bac Giang provinces drives demand for LPDDR5 and UFS storage modules. Industrial zones near Hanoi attract module test and burn-in capacity from Korean and Japanese vendors.
Asia Pacific Semiconductor Memory Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in wafer fabrication and advanced packaging. Market structure consolidates around three equipment-qualified manufacturers for sub-7nm DRAM nodes while fragmenting across secondary lithography tool vendors forced by geopolitical constraints. Strategic archetypes include vertical integrators spanning wafer-to-module production, packaging specialists concentrating multi-die integration, and fabless designers outsourcing fabrication to foundry partners. Dominant competitive moves encompass geographic footprint diversification and captive supply chain development.
Within the vertical integration archetype, Samsung Electronics Co. Ltd exemplifies wafer-to-module production control, while SK Hynix Inc. occupies a position emphasizing advanced packaging investments. Kioxia Corporation anchors the layer-stacking specialization tier among Japanese suppliers. These three entities represent distinct strategic postures: Korean scale-driven integration, Korean packaging-led differentiation, and Japanese density-focused architecture specialization.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| SK Hynix Inc. |
| Micron Technology Inc. |
| ROHM Co. Ltd. |
| STMicroelectronics NV |
| Kioxia Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| Macronix International |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta 3D NAND fabs is compressing spot pricing for standard-grade flash modules while tightening configured-to-order premiums for automotive-qualified components. Samsung Electronics and SK Hynix leverage captive wafer supply in South Korea's K-Semiconductor Belt to defend margin structures against this pressure. Japan's METI-subsidized packaging facilities capture scarcity rents for AEC-Q100 certified products unavailable from Chinese competitors facing equipment access constraints.
Pricing Analysis
The customization-premium spread between configured-to-order automotive-grade memory and standard commodity DRAM spans three distinct pricing tiers across premium, standard, and economy levels. Contract-based long-term offtake agreements dominate hyperscale procurement in Taiwan and South Korea, with price differentiation driven by certification level (AEC-Q100 vs industrial-grade) and volume scale commitments. Cost compression in standard DDR4 modules is intensifying because Chinese fabs absorb margin pressure from lithography tool restrictions. Consumer electronics OEMs in Vietnam and Malaysia exhibit highest price sensitivity, while autonomous driving system integrators in Japan's Kanto corridor demonstrate least elasticity due to supply continuity requirements.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-financing arrangements for equipment-qualified memory manufacturers navigating EUV scanner lead times. Geographic supply concentration centers on South Korea, Taiwan, and Japan for wafer fabrication, with backend assembly drawing from Vietnam and Malaysia. Raw material dependencies rest on 300mm silicon wafers from Shin-Etsu and SUMCO, EUV photoresist from JSR and Tokyo Ohka Kogyo, and specialty gases from Air Liquide and Linde. Single-source vulnerability for ASML EUV scanners creates capacity bottlenecks for sub-7nm DRAM nodes. Distribution runs through direct OEM contracts for hyperscale operators and tiered distributor networks for industrial and automotive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock hyperscale operators into qualified supplier relationships spanning multi-year server refresh cycles. Regulatory entrenchment through Japan's METI subsidies and South Korea's local content requirements reinforces incumbent positioning against geographic diversification attempts.
For Market Incumbents: Entrench through backward integration into EUV photoresist chemistry partnerships with JSR and Tokyo Ohka Kogyo, securing process engineering talent pipelines against Korean national lab concentration. Add test and burn-in capacity in Vietnam's Bac Ninh industrial zones to arbitrage geographic risk without ceding packaging technology leadership. Threat from Chinese domestic equipment vendors qualifying secondary lithography tools demands accelerated R&D in multi-die bonding thermal management.
For New Entrants and Emerging Players: Southeast Asia's backend packaging corridors offer underpenetration opportunity for automotive-grade memory qualification services, specifically AEC-Q100 testing infrastructure in Malaysia's Penang cluster. Target industrial automation OEMs in Japan's Kansai manufacturing belt with decade-long supply continuity commitments for EEPROM and ruggedized NAND configurations. Go-to-market angle: firmware customization services bundled with configuration storage solutions for programmable logic controllers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among advanced packaging specialists with captive HBM stack bonding capabilities serving AI training cluster buildouts. Long-term viability across the analysis window favors component suppliers with demonstrated qualification pathways through South Korea's K-Semiconductor Belt local content requirements. Acquisition target archetype: layer-stacking density specialists with METI-subsidized R&D facilities in Yokohama or Osaka. Signal to watch: hyperscale operator procurement tenders embedding performance-per-watt metrics as primary supplier scorecard criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | SK Hynix's multi-die integration investments in Gyeonggi Province tighten supply for AI training clusters. |
| Backward Integration into Photoresist Chemistry | Samsung Electronics' JSR partnership secures EUV process engineering talent against Japanese national lab concentration. |
| Geographic Diversification to Vietnam | Korean and Japanese vendors relocating test capacity to Bac Ninh arbitrages China-Taiwan geopolitical exposure. |
| Automotive-Grade Certification Investment | Kioxia's AEC-Q100 qualification in METI-subsidized facilities captures temperature-resilient NAND scarcity premiums. |
| Long-Term Supply Agreement with Hyperscalers | Taiwanese operators' DDR5 standardization at 4800 MT/s locks in multi-year offtake commitments. |
Research Methodology
A standing panel of memory procurement executives at hyperscale operators, fab operations directors, advanced packaging R&D leads, and automotive Tier 1 supplier quality managers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEMI equipment shipment data, Korean Ministry of Trade customs records, METI subsidy disclosure filings, and hyperscaler capital expenditure disclosures. Bottom-up triangulation against top-down semiconductor consumption models anchored value estimates.
Scenario-bracketing around EUV equipment access constraints and dual carbon goal implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include memory type (DRAM, Flash, SRAM, EEPROM), technology node (3D NAND, DDR5, 2D NAND, DDR4), end user (automotive, data center, consumer electronics, industrial), and application workload (embedded systems, mobile devices, PCs). CAGRs derived from equipment shipment trajectories, fab capacity expansion schedules, and server refresh cycle timing. Industry-specific inputs encompassed EUV scanner installation pipelines and automotive AEC-Q100 qualification backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic memory suppliers qualifying secondary lithography vendors would shift outcomes. Macroeconomic deviation in semiconductor capital expenditure cycles, regulatory tightening in export control alignment, or technological breakthrough in alternative memory architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Japan DRAM Market
Memory Chips
Memristor Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Mobile DRAM Market
Memory Chips
Smartphone RAM Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Automotive Memory Market
Memory Chips
Japan Flash Memory Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Memory IC Market
Memory Chips
Automotive DRAM Market
Memory Chips
Static Random-Access Memory (SRAM) Market