

eMMC Master Control Chip Market Size, Share, and Industry Trends Forecast 2026-2036
eMMC Master Control Chip Market Insights
High-reliability grade eMMC controllers is redrawing competitive boundaries in embedded storage. Samsung Electronics leverages captive NAND fabrication to anchor its vertical supply chain. Phison Electronics specializes in turnkey controller solutions for mid-tier smartphone OEMs. Silicon Motion Technology competes through advanced error-correction firmware stacks.
An eMMC master control chip integrates NAND flash management, wear-leveling algorithms, and host interface logic within a single silicon die, typically manufactured on mature process nodes between 28nm and 40nm to balance cost with power efficiency. The device translates raw NAND behavior into standardized block-level storage for mobile and embedded hosts. Controller IC products occupy the largest margin pool due to firmware differentiation and IP barriers, while Package on Package technology leads smartphone integration for space-constrained designs. Wafer Level Chip Scale Package formats are gaining traction in wearable electronics where thickness constraints dominate engineering trade-offs.
China's MIIT enforces domestic semiconductor content requirements that redirect procurement toward local foundry partnerships. South Korea's MFDS and Japan's METI coordinate export control frameworks affecting advanced packaging equipment access. REACH compliance in Europe restricts hazardous substances in semiconductor packaging materials, altering substrate supplier qualification. Stakeholders must monitor which regulatory jurisdiction governs their end customer's product certification path before committing controller tape-out schedules.
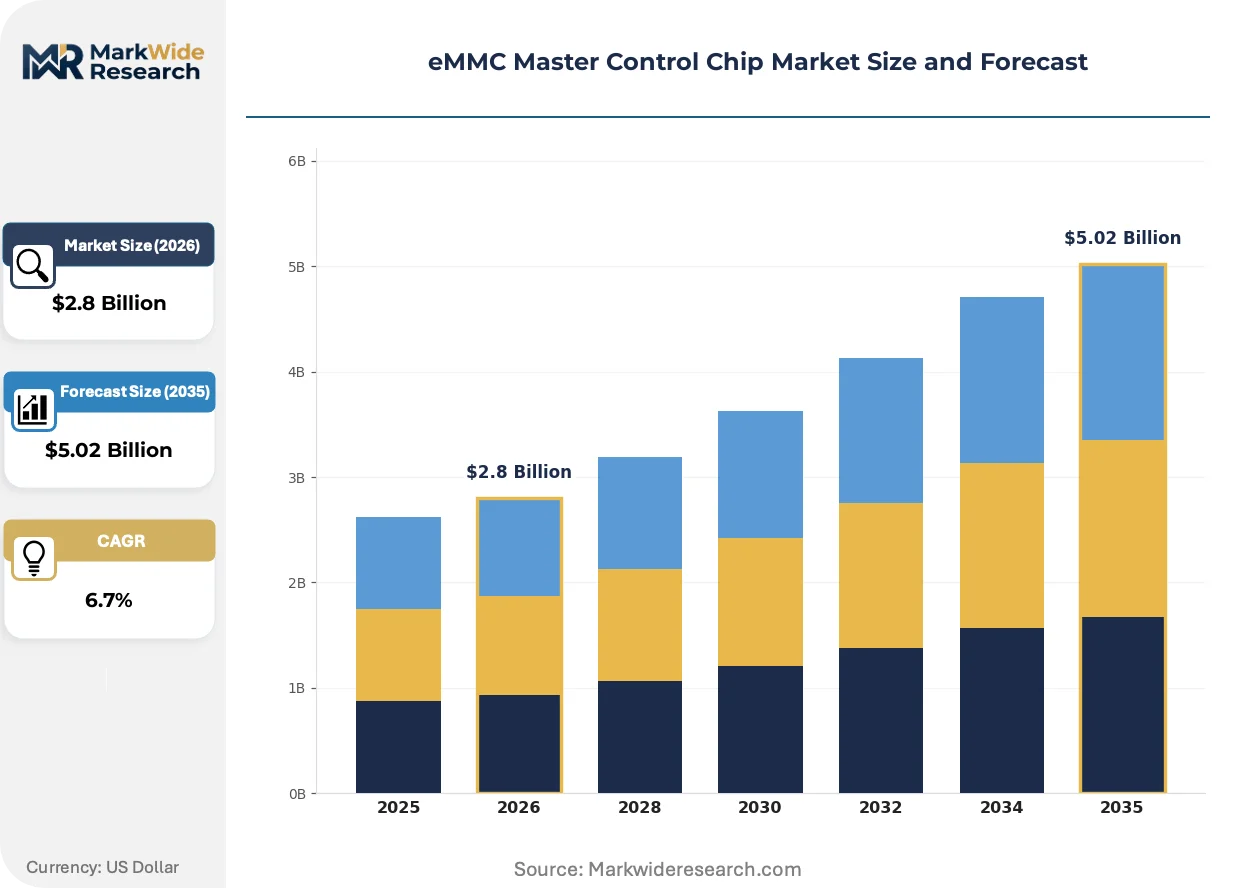
Market Dynamics
Automotive infotainment systems and industrial IoT gateways are pulling eMMC controllers into reliability grades previously reserved for enterprise SSDs, forcing firmware architectures to evolve beyond mobile-centric design assumptions.
Growth Catalysts
- Automotive Functional Safety Mandates:ISO 26262 ASIL-B compliance requirements in automotive ECUs are expanding addressable controller volume for qualified suppliers.
- MIIT Domestic Sourcing Directives:China's semiconductor localization targets are redirecting foundry tape-outs toward indigenous controller design houses.
- Wearable Form Factor Compression:Wafer Level Chip Scale Package adoption in fitness trackers and hearables is generating incremental controller demand for sub-0.4mm thickness specifications.
Market Restraints
- Mature Node Capacity Constraints:28nm to 40nm foundry allocation scarcity at TSMC and GlobalFoundries is extending lead times for controller tape-outs.
- NAND Flash Supply Concentration:Three Korean and Taiwanese memory fabricators control wafer supply, creating upstream dependency risk for fabless controller vendors.
- UFS Interface Substitution:Universal Flash Storage 3.1 and 4.0 protocols are capturing flagship smartphone sockets previously served by eMMC 5.1.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for mobile and IT hardware production are creating new controller procurement nodes in Noida and Chennai clusters.
- Industrial Edge Computing:-40°C to 105°C extended temperature grade controllers for factory automation gateways represent underpenetrated volume.
- EU Battery Passport Integration:Data logging requirements under the EU Green Deal are embedding storage in battery management systems.
Industry Challenges
- Firmware Talent Scarcity:Advanced LDPC error-correction and wear-leveling algorithm development requires scarce NAND flash physics expertise concentrated in Hsinchu and Seoul.
- Multi-Jurisdiction Certification Burden:AEC-Q100 automotive qualification, REACH substance compliance, and MIIT encryption approvals must converge for China-bound automotive shipments.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
eMMC Master Control Chip Market Trends and Innovations
Controller architectures are bifurcating between cost-optimized mobile derivatives and reliability-hardened automotive variants, with firmware differentiation overtaking raw silicon performance as the primary value anchor.
Triple-level cell NAND management with adaptive voltage threshold tracking is supplanting older MLC-based controller firmware in mid-tier smartphone designs. ODMs in Dongguan and Shenzhen are qualifying these configurations for 128GB and 256GB SKUs. The shift is compressing margin structures for controller vendors lacking in-house LDPC IP.
REACH substance restrictions on leadframe plating materials are forcing substrate supplier requalification across European-bound controller shipments. ECHA enforcement of SVHC disclosure requirements is extending compliance documentation burdens to Package on Package assembly houses. Automotive tier-1s in Stuttgart and Munich are now mandating full material declaration transparency from controller vendors.
Direct foundry engagement by smartphone OEMs is displacing traditional module vendor intermediation in procurement channels. Xiaomi and OPPO procurement teams in Beijing and Shenzhen are negotiating controller wafer supply directly with Silicon Motion and Phison. The pattern is most visible in China, where domestic brand volume concentration creates negotiating leverage unavailable to smaller regional handset makers.
eMMC Master Control Chip Market Segmentation
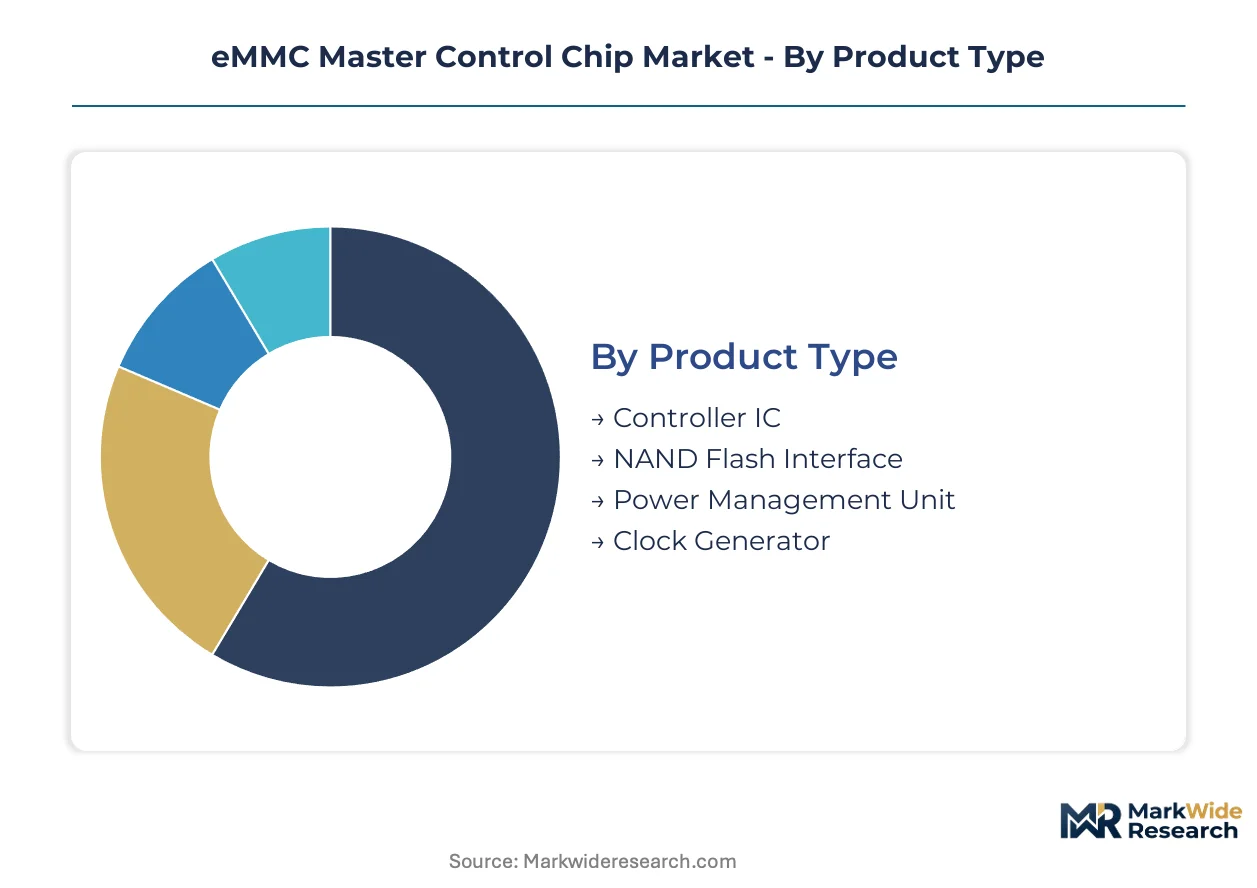
eMMC controller segmentation reveals how margin pools concentrate in firmware-differentiated silicon rather than commodity packaging. Understanding these splits exposes where captive NAND integration, advanced error-correction IP, and automotive qualification premiums command pricing power.
Product Type:
Controller IC products capture the deepest margin pools due to firmware IP barriers and LDPC algorithm differentiation that fabless vendors exploit.
- Controller IC:Integrates NAND flash management, wear-leveling algorithms, and host interface logic on 28nm to 40nm process nodes. Samsung Electronics and Silicon Motion Technology anchor demand in South Korea and Taiwan through captive and merchant supply respectively, constrained by foundry allocation scarcity at TSMC.
- NAND Flash Interface:Physical layer translators between raw NAND and controller logic, typically bundled or discrete depending on vertical integration strategy. Phison Electronics and domestic Chinese design houses are redirecting procurement toward local foundry partnerships under MIIT directives, forcing requalification timelines.
- Power Management Unit:Voltage regulators and sequencing circuits for multi-rail NAND operation.
- Clock Generator:Timing distribution circuits for synchronous NAND interfaces.
The dominant share belongs to Controller IC, while NAND Flash Interface is closing the gap fastest as direct OEM-foundry engagement displaces traditional module vendor channels.
Technology:
Package selection tracks directly to thickness constraints and thermal dissipation requirements across end-use form factors.
- Package on Package:Stacked memory-over-logic configuration dominates smartphone integration where Z-height budgets sit below 1.0mm. Xiaomi and OPPO procurement teams in Beijing and Shenzhen negotiate direct wafer supply with Phison and Silicon Motion, bypassing legacy module intermediaries.
- Wafer Level Chip Scale Package:Sub-0.4mm thickness capability serves fitness trackers and hearables in Dongguan manufacturing clusters. REACH substance restrictions on leadframe plating materials force substrate requalification across European-bound shipments.
- Ball Grid Array:Standard pitch configurations for industrial and automotive applications.
- Chip Scale Package:Mid-tier thickness solutions for tablets and portable media players.
Package on Package retains volume leadership, though Wafer Level Chip Scale Package is expanding most quickly as wearable form factors compress.
Application:
Automotive infotainment systems and industrial gateways are pulling controllers into reliability grades previously reserved for enterprise SSDs.
- Smartphones:Triple-level cell NAND management with adaptive voltage threshold tracking supplants older MLC firmware in 128GB and 256GB SKUs. ODMs in Dongguan and Shenzhen qualify these for mid-tier China-bound handsets, compressing margins for vendors lacking in-house LDPC IP.
- Wearable Electronics:Sub-0.4mm thickness specifications drive WLCSP adoption in fitness trackers and hearables. Extended temperature cycling requirements from factory automation integrators are emerging as a secondary demand node.
- Tablets:Larger form factor permits BGA and CSP configurations with relaxed thickness constraints.
- Portable Media Players:Cost-optimized PoP derivatives serving declining volume segments.
- Digital Cameras:Specialized controllers for burst-write buffering and power sequencing.
Smartphones command the installed base, yet Wearable Electronics is gaining share fastest as thickness constraints dominate engineering trade-offs.
End User Industry:
Procurement channel structure varies sharply between direct foundry engagement and traditional module vendor intermediation.
- Consumer Electronics Manufacturers:Smartphone OEMs in Beijing and Shenzhen negotiate controller wafer supply directly with Silicon Motion and Phison, displacing module vendor intermediation. This pattern concentrates in China where domestic brand volume creates negotiating leverage unavailable to smaller regional handset makers.
- Semiconductor Foundries:TSMC and GlobalFoundries allocate 28nm to 40nm capacity for controller tape-outs, with MIIT domestic sourcing directives redirecting flow toward indigenous design houses.
- Telecommunication Providers:Carrier-branded device procurement with standardized component sourcing.
- Embedded Systems Integrators:Industrial gateway and factory automation demand for -40°C to 105°C extended temperature grades.
Consumer Electronics Manufacturers hold the largest procurement volume, while Semiconductor Foundries is climbing the fastest as direct engagement reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for mature process nodes clusters in East Asian manufacturing basins. Samsung Electronics anchors South Korean output through captive NAND fabrication. Chinese design houses redirect tape-outs toward indigenous foundry partnerships under MIIT localization mandates.
South Korea
Automotive infotainment systems and smartphone OEM procurement drive controller demand. MFDS coordinates export control frameworks affecting advanced packaging equipment access. Hsinchu and Seoul host concentrated NAND flash physics expertise for firmware development.
China
Domestic smartphone brands negotiate direct wafer supply with controller vendors. MIIT mandates domestic semiconductor sourcing targets that reshape supply chain planning. Beijing and Shenzhen procurement teams bypass legacy module intermediaries for volume concentration leverage.
Taiwan
Merchant controller supply and foundry services anchor regional competitiveness. TSMC allocates 28nm to 40nm capacity for controller tape-outs with allocation scarcity extending lead times. Hsinchu clusters house LDPC algorithm development capabilities concentrated among fabless vendors.
Japan
Industrial IoT gateways pull eMMC controllers into extended temperature reliability grades. METI coordinates export control frameworks with South Korean counterparts on packaging equipment. Factory automation integrators in Nagoya and Osaka demand -40°C to 105°C qualified components.
United States
Automotive tier-1s mandate full material declaration transparency from controller vendors. EPA and OSHA frameworks govern semiconductor manufacturing facility compliance. Midwest automotive electronics clusters in Michigan and Ohio qualify AEC-Q100 compliant controllers for ECU integration.
eMMC Master Control Chip Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the eMMC controller market. Captive NAND fabricators consolidate supply-side control while merchant controller vendors compete through firmware differentiation. Three archetypes dominate: vertically integrated memory fabricators, fabless controller specialists, and turnkey solution providers. Competitive moves concentrate on strategic foundry partnerships and automotive qualification certification.
Among vertically integrated fabricators, Samsung Electronics exemplifies the captive supply archetype through in-house NAND production. SK Hynix occupies a position within the same tier, leveraging Korean manufacturing concentration. On the merchant controller vector, Phison Electronics and Silicon Motion Technology represent fabless specialists competing through firmware IP and direct OEM engagement.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| KIOXIA |
| Western Digital |
| SanDisk |
| Kingston Technology |
| Phison Electronics |
| Silicon Motion Technology |
| Others |
Pricing and Supply Chain Analysis
UFS interface substitution in flagship smartphones is compressing eMMC controller pricing into mid-tier and automotive segments while simultaneously concentrating procurement leverage among direct OEM-foundry negotiators in Beijing and Shenzhen. This displacement dynamic redraws margin pools away from volume mobile sockets toward firmware-differentiated automotive and industrial grades.
Pricing Analysis
MIIT domestic sourcing directives dictate the pricing tier structure across the Chinese procurement landscape. Three-tier pricing separates AEC-Q100 automotive-qualified controllers from industrial-grade and consumer-mobile variants, with ISO 26262 ASIL-B certification commanding substantial premiums. Cost compression in consumer-mobile tiers is intensifying because direct OEM-foundry engagement eliminates module vendor margin stacking. Smartphone OEMs in Dongguan manufacturing clusters exhibit the highest price sensitivity, while automotive tier-1s in Stuttgart and Munich demonstrate the lowest due to qualification switching costs.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and captive NAND supply for controller integration. The supply chain draws from 28nm to 40nm mature process nodes, NAND flash wafers from Korean and Taiwanese fabricators, and advanced packaging substrates from Japanese suppliers. Single-source vulnerability concentrates in TSMC foundry allocation scarcity for controller tape-outs. Distribution runs through direct OEM engagement channels displacing traditional module vendor intermediation, particularly for China-bound smartphone volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eMMC controller market sits in a cyclical recovery phase driven by automotive infotainment system upgrades replacing legacy storage architectures. Foundry capacity normalization and MIIT localization mandates are creating asymmetric opportunity windows across stakeholder archetypes.
For Market Incumbents: Fortify automotive qualification moats through accelerated AEC-Q100 certification investment before Chinese design houses achieve comparable reliability grades. Deepen captive NAND integration to defend margin position against merchant controller vendors lacking upstream wafer access. Prioritize firmware talent retention in Hsinchu and Seoul clusters where LDPC algorithm expertise concentrates.
For New Entrants and Emerging Players: Anchor in industrial edge computing segments requiring -40°C to 105°C extended temperature grades, where incumbent penetration remains shallow and qualification timelines create defensive barriers. Target factory automation integrators in Nagoya and Osaka with purpose-built controller firmware. Pursue foundry partnerships with GlobalFoundries to bypass TSMC allocation constraints affecting established competitors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that targets firmware-differentiated fabless specialists with automotive qualification pipelines. Long-term viability hinges on controller vendors escaping commodity mobile pricing through industrial and automotive grade diversification. Watch MIIT encryption approval timelines as the signal indicating indigenous Chinese controller competitiveness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Acceleration | AEC-Q100 certification opens ISO 26262 ASIL-B addressable volume for qualified suppliers. |
| Direct Foundry Partnership | Silicon Motion and Phison negotiate wafer supply directly with Xiaomi and OPPO procurement teams. |
| Firmware IP Acquisition | In-house LDPC algorithm ownership separates margin leaders from commodity controller vendors. |
| Extended Temperature Grade Development | -40°C to 105°C specifications capture factory automation gateway demand in Nagoya clusters. |
| Wafer Level Chip Scale Package Expansion | Sub-0.4mm thickness capability serves wearable electronics manufacturing in Dongguan. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Semiconductor design house executives, foundry account managers, automotive tier-1 procurement directors, smartphone OEM supply chain leads, and packaging substrate suppliers provided operational perspective. Secondary sources include MIIT directive documentation, MFDS export control frameworks, METI policy coordination records, AEC-Q100 qualification databases, and TSMC capacity allocation disclosures. Bottom-up controller shipment estimates triangulate against top-down NAND flash demand forecasts.
Sensitivity analysis around foundry capacity allocation scenarios shapes the projection framework across the analysis window. Segmentation dimensions span controller IC versus interface products, Package on Package versus Wafer Level Chip Scale Package formats, smartphone versus automotive versus wearable applications, and consumer electronics versus semiconductor foundry versus embedded systems integrator end users. CAGRs derive from shipment volume trajectories weighted by average selling price evolution across certification tiers. Forecast inputs incorporate MIIT localization compliance timelines and automotive infotainment system upgrade cycles.
Material uncertainties — foundry allocation reallocation, NAND flash supply disruption, and UFS substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and technology transition pacing. Recalibration cycles align with material shifts in MIIT directive implementation and automotive platform qualification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.