
 Europe Advanced Distribution Management System Market | 2026-2036
Europe Advanced Distribution Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced Distribution Management System Market Insights
Multi-source procurement of grid software is shifting toward integrated platform contracts across European utilities. Siemens AG leverages its hardware-software bundling to anchor large-scale DSO partnerships. Schneider Electric competes through open-architecture interoperability that reduces vendor lock-in. Hitachi Energy specializes in real-time network analytics for high-renewable penetration grids.
An Advanced Distribution Management System is a software platform that orchestrates electric distribution grid operations through real-time monitoring, fault detection, and automated switching with sub-second response parameters. It enables utilities to balance bidirectional power flows from rooftop solar, battery storage, and electric vehicle charging infrastructure. The outage management systems segment leads current deployments as storm resilience climbs the priority ladder for regulators and ratepayers. Cloud-based and software-as-a-service delivery models represent the fastest-expanding deployment channels, shrinking upfront capital barriers for mid-sized municipal utilities. Artificial intelligence and machine learning integrations are capturing margin pools by reducing non-technical losses and predictive maintenance costs.
The EU Green Deal, F-Gas Regulation, and CE marking frameworks collectively shape ADMS demand by mandating carbon-transparent grid operations and interoperable equipment standards. National regulators in Germany, France, and Italy transpose these directives into grid code amendments that require real-time visibility down to the low-voltage level. Stakeholders must monitor how the EU AI Act classification rules affect automated decision-making modules within outage restoration algorithms.
Market Dynamics
European distribution system operators face intensifying pressure to modernize grid orchestration software as distributed energy resource penetration crosses critical operational thresholds. The EU Green Deal's binding efficiency mandates and F-Gas Regulation compliance deadlines compress procurement cycles while expanding functional requirements for real-time network visibility.
Growth Catalysts
- EU Green Deal carbon transparency mandates:National grid codes in Germany, France, and Italy now require real-time emissions tracking down to low-voltage substations, forcing DSOs to deploy ADMS platforms with integrated carbon accounting modules.
- Storm resilience regulatory escalation:Regulators in storm-prone Nordic and Central European markets are tightening outage duration penalties, accelerating fault detection and automated switching investments.
- Rooftop solar saturation:Bidirectional power flow management has become operationally critical in markets where distributed photovoltaic penetration exceeds 15% of distribution feeder capacity.
Market Restraints
- Specialized engineering talent scarcity:Power systems software expertise concentrates among a narrow cohort of mid-career professionals, constraining deployment velocity for complex multi-feeder implementations.
- Legacy SCADA integration friction:Proprietary protocols in existing substation automation infrastructure create data interoperability barriers that extend implementation timelines.
- Long procurement cycles:Municipal and cooperative utilities operate under public procurement frameworks that stretch vendor selection and contracting phases across 18-24 month windows.
Strategic Opportunities
- Eastern European grid modernization:Polish and Romanian DSOs lag Western European ADMS penetration by approximately one technology generation, creating first-mover advantage windows for platform vendors with localized support infrastructure.
- EU AI Act algorithmic transparency requirements:Automated outage restoration decision modules will require explainability certifications, opening specialized compliance service revenue streams.
- Cloud-native SaaS delivery models:Mid-sized municipal utilities in Italy and Spain are bypassing on-premise capital expenditure barriers through subscription-based platform access.
Industry Challenges
- Cybersecurity certification complexity:CE marking combined with national critical infrastructure protection frameworks creates overlapping compliance obligations that delay product release schedules.
- Interoperability standard fragmentation:Divergent national implementations of IEC 61968 and 61970 standards force vendors to maintain multiple integration codebases, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced Distribution Management System Market |
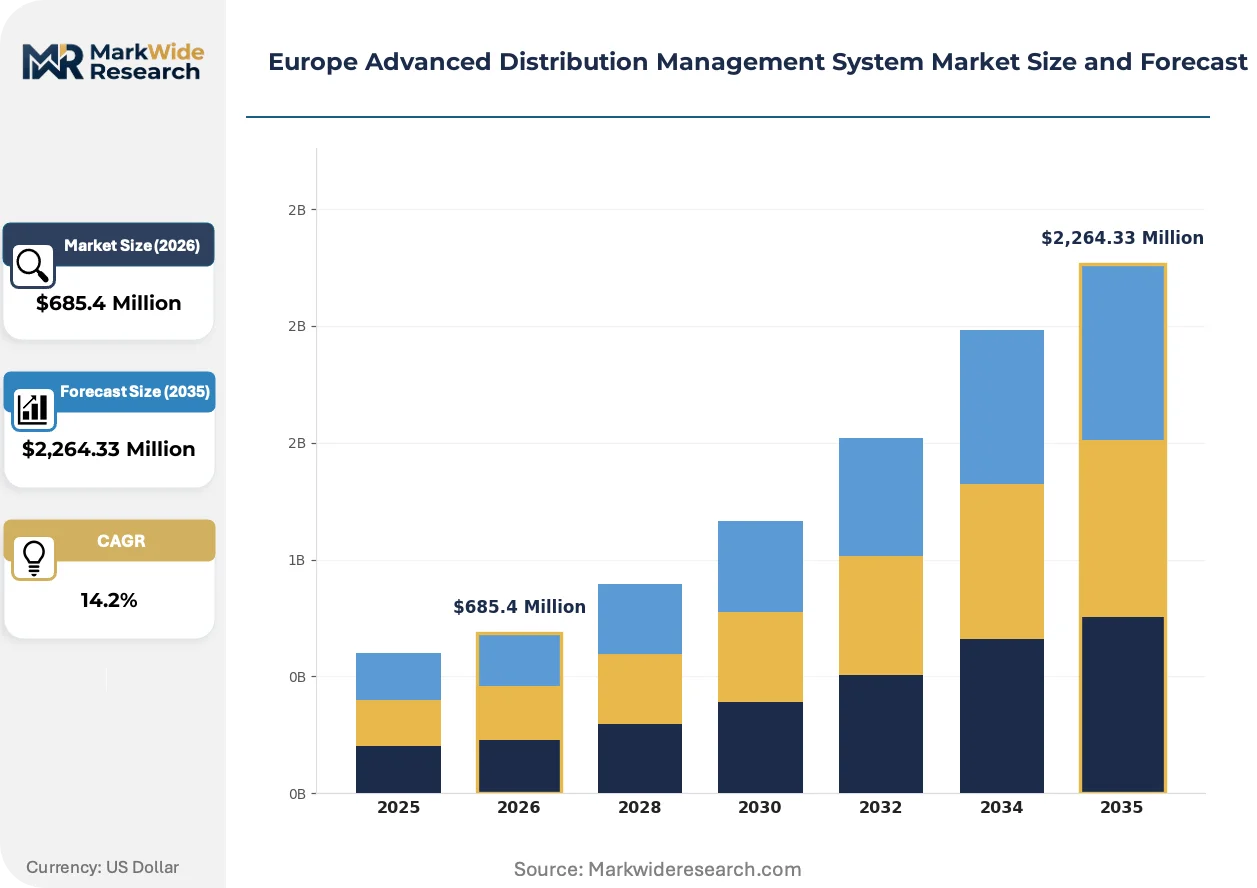
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management Systems, Network Management Systems, Outage Management Systems, Advanced Metering Infrastructure End User: Utilities, Industrial Manufacturers, Commercial Enterprises, Residential Consumers Deployment: On-Premise, Cloud-Based, Hybrid Systems, Software as a Service Technology: Artificial Intelligence, Internet of Things, Big Data Analytics, Machine Learning |
| Companies Covered | Siemens AG, Schneider Electric, General Electric, Hitachi Energy, Eaton Corporation, Oracle Corporation, Landis+Gyr Group, Itron, ABB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced Distribution Management System Market Trends and Innovations
Artificial intelligence integration is redefining core ADMS functionality beyond traditional supervisory control, embedding predictive capabilities directly into grid orchestration workflows. Three convergent developments are compressing the technology refresh cycle across European utilities.
Machine learning-based predictive maintenance algorithms are expanding into distribution transformer monitoring and cable thermal rating applications. German and Dutch DSOs with high offshore wind interconnection volumes are deploying these modules to pre-emptively identify insulation degradation patterns. The technology is expanding into margin capture by reducing unplanned outage costs and extending asset replacement intervals.
F-Gas Regulation phase-down schedules are forcing refrigerant-dependent grid equipment replacements that coincide with ADMS upgrade windows. The regulation's 2030 reduction targets accelerate synchronized procurement of switchgear and orchestration software. High-voltage distribution segments in France and Belgium face the most compressed compliance timelines.
Consolidated platform procurement is displacing multi-vendor software stacks as DSOs prioritize single-contract accountability for grid digitization outcomes. Integrated hardware-software bundles are capturing preference share among risk-averse municipal utilities. This pattern is most visible in German Energiewende acceleration zones where project complexity demands unified vendor responsibility.
Europe Advanced Distribution Management System Market Segmentation
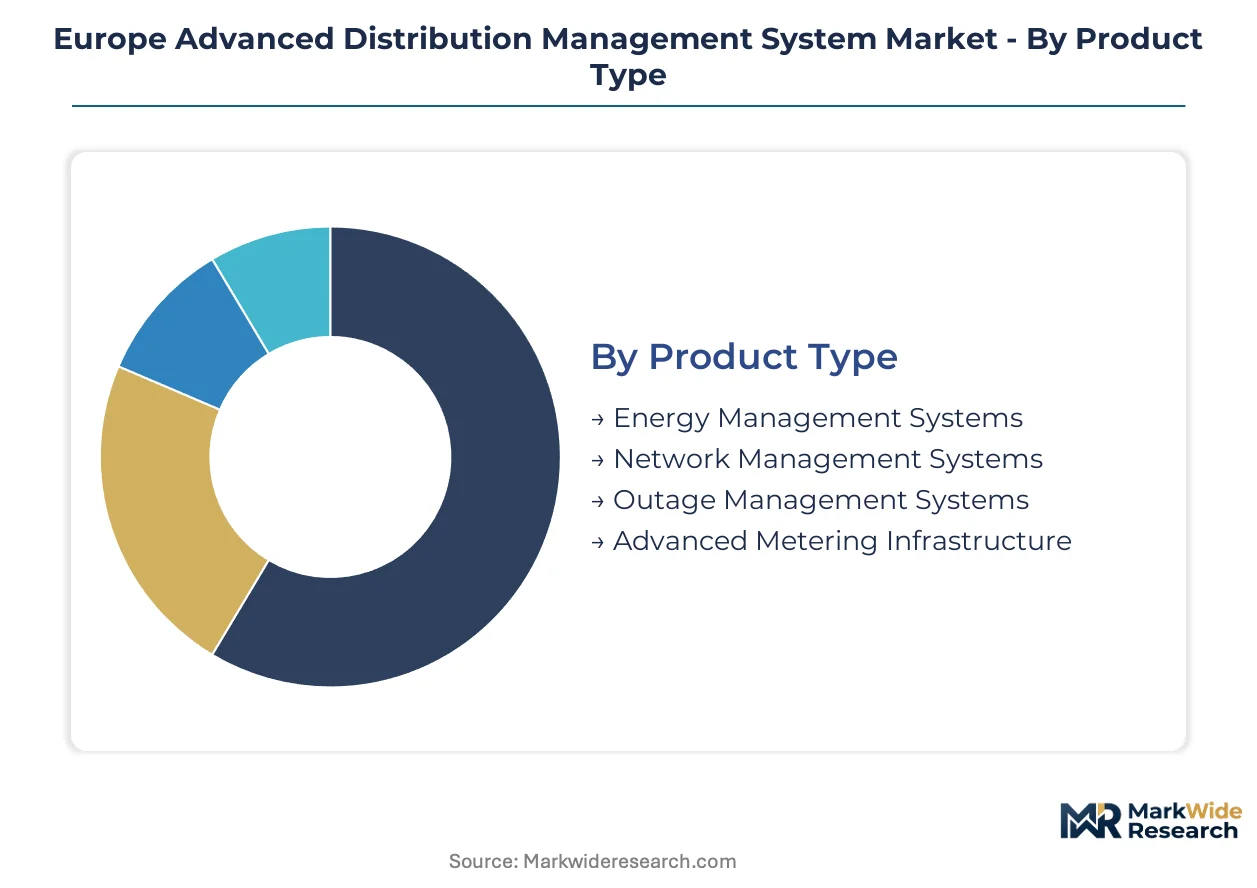
ADMS procurement patterns across Europe diverge sharply by integration depth and operational maturity. German and French utilities prioritize unified platforms that collapse multiple functional domains into single vendor contracts, while Eastern European operators still acquire point solutions for immediate compliance deadlines.
Product Type:
Standalone modules address narrow functional gaps in legacy infrastructure, whereas embedded systems integrate across SCADA, GIS, and DERMS layers for unified grid orchestration.
- Outage Management Systems:Real-time fault detection algorithms coordinate automated switching sequences with sub-second response parameters. Storm-prone Nordic utilities in Norway and Sweden deploy these modules most aggressively as regulators tighten SAIDI penalty frameworks.
- Network Management Systems:Topology processors and state estimators enable dynamic load flow calculations across meshed distribution networks. Dutch DSOs with high offshore wind interconnection volumes lead adoption for managing bidirectional power flows.
- Energy Management Systems:Dispatch optimization engines balance distributed generation against demand response signals.
- Advanced Metering Infrastructure:AMI headend systems feed consumption data into ADMS analytics layers for load forecasting refinement.
Outage Management Systems lead volumes today; Network Management Systems is gaining share fastest.
End User:
Cost tier stratification separates capital-rich national transmission operators from municipal utilities constrained by public procurement frameworks.
- Utilities:Distribution system operators command the largest procurement budgets, bundling ADMS with substation automation hardware under unified capital programs. German Energiewende zones concentrate the highest deployment density.
- Industrial Manufacturers:Captive microgrid operators at chemical and automotive plants purchase scaled-down ADMS licenses for islanding capability during grid disturbances.
- Commercial Enterprises:Data center operators and retail chains deploy limited-functionality platforms for behind-the-meter DER optimization.
- Residential Consumers:Aggregator-managed virtual power plants represent an emerging demand channel through third-party platform access.
Utilities dominate capital deployment; Industrial Manufacturers represent the steepest expansion trajectory among non-utility segments.
Deployment:
Delivery model selection tracks organizational IT maturity and balance sheet capacity, with subscription models penetrating mid-tier municipal operators.
- Cloud-Based:Scalable compute resources support machine learning model training without on-premise infrastructure investment. Italian and Spanish municipal utilities bypass capital expenditure barriers through this channel.
- Software as a Service:Fully managed platform instances shift operational responsibility to vendors. Polish DSOs entering first-generation ADMS procurement favor this model for risk transfer.
- On-Premise:Air-gapped installations persist in critical infrastructure protection contexts.
- Hybrid Systems:Split architectures keep control functions local while pushing analytics to cloud environments.
On-Premise retains share among security-sensitive operators; Cloud-Based is climbing the fastest as cybersecurity certification pathways mature.
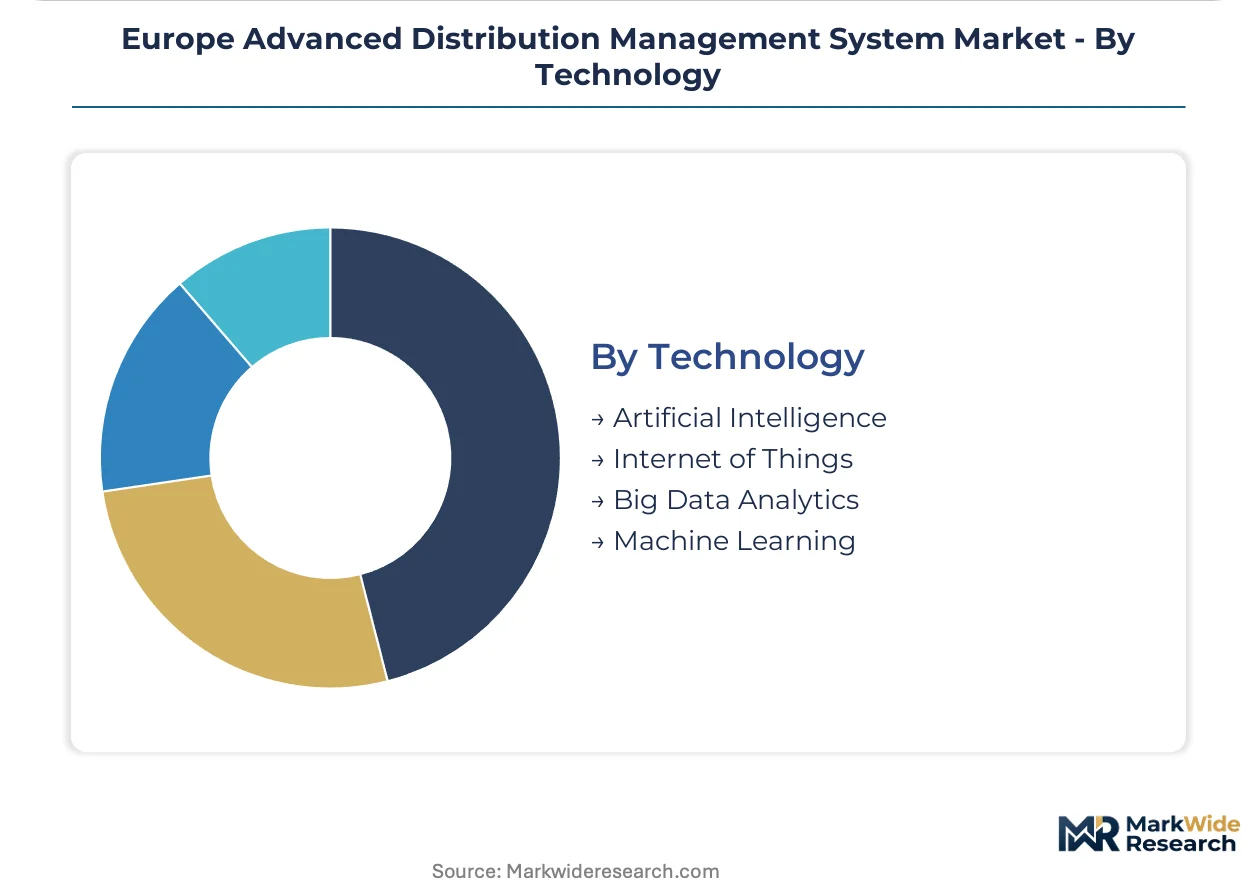
Technology:
Functional embedding depth separates surface-level dashboarding from predictive algorithms that automate switching decisions.
- Machine Learning:Predictive maintenance models identify transformer insulation degradation patterns before thermal runaway. German DSOs with aging distribution infrastructure deploy these modules for asset replacement interval extension.
- Artificial Intelligence:Automated outage restoration algorithms must now satisfy EU AI Act explainability requirements for high-risk system classifications.
- Internet of Things:Sensor fusion from smart meters, fault indicators, and environmental monitors feeds real-time network state estimation.
- Big Data Analytics:Historical load pattern mining supports long-term capacity planning and non-technical loss detection.
Internet of Things anchors current deployment volumes; Machine Learning is expanding most quickly as algorithmic transparency frameworks stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping ADMS deployment patterns as utilities migrate procurement priorities toward jurisdictions with accelerated grid-code enforcement. Cost-of-compliance gaps between Western and Eastern European markets are compressing as the EU Green Deal harmonizes carbon-transparency mandates across member states.
Germany
Energiewende acceleration zones in Bavaria and North Rhine-Westphalia drive substation modernization at scale. The national grid code now mandates real-time low-voltage visibility under transposed EU Green Deal directives. Munich-based DSOs bundle ADMS with switchgear replacements to satisfy F-Gas Regulation phase-down timelines.
France
Offshore wind interconnection volumes in Brittany and Normandy necessitate dynamic load flow management. The country's national energy regulator enforces storm-resilience penalties that tighten SAIDI thresholds. Paris-region utilities consolidate procurement around unified hardware-software platforms to reduce vendor fragmentation.
Netherlands
High rooftop solar penetration in Randstad urban corridors creates bidirectional power flow complexity. The Dutch national grid code requires carbon-accounting modules at distribution substations. Rotterdam-area DSOs deploy predictive maintenance algorithms for cable thermal rating in offshore wind zones.
Italy
Municipal utilities in Lombardy and Veneto bypass capital expenditure barriers through cloud-native SaaS delivery models. The national transposition of EU AI Act requirements shapes automated outage restoration procurement. Milan-based operators favor subscription platforms to transfer operational risk.
Poland
First-generation ADMS procurement in Masovian and Silesian Voivodeships lags Western European deployment by one technology generation. The country's national grid modernization program accelerates under EU cohesion funding. Warsaw-area DSOs prioritize fully managed platform instances for risk mitigation.
Europe Advanced Distribution Management System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery and AI-enabled analytics modules. The vendor landscape concentrates around integrated platform specialists and point-solution modularists. Three archetypes dominate: hardware-software bundlers, open-architecture interoperability providers, and real-time analytics specialists. Competitive moves center on consolidated procurement contract capture and SaaS delivery model expansion.
Within the hardware-software bundler tier, Siemens AG and ABB exemplify integrated platform positioning. Schneider Electric occupies a position among open-architecture specialists. Hitachi Energy anchors the real-time network analytics segment. These three represent divergent strategic postures toward vendor lock-in reduction, unified accountability, and high-renewable grid specialization.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| General Electric |
| Hitachi Energy |
| Eaton Corporation |
| Oracle Corporation |
| Landis+Gyr Group |
| Itron |
| ABB |
| Others |
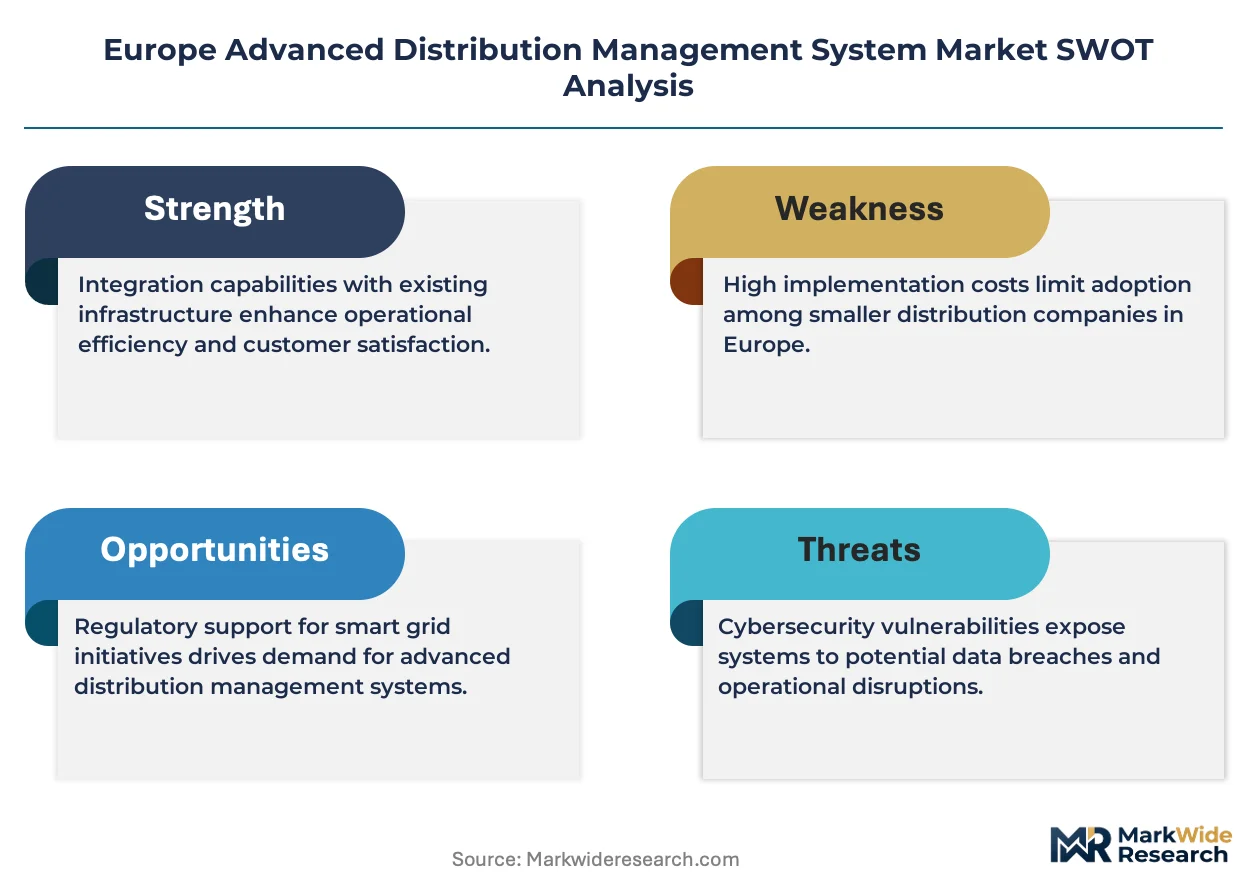
Pricing and Supply Chain Analysis
Hardware-software bundling by German and French platform vendors anchors supply positions while compressing pricing power for standalone software specialists. This integration pattern concentrates procurement leverage among DSOs demanding unified accountability, forcing modularists toward SaaS delivery to escape margin erosion.
Pricing Analysis
Distributor margins for on-premise ADMS implementations absorb 15-25% of project value before reaching municipal utilities. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG's bundled enterprise suites from Schneider Electric's interoperability modules and Polish SaaS entrants. Pricing pressure stems from cloud-native subscription models that bypass capital expenditure barriers for mid-tier Italian and Spanish operators. Municipal utilities in Eastern Europe exhibit highest price sensitivity due to EU cohesion funding constraints, while German Energiewende zones tolerate premium positioning for F-Gas Regulation compliance bundling.
Supply Chain Analysis
EU Green Deal domestic-content mandates for carbon-transparent grid equipment are reshaping sourcing toward localized switchgear manufacturing in Germany, France, and Italy. ADMS software development draws from Indian engineering centers for algorithmic modules, German industrial software clusters for SCADA integration layers, and US cloud infrastructure for SaaS hosting. Single-source vulnerability concentrates in specialized power systems engineering talent pools constraining deployment velocity. Distribution runs through direct vendor-DSO relationships for enterprise implementations, with channel partners penetrating mid-sized municipal utilities in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate where Polish and Romanian DSOs face compressed procurement timelines against Western European F-Gas Regulation compliance deadlines, widening acceptable price-quality tradeoffs for first-generation ADMS platforms.
For Market Incumbents: Lock in long-term service contracts with German Energiewende zone DSOs before F-Gas Regulation phase-down windows close. Consolidate predictive maintenance algorithm portfolios through targeted capability acquisitions to defend against cloud-native entrants offering AI-enabled analytics without legacy integration burdens. Prioritize CE marking cybersecurity certification investments to extend compliance moats. For New Entrants and Emerging Players: Municipal utility cooperatives in Poland and Romania represent the most penetrable buyer segment, with 18-24 month procurement cycles creating first-mover windows before Western vendors establish localized support infrastructure. Cloud-native SaaS delivery bypasses capital barriers that exclude mid-tier Italian operators from on-premise competition. Partner with regional system integrators possessing existing SCADA relationships to accelerate trust formation. For Investors and Strategic Acquirers: Consolidation pressure builds where algorithmic transparency requirements under the EU AI Act fragment compliance capabilities across sub-scale vendors. Long-term viability favors platforms with embedded carbon-accounting modules and explainable outage restoration algorithms. Watch for inflection when German grid code amendments mandate real-time low-voltage visibility thresholds that obsolete first-generation deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified ADMS-DERMS-SCADA contracts capture preference share from risk-averse German municipal utilities. |
| Cloud-Native SaaS Expansion | Subscription delivery bypasses capital barriers for Italian and Spanish mid-tier DSOs. |
| AI Act Compliance Certification | Explainable algorithm credentials open specialized service revenue streams for outage restoration modules. |
| Backward Integration into Switchgear | Synchronized F-Gas Regulation procurement windows bundle hardware replacement with software upgrades. |
| Eastern European Localization | Polish and Romanian support infrastructure captures first-generation ADMS demand under EU cohesion funding. |
Research Methodology
Coverage spans Germany, France, Italy, Netherlands, Poland, and Romania, with primary inputs from each market's distribution system operator planning officers, grid automation procurement leads, substation integration engineers, and regulatory compliance specialists. Secondary validation draws from EU Green Deal directive texts, F-Gas Regulation implementation schedules, national grid code amendments, and CE marking cybersecurity framework documentation. Bottom-up deployment tracking triangulates against top-down utility capital expenditure disclosures.
Rate-of-change decomposition separates baseline grid modernization investment from incremental ADMS penetration acceleration across the analysis window. Segmentation dimensions modeled include deployment model, utility scale tier, integration complexity depth, renewable penetration level, and regional regulatory enforcement intensity. CAGRs derive from utility-reported project pipelines and vendor order backlogs, with machine learning module adoption curves and SaaS subscription conversion rates as industry-specific forecast inputs.
Revisions become necessary when EU AI Act enforcement timelines accelerate, F-Gas Regulation phase-down schedules shift, or cybersecurity certification pathways fragment across member state implementations. Forecasts reflect documented assumptions regarding DSO procurement cycle durations and cloud migration willingness thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
IoT Smart Gas Meter Market