
 Nonwoven Cleanroom Apparel Market | 2026-2036
Nonwoven Cleanroom Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Cleanroom Apparel Market Intelligence
Cleanroom garment technician availability is bifurcating the competitive landscape, as advanced ISO Class 5 manufacturing demands specialized laminating and sealing expertise that remains scarce outside established hubs. DuPont leverages its Tyvek and ProShield material portfolios to anchor premium positioning in pharmaceutical and biotechnology end users. Berkshire Corporation specializes in vertically integrated US-based production of polyester cleanroom fabrics, sustaining consistent supply to domestic semiconductor fabs. Ansell Limited competes through its controlled environment solutions division, extending global reach across electronics manufacturing corridors in Taiwan and South Korea.
Nonwoven cleanroom apparel comprises engineered fabric garments—typically spunbond polypropylene, meltblown composites, or spunbond-meltblown-spunbond (SMS) laminates with basis weights of 40–65 gsm—designed to barrier human-borne particulates from controlled environments. These garments achieve filtration efficiencies exceeding 95% for particles 0.5 microns and larger, serving as critical contamination control in pharmaceutical aseptic processing, semiconductor lithography, and biotechnology sterile operations. Coveralls dominate product type value pools due to their surface area and multi-layer construction requirements, while gloves represent the highest unit-volume segment with thinner-gauge nitrile and vinyl alternatives pressuring polypropylene margins. Material selection is concentrating in spunbond-meltblown composites for ISO Class 5 applications, where polyester substrates command premium positioning over standard polypropylene in biotechnology cleanrooms.
FDA sterile manufacturing guidance, EU MDR Annex I general safety requirements, and ISO 14644 cleanroom classification standards collectively elevate barrier performance thresholds and documentation burdens for apparel suppliers. The EPA's evolving particulate emissions frameworks indirectly shape nonwoven manufacturing processes, pushing producers toward lower-energy bonding technologies. Stakeholders must monitor how FDA's quality metrics program and the EU's forthcoming revision to its GMP Annex 1 will redefine acceptable garment testing protocols before committing capital to capacity expansion.
Market Dynamics
Semiconductor node shrinkage below 3nm is compressing acceptable particulate thresholds, forcing fabricators to abandon standard polypropylene for multilayer spunbond-meltblown composites that demand scarce laminating expertise concentrated in East Asian manufacturing hubs.
Growth Catalysts
- EU MDR Annex I requirements:Sterile manufacturing guidance tightens particulate standards for pharmaceutical cleanrooms, compelling material upgrades across European aseptic processing facilities.
- Taiwan semiconductor corridor expansion:Domestic foundries in Hsinchu and Tainan Science Parks are scaling ISO Class 5 garment procurement as advanced lithography ramps.
- Spunbond-meltblown composite adoption:Filtration efficiency gains exceeding 95% for 0.5-micron particles are pulling demand from biotechnology sterile operations into semiconductor fabs.
Market Restraints
- Specialized laminating equipment scarcity:SMS composite production requires thermal bonding calenders concentrated among Korean and Japanese machinery suppliers, creating capacity bottlenecks.
- Polypropylene feedstock volatility:Propylene monomer price swings tied to naphtha cracking economics compress margins for standard-grade garment producers.
- ISO 14644-1 certification timelines:Extended validation periods for cleanroom garment testing protocols delay new supplier qualification by 12-18 months.
Strategic Opportunities
- Chinese domestic foundry buildout:Yangtze Memory Technologies and SMIC are expanding captive cleanroom apparel consumption as localization targets harden.
- Biotechnology CDMO channel penetration:Contract development and manufacturing organizations represent underpenetrated demand for polyester-substrate premium garments.
- Reusable garment service models:Industrial laundry networks in Germany and Switzerland are piloting rental-plus-processing contracts that displace disposable unit purchasing.
Industry Challenges
- Seam-sealing technician scarcity:Heat-tape application expertise for ISO Class 5 coveralls remains concentrated among veteran operators in South Korean and Taiwanese contract manufacturers.
- Legacy polypropylene inventory stranding:Semiconductor fabs holding standard-grade garment stocks face accelerated obsolescence as node migration compresses allowable particle counts.
- Cross-border qualification reciprocity gaps:FDA and EMA testing protocol misalignment forces redundant garment validation for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Cleanroom Apparel Market |
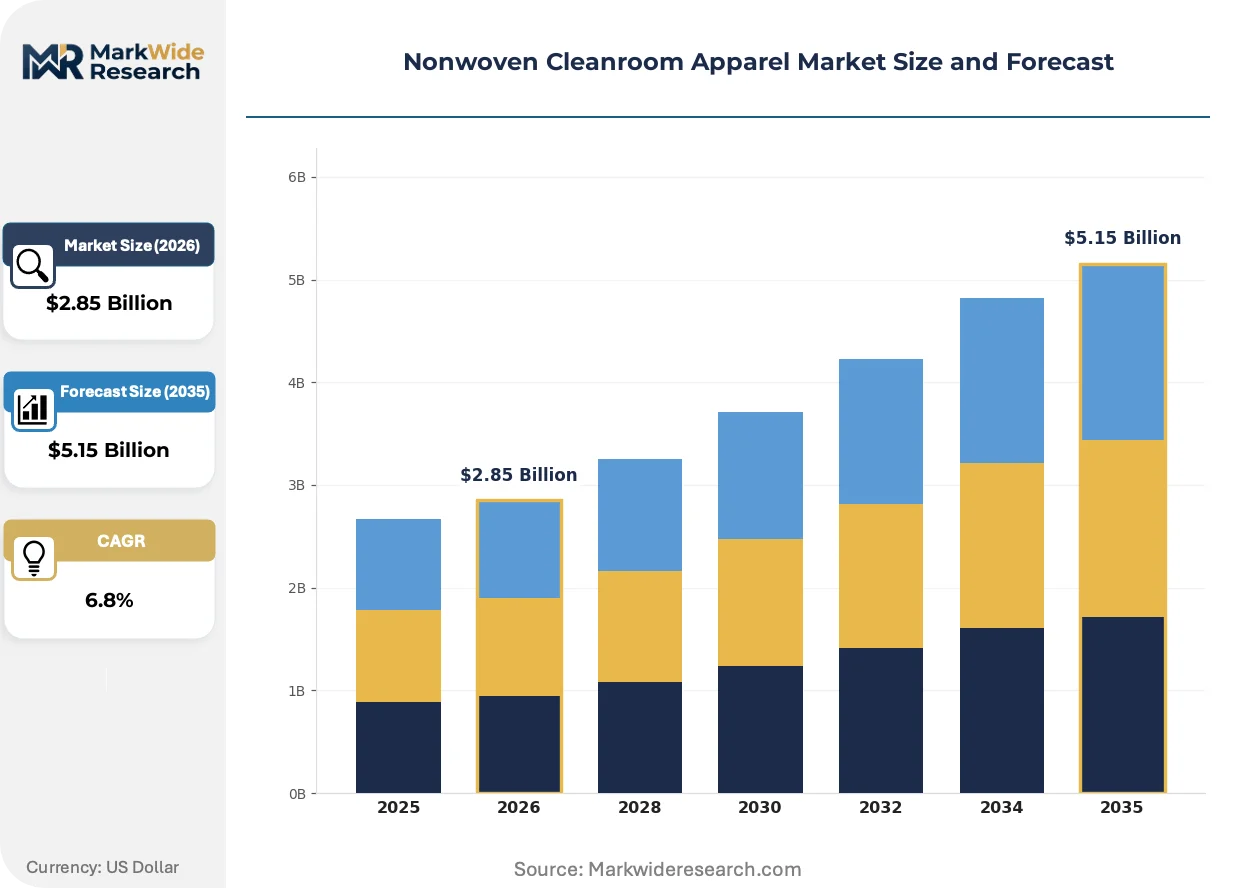
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Hoods, Gloves, Shoe Covers Material: Polypropylene, Polyester, Nylon, Vinyl End User: Pharmaceuticals, Biotechnology, Electronics, Food Processing Application: ISO Class 5, ISO Class 6, ISO Class 7, ISO Class 8 |
| Companies Covered | Kimberly-Clark Corporation, DuPont, Berkshire Corporation, Ansell Limited, 3M Company, Dynarex Corporation, Connect 2 Cleanrooms Ltd., Clean Air Products, Valutek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Cleanroom Apparel Market Strategic Shifts & Innovations
Material science convergence with regulatory pressure is fragmenting the competitive landscape into technology-tiered supplier tiers, with composite laminators separating from commodity polypropylene converters.
Spunbond-meltblown-spunbond (SMS) laminates with basis weights of 55-65 gsm are displacing standard 40 gsm polypropylene coveralls in semiconductor lithography bays. TSMC and Samsung Foundry have mandated SMS construction for all ISO Class 5 personnel garments since 2024. This displacement is compressing margins for single-layer converters while concentrating value capture among Korean and Japanese composite specialists with captive meltblown capacity.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing European pharmaceutical cleanroom operators to eliminate fluorinated fabric treatments from barrier garments. ECHA's 2023 restriction proposal targets water-repellent chemistries common in polyester cleanroom fabrics. German and Swiss biotechnology clusters are accelerating qualification of silicone-based alternatives, with BASF and Wacker Chemie scaling fluorine-free finishing agent production.
Direct mill-to-fab procurement contracts are displacing distributor-mediated purchasing for high-volume semiconductor garment consumers. TSMC's Central Procurement Organization now sources coveralls through single-source agreements with Korean textile laminators, bypassing traditional cleanroom supply houses. This channel compression is most visible in Taiwan and South Korea, where foundry concentration enables volume aggregation that smaller European pharmaceutical buyers cannot replicate.
Nonwoven Cleanroom Apparel Market Segmentation
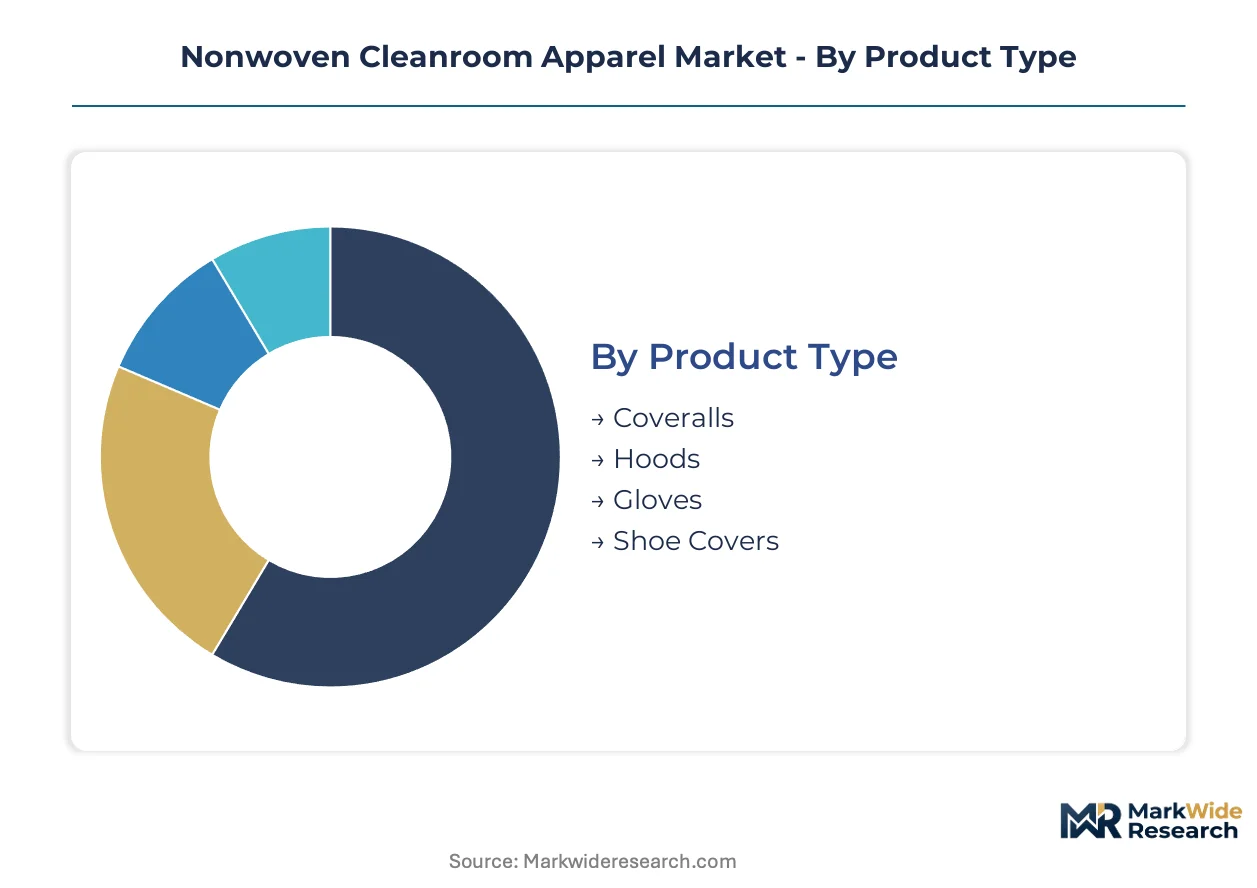
Cleanroom apparel segmentation reveals how material specifications and certification tiers fragment procurement patterns across semiconductor and pharmaceutical end users. Node shrinkage below 3nm and EU MDR tightening are compressing acceptable segments while elevating premium material grades.
Product Type:
Margin pools concentrate in garments with the largest surface area and most complex seam-sealing requirements, where ISO Class 5 certification commands substantial premiums over lower-grade alternatives.
- Coveralls:Full-body garments constructed from 55-65 gsm SMS laminates with heat-taped seams achieve filtration efficiencies exceeding 95% for 0.5-micron particles. TSMC and Samsung Foundry procurement concentrates in Hsinchu and Tainan Science Parks as advanced lithography ramps mandate multilayer composite construction.
- Gloves:Nitrile and vinyl alternatives with thinner-gauge construction dominate unit volumes but compress polypropylene margins through substitution pressure. Electronics manufacturing corridors in Taiwan and South Korea drive qualification of silicone-based alternatives as REACH PFAS restrictions eliminate fluorinated treatments.
- Hoods:Head and neck coverage garments integrate with coverall systems in biotechnology sterile operations.
- Shoe Covers:Disposable polypropylene footwear barriers serve lower-grade ISO Class 7-8 environments with minimal seam complexity.
The dominant share belongs to Coveralls, while Gloves is closing the gap fastest through volume expansion in electronics corridors.
Material:
Cost tier stratification separates commodity converters from composite laminators as semiconductor fabs abandon standard grades for multilayer constructions.
- Polypropylene:Single-layer spunbond fabrics with 40 gsm basis weights face accelerated obsolescence as node migration compresses allowable particle counts. Legacy inventory stranding threatens standard-grade garment stocks held by fabs transitioning to sub-3nm processes.
- Polyester:Premium substrates command positioning in biotechnology cleanrooms where ECHA PFAS restrictions force qualification of fluorine-free finishing agents from BASF and Wacker Chemie. German and Swiss CDMO channels represent underpenetrated demand for polyester-substrate garments.
- Nylon:Alternative synthetic fiber with higher tensile strength serves specialized mechanical protection applications.
- Vinyl:Cost-competitive barrier material pressures polypropylene margins in glove segments.
Spunbond-meltblown composites are displacing single-layer alternatives fastest, while polyester gains share in pharmaceutical applications.
End User:
Application maturity varies sharply across sectors, with semiconductor procurement consolidating through direct mill-to-fab contracts while pharmaceutical channels retain distributor mediation.
- Electronics:Semiconductor fabs in Taiwan and South Korea anchor demand for ISO Class 5 garments as TSMC's Central Procurement Organization sources coveralls through single-source Korean textile laminator agreements, bypassing traditional supply houses.
- Pharmaceuticals:European aseptic processing facilities face EU MDR Annex I particulate standard tightening that compels material upgrades from standard polypropylene to multilayer composites.
- Biotechnology:Sterile operations pull SMS laminate demand from pharmaceutical applications, with CDMO channels accelerating polyester qualification.
- Food Processing:Lower-grade ISO Class 7-8 applications sustain commodity polypropylene consumption with minimal barrier performance requirements.
Electronics holds the dominant procurement volume, though Pharmaceuticals is expanding most quickly through regulatory-forced material upgrades.
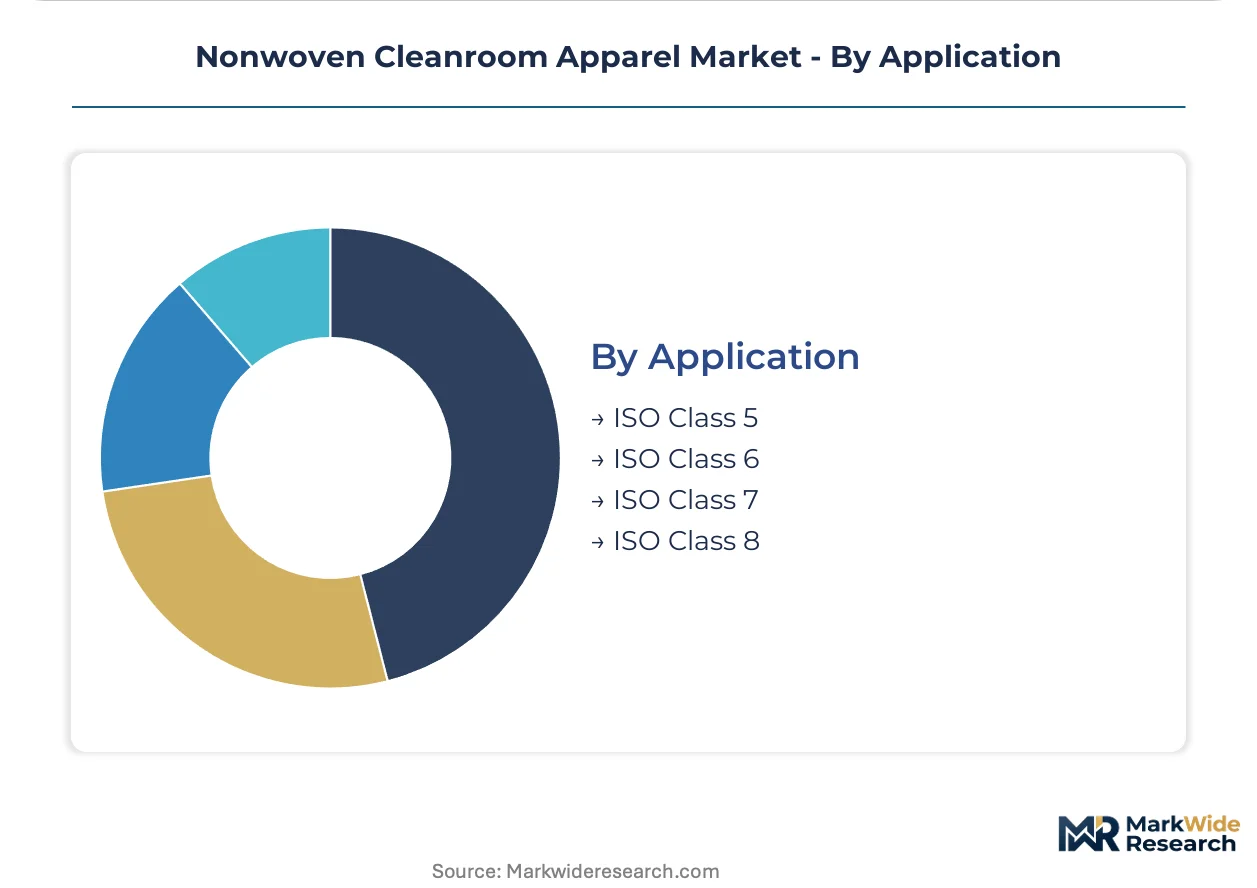
Application:
Certification tier directly determines supplier qualification timelines and seam-sealing expertise requirements, with ISO 14644-1 validation periods extending 12-18 months for new entrants.
- ISO Class 5:Stringent particulate thresholds below 3,520 particles per cubic meter at 0.5 microns demand multilayer spunbond-meltblown-spunbond laminates with thermal bonding calender production concentrated among Korean and Japanese machinery suppliers.
- ISO Class 6:Intermediate cleanliness requirements accommodate some standard polypropylene garments in transitional fab zones.
- ISO Class 7:Reduced barrier specifications serve support areas with lower laminating expertise demands.
- ISO Class 8:Minimal contamination control permits commodity-grade polypropylene across all garment types.
ISO Class 5 captures the steepest expansion trajectory, while ISO Class 8 retains volume leadership in cost-sensitive food processing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics corridors consume ISO Class 5 garments at intensities unmatched elsewhere, while European pharmaceutical clusters drive premium polyester qualification under REACH pressure. This geographic split shapes divergent procurement patterns across the analysis window.
United States
FDA sterile manufacturing guidance and EPA particulate frameworks elevate barrier documentation burdens for domestic suppliers. Berkshire Corporation's vertically integrated polyester production anchors supply to domestic semiconductor fabs in Arizona and Texas. Greater Phoenix and Austin-San Antonio corridors concentrate foundry garment demand as Intel and Samsung expand captive consumption.
Taiwan
TSMC's Central Procurement Organization sources coveralls through direct mill agreements, bypassing traditional supply houses. The island's national semiconductor strategy accelerates ISO Class 5 garment scaling across Hsinchu and Tainan Science Parks. Tainan cluster procurement concentrates among Korean textile laminators with captive meltblown capacity.
South Korea
Samsung Foundry mandates SMS construction for all ISO Class 5 personnel garments since 2024. MFDS alignment with FDA testing protocols streamlines qualification for exporters serving both markets. Seoul-Pyeongtaek corridor demand concentrates among domestic composite specialists with thermal bonding calender production.
China
Yangtze Memory Technologies and SMIC expand captive cleanroom apparel consumption as localization targets harden. NMPA sterile manufacturing standards tighten particulate thresholds for domestic pharmaceutical facilities. Yangtze River Delta foundry clusters pull multilayer composite demand from Korean and Japanese machinery suppliers.
Germany
ECHA REACH restrictions on PFAS force qualification of silicone-based fabric treatments across biotechnology cleanrooms. EU MDR Annex I particulate standards compel material upgrades from standard polypropylene to multilayer composites. Rhine-Main and Munich biotech clusters accelerate polyester-substrate garment adoption through CDMO channels.
Nonwoven Cleanroom Apparel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with material science capabilities fragmenting competitive positioning across certification grades. Korean and Japanese composite laminators capture premium ISO Class 5 value pools through captive meltblown capacity, while commodity polypropylene converters face margin compression. Three archetypes dominate: integrated material-laminator hybrids, regional garment assemblers, and distributor-mediated service providers. Capacity expansion and direct mill-to-fab procurement contracts represent the dominant competitive moves reshaping channel structures.
Among North American material specialists, DuPont and Berkshire Corporation occupy positions anchoring premium polyester supply to domestic pharmaceutical and semiconductor end users. Ansell Limited exemplifies the controlled-environment solutions archetype extending reach across East Asian electronics manufacturing corridors. These three companies represent the tier separating composite laminators from commodity converters as node shrinkage and regulatory tightening elevate technical barriers.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| DuPont |
| Berkshire Corporation |
| Ansell Limited |
| 3M Company |
| Dynarex Corporation |
| Connect 2 Cleanrooms Ltd. |
| Clean Air Products |
| Valutek Inc. |
| Others |
Cost & Logistics Intelligence
ISO 14644-1 certification timelines gate both supplier qualification and price differentiation simultaneously, as extended validation periods concentrate purchasing power among established composite laminators while compressing margins for commodity converters unable to absorb 12-18 month testing delays.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-volume semiconductor fabs, with TSMC's Central Procurement Organization negotiating single-source agreements that bypass traditional supply houses entirely. Price differentiation rests on certification tier and captive meltblown capacity, with ISO Class 5 garments commanding substantial premiums over lower-grade alternatives. Cost compression in standard polypropylene intensifies because semiconductor node migration below 3nm accelerates obsolescence of single-layer constructions. Biotechnology CDMOs exhibit highest price sensitivity due to fragmented purchasing volumes, while foundry direct procurement demonstrates lowest sensitivity through volume aggregation.
Supply Chain Analysis
Port congestion on Busan-Kaohsiung trade lanes elevates inbound logistics costs for Korean textile laminators serving Taiwanese foundry clusters. Geographic supply concentrates in South Korea, Japan, and Taiwan, where thermal bonding calender production anchors composite manufacturing. Raw material dependencies draw from propylene monomer feedstocks, meltblown polypropylene resins, and silicone-based finishing agents. Single-source vulnerability runs through Korean and Japanese machinery suppliers controlling SMS composite equipment. Distribution runs through direct mill-to-fab contracts displacing traditional cleanroom supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom apparel procurement is shifting toward platform-economics dynamics as direct mill-to-fab contracts create interoperability standards that lock in supplier ecosystems and fragment distributor-mediated channels.
For Market Incumbents: Compound defensive positioning by securing captive meltblown capacity in Korean and Japanese manufacturing hubs before equipment lead times extend further. Deepen backward integration into thermal bonding calender production to isolate margin compression from machinery supplier bottlenecks. Lock in long-term offtake agreements with TSMC and Samsung Foundry procurement organizations to preempt emerging composite laminators from qualifying through extended ISO 14644-1 validation windows.
For New Entrants and Emerging Players: Anchor in biotechnology CDMO channels across German and Swiss clusters, where polyester-substrate garment demand remains underpenetrated and procurement fragmentation prevents volume aggregation. Target silicone-based fabric finishing qualifications as ECHA REACH restrictions eliminate fluorinated treatments from European pharmaceutical cleanrooms. Pursue qualification partnerships with BASF and Wacker Chemie to accelerate regulatory approval pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across spunbond-meltblown composite manufacturing as thermal bonding calender scarcity elevates equipment costs and extends payback periods. Prioritize acquisition targets with existing ISO Class 5 certification and established relationships with Korean or Japanese machinery suppliers. Monitor MFDS-FDA testing protocol alignment as signal for cross-border qualification reciprocity improvements that would unlock dual-market revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Meltblown Capacity Expansion | Korean and Japanese composite specialists capture ISO Class 5 premium value pools through upstream resin control. |
| Direct Mill-to-Fab Procurement Contracts | TSMC's Central Procurement Organization bypasses traditional supply houses, fragmenting distributor-mediated channels. |
| Silicone-Based Fabric Treatment Qualification | BASF and Wacker Chemie scale fluorine-free finishing agents as ECHA REACH restrictions eliminate PFAS chemistries. |
| Biotechnology CDMO Channel Penetration | German and Swiss sterile operations accelerate polyester-substrate adoption through contract manufacturing partnerships. |
| Reusable Garment Service Model Pilot | Industrial laundry networks in Germany and Switzerland displace disposable unit purchasing through rental-plus-processing contracts. |
Research Approach
The analysis maps ISO Class 5 coverall procurement, spunbond-meltblown composite manufacturing, and biotechnology CDMO channel penetration, each validated through cleanroom procurement managers, textile laminator operations directors, and semiconductor fab contamination control engineers. Primary interviews with Korean and Japanese machinery suppliers, European pharmaceutical regulatory consultants, and Chinese domestic foundry sourcing leads combined with secondary validation from FDA sterile manufacturing guidance documents, ECHA REACH restriction proposals, and ISO 14644 cleanroom classification standards. Bottom-up demand modeling across foundry garment consumption and top-down supply validation through thermal bonding calender production capacity triangulated volume and value estimates.
Consistency checks against semiconductor capital expenditure disclosures and pharmaceutical aseptic processing facility buildout announcements validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-use industry, ISO certification class, and regional regulatory framework cluster. CAGRs derived from node shrinkage trajectories and EU MDR implementation timelines incorporated propylene monomer price elasticity and laminating equipment capacity constraints as industry-specific forecast inputs.
Material uncertainties — regulatory protocol revisions, machinery supplier capacity bottlenecks, and feedstock price volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable ISO 14644-1 validation timelines and continued semiconductor node migration below 3nm. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Non Woven Fabric Making Machine Market