
 Global Stone Retrieval Basket Market | 2026-2036
Global Stone Retrieval Basket Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stone Retrieval Basket Market Foresight
The EU Medical Device Regulation is decoupling market access from legacy CE certifications, forcing manufacturers to rebuild technical documentation around biocompatibility and clinical evidence. Boston Scientific Corporation leverages its vertically integrated nitinol supply chain to sustain margin structures under these compliance burdens. Cook Medical anchors its competitive stance through specialized urology-focused distribution networks across European tertiary centers. Coloplast Group differentiates via polymer-coated basket portfolios that navigate stricter cytotoxicity thresholds.
Stone retrieval baskets are minimally invasive instruments designed to capture, secure, and extract calculi from the urinary tract or biliary system during endoscopic procedures, typically constructed from superelastic nitinol wires configured into helical or flat-wire geometries with opening widths ranging from 1.5 mm to 4.5 mm. Wire basket configurations dominate procedural volumes in urology suites due to their radial strength and stone encagement reliability, while hybrid basket designs represent the fastest-growing segment as manufacturers blend net and wire architectures to improve capture rates for irregular stone morphologies. Nitinol material demand leads the material segmentation because its superelastic properties enable basket collapse within narrow working channels without permanent deformation.
FDA 510(k) pathways and the EU MDR frame product entry timelines, with both regulators now demanding predicate device comparisons and post-market surveillance protocols that extend development cycles. Japan's PMDA maintains distinct mechanical testing standards for retrieval devices that create additional localization requirements for multinational manufacturers. Stakeholders must monitor how reimbursement shifts toward outpatient urology procedures reshape purchasing authority from hospital procurement to ambulatory surgery center administrators.
Market Dynamics
The EU Medical Device Regulation is decoupling market access from legacy CE certifications, forcing manufacturers to rebuild technical documentation around biocompatibility and clinical evidence. This regulatory compression is reshaping competitive positioning across nitinol-based instrument portfolios.
Growth Catalysts
- EU MDR Compliance Windows:The Medical Device Regulation's transition deadlines are accelerating hospital procurement of validated single-use retrieval devices before legacy certificates expire.
- Minimally Invasive Surgery Expansion:Urology departments in hospital systems are scaling endoscopic stone management programs, concentrating demand for helical and flat-wire basket configurations.
- Nitinol Superelasticity Advantages:The material's ability to collapse within narrow working channels without permanent deformation sustains procedural preference over polymer alternatives.
Market Restraints
- Nitinol Supply Concentration:Superelastic wire production concentrates among limited specialty metallurgy suppliers, creating input vulnerability for basket manufacturers.
- Biocompatibility Testing Burden:The EU MDR's tightened cytotoxicity protocols extend validation timelines and inflate regulatory compliance costs for nitinol-based instruments.
- Reusable Device Substitution:Cost-conscious procurement committees in public hospital systems continue evaluating reprocessing protocols as alternatives to single-use baskets.
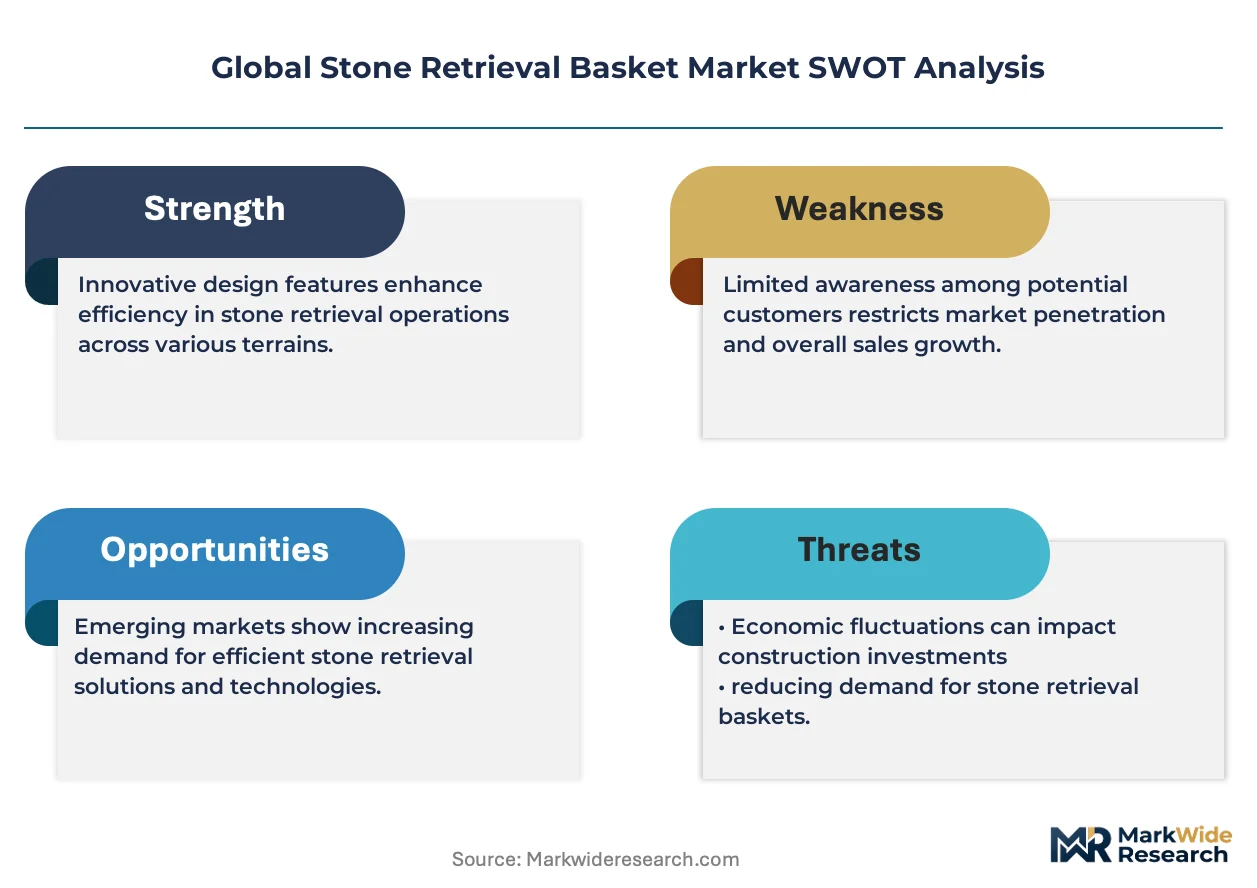
Strategic Opportunities
- Hybrid Architecture Development:Manufacturers blending net and wire geometries can capture irregular stone morphologies that escape traditional helical configurations.
- Ambulatory Surgery Center Penetration:Reimbursement shifts toward outpatient urology procedures are transferring purchasing authority to ASC administrators seeking streamlined device portfolios.
- Japan Localization Requirements:The PMDA's distinct mechanical testing standards create first-mover advantages for manufacturers establishing dedicated compliance infrastructure.
Industry Challenges
- Predicate Device Comparison Burden:FDA 510(k) pathways now demand extensive equivalence documentation that compresses development timelines for novel basket geometries.
- Post-Market Surveillance Infrastructure:Both FDA and EU MDR require active monitoring systems that strain quality assurance resources at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stone Retrieval Basket Market |
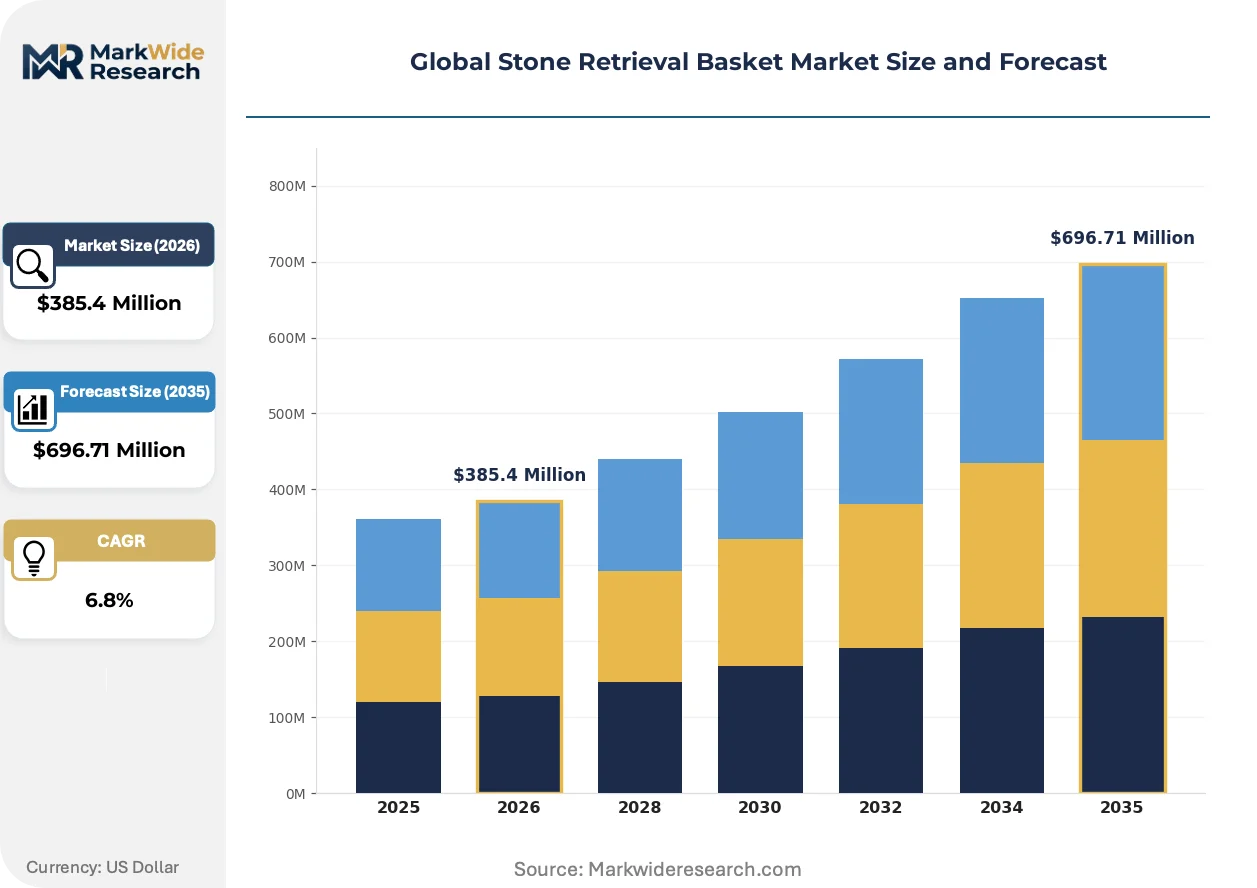
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Basket, Net Basket, Hybrid Basket, Sheath Basket Application: Urology Procedures, Gastroenterology Procedures, Endoscopy, Minimally Invasive Surgery End User: Specialty Clinics, Ambulatory Surgery Centers, Diagnostic Centers, Clinical Laboratories Material: Nitinol, Stainless Steel, Polymer Coated, Braided Wire |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Coloplast Group, Olympus Corporation, Becton, Dickinson and Company, Stryker, Medi-Globe GmbH, Advin Health Care, UROMED Kurt Drews KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stone Retrieval Basket Market Shifts & Advancements
Device architectures are converging across material science and procedural workflow optimization, with regulatory frameworks simultaneously tightening performance validation standards. These intersecting pressures are compressing product development cycles while elevating technical barriers to market entry.
Polymer-coated basket surfaces are converging with traditional nitinol wire cores to reduce stone fragmentation during extraction. Tertiary urology centers in Germany and Japan are piloting these hybrid configurations for complex renal calculi cases. This convergence is enabling higher capture rates for irregular stone morphologies while extending device functional life within single-use parameters.
The EU MDR's biocompatibility testing protocols are mandating ISO 10993 cytotoxicity validation for all nitinol-based instruments regardless of prior CE marking. Manufacturers must resubmit technical documentation with expanded clinical evidence packages. European tertiary centers are prioritizing suppliers with established MDR certificates, compressing vendor pools before the 2027 enforcement deadline.
Hospital procurement committees are consolidating supplier relationships around full-procedure portfolios rather than standalone basket purchases. Ambulatory surgery centers in the United States are displacing traditional distributor relationships with direct manufacturer contracts that bundle retrieval devices with lithotripsy systems. This concentration is most visible in Florida and Texas, where ASC chains are centralizing urology service line purchasing authority.
Global Stone Retrieval Basket Market Segmentation
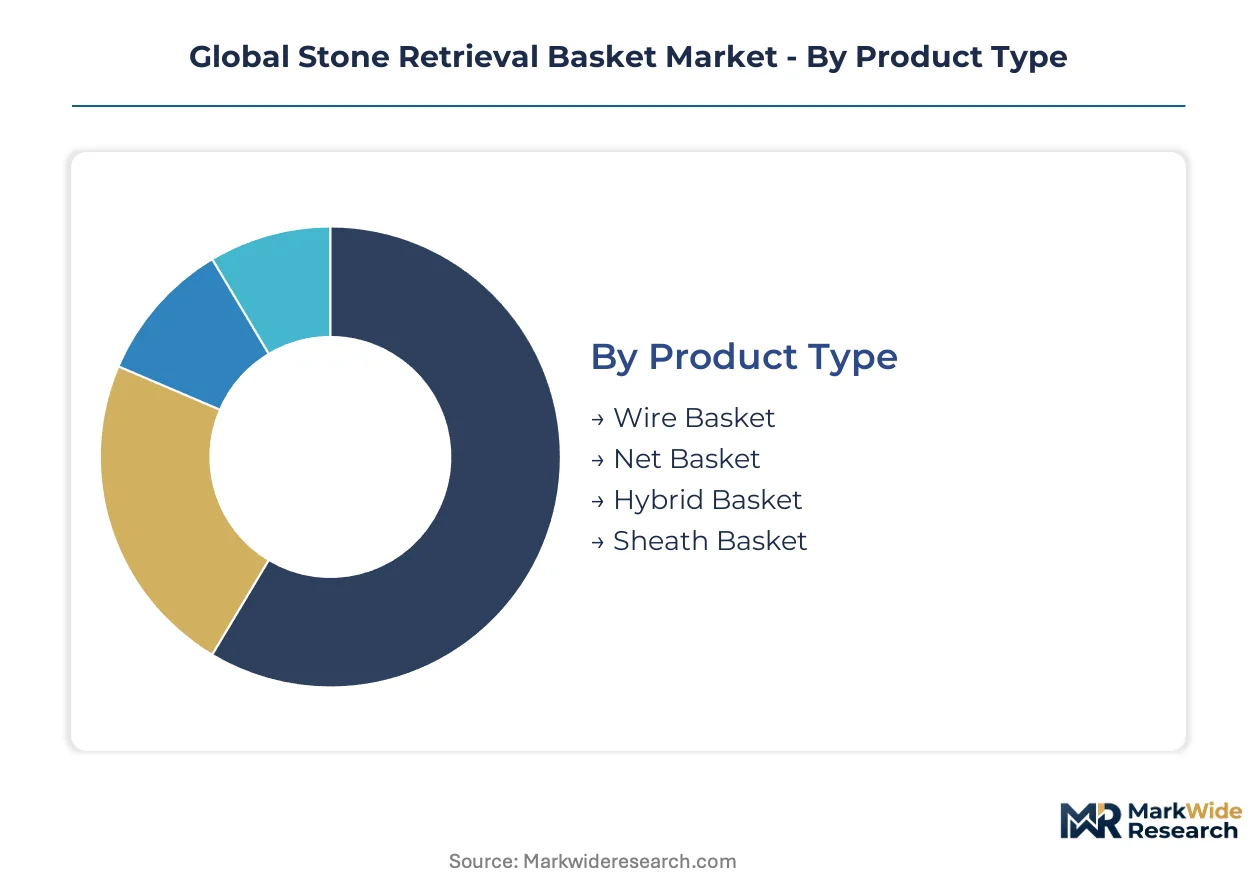
Stone retrieval basket procurement varies sharply across clinical settings and material specifications, with regulatory pathways from the FDA, EU MDR, and Japan's PMDA creating divergent compliance burdens for each segment. Manufacturers must align product portfolios with the specific certification requirements and reimbursement structures governing each category.
Product Type:
FDA 510(k) clearances and EU MDR technical documentation requirements vary substantially across basket architectures, with hybrid designs facing the most complex predicate device comparisons.
- Wire Basket:Helical and flat-wire configurations constructed from superelastic nitinol deliver radial strength and reliable stone encagement. Demand concentrates in United States hospital urology suites scaling endoscopic stone management programs, though reusable device substitution pressures persist in cost-conscious procurement committees.
- Hybrid Basket:Blended net and wire architectures improve capture rates for irregular stone morphologies. Germany and Japan tertiary centers are piloting these configurations for complex renal calculi cases, with manufacturers investing in expanded clinical evidence packages to satisfy EU MDR biocompatibility protocols.
- Net Basket:Polymer mesh configurations offer alternative encagement mechanics for specific stone geometries.
- Sheath Basket:Integrated sheath designs streamline procedural workflow in high-volume ambulatory settings.
Leading the category by volume: Wire Basket. Growing fastest: Hybrid Basket.
Application:
Procedure reimbursement codes and site-of-service policies reshape purchasing authority across clinical applications, with outpatient shifts favoring streamlined device portfolios.
- Urology Procedures:Endoscopic stone extraction from the urinary tract represents the core procedural volume for retrieval baskets. United States ambulatory surgery centers in Florida and Texas are displacing traditional distributor relationships with direct manufacturer contracts as reimbursement migrates outpatient.
- Minimally Invasive Surgery:Laparoscopic and robot-assisted stone management procedures demand specialized basket configurations with enhanced maneuverability. Japanese hospital systems are expanding procurement of single-use retrieval devices as minimally invasive surgery programs scale nationally.
- Gastroenterology Procedures:Biliary stone extraction applications require distinct tip flexibility and opening width specifications.
- Endoscopy:Diagnostic and therapeutic endoscopic procedures utilize retrieval baskets for foreign body and calculus management.
Urology Procedures command the largest procedure volume. Minimally Invasive Surgery shows the steepest expansion trajectory as hospital systems consolidate service lines.
End User:
Customer procurement sophistication and contract structures diverge markedly across care delivery settings, from centralized hospital committees to independent ASC administrators.
- Ambulatory Surgery Centers:Independent administrators in United States markets seek bundled device portfolios and direct manufacturer relationships. These customers prioritize streamlined SKUs and volume pricing over technical customization.
- Specialty Clinics:Urology-focused practices in Germany maintain specialized distributor relationships for technical support and inventory management.
- Diagnostic Centers:Imaging and diagnostic facilities require retrieval baskets for interventional procedures.
- Clinical Laboratories:Research and reference laboratories utilize baskets for specimen handling applications.
Ambulatory Surgery Centers are gaining purchasing authority fastest as site-of-service shifts accelerate. Specialty Clinics retain the most fragmented supplier base.
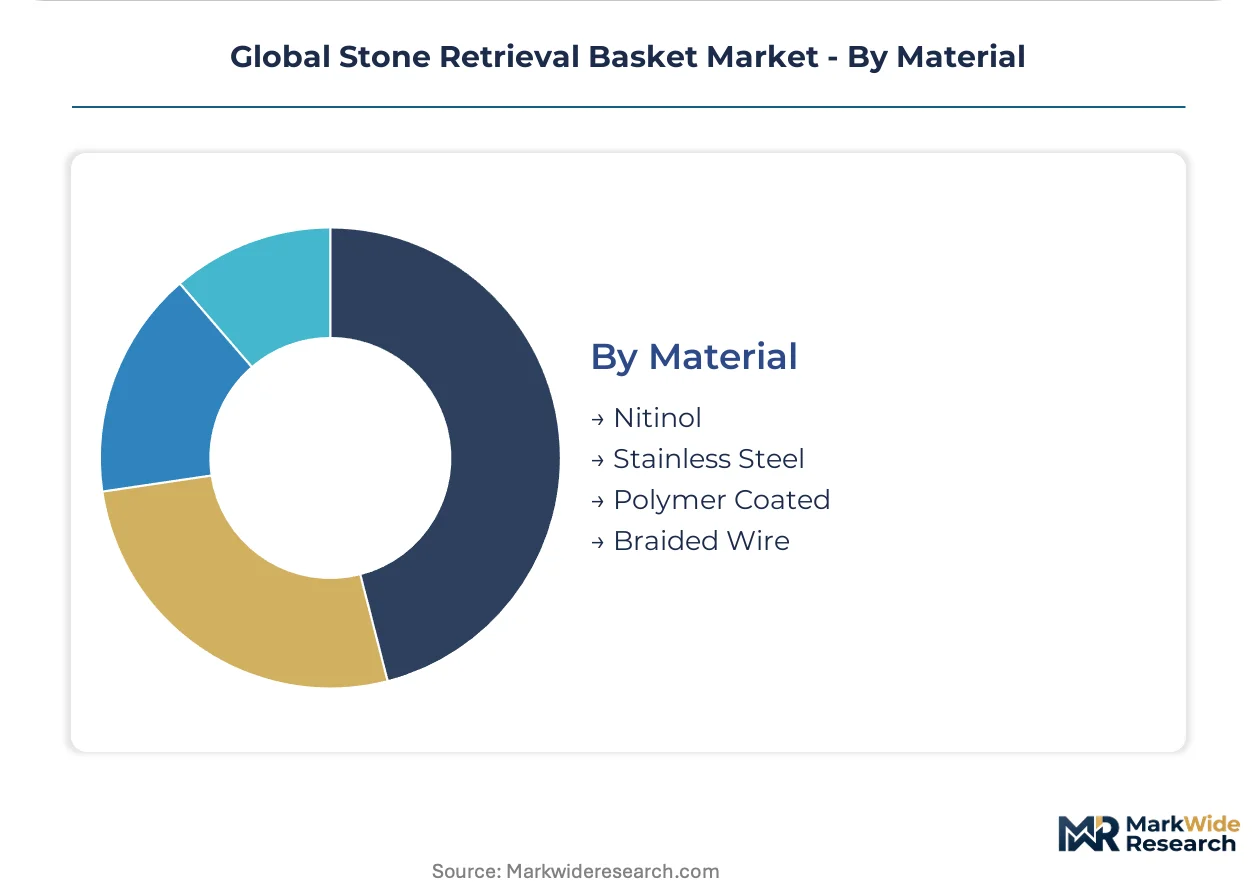
Material:
Input sourcing strategies and biocompatibility testing protocols create divergent margin structures across material categories, with nitinol supply concentration generating strategic vulnerability.
- Nitinol:Nickel-titanium superelastic alloy enables basket collapse within narrow working channels without permanent deformation. EU MDR tightened cytotoxicity protocols now mandate ISO 10993 validation for all nitinol instruments, extending timelines for European market access.
- Polymer Coated:Surface-coated nitinol or stainless steel cores reduce stone fragmentation during extraction. These configurations navigate stricter cytotoxicity thresholds in European tertiary centers prioritizing suppliers with established MDR certificates.
- Stainless Steel:Traditional material alternative for cost-sensitive procurement segments.
- Braided Wire:Multi-filament constructions offer alternative mechanical properties for specific procedural requirements.
Nitinol dominates procedural preference and revenue concentration. Polymer Coated variants are climbing the fastest as European compliance windows compress vendor pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for stone retrieval baskets concentrates in the United States, Germany, and Japan as these countries scale minimally invasive stone management programs and tighten regulatory compliance windows.
United States
Ambulatory surgery centers in Florida and Texas are displacing traditional distributor relationships with direct manufacturer contracts. The FDA's 510(k) pathway demands extensive predicate device comparisons that compress development timelines for novel basket geometries. Boston Scientific Corporation leverages its vertically integrated nitinol supply chain to sustain margin structures under these compliance burdens.
Germany
Tertiary urology centers in Germany are piloting hybrid basket configurations for complex renal calculi cases. The EU Medical Device Regulation is tightening biocompatibility testing protocols for nitinol-based instruments, forcing manufacturers to rebuild technical documentation. Cook Medical anchors its competitive stance through specialized urology-focused distribution networks across European tertiary centers.
Japan
Japanese hospital systems are expanding procurement of single-use retrieval devices as minimally invasive surgery programs scale nationally. The PMDA maintains distinct mechanical testing standards for retrieval devices that create additional localization requirements for multinational manufacturers. Olympus Corporation occupies a strategic position within this regulatory environment.
United Kingdom
Hospital procurement committees in the UK are consolidating supplier relationships around full-procedure portfolios rather than standalone basket purchases. The EU MDR's biocompatibility testing protocols mandate ISO 10993 cytotoxicity validation for all nitinol-based instruments regardless of prior CE marking. London and Southeast England cluster the majority of specialized urology centers driving device adoption.
India
Cost-conscious procurement committees in public hospital systems continue evaluating reprocessing protocols as alternatives to single-use baskets. The country's national medical device regulator is aligning testing standards with international benchmarks. Advin Health Care represents domestic manufacturing capabilities serving price-sensitive segments.
Global Stone Retrieval Basket Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions through regulatory compliance infrastructure. The market structure reflects moderate consolidation around vertically integrated nitinol processors and specialized urology distributors. Three archetypes dominate: multinational conglomerates with captive metallurgy supply, mid-scale regional specialists with MDR certification advantages, and emerging Asian fabricators competing on cost. Competitive moves concentrate on MDR compliance acceleration and ambulatory surgery center direct contracting.
Among United States-based multinationals, Boston Scientific Corporation and Stryker exemplify scale-driven archetypes with integrated supply chain control. Cook Medical, a privately held Indiana corporation, represents the specialist distributor model with deep European tertiary center penetration. Coloplast Group, the Danish multinational, occupies a position within polymer-coated basket portfolios that navigate stricter cytotoxicity thresholds. These three anchors illustrate how regulatory compression is reshaping competitive positioning across nitinol-based instrument portfolios.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Coloplast Group |
| Olympus Corporation |
| Becton, Dickinson and Company |
| Stryker |
| Medi-Globe GmbH |
| Advin Health Care |
| UROMED Kurt Drews KG |
| Others |
Supply & Pricing Matrix
Captive nitinol supply chains at Boston Scientific and Stryker anchor both procurement security and premium pricing power across hospital and ambulatory surgery center segments. These vertically integrated structures insulate margin structures from raw material volatility while compressing competitive room for mid-scale manufacturers facing EU MDR compliance burdens.
Pricing Analysis
Volume procurement by United States ambulatory surgery centers concentrates in standard-tier wire baskets, while premium hybrid configurations command margin premiums at German and Japanese tertiary centers. Price differentiation rests on FDA 510(k) certification tier and MDR compliance status, with legacy CE-marked inventory clearing at distressed levels ahead of regulatory deadlines. Cost compression in standard-tier segments intensifies as reusable device reprocessing protocols gain traction among public hospital procurement committees. Ambulatory surgery center administrators exhibit highest price sensitivity, prioritizing streamlined SKUs over technical customization, while academic medical centers absorb premium pricing for complex-case hybrid architectures.
Supply Chain Analysis
Regional distribution centers in Indiana, Denmark, and Tokyo operate hub-and-spoke patterns serving hospital systems and specialty clinics. Superelastic nitinol wire production concentrates in the United States, Germany, and Japan, with specialty metallurgy suppliers maintaining tight control over superelastic alloy specifications. Raw material dependencies include nickel-titanium feedstock, polymer coating substrates, and precision-drawn wire diameters. Single-source vulnerability characterizes superelastic wire supply, where limited qualified metallurgy houses create bottleneck risk for basket manufacturers scaling output. Distribution runs through specialized urology-focused distributor networks in Europe and direct manufacturer contracts displacing traditional channels in United States ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR compliance windows are forcing weaker capitalized manufacturers toward exit or acquisition. Regulatory compression is eliminating technical documentation capabilities at mid-scale competitors, concentrating vendor pools around MDR-certified incumbents.
For Market Incumbents: Lock in ambulatory surgery center direct contracting relationships in Florida and Texas before reimbursement shifts fully mature. Defend against reusable device substitution by embedding single-use baskets into lithotripsy system bundles that raise switching costs. Prioritize backward integration into nitinol wire supply or long-term offtake agreements with qualified metallurgy suppliers to secure input access as superelastic production capacity tightens.
For New Entrants and Emerging Players: EU MDR in Europe opens a window for specialized compliance consultancies and contract manufacturers serving mid-tier brands lacking technical documentation infrastructure. Target polymer-coated basket segments where cytotoxicity validation requirements create differentiation headroom against legacy nitinol wire competitors. Pursue white-label manufacturing arrangements with established MDR certificate holders rather than direct brand building, leveraging Japan PMDA localization requirements as a secondary entry pathway after European validation.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational conglomerates seeking MDR-certified manufacturing assets and European tertiary center distribution relationships. Long-term viability favors targets with captive nitinol supply relationships or established hybrid architecture R&D pipelines. Watch hospital procurement committee consolidation around full-procedure portfolios as the inflection signal for valuation compression at standalone basket manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | Establishes market access before legacy CE certificates expire across European tertiary centers. |
| Ambulatory Surgery Center Direct Contracting | Captures purchasing authority migration from hospital procurement to ASC administrators in Florida and Texas. |
| Hybrid Architecture R&D Investment | Addresses irregular stone morphologies escaping traditional helical configurations in complex renal cases. |
| Nitinol Supply Security Programs | Mitigates single-source vulnerability at specialty metallurgy suppliers through long-term offtake structures. |
| Japan PMDA Localization Infrastructure | Creates first-mover positioning against multinational competitors lacking dedicated mechanical testing capabilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and urology department heads. Secondary sources included FDA 510(k) clearance databases, EU MDR technical documentation repositories, Japanese PMDA submission records, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down device manufacturer revenue segmentation.
Data-stream reconciliation across product type, application, end user, material specification, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs derived from weighted average of procedure growth assumptions and device ASP trajectory modeling. Forecast inputs incorporated ambulatory surgery center site-of-service shift rates, EU MDR enforcement timeline assumptions, and nitinol supply capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for reusable device reprocessing or polymer substitution would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and reimbursement migration timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Rectal Catheters Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Cannula Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Human Anatomy Model Market
Medical Devices
TMJ Implants Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Global Electronic Stethoscope Market