
 Smart Sports Market | 2026-2036
Smart Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sports Market Analytics
Advanced polymer composites and graphene-infused textiles are consolidating as the dominant substrate for next-generation smart apparel, displacing traditional nylon-elastomer blends in high-performance garments. Nike, Inc. leverages vertically integrated textile R&D to sustain premium positioning across wearable categories. Garmin Ltd. anchors its growth in GPS-integrated multi-sport devices with proprietary chipset architecture. Catapult Sports specializes in athlete load-management algorithms that differentiate its platform from generalist fitness trackers.
Smart Sports encompasses integrated hardware-software ecosystems where embedded sensors, wireless connectivity modules, and edge-computing processors collect real-time biomechanical and physiological data for performance optimization. These systems typically operate on sub-1GHz or Bluetooth Low Energy protocols with power budgets under 50mW to enable continuous monitoring during competitive activity. Wearable Devices and Smart Equipment represent the largest installed base segments, while Data Analytics and Artificial Intelligence capture expanding margin pools as teams shift from hardware procurement to subscription-based insight platforms. Fitness Trackers face commoditization pressure as smartphone-native health applications absorb casual-user demand.
The Federal Communications Commission governs radio-frequency emissions from connected sports devices in the United States, while the European Union's GDPR and AI Act impose strict constraints on biometric data processing and algorithmic decision-making in athlete monitoring systems. China's MIIT and GB standards mandate cybersecurity certification for IoT-enabled training equipment entering domestic channels. Stakeholders must evaluate regulatory divergence across these jurisdictions when architecting data pipelines and selecting cloud infrastructure partners.
Market Dynamics
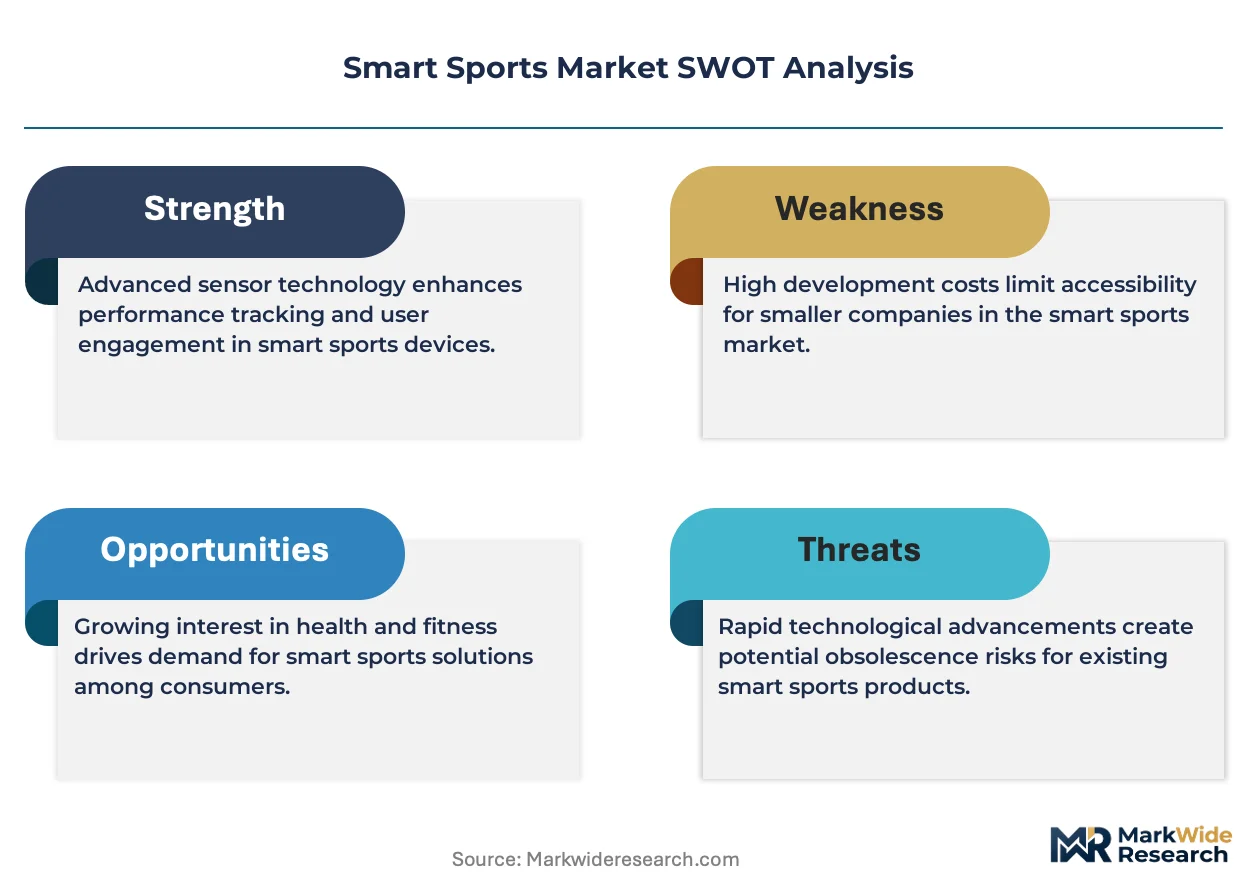
Compression of sensor power budgets below 50mW is collapsing hardware margins and forcing suppliers to monetize through recurring analytics subscriptions rather than device sales. This structural pivot from capital expenditure to operational expenditure models is redistributing value capture toward software platforms.
Growth Catalysts
- GDPR and EU AI Act compliance frameworks:European sports federations are mandating biometric governance protocols that accelerate procurement of certified athlete monitoring systems.
- Wearable sensor miniaturization:Sub-millimeter form factors enable integration into competition-legal garments without performance interference.
- China:MIIT cybersecurity certification requirements for IoT training equipment are filtering low-quality imports and elevating domestic vendor procurement.
Market Restraints
- Advanced polymer composite input costs:Graphene-infused textile substrates face price volatility tied to rare earth processing constraints.
- Bluetooth Low Energy protocol limitations:Sub-1GHz spectrum congestion in dense training environments creates data packet loss during multi-athlete sessions.
- Smartphone-native health applications:Casual fitness users are abandoning dedicated trackers for integrated mobile ecosystems.
Strategic Opportunities
- Rehabilitation medicine integration:Post-surgical recovery protocols in Germany are adopting load-management algorithms originally developed for elite performance.
- Subscription-based insight platforms:Professional teams in the United States are shifting from perpetual hardware licenses to annual analytics contracts.
- Edge-computing processor convergence with 5G:Real-time biomechanical feedback loops are enabling mid-competition tactical adjustments.
Industry Challenges
- Biomechanical data science talent scarcity:Teams lack personnel capable of interpreting multi-variate athlete load signals.
- ISO 27001 certification timelines:Cloud infrastructure partners require extended security audits before handling federated biometric repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sports Market |
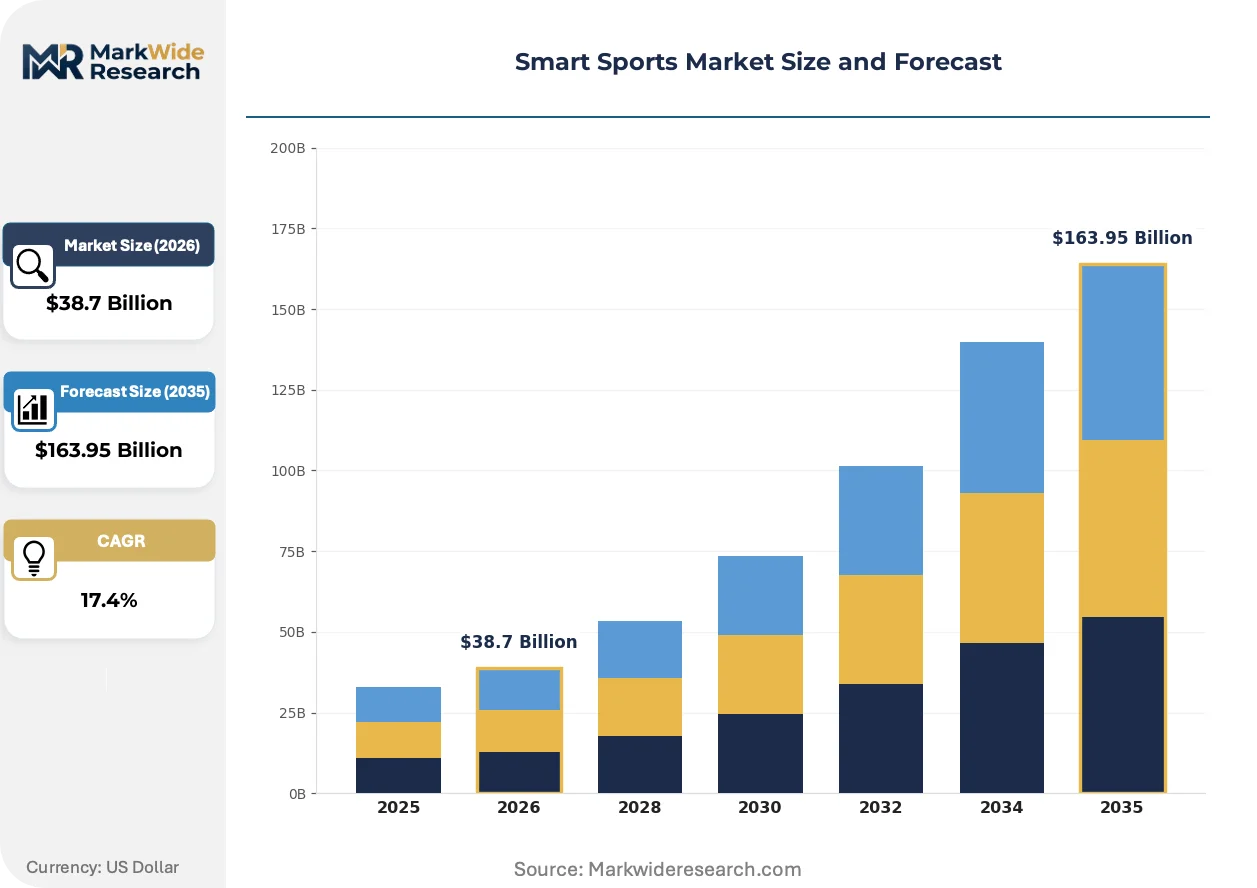
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Apparel, Fitness Trackers, Smart Equipment Application: Performance Monitoring, Injury Prevention, Training Optimization, Fan Engagement End User: Athletes, Coaches, Sports Teams, Fitness Enthusiasts Technology: IOT Solutions, Data Analytics, Artificial Intelligence, Cloud Computing |
| Companies Covered | Nike, Inc., Adidas AG, Garmin Ltd., Wilson Sporting Goods, Technogym, Under Armour, Inc., Fitbit, Inc., Catapult Sports, Puma SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sports Market Evolving Landscape
Convergence of embedded sensors, wireless modules, and edge processors is collapsing the traditional separation between hardware manufacturers and software analytics providers. This integration is compressing supplier margins while expanding platform stickiness.
Graphene-infused textile substrates are unifying conductivity, durability, and elasticity in single-layer fabrics. Professional cycling and swimming programs are adopting these materials for competition-legal suits. This unification is eliminating multi-layer construction costs and enabling thinner, lighter garment profiles.
The EU AI Act imposes algorithmic transparency requirements on automated athlete selection and training decisions. Sports federations must now document decision pathways for biometric-derived recommendations. Elite football clubs in Spain and Italy are restructuring data pipelines to satisfy audit requirements.
Subscription pricing for analytics platforms is displacing perpetual hardware licenses in professional team procurement. General managers now prioritize annual recurring revenue predictability over upfront capital expenditure. This shift is most visible in National Football League and Major League Baseball front offices.
Smart Sports Market Segmentation
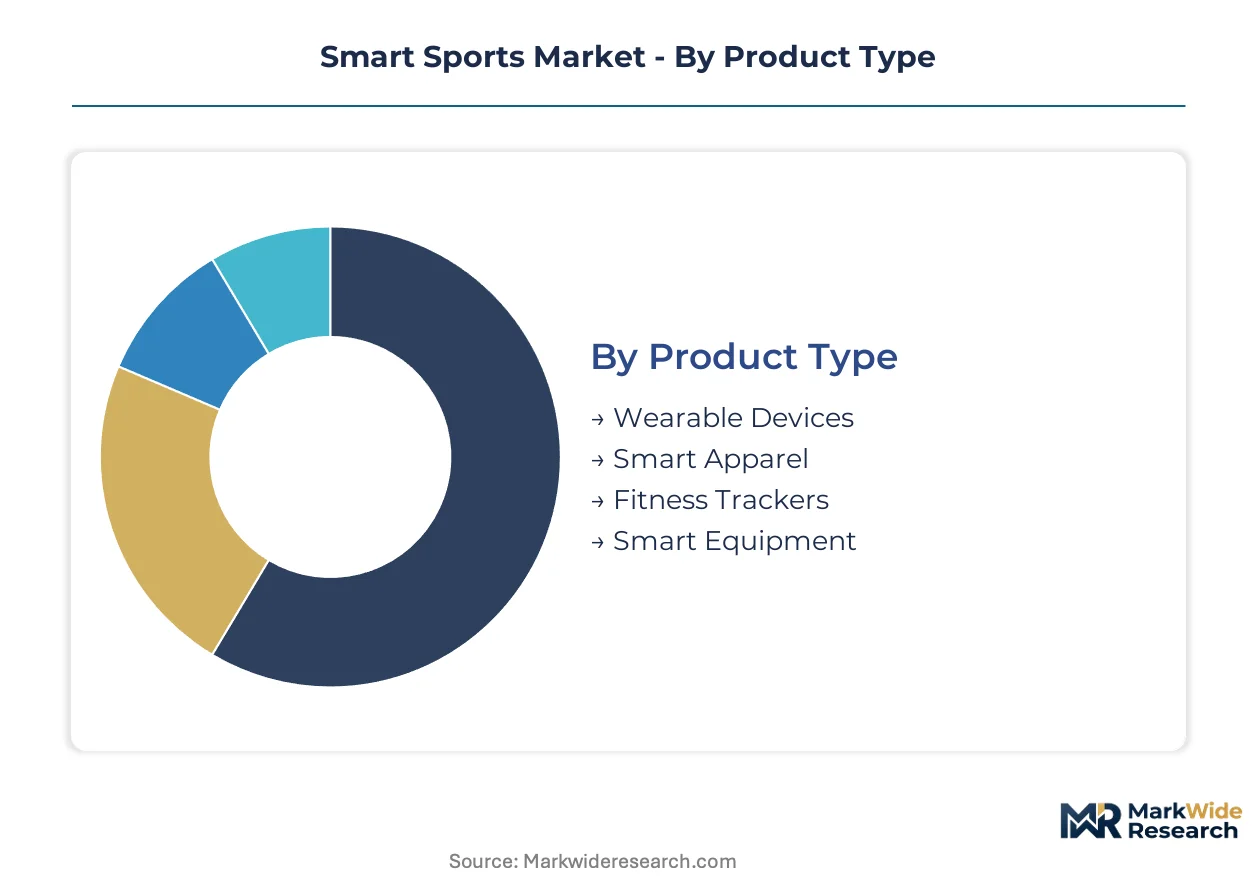
Smart Sports Market segmentation reveals how hardware commoditization and software value capture are redistributing revenue across product tiers. Technology architecture and end-user sophistication determine margin pools more than volume scale alone.
Product Type:
Form factor and sensor integration density separate premium systems from mass-market alternatives.
- Wearable Devices:Multi-sensor wristbands and chest straps with sub-50mW power budgets capture continuous physiological streams. Professional cycling teams in Germany and triathlon programs in Australia drive procurement of GPS-integrated units with proprietary chipset architectures.
- Smart Apparel:Graphene-infused textile substrates unify conductivity and elasticity in single-layer competition garments. Elite swimming programs and professional cycling teams are displacing nylon-elastomer blends for FINA and UCI-legal suits that eliminate multi-layer construction.
- Fitness Trackers:Casual-user demand is migrating to smartphone-native health applications, compressing dedicated device margins.
- Smart Equipment:Embedded load cells and accelerometers in training apparatus feed biomechanical databases for technique refinement.
Mature deployment sits with Wearable Devices. Newer deployment is concentrated in Smart Apparel.
Application:
Use case sophistication determines whether procurement flows to hardware vendors or analytics platforms.
- Performance Monitoring:Real-time biomechanical feedback during competitive activity requires edge-computing processors with sub-1GHz or Bluetooth Low Energy protocols. National Football League and Major League Baseball front offices are shifting from perpetual hardware licenses to annual analytics contracts for predictive load management.
- Injury Prevention:Post-surgical recovery protocols in German rehabilitation medicine are adopting athlete load-management algorithms originally developed for elite performance optimization.
- Training Optimization:AI-driven pattern recognition in multi-variate data streams enables mid-competition tactical adjustments through 5G-enabled feedback loops.
- Fan Engagement:Biometric-derived content and immersive viewing experiences create secondary revenue streams for broadcast rights holders.
Revenue concentration favors Performance Monitoring. Training Optimization is climbing the fastest as federations mandate algorithmic transparency under EU AI Act requirements.
End User:
Budget scale and technical staffing separate institutional procurement from individual purchasing patterns.
- Athletes:Individual professionals and Olympic hopefuls purchase direct-to-consumer devices with limited analytics depth.
- Coaches:Staff biomechanists and performance directors require federated data repositories with ISO 27001-certified cloud infrastructure.
- Sports Teams:Professional organizations in the United States, China, and Germany build elite training infrastructure with data governance frameworks for athlete monitoring.
- Fitness Enthusiasts:Price-sensitive casual users are abandoning dedicated trackers for integrated mobile ecosystems.
Contract value peaks with Sports Teams. Individual Athlete purchases are expanding most quickly in emerging training infrastructure markets.
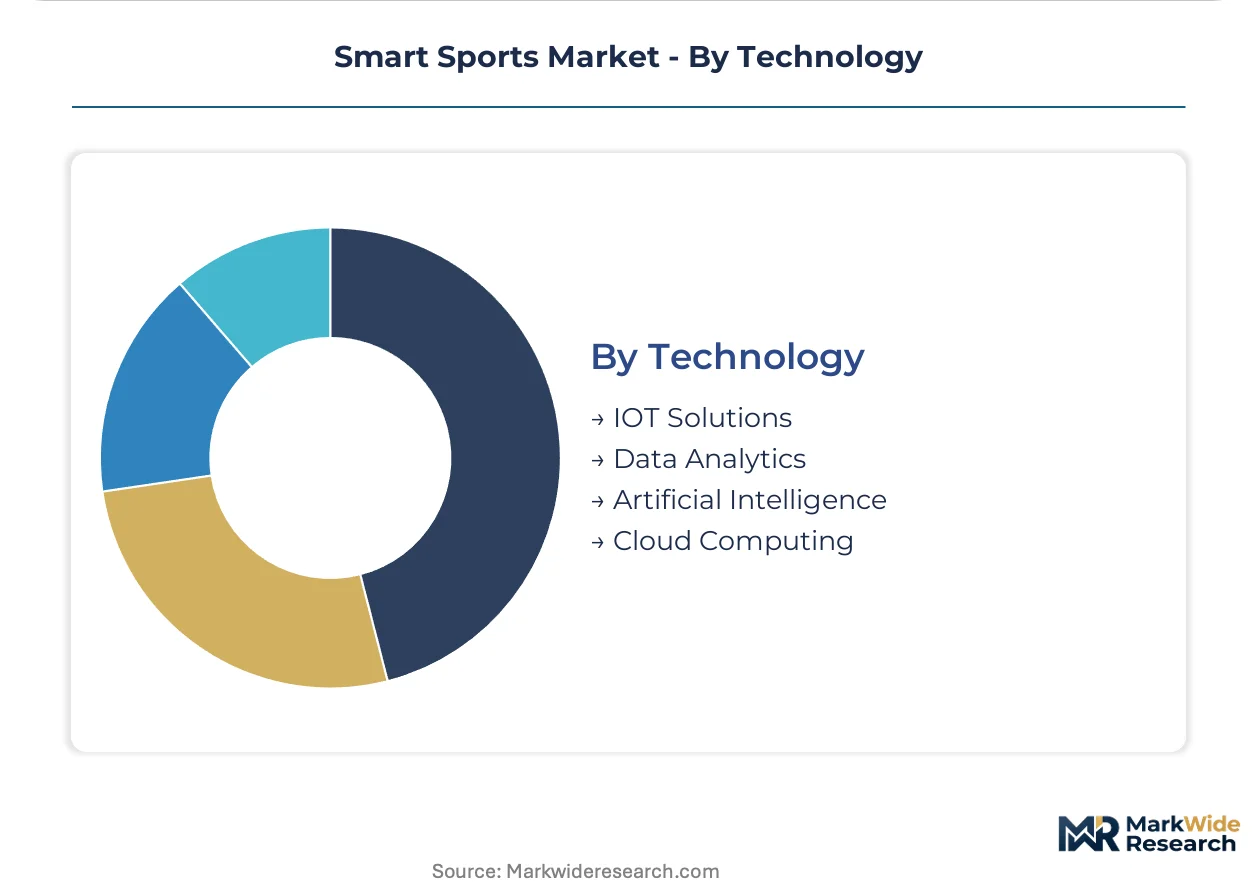
Technology:
Stack layer determines whether value capture accrues to component suppliers, platform operators, or algorithm developers.
- IOT Solutions:Wireless connectivity modules and embedded sensors with MIIT cybersecurity certification for China market entry.
- Data Analytics:Subscription-based insight platforms displace perpetual licenses as general managers prioritize annual recurring revenue predictability.
- Artificial Intelligence:Automated athlete selection and training decisions now require documented decision pathways under EU AI Act audit requirements for Spanish and Italian football clubs.
- Cloud Computing:Extended security audits for federated biometric repositories create certification bottlenecks for infrastructure partners.
Platform stickiness concentrates in Data Analytics. Artificial Intelligence represents the steepest expansion trajectory as regulatory compliance mandates accelerate certified system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional teams in the United States, China, and Germany account for the majority of elite training infrastructure investment, with procurement patterns diverging sharply between institutional buyers and individual consumers across each market.
United States
National Football League and Major League Baseball front offices drive demand for predictive load management systems. FCC regulations govern radio-frequency emissions from connected devices used in competitive environments. Boston and Los Angeles clusters host the densest concentrations of sports technology startups developing edge-computing processors for real-time biomechanical feedback.
China
Domestic vendor procurement accelerates as MIIT cybersecurity certification requirements filter low-quality IoT training equipment imports. GB standards mandate specific technical protocols for athlete monitoring devices entering commercial channels. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou produce graphene-infused textile substrates for smart apparel export markets.
Germany
Post-surgical rehabilitation medicine programs adopt athlete load-management algorithms originally developed for elite performance optimization. GDPR compliance frameworks impose strict biometric data processing constraints on federated monitoring systems. Bavarian sports science institutes in Munich collaborate with professional football clubs to validate ISO 27001-certified cloud infrastructure for athlete data repositories.
Australia
Triathlon programs and professional cycling teams procure GPS-integrated wearable units with proprietary chipset architectures. The country's national data protection regulator enforces alignment with GDPR-equivalent privacy standards for biometric collection. Melbourne and Sydney training facilities serve as testbeds for sub-1GHz protocol deployments in dense multi-athlete session environments.
Japan
Corporate wellness programs and Olympic training centers expand procurement of embedded sensor systems for technique refinement. METI industrial policy supports domestic development of low-power wireless connectivity modules. Kanto region manufacturers in Tokyo and Yokohama specialize in miniaturized accelerometers for integration into competition-legal garments.
Smart Sports Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with apparel incumbents leveraging vertically integrated textile R&D against pure-play sensor developers. The vendor base concentrates around three strategic archetypes: integrated sportswear conglomerates with captive wearable divisions, dedicated fitness technology developers with proprietary chipset architectures, and niche athlete analytics platforms specializing in load-management algorithms. Competitive moves center on M&A activity targeting biometric data science capabilities and strategic partnerships with cloud infrastructure providers seeking ISO 27001 certification.
Among integrated sportswear conglomerates, Nike, Inc. and Adidas AG exemplify archetypes combining apparel manufacturing scale with in-house sensor development programs. Garmin Ltd. occupies a position within the dedicated fitness technology tier, anchoring geographic concentration in GPS-integrated multi-sport device categories. These three entities represent distinct strategic postures: captive supply chain control, component specialization, and platform ecosystem development respectively.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Garmin Ltd. |
| Wilson Sporting Goods |
| Technogym |
| Under Armour, Inc. |
| Fitbit, Inc. |
| Catapult Sports |
| Puma SE |
| Others |
Value Network & Pricing Analysis
Biomechanical data science talent scarcity in the United States and Germany widens pricing-tier spreads between certified analytics platforms and basic hardware vendors. Labor-cost differentials for ISO 27001-certified cloud architects versus commodity sensor assemblers separate premium subscription tiers from economy device margins.
Pricing Analysis
Volume concentrates in fitness trackers while margins accrue to data analytics platforms. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified federated repositories from uncertified local storage. Price differentiation hinges on algorithmic transparency documentation for EU AI Act compliance and graphene-infused textile substrate quality. Pricing pressure stems from smartphone-native health applications absorbing casual-user demand. Fitness enthusiasts exhibit highest price sensitivity; professional sports teams in the United States demonstrate lowest sensitivity due to recurring revenue predictability priorities.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from National Football League and Major League Baseball front offices. Component manufacturing concentrates in China, Taiwan, and Japan for embedded sensors and edge-computing processors. Raw material dependencies include graphene for textile conductivity, rare earth elements for sensor miniaturization, and advanced polymer composites for garment substrates. Supply chain risk centers on MIIT cybersecurity certification timelines creating import bottlenecks for IoT training equipment. Distribution runs through certified systems integrators and cloud infrastructure partners with ISO 27001 credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over graphene-infused textile R&D or proprietary chipset architecture determines margin capture. Players are pursuing backward integration into sensor fabrication to escape hardware commoditization.
For Market Incumbents: Lock in federated data repository contracts with ISO 27001-certified cloud infrastructure partners before certification timelines extend. Acquire niche athlete analytics platforms specializing in load-management algorithms to defend against generalist fitness tracker erosion. Prioritize graphene-infused textile substrate supply agreements in Yangtze River Delta manufacturing hubs to secure competition-legal smart apparel inputs. For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in Spain and Italy open a window for compliance-focused analytics platforms. Target post-surgical rehabilitation medicine programs in Germany adopting athlete load-management algorithms for white-space entry. Deploy direct-to-consumer subscription models with MIIT pre-certification to bypass import filtering for China market access. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated sportswear conglomerates given captive textile R&D leverage against pure-play sensor developers. Long-term viability favors entities controlling both graphene substrate supply and proprietary chipset architecture. Watch for EU AI Act audit completion rates among Spanish and Italian football clubs as inflection indicator for certified platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive production of sub-50mW power budget modules escapes hardware margin compression. |
| ISO 27001 Cloud Infrastructure Partnership | Certified federated repositories satisfy GDPR constraints for German professional teams. |
| Graphene Textile Substrate Supply Agreement | Single-layer fabric conductivity eliminates multi-layer construction costs for FINA-legal suits. |
| EU AI Act Compliance Platform Development | Documented decision pathways unlock procurement from Spanish and Italian football clubs. |
| Rehabilitation Medicine Algorithm Licensing | German post-surgical protocols expand addressable market beyond elite performance optimization. |
Research Methodology
Document review covered SEC filings from wearable device manufacturers, EMA regulatory guidance on biometric data processing, and MIIT cybersecurity certification standards, complemented by interviews with performance directors at professional sports teams, biomechanical data scientists, cloud infrastructure procurement leads, and textile R&D directors. Secondary validation drew from FCC radio-frequency emission databases, ClinicalTrials.gov for rehabilitation protocol studies, and customs records for graphene-infused textile trade flows. Bottom-up sensor shipment estimates and top-down analytics platform revenue triangulation anchored market sizing.
Market value outputs across the projection horizon reflect segmentation by product type, application sophistication, end-user budget scale, and technology stack layer. CAGRs were derived from installed base growth rates for wearable devices and subscription pricing expansion for analytics platforms. Industry-specific inputs included MIIT certification timeline assumptions, EU AI Act compliance cost estimates, and graphene substrate price volatility indices.
Caveats apply where MIIT cybersecurity certification delays, GDPR enforcement intensity variations, or rare earth processing constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding sensor miniaturization cost curves and professional team procurement cycle timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Europe Spectator Sports Market