
 Racing Apparel Market | 2026-2036
Racing Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Apparel Market Analysis
FIA 8856-2018 certification-grade gear is rotating through the premium tier as the baseline expectation for professional and semi-professional buyers. Alpinestars leverages its vertically integrated manufacturing base in Northern Italy to control quality from fabric weaving to finished suit assembly. Sparco sustains deep relationships with factory-backed racing teams across GT and rally disciplines. Dainese differentiates through its proprietary D-Air airbag integration technology in racing suits, extending its position beyond passive protection into active safety systems.
Racing apparel encompasses specialized protective garments engineered with fire-resistant fabrics such as Nomex blends rated to withstand temperatures exceeding 800°C, designed to shield motorsport participants from thermal injury during high-speed incidents. The primary commercial purpose centers on compliance with sanctioning body safety mandates while enabling driver performance through lightweight, breathable constructions. Racing suits and gloves dominate volume flows given mandatory use across all professional categories, while helmets command the highest unit margins due to composite shell engineering and integrated communications systems. Leather retains strong share in motorcycle racing applications where abrasion resistance outweighs thermal priorities, though Nomex continues to displace legacy materials in four-wheel motorsport.
FIA homologation standards, Europe's REACH chemical regulations, and the EU Green Deal's textile sustainability framework collectively shape material sourcing, manufacturing processes, and market access conditions for racing apparel producers. The US EPA oversees chemical emissions from coating and finishing operations, while OSHA workplace safety rules influence domestic production economics. Stakeholders must monitor evolving biodegradability mandates and end-of-life recycling obligations as these frameworks extend into technical textiles.
Market Dynamics
FIA 8856-2018 certification mandates are compressing product lifecycles and forcing manufacturers to requalify entire product lines, while REACH chemical restrictions simultaneously constrain material sourcing options across European supply chains.
Growth Catalysts
- Airbag-integrated racing suits:D-Air and similar active protection systems are creating replacement demand among professional teams seeking enhanced driver safety beyond passive Nomex barriers.
- REACH textile sustainability framework:Europe's biodegradability mandates are accelerating R&D investment in recyclable fire-resistant fabrics, opening premium positioning for compliant suppliers.
- GT and rally factory team expansion:Manufacturer-backed endurance racing programs in Germany, Japan, and the United States are driving volume procurement of homologated gloves and footwear.
Market Restraints
- Aramid fiber supply concentration:DuPont's Nomex and Teijin's Twaron production clusters in the United States and Japan create input vulnerability for European and Asian suit manufacturers.
- REACH SVHC compliance costs:Substances of Very High Concern screening adds 12-18 months to material qualification timelines, freezing supplier switches.
- Leather substitution ceiling:Motorcycle racing's abrasion requirements prevent full Nomex displacement, fragmenting R&D budgets across incompatible material platforms.
Strategic Opportunities
- India motorsport infrastructure buildout:The Buddh International Circuit revival and FIA-backed karting academies are creating first-mover advantage for certified apparel distribution.
- Sim racing hardware convergence:Physical suit and glove sales to esports competitors are attaching to direct-to-consumer channels, bypassing traditional team procurement.
- EU Green Deal circular textile pilots:End-of-life racing suit recycling programs in Italy and Germany are generating brand differentiation and regulatory goodwill.
Industry Challenges
- FIA homologation testing bottlenecks:The single approved laboratory structure in France creates 8-12 month queues for new product certification, delaying revenue recognition.
- Multi-standard compliance complexity:Simultaneous SFI 3.2A, FIA 8856-2018, and ISO 11612 requirements force redundant testing budgets and SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Apparel Market |
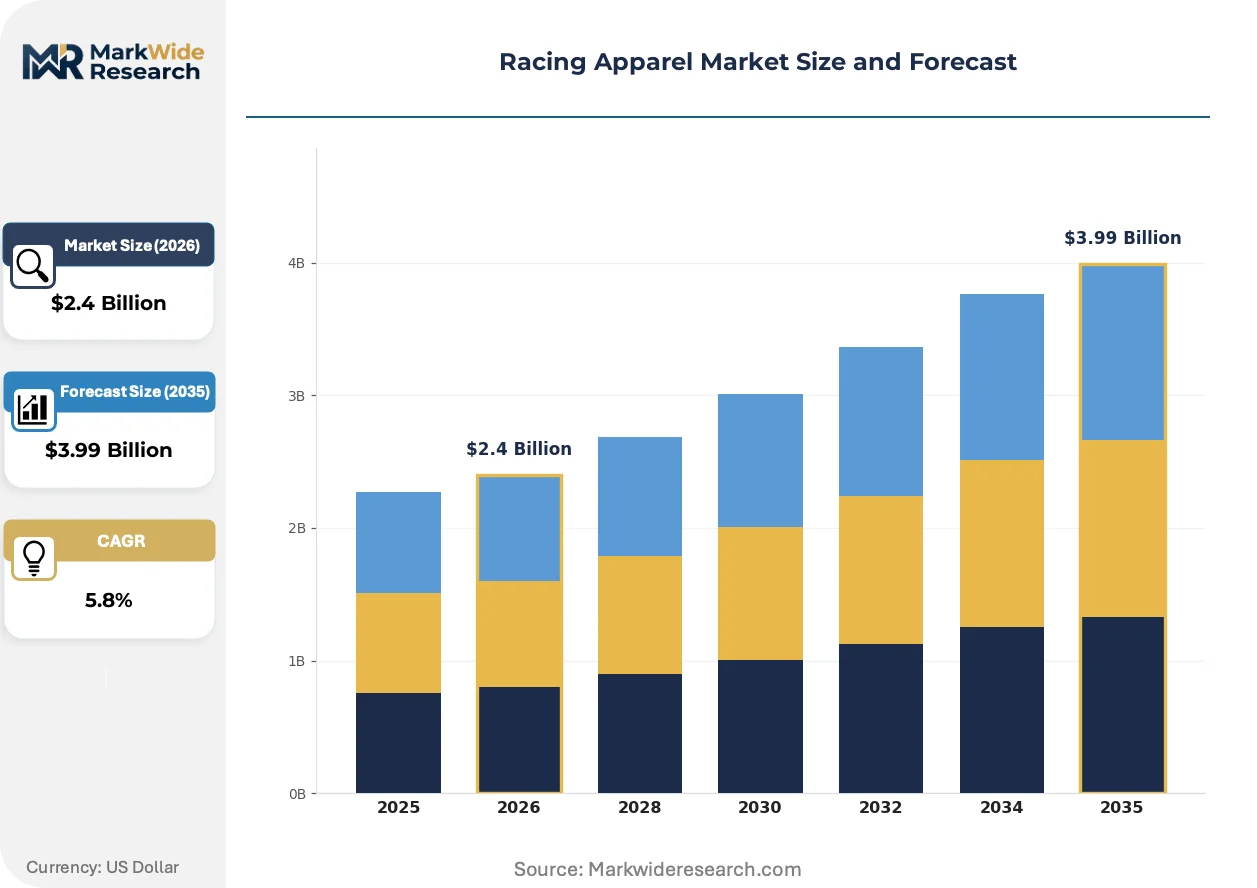
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racing Suits, Gloves, Shoes, Helmets Material: Nomex, Polyester, Leather, Mesh End User: Professional Drivers, Track Enthusiasts, Racing Teams, Retail Customers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Fox Head, FLY Racing, Alpinestars, AGV Sports Group, Sparco, OMP Racing, Adidas, BMW, Dainese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Apparel Market Emerging Trajectories
Active safety systems are migrating from motorcycle road gear into four-wheel motorsport, while regulatory chemical restrictions and direct-to-consumer channel growth are simultaneously reshaping how racing apparel reaches end users.
Sensor-embedded fabric technology is miniaturizing. Micro-accelerometers woven into Nomex layers now transmit real-time biometric and impact data to pit wall systems. Formula 1 and WEC teams are mandating these suits for 2024-season driver contracts. This capability is miniaturizing the boundary between protective equipment and telemetry infrastructure, compressing supplier margins on standalone suits while expanding systems-integration revenue pools.
Europe's REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy water-repellent treatments from fire-resistant textiles. Italian manufacturers around Vicenza are retrofitting plasma-based finishing lines to maintain performance without restricted chemistry. The premium suit segment bears the heaviest compliance burden, with smaller ateliers exiting rather than absorbing capital conversion costs.
Direct team-to-manufacturer contracting is displacing traditional distributor networks in professional categories. GT3 and LMP2 squads in Germany and the United Kingdom now negotiate multi-year supply agreements covering suits, gloves, and crew apparel as unified bundles. This consolidation is most visible in the United Kingdom, where McLaren Customer Racing and Aston Martin Racing have centralized procurement through single-source frameworks, marginalizing independent regional distributors.
Racing Apparel Market Segmentation
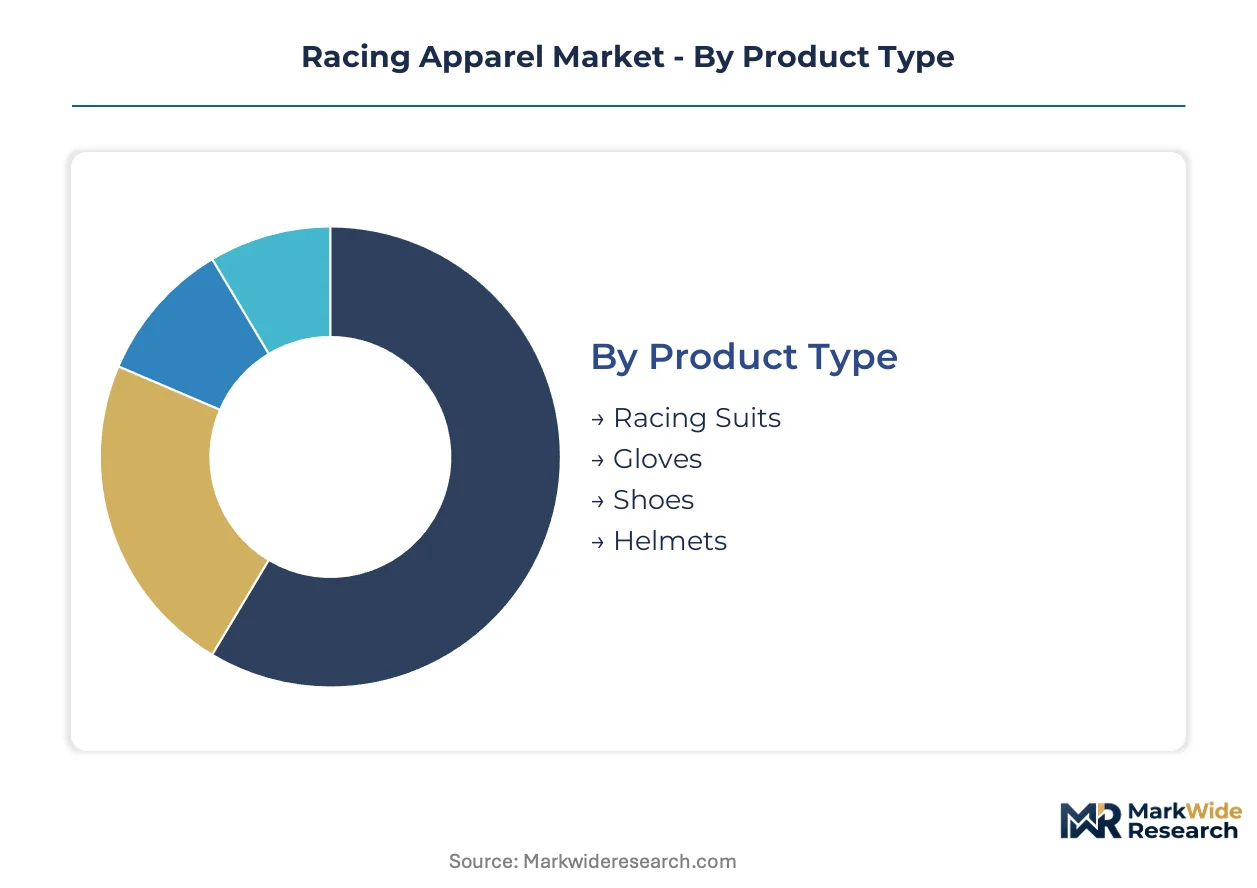
Racing apparel segmentation reveals divergent margin structures across material platforms and certification tiers. Product categories face distinct substitution pressures from adjacent safety equipment, while distribution channels fragment along professional-amateur boundaries.
Product Type:
Nomex-based racing suits face substitution pressure from airbag-integrated active protection systems, compressing standalone suit margins while expanding systems-integration revenue pools.
- Racing Suits:Fire-resistant one-piece and two-piece garments engineered from Nomex blends rated to withstand temperatures exceeding 800°C. Professional Formula 1 and NASCAR teams in the United States and Germany mandate FIA 8856-2018 certification, forcing 8-12 month homologation queues at France's single approved laboratory.
- Gloves:Fire-resistant hand protection with reinforced palm grips and seamless finger construction for steering wheel feedback. Factory-backed GT and endurance racing programs in Japan and the United Kingdom drive volume procurement through multi-year supply agreements covering unified crew apparel bundles.
- Shoes:Thin-sole driving footwear with fire-resistant uppers and extended ankle protection. Nomex construction dominates four-wheel applications while leather retains motorcycle racing share.
- Helmets:Composite shell head protection integrating communications systems and HANS device anchoring. Carbon fiber and Kevlar construction commands the highest unit margins across all product categories.
Racing suits anchor the volume base while airbag-integrated suits gain share at the steepest rate.
Material:
REACH chemical restrictions are fragmenting material sourcing economics across European supply chains, with plasma-based finishing lines replacing legacy water-repellent treatments.
- Nomex:Meta-aramid fiber delivering thermal protection above 800°C with inherent flame resistance. DuPont's United States and Teijin's Japan production clusters create input vulnerability for European and Asian suit manufacturers.
- Polyester:Synthetic fiber blended with fire-resistant treatments for entry-level and enthusiast segments. Lower certification tiers in India and Southeast Asia absorb cost-conscious demand from karting academies.
- Leather:Natural hide material prized for abrasion resistance in motorcycle racing applications. Abrasion requirements prevent full Nomex displacement, fragmenting R&D budgets across incompatible material platforms.
- Mesh:Breathable synthetic weave for ventilation panels in high-temperature cockpit environments. Secondary material function limits standalone application to suit inserts and glove backing.
Nomex dominates professional certification tiers while leather maintains defensible share in motorcycle racing where abrasion resistance outweighs thermal priorities.
End User:
Professional procurement consolidation is marginalizing independent regional distributors as factory-backed teams negotiate direct manufacturer contracts.
- Professional Drivers:FIA-homologated gear users competing in sanctioned championship series. McLaren Customer Racing and Aston Martin Racing in the United Kingdom have centralized procurement through single-source frameworks.
- Track Enthusiasts:Amateur participants requiring club-level certification for high-performance driving events. Direct-to-consumer channels attach physical suit sales to sim racing hardware convergence.
- Racing Teams:Organized squads purchasing coordinated crew apparel and driver equipment. GT3 and LMP2 programs in Germany negotiate multi-year supply agreements.
- Retail Customers:Individual buyers through e-commerce and specialty motorsport retailers. Esports competitors bypass traditional team procurement for personal sim racing setups.
Racing teams anchor the volume base while track enthusiasts expand most quickly through sim racing hardware attachment.
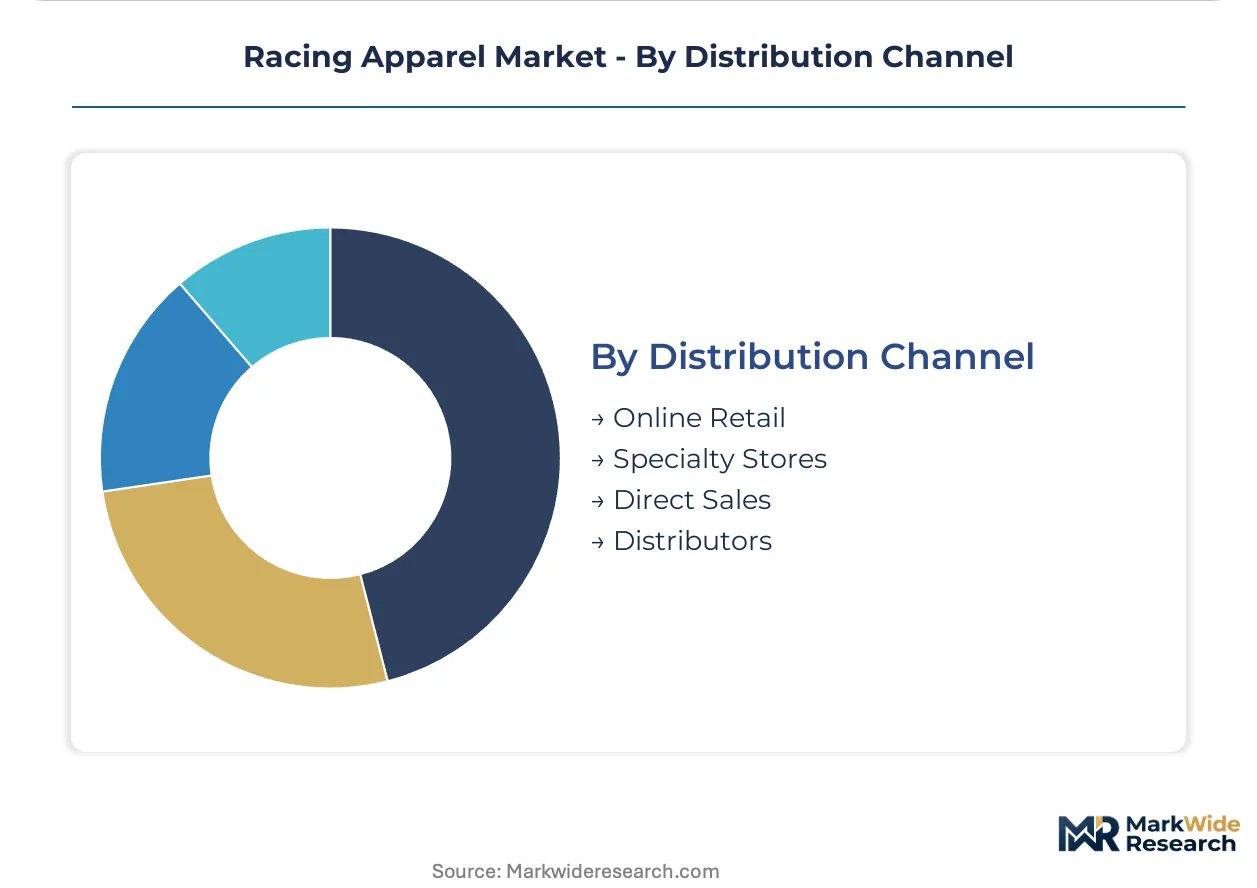
Distribution Channel:
Channel economics stratify around certification complexity, with professional tiers demanding technical consultation and amateur tiers accepting self-service purchase.
- Online Retail:Direct-to-consumer platforms capturing sim racing and enthusiast segments. Esports hardware convergence drives first-party sales bypassing traditional distributor networks.
- Specialty Stores:Motorsport-focused retailers providing fitting services and certification guidance. Physical presence concentrates in Italy around Milan and Vicenza manufacturing clusters.
- Direct Sales:Manufacturer-to-team contracting for professional category procurement. Unified bundle agreements displace independent regional distributors in the United Kingdom and Germany.
- Distributors:Wholesale intermediaries serving fragmented amateur and club racing demand. Margin compression from direct sales consolidation forces geographic specialization.
Direct sales anchor the volume base while online retail climbs the fastest through esports and sim racing attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian manufacturers command the upstream supply base for fire-resistant racing textiles, with Milan and Vicenza hosting vertically integrated production clusters that serve professional motorsport procurement worldwide. DuPont's Nomex facilities in the United States and Teijin's Twaron operations in Japan create aramid fiber dependencies that European suit makers must navigate through long-term supply contracts.
United States
NASCAR and IndyCar series drive institutional demand for SFI 3.2A-certified suits and gloves across professional and amateur categories. OSHA workplace safety regulations influence domestic production economics for coating and finishing operations. North Carolina's Charlotte-Concord corridor anchors team procurement headquarters and regional distributor networks serving the Southeast racing belt.
Germany
Factory-backed GT3 and LMP2 endurance programs generate multi-year supply agreements for homologated crew apparel and driver equipment. REACH SVHC screening requirements add 12-18 months to material qualification timelines for European manufacturers. Baden-Württemberg's Stuttgart region concentrates OEM motorsport divisions that centralize procurement through single-source frameworks.
Italy
Alpinestars, Dainese, and Sparco maintain manufacturing clusters around Milan and Vicenza with captive fabric weaving through finished suit assembly. EU Green Deal circular textile pilots in Northern Italy are generating brand differentiation through end-of-life racing suit recycling programs. The FIA's single approved homologation laboratory in France creates certification bottlenecks that Italian exporters must factor into product launch timelines.
Japan
Teijin's Twaron production facilities supply meta-aramid fiber to domestic and Asian suit manufacturers, creating regional input security for Super GT and rally programs. METI industrial standards coordinate with FIA safety mandates for export-oriented production. The Nagoya-Tokyo corridor hosts composite helmet engineering and integrated communications systems development for premium-tier head protection.
United Kingdom
McLaren Customer Racing and Aston Martin Racing have centralized procurement through direct manufacturer contracts, marginalizing independent regional distributors. The country's national workplace safety regulator enforces chemical handling standards for textile finishing operations. The Midlands motorsport engineering belt around Silverstone maintains specialist fitting services and technical consultation for professional team accounts.
Racing Apparel Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium-tier specialists commanding FIA-homologated product development while scale-oriented manufacturers serve entry-level karting and enthusiast segments through polyester-based constructions. The vendor base stratifies around certification complexity, with three to four Italian and German firms controlling professional-category supply and a fragmented tier of Asian producers absorbing cost-conscious demand. Two dominant competitive moves define current positioning: direct-to-team contracting that displaces distributor networks, and backward integration into fabric weaving to secure Nomex supply chain control.
Within the premium-tier specialist archetype, Alpinestars and Dainese represent vertically integrated Italian manufacturers with captive production capabilities spanning Northern Italy, while Sparco occupies a position exemplifying deep factory-backed team relationships across GT and rally disciplines. OMP Racing sits within the same geographic cluster, anchoring the competitive set that defines professional motorsport procurement standards. These firms collectively illustrate how FIA 8856-2018 certification requirements and REACH chemical compliance have consolidated technical expertise within established European manufacturing bases.
| Leading Market Players |
|---|
| Fox Head |
| FLY Racing |
| Alpinestars |
| AGV Sports Group |
| Sparco |
| OMP Racing |
| Adidas |
| BMW |
| Dainese |
| Others |
Supply Flow & Price Mechanics
Nomex displacement by airbag-integrated active protection systems simultaneously redraws supply geography toward Italian electronics-assembly clusters and compresses standalone suit pricing power while expanding systems-integration revenue pools. This substitution dynamic concentrates premium-tier pricing authority with vertically integrated manufacturers capable of combining fabric weaving with sensor-embedded telemetry hardware.
Pricing Analysis
FIA 8856-2018 certification dictates the pricing tier structure across professional and amateur segments. Three-tier pricing structure across premium, standard, and economy levels separates FIA-homologated suits from club-certified gear and entry-level polyester constructions. Cost compression in the economy tier is intensifying because REACH SVHC screening extends material qualification timelines. Track enthusiasts purchasing through direct-to-consumer channels exhibit highest price sensitivity, while factory-backed racing teams demonstrate lowest sensitivity given safety mandate compliance requirements.
Supply Chain Analysis
The United States and Japan anchor meta-aramid fiber production through DuPont's Nomex facilities and Teijin's Twaron operations. European suit manufacturers draw from these distant supply clusters for thermal-resistant inputs, while Italian producers around Milan and Vicenza maintain captive fabric weaving capabilities. Single-source vulnerability concentrates in France's sole FIA-approved homologation laboratory, creating certification bottlenecks. Distribution runs through direct manufacturer-to-team contracting for professional tiers and specialty motorsport retailers for amateur segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from active protection systems that merge racing apparel with telemetry infrastructure, requiring defensive repositioning around integrated safety platforms rather than standalone garments.
For Market Incumbents: Fortify upstream control over Nomex supply through long-term contracts with DuPont and Teijin, eliminating input vulnerability from trans-Pacific logistics. Expand in-house production of sensor-embedded fabric technology to capture systems-integration margins that standalone suit sales cannot match. Airbag-integrated racing suits from Dainese's D-Air platform represent the named substitute threat compressing traditional product margins. For New Entrants and Emerging Players: Lead with certified apparel distribution targeting India's Buddh International Circuit revival and FIA-backed karting academies, where first-mover advantage remains unclaimed. Attach physical suit sales to sim racing hardware convergence through direct-to-consumer channels, bypassing entrenched distributor networks that dominate European and North American procurement. Esports competitors seeking personal racing setups represent the most penetrable buyer archetype. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive fabric weaving and finished assembly capabilities. Long-term viability over the next decade hinges on regulatory compliance expertise as REACH chemical restrictions and FIA homologation standards raise barriers. Acquisition targets should demonstrate established relationships with factory-backed GT and endurance racing programs. The signal to watch is queue length at France's single approved homologation laboratory, as certification bottlenecks directly constrain revenue recognition timelines for new product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Airbag Technology Integration | D-Air and similar active protection systems merge passive Nomex barriers with real-time impact mitigation for professional drivers. |
| Backward Integration into Fabric Weaving | Alpinestars' captive production base in Northern Italy eliminates dependency on external textile suppliers for quality control. |
| Direct-to-Team Contracting | McLaren Customer Racing and Aston Martin Racing centralized procurement marginalizes independent regional distributors. |
| EU Green Deal Circular Textile Pilots | End-of-life racing suit recycling programs in Italy and Germany generate brand differentiation and regulatory goodwill. |
| Plasma-Based Finishing Line Retrofit | Vicenza manufacturers replace legacy water-repellent treatments eliminated by REACH Annex XVII perfluorinated compound restrictions. |
Methodological Framework
Cross-validation between primary interviews with racing team procurement managers, motorsport apparel R&D directors, and FIA regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FIA homologation databases, REACH SVHC substance listings, customs trade records for aramid fiber imports, and SEC filings from DuPont and Teijin. Bottom-up segmentation modeling triangulates against top-down market sizing from motorsport sanctioning body participation data.
Sensitivity analysis across certification tier, material platform, and end-user category shapes the analytical framework over the projection horizon. Modeled segmentation spans product type, material composition, end-user archetype, and distribution channel, with regional production cluster as an industry-specific dimension. CAGRs derive from regression analysis against motorsport participation rates and factory-backed team expansion patterns. Key forecast inputs include FIA 8856-2018 adoption curves and REACH chemical restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained professional motorsport investment levels or accelerated biodegradability mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding homologation laboratory capacity and aramid fiber supply stability. Specific risks that could revise projections include FIA certification queue extensions, additional REACH SVHC designations, or factory-backed team procurement consolidation acceleration. Recalibration cycles align with material shifts in regulatory enforcement patterns and motorsport OEM investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Football Merchandise Market