
 Smart Stadium Market | 2026-2036
Smart Stadium Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Stadium Market Intelligence
Multi-source vendor consolidation is consolidating procurement patterns across large venue developments. Cisco Systems leverages its networking hardware dominance to anchor connectivity layer contracts in North American arenas. Huawei Technologies competes on integrated 5G infrastructure bundles for stadium deployments across Asia-Pacific and Middle Eastern markets. IBM Corporation differentiates through AI-driven crowd analytics and predictive maintenance platforms tailored for facility operators.
Smart stadium infrastructure encompasses IoT sensor networks, edge computing nodes, and AI-powered analytics platforms engineered to process sub-second latency data streams from tens of thousands of connected endpoints. These systems enable real-time crowd flow optimization, energy load balancing, and personalized content delivery to spectator mobile devices. IoT Sensors and AI Analytics command the largest addressable segments, with Wireless Connectivity emerging as the fastest-growing technology layer as venues replace legacy distributed antenna systems with private 5G networks. Deployment patterns favor Hybrid Cloud architectures, balancing on-premises edge processing for low-latency operations with cloud-based analytics for longitudinal fan behavior modeling.
FCC spectrum allocations for private wireless networks and the EU AI Act algorithmic transparency mandates directly shape product certification requirements and procurement timelines for stadium technology vendors. ISO 27001 information security standards and GDPR data processing frameworks govern fan biometric and location data collection, constraining vendor system designs. Stakeholders must monitor evolving national cybersecurity directives and carbon disclosure regulations that will determine which integrated platform architectures qualify for public venue financing instruments.
Market Dynamics
Private 5G network deployment is compressing procurement timelines for stadium connectivity infrastructure, forcing venue operators to consolidate vendor relationships around integrated platform providers rather than point-solution specialists.
Growth Catalysts
- FCC private spectrum allocation:The FCC's Citizens Broadband Radio Service framework enables venue-owned wireless networks, eliminating reliance on carrier-managed distributed antenna systems and accelerating capital deployment for stadium-specific connectivity.
- EU AI Act compliance mandates:Algorithmic transparency requirements for biometric and crowd analytics are driving replacement cycles for legacy fan-tracking systems, creating certified-platform upgrade demand across European football venues.
- Energy management convergence:Smart grid integration requirements from facility operators are bundling IoT sensor procurement with building automation contracts, expanding addressable spend per stadium project.
Market Restraints
- Semiconductor supply concentration:Edge computing node production depends on concentrated advanced chip foundry capacity in Taiwan, exposing deployment timelines to geopolitical supply disruptions.
- GDPR biometric data friction:Facial recognition and gait analysis implementations face extended legal review periods in EU member states, delaying revenue recognition for analytics platform vendors.
- Legacy infrastructure lock-in:Stadiums with recent distributed antenna system investments face sunk-cost barriers to 5G private network migration, stretching replacement cycles.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:Neom and Qiddiya entertainment district developments represent greenfield smart stadium construction at scale, bypassing legacy integration constraints entirely.
- Carbon disclosure convergence:EU CSRD scope 3 reporting requirements are creating demand for stadium energy analytics as a service, opening recurring revenue models beyond hardware sales.
- Esports venue hybridization:Traditional sports franchises are retrofitting facilities for competitive gaming events, requiring low-latency connectivity and immersive broadcast infrastructure that exceeds standard specifications.
Industry Challenges
- Edge AI engineering scarcity:Deployment of sub-second latency analytics requires specialized machine learning operations talent that remains concentrated in technology hub labor markets.
- Multi-vendor integration complexity:Stadium operators must orchestrate connectivity hardware, sensor networks, and software platforms from disparate suppliers, creating commissioning delays and interoperability failures.
- ISO 27001 certification timelines:Fan data security requirements demand extended third-party audit cycles that compress implementation windows between sports seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Stadium Market |
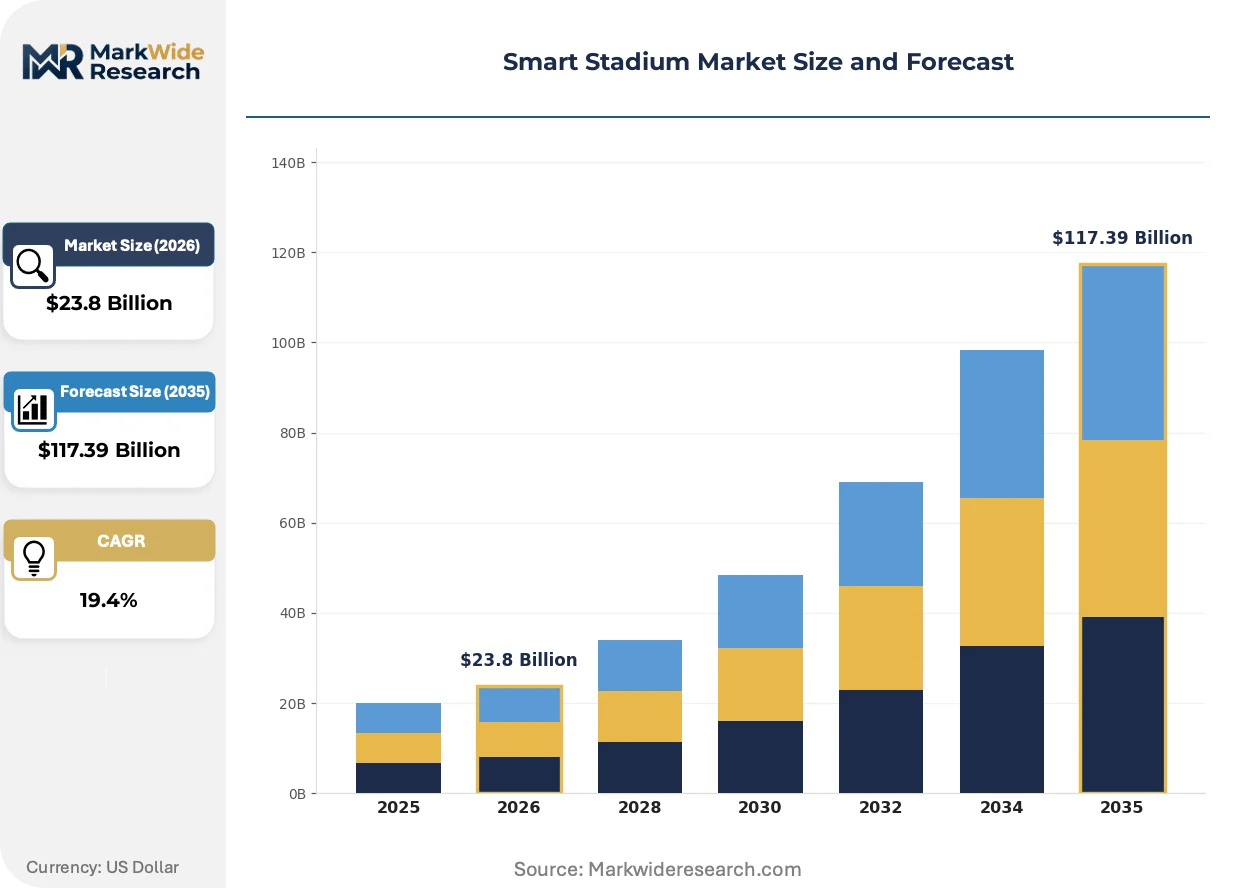
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $117.39 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, AI Analytics, Video Surveillance, Wireless Connectivity, Cloud Computing, Edge Computing Application: Fan Engagement, Security Monitoring, Facility Management, Traffic Control, Advertising & Promotions, Ticketing Systems End User: Sports Teams, Event Organizers, Venue Operators, Security Firms, Advertising Agencies, Hospitality Services Deployment: On-Premises, Hybrid Cloud, Private Cloud, Public Cloud, Managed Services, SaaS Platforms |
| Companies Covered | Johnson Controls, Huawei Technologies, Cisco Systems, Honeywell International, Intel Corporation, IBM Corporation, Schneider Electric, NXP Semiconductors, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Stadium Market Strategic Shifts & Innovations
Convergence between physical infrastructure and digital service layers is collapsing traditional procurement boundaries, with venue operators demanding outcome-guaranteed performance contracts rather than capital equipment purchases.
Digital twin technology is unifying stadium design, construction, and operational phases into continuous simulation environments. Architects and facility managers now model crowd flow, energy loads, and network traffic before breaking ground. This capability compresses commissioning timelines and reduces change-order costs. The technology is unifying previously separate vendor ecosystems around shared data models.
EU AI Act algorithmic transparency mandates are forcing biometric analytics vendors to document training data provenance and decision logic. Stadium operators deploying facial recognition for security and personalized marketing must now maintain audit trails. European football venues face the strictest compliance timelines. Vendors are responding with explainable AI modules and on-premise processing to limit data exposure.
Subscription-based service contracts are displacing perpetual license sales for crowd analytics and predictive maintenance software. Venue operators prefer operational expenditure treatment for technology investments, particularly in smaller market franchises with constrained capital budgets. This shift is most pronounced in United States minor league baseball and mid-tier college athletic facilities. Vendors are restructuring pricing around per-attendee or per-event metrics to align with this preference.
Smart Stadium Market Segmentation
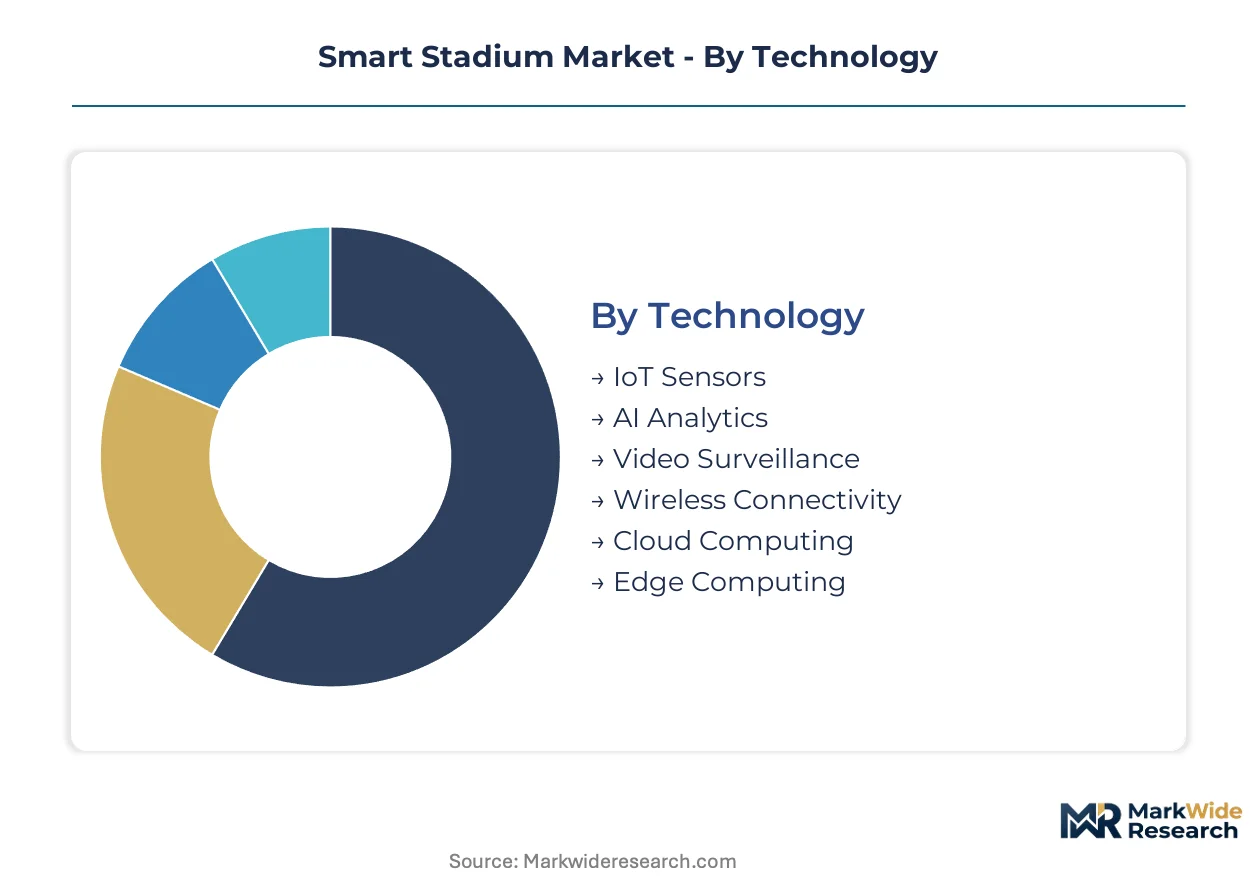
Technology procurement patterns in smart stadiums diverge sharply by operator maturity and capital availability. Venue operators select infrastructure layers based on whether they prioritize real-time operational control or longitudinal fan data monetization.
Technology:
Buyers differentiate by latency tolerance and data sovereignty requirements.
- IoT Sensors:Environmental, occupancy, and asset-tracking endpoints generate continuous telemetry streams. Demand concentrates in United States NFL and MLB venues deploying seat-level sensors for crowd density monitoring and concession queue optimization under FCC private spectrum frameworks.
- AI Analytics:Machine learning platforms process behavioral and operational data for predictive insights. European football clubs drive procurement under EU AI Act compliance mandates requiring algorithmic transparency documentation for biometric crowd analytics.
- Video Surveillance:High-definition camera networks with computer vision overlays for security and crowd management.
- Wireless Connectivity:Private 5G and Wi-Fi 6E infrastructure replacing legacy distributed antenna systems.
- Cloud Computing:Centralized data processing and storage for non-latency-sensitive workloads.
- Edge Computing:Localized processing nodes enabling sub-second response times for safety-critical applications.
Volume sits with IoT Sensors; growth tilts toward Wireless Connectivity.
Application:
Functional priority determines budget allocation between revenue-generating and cost-avoidance use cases.
- Fan Engagement:Mobile app integrations, personalized content delivery, and gamification platforms. Saudi Arabia giga-projects at Neom and Qiddiya anchor greenfield deployments specifying immersive augmented reality experiences without legacy integration constraints.
- Security Monitoring:Biometric access control, threat detection, and emergency response coordination. GDPR biometric data friction in Germany and France extends legal review periods for facial recognition implementations.
- Facility Management:HVAC, lighting, and energy system automation.
- Traffic Control:Parking, ingress, and egress flow optimization.
- Advertising & Promotions:Targeted digital signage and sponsorship activation platforms.
- Ticketing Systems:Blockchain-verified and mobile-first access solutions.
Facility Management commands the largest installed base; Fan Engagement expands most quickly.
End User:
Contracting authority varies by venue ownership structure and event frequency.
- Sports Teams:Franchise-owned technology decisions prioritizing competitive and commercial advantage. United States professional leagues dominate capital deployment with dedicated technology budgets exceeding mid-tier college athletic facilities.
- Venue Operators:Third-party facility managers serving multiple tenant events. Subscription-based service contracts are displacing perpetual licenses as these operators prefer operational expenditure treatment.
- Event Organizers:Temporary infrastructure procurement for single or seasonal engagements.
- Security Firms:Specialized contractors delivering crowd safety as a managed service.
- Advertising Agencies:Media rights holders installing activation and measurement infrastructure.
- Hospitality Services:Concession and premium experience providers deploying point-of-sale and fulfillment systems.
Sports Teams retain procurement volume; Venue Operators are gaining share fastest.
Deployment:
Architecture choice reflects data residency requirements and edge latency specifications.
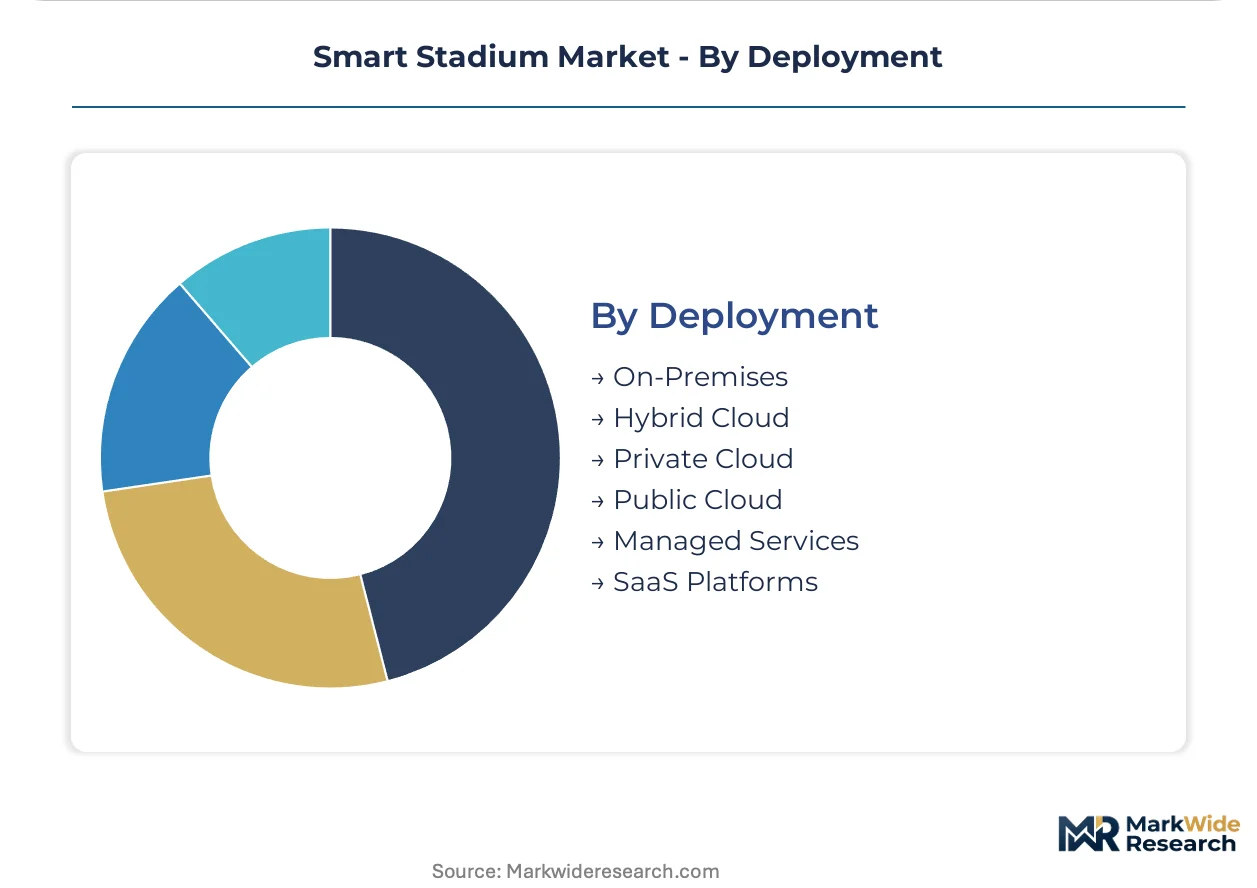
- Hybrid Cloud:Combined on-premises edge processing with cloud-based analytics. ISO 27001 certification timelines compress implementation windows between sports seasons for European venues handling GDPR-governed fan biometric data.
- On-Premises:Fully localized infrastructure eliminating third-party data exposure. Military and government-owned venues in the United States mandate this architecture under federal cybersecurity directives.
- Private Cloud:Dedicated cloud environments with single-tenant isolation.
- Public Cloud:Shared infrastructure for cost-sensitive or non-sensitive workloads.
- Managed Services:Outsourced operation and maintenance contracts.
- SaaS Platforms:Software subscription models with minimal infrastructure ownership.
Hybrid Cloud holds dominant share; SaaS Platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors semiconductor supply for edge computing nodes deployed across stadium infrastructure worldwide. Regional deployment patterns diverge sharply between mature venues retrofitting legacy systems and greenfield developments specifying integrated digital platforms from initial design.
United States
NFL and MLB franchises drive capital deployment for next-generation connectivity infrastructure. FCC Citizens Broadband Radio Service allocations enable venue-owned private 5G networks, eliminating carrier-managed distributed antenna dependencies. Texas and California stadium clusters lead procurement volume for integrated IoT sensor and AI analytics bundles.
Germany
Bundesliga venues face accelerated replacement cycles for legacy fan-tracking systems under EU AI Act algorithmic transparency mandates. KBA and federal data protection authorities extend legal review periods for biometric implementations. Munich and Dortmund industrial clusters concentrate vendor certification activity for GDPR-compliant crowd analytics platforms.
China
MIIT 5G spectrum policies and dual carbon goals shape procurement specifications for municipal venue operators. Beijing-Tianjin-Hebei and Yangtze River Delta megaprojects integrate smart grid requirements with building automation contracts. Shanghai and Shenzhen stadium developments specify domestic edge computing hardware to reduce import dependency.
Saudi Arabia
Neom and Qiddiya entertainment district developments represent greenfield smart stadium construction at scale without legacy integration constraints. SFDA and national cybersecurity frameworks govern fan data collection for biometric access systems. Riyadh and Eastern Province clusters anchor procurement for immersive augmented reality and low-latency broadcast infrastructure.
United Kingdom
Premier League operators balance GDPR biometric data friction against security modernization imperatives. The Information Commissioner's Office extends audit timelines for facial recognition deployments. London and Manchester venue clusters drive hybrid cloud architecture adoption, combining on-premises edge processing with cloud-based longitudinal fan behavior modeling.
Smart Stadium Market Key Industry Players
Global majors compete with regional champions across connectivity hardware and analytics software layers. The vendor base stratifies between integrated platform providers and point-solution specialists, with procurement consolidation favoring the former. Three archetypes dominate: networking infrastructure incumbents anchoring connectivity contracts, AI analytics specialists differentiating through predictive maintenance capabilities, and building automation conglomerates bundling energy management with sensor deployments. Competitive moves center on strategic partnerships for multi-vendor integration and geographic expansion into greenfield Middle Eastern developments.
Within the networking infrastructure tier, Cisco Systems and Huawei Technologies occupy positions reflecting their regional market access patterns. Cisco leverages its North American installed base to anchor connectivity layer contracts, while Huawei competes on integrated 5G infrastructure bundles across Asia-Pacific and Middle Eastern markets. IBM Corporation exemplifies the AI analytics archetype, differentiating through predictive maintenance and crowd flow optimization platforms. Johnson Controls and Schneider Electric represent building automation conglomerates bundling IoT sensor procurement with energy management contracts.
| Leading Market Players |
|---|
| Johnson Controls |
| Huawei Technologies |
| Cisco Systems |
| Honeywell International |
| Intel Corporation |
| IBM Corporation |
| Schneider Electric |
| NXP Semiconductors |
| Ericsson |
| Others |
Cost & Logistics Intelligence
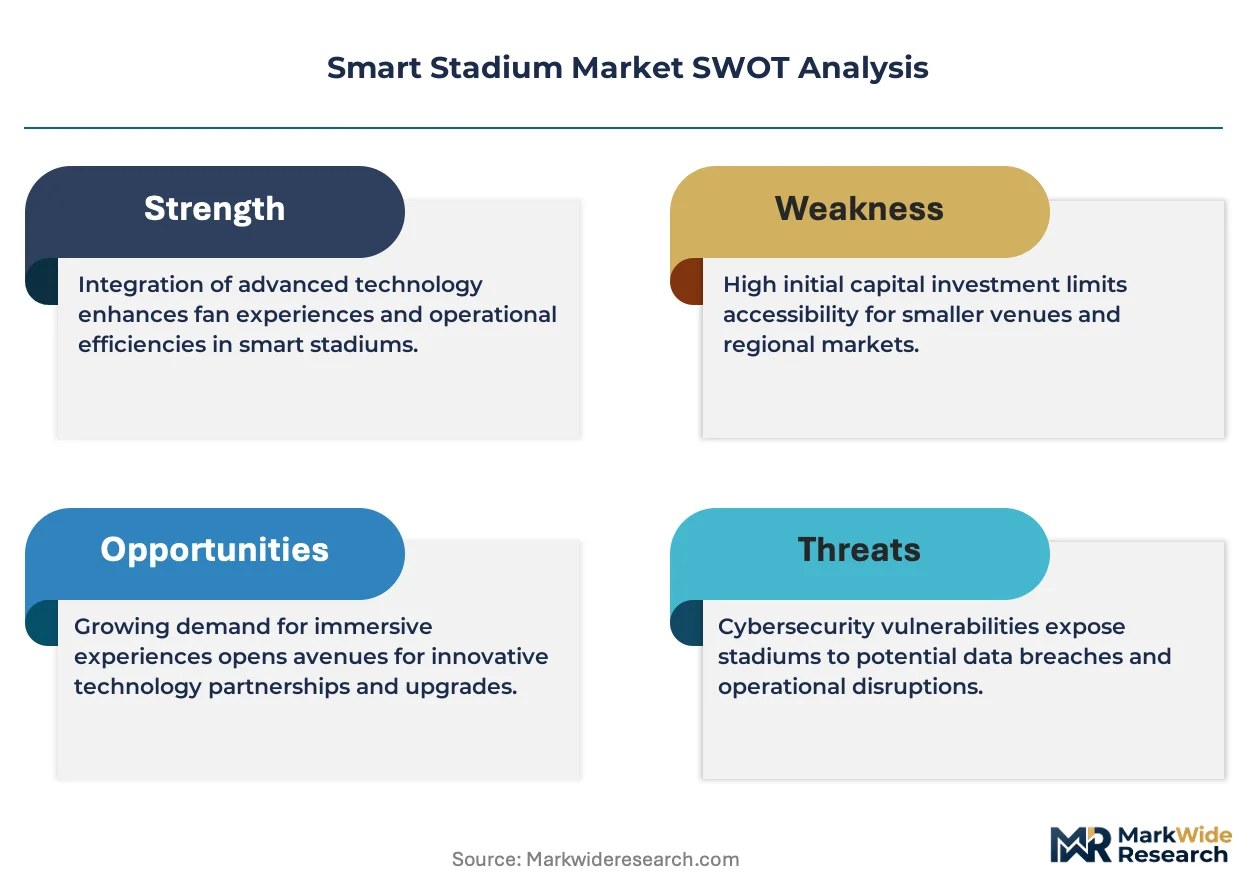
EU AI Act algorithmic transparency mandates are forcing stadium operators toward certified-platform procurement bundles, compressing vendor margins on unbundled point solutions and rewarding integrated providers with pricing power through compliance guarantees.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from standard offerings, with ISO 27001-certified platforms commanding sustained premiums over uncertified alternatives. Pricing stratifies across three tiers based on edge computing performance specifications and GDPR compliance documentation depth. Cost compression in the mid-tier is intensifying because venue operators are consolidating vendor relationships around integrated platform providers. Minor league baseball franchises and mid-tier college athletic facilities exhibit the highest price sensitivity, while NFL and MLB franchises prioritize outcome-guaranteed performance contracts over unit economics.
Supply Chain Analysis
Freight cost volatility for edge computing hardware is elevating landed costs for European and Middle Eastern deployments sourcing from Asia-Pacific manufacturing hubs. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with advanced chip foundry capacity anchoring edge node production. Raw material dependencies span silicon wafers, rare earth elements for sensor components, and lithium-ion cells for backup power systems. Single-source vulnerability in Taiwanese foundry exposure threatens deployment timelines for stadium projects with fixed commissioning windows. Distribution runs through systems integrators and direct OEM relationships with large venue developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart stadium infrastructure procurement is consolidating around integrated platform providers, with FCC private spectrum mandates and EU AI Act compliance timelines accelerating elimination of point-solution specialists lacking certification depth.
For Market Incumbents: Acquire edge AI engineering talent pools to address capability scarcity that delays sub-second latency deployments. Anchor defensive positioning through backward integration into sensor manufacturing and predictive maintenance software stacks. Threaten emerging entrants by bundling energy management contracts with connectivity infrastructure, leveraging existing building automation relationships to compress their addressable windows.
For New Entrants and Emerging Players: Begin with SaaS-native crowd analytics targeting United States minor league baseball and mid-tier college athletic facilities, where capital constraints favor operational expenditure treatment over hardware ownership. Penetrate Saudi Arabia giga-project developments at Neom and Qiddiya through greenfield specifications unburdened by legacy integration complexity. Deploy per-attendee pricing models to align with venue operator budget cycles and reduce procurement friction.
For Investors and Strategic Acquirers: The window for entry favors AI analytics specialists with explainable AI modules and GDPR-compliant on-premise processing architectures. Long-term viability hinges on regulatory certification moats rather than hardware scale. Monitor EU member state biometric data enforcement patterns as the inflection signal for platform replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies connectivity hardware, sensor networks, and analytics software under single vendor accountability. |
| Strategic Partnership | Combines Cisco networking dominance with IBM predictive maintenance for bundled NFL venue contracts. |
| Acquisition of Specialist Firm | Addresses edge AI engineering scarcity concentrated in technology hub labor markets. |
| Geographic Expansion | Captures Saudi Arabia giga-project pipeline at Neom and Qiddiya without legacy constraints. |
| Product Launch | Introduces explainable AI modules satisfying EU AI Act algorithmic transparency mandates. |
Research Approach
Multi-period observation of FCC spectrum allocation timelines and EU AI Act implementation phases anchored the trend analysis, supplemented by interviews with stadium technology procurement officers, facility operations directors, systems integration specialists, and vendor solution architects. Secondary validation drew from SEC filings of publicly traded infrastructure providers, hyperscaler edge computing capex disclosures, and municipal venue operator budget documents. Bottom-up project pipeline tracking across announced stadium developments was triangulated against top-down vendor revenue segmentation.
Segment-weighting applied differential growth assumptions across IoT Sensors, AI Analytics, and Wireless Connectivity technology layers, with deployment architecture preferences modeled across Hybrid Cloud, On-Premises, and SaaS Platforms. End-user segmentation distinguished Sports Teams, Venue Operators, and Event Organizers by contracting authority and capital availability. CAGRs were derived from installation base expansion rates and replacement cycle compression under regulatory mandates. Forecast inputs incorporated private 5G network deployment timelines and GDPR biometric data friction effects on analytics platform adoption.
Underlying measurement precision varies by segment; Wireless Connectivity and SaaS Platforms carry tighter precision than legacy distributed antenna system replacement estimates. Forecasts reflect assumptions about regulatory enforcement consistency and semiconductor supply stability that could shift with geopolitical developments or foundry capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
3D Motion Capture Market