
 Smart Swimming Caps Market | 2026-2036
Smart Swimming Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Swimming Caps Market Analytics
China is reshaping supply dynamics for smart swimming caps through expanded silicone molding capacity and integrated electronics assembly clusters in Guangdong Province. Speedo leverages its established aquatic sports distribution network to sustain premium positioning across competitive swimming channels. Arena differentiates through specialized partnerships with European national swimming federations. TYR anchors North American volume through direct relationships with collegiate athletic programs.
Smart swimming caps combine elastomeric head coverings with embedded sensor arrays, typically integrating Bluetooth Low Energy modules and waterproofed accelerometers within medical-grade silicone shells rated to IPX8 submersion standards, designed to transmit real-time stroke metrics and physiological data to poolside receivers or mobile applications. Motion sensor technology leads current shipment volumes due to lower unit costs and simpler calibration requirements, while heart rate monitoring features capture expanding margin pools as biometric accuracy improves. GPS-enabled variants remain niche given signal attenuation challenges in indoor pool environments, though open-water triathlon applications sustain specialized demand.
FDA clearance pathways for wearable health devices constrain US market entry timelines, while CE marking under the EU Medical Device Regulation shapes European product design requirements for cap-integrated heart rate monitors. China's NMPA and GB standards for electronic wearables impose additional electromagnetic compatibility testing on Bluetooth-enabled models. Stakeholders must monitor evolving data privacy frameworks governing biometric collection in public aquatic facilities and calibrate regional compliance investments against accessible addressable pools.
Market Dynamics
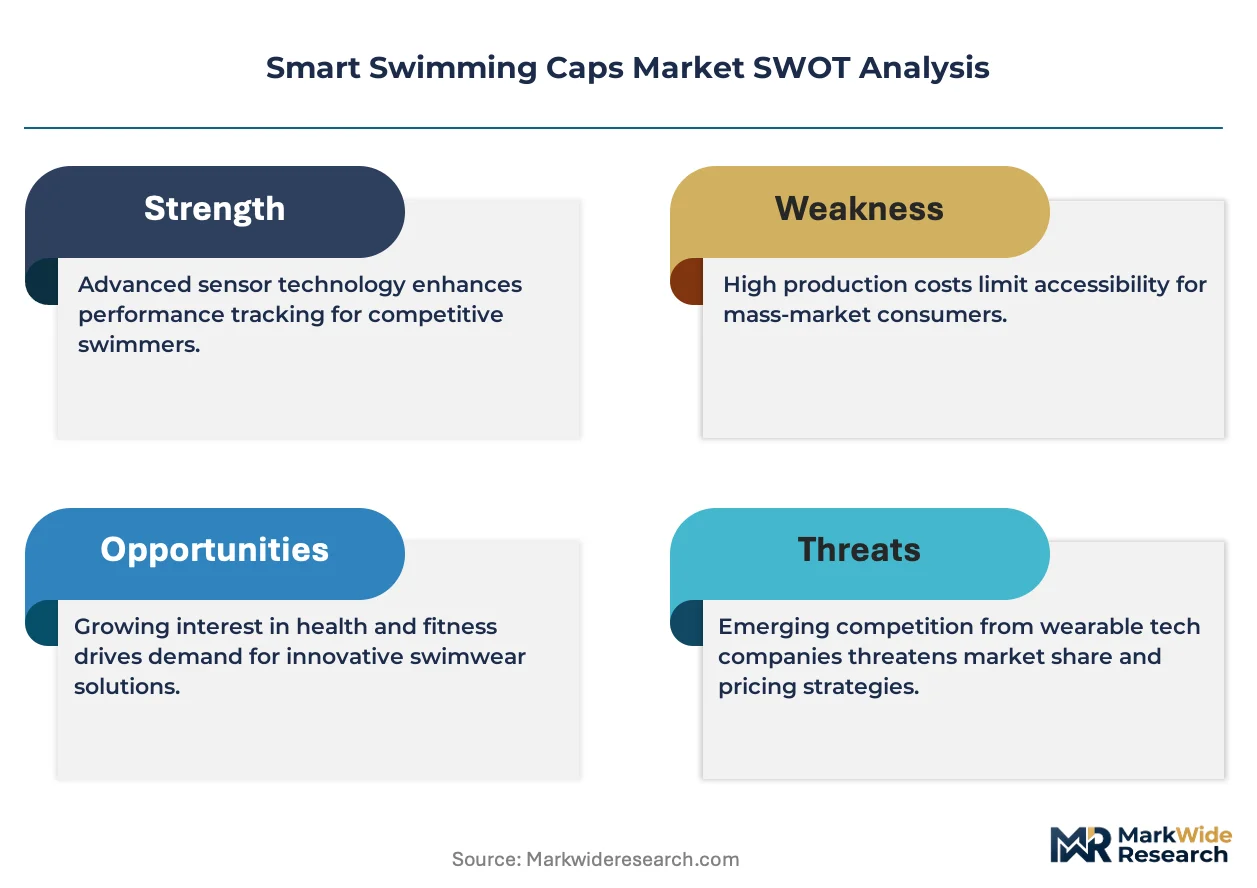
Biometric sensor miniaturization is compressing component costs while tightening IPX8 waterproofing standards are forcing redesign cycles across silicone-embedded electronics manufacturing.
Growth Catalysts
- EU AI Act compliance pathways:Wearable health device certification under the EU Medical Device Regulation is creating tiered market access that rewards early entrants with CE marking precedence.
- Guangdong electronics assembly clusters:Integrated silicone molding and Bluetooth module production is shortening lead times for cap-integrated sensor arrays.
- Municipal aquatic center procurement:Structured athlete development programs in Shanghai and Beijing are institutionalizing bulk purchasing of stroke-monitoring equipment.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations are squeezing margins on IPX8-rated elastomer shells.
- Single-source Bluetooth module dependency:Concentrated semiconductor fabrication in East Asian foundries is exposing supply chains to geopolitical disruption.
- FDA 510(k) clearance timelines:Heart rate monitoring variants face extended premarket notification periods that delay US commercialization.
Strategic Opportunities
- Open-water triathlon segment:GPS-enabled variants are penetrating endurance sports where satellite signal acquisition is unobstructed.
- Collegiate athletic program direct contracting:Bypassing retail channels through institutional procurement is capturing volume commitments.
- China dual carbon goals:Energy efficiency mandates for electronics manufacturing are accelerating domestic supplier qualification for export markets.
Industry Challenges
- Biomechanical calibration expertise scarcity:Poolside sensor validation requires specialized motion-capture engineering talent that outstrips supply.
- Cross-border data privacy fragmentation:Biometric collection in public aquatic facilities triggers divergent GDPR, HIPAA, and PIPL compliance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Swimming Caps Market |
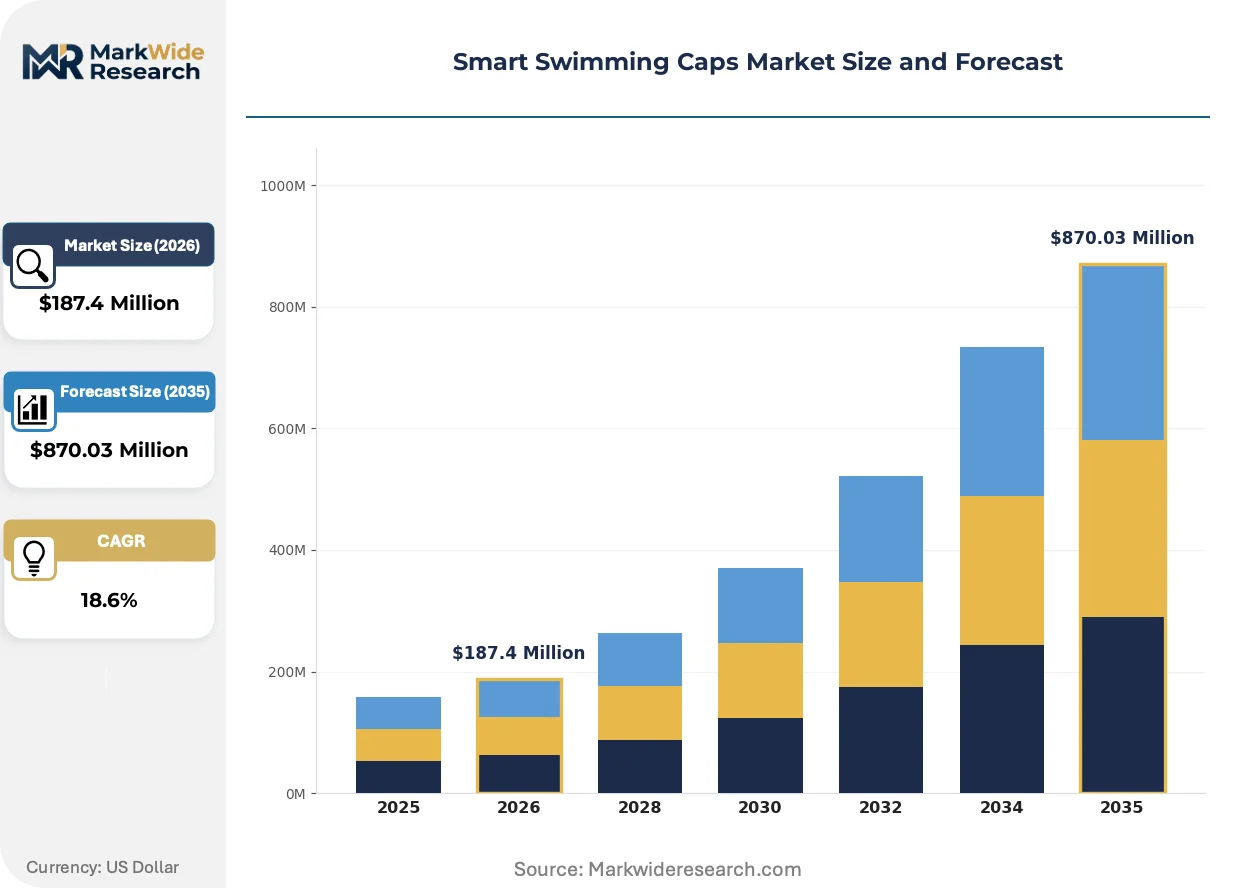
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Bluetooth, NFC, GPS, Motion Sensors End User: Professional Athletes, Amateur Swimmers, Coaches, Fitness Enthusiasts Material: Silicone, Lycra, Neoprene, Nylon Feature: Water Resistance, Heart Rate Monitoring, Speed Tracking, Communication |
| Companies Covered | TheMagic5, Orca, Speedo, ROKA, 2XU, Arena, Sporti, Blue Seventy, TYR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Swimming Caps Market Evolving Landscape
Sensor fusion architectures are redefining competitive advantage as manufacturers race to integrate multiple biometric streams within constrained power budgets.
Photoplethysmography heart rate sensing is migrating from medical-grade chest straps to cap-integrated optical arrays. Competitive swimming programs in the United States are piloting these systems for real-time lactate threshold monitoring. The technology is migrating from clinical validation studies to mass-market deployment as LED and photodiode costs fall below threshold for consumer pricing.
The EU AI Act's risk classification framework for biometric identification systems is forcing algorithmic transparency disclosures. Manufacturers must document training data provenance and performance metrics for cap-integrated stroke recognition software. European national swimming federations are demanding these disclosures as procurement preconditions, compressing vendor qualification timelines.
Direct institutional contracting is displacing traditional retail distribution for volume purchases. Collegiate athletic programs and municipal aquatic centers are negotiating multi-year sensor-as-a-service agreements. This pattern is most visible in North America where athletic department procurement autonomy exceeds centralized purchasing constraints.
Smart Swimming Caps Market Segmentation
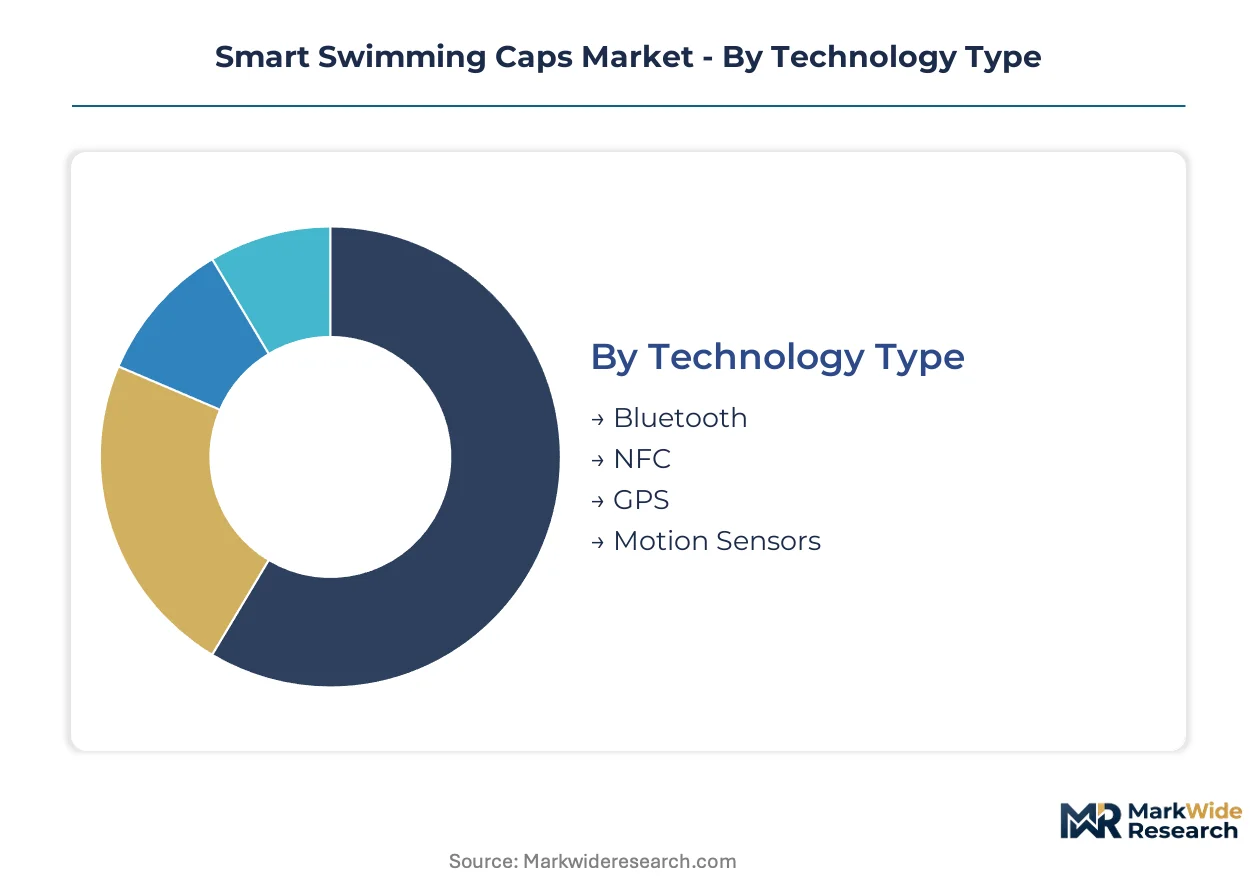
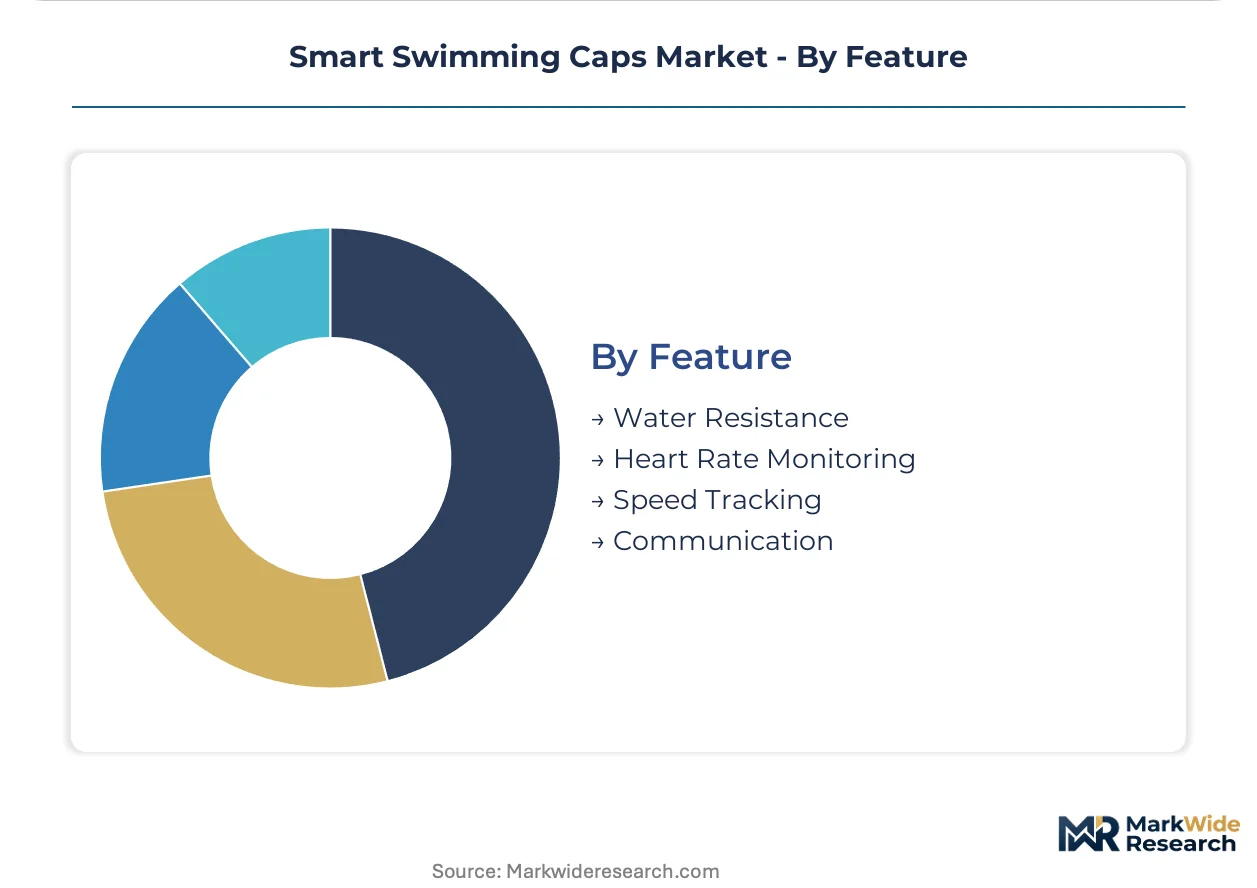
Smart swimming caps fragment across four distinct taxonomies that determine procurement pathways and margin structures. Technology type governs unit economics and waterproofing complexity. End-user segmentation separates institutional bulk purchasing from discretionary consumer spending. Material selection trades acoustic transparency against durability. Feature bundling aligns price positioning with biometric sophistication.
Technology Type:
Bluetooth modules anchor mass-market production through established supply chains in Guangdong electronics clusters. NFC occupies ultra-short-range authentication use cases. GPS variants target open-water triathlon segments where satellite acquisition remains unobstructed. Motion sensors dominate current shipment volumes due to calibration simplicity and lower semiconductor content.
- Bluetooth:Low Energy 5.0 modules integrate within medical-grade silicone shells rated to IPX8 standards. Municipal aquatic centers in Shanghai deploy Bluetooth-enabled caps for real-time stroke metric transmission to poolside receivers. Component costs are compressing as Shenzhen foundries scale BLE die production.
- Motion Sensors:Tri-axial accelerometers and gyroscopes capture stroke count, lap timing, and turn efficiency without biometric complexity. Competitive swimming programs in the United States favor this technology for its plug-and-play calibration and minimal FDA regulatory exposure compared to heart rate monitoring variants.
- NFC:Passive 13.56 MHz tags enable tap-to-authenticate pool entry and locker access without battery dependence.
- GPS:Multi-constellation receivers penetrate triathlon and open-water training where indoor signal attenuation is absent.
The dominant share belongs to Motion Sensors, while Heart Rate Monitoring (within Bluetooth architectures) is closing the gap fastest.
End User:
Procurement authority concentrates in institutional channels versus fragmented consumer retail. Volume commitments scale with program formalization and athlete roster size.
- Professional Athletes:Federations and national teams negotiate multi-year sensor-as-a-service agreements with algorithmic performance guarantees. European national swimming federations mandate EU AI Act compliance disclosures for stroke recognition software as procurement preconditions.
- Coaches:Poolside analytics platforms aggregate cap-transmitted data for technique correction and training load management. Collegiate athletic programs in North America exercise procurement autonomy that exceeds centralized purchasing constraints.
- Amateur Swimmers:Price-sensitive recreational users purchase through retail channels with limited technical support infrastructure.
- Fitness Enthusiasts:Health-tracking integration with mobile ecosystems drives replacement cycles and accessory attachment.
Professional Athletes command premium pricing, yet Coaches represent the steepest expansion trajectory as institutional contracting displaces traditional distribution.
Material:
Acoustic properties and chemical resistance determine sensor housing compatibility. Medical-grade certifications stratify pricing tiers.
- Silicone:Platinum-cured elastomer shells achieve IPX8 submersion ratings while maintaining Bluetooth signal transparency. Guangdong Province silicone molding capacity is expanding to meet sensor-embedded demand from domestic and export markets.
- Lycra:Woven spandex blends offer hydrodynamic profiles for competitive racing with minimal sensor integration depth.
- Neoprene:Thickness and thermal insulation properties suit open-water cold temperature applications.
- Nylon:Cost-optimized recreational caps sacrifice sensor embedding feasibility for disposable price points.
Silicone captures institutional procurement, though Neoprene variants are gaining share fastest among triathlon segment expansion.
Feature:
Capability bundling aligns with regulatory exposure and reimbursement potential. Biometric accuracy thresholds separate clinical-grade from consumer-grade positioning.
- Water Resistance:IPX8 certification at 2-meter depth for 30 minutes is mandatory baseline for all electronic variants. FDA 510(k) clearance timelines extend for caps claiming diagnostic-grade physiological monitoring.
- Heart Rate Monitoring:Photoplethysmography optical arrays migrate from chest straps to cap-integrated forehead positioning. Real-time lactate threshold monitoring pilots are underway in United States competitive swimming programs.
- Speed Tracking:Doppler and inertial measurement fusion calculates instantaneous velocity and distance per stroke.
- Communication:Bone conduction audio and haptic feedback enable coach-to-swimmer instruction without poolside interruption.
Water Resistance is table stakes across all tiers, while Heart Rate Monitoring is climbing the fastest as LED and photodiode costs fall below consumer pricing thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's distribution capacity for silicone-embedded electronics, while Shenzhen's Yantian container terminal anchors Asia-Pacific export throughput for Bluetooth module assembly clusters.
United States
Collegiate athletic programs in California and Texas exercise procurement autonomy for biometric training gear. FDA 510(k) clearance timelines for heart rate monitoring variants extend commercialization schedules. The Southeast manufacturing corridor in Georgia and the Carolinas hosts medical-grade silicone compounding facilities serving domestic cap production.
China
Municipal aquatic centers in Shanghai and Beijing deploy stroke-monitoring equipment for structured athlete development. NMPA electromagnetic compatibility testing and GB standards for electronic wearables regulate Bluetooth-enabled model certification. Guangdong Province's integrated silicone molding and electronics assembly clusters shorten lead times for sensor-embedded caps.
Germany
European national swimming federations headquartered in Berlin and Frankfurt mandate EU AI Act compliance disclosures for stroke recognition software. CE marking under the EU Medical Device Regulation shapes product design for cap-integrated heart rate monitors. Bavaria's precision polymer processing sector supplies medical-grade elastomer formulations to regional fabricators.
United Kingdom
Competitive swimming programs in London and Manchester pilot photoplethysmography systems for real-time lactate threshold monitoring. GDPR compliance frameworks govern biometric data collection in public aquatic facilities. The Midlands manufacturing belt concentrates silicone molding capacity for export-oriented wearable producers.
Australia
Open-water triathlon training programs along the Gold Coast and Sydney Harbour sustain GPS-enabled variant demand where satellite acquisition remains unobstructed. TGA consultation pathways for wearable health devices inform product registration strategies. Melbourne's sports technology incubator cluster supports algorithm development for stroke recognition software.
Smart Swimming Caps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and waterproofed electronics. The vendor base stratifies across three tiers: established aquatic sports brands with distribution infrastructure, sports technology specialists with biometric engineering capabilities, and contract manufacturers serving private-label programs. Two strategic archetypes dominate: federated partnership builders securing multi-year institutional contracts, and vertical specialists controlling captive silicone molding and Bluetooth module sourcing. Competitive moves concentrate on direct institutional contracting bypassing retail channels, and sensor fusion R&D integrating multiple biometric streams within power-constrained architectures.
Among heritage aquatic equipment manufacturers, Speedo International Limited and Arena S.p.A. exemplify the federated partnership archetype, while TYR Sport, Inc. occupies a position within the North American institutional procurement tier. Speedo leverages established distribution networks across competitive swimming channels. Arena differentiates through specialized relationships with European national swimming federations. TYR anchors volume commitments through direct relationships with collegiate athletic programs. These three represent divergent geographic anchoring strategies within a market where procurement authority increasingly concentrates in institutional rather than consumer channels.
| Leading Market Players |
|---|
| TheMagic5 |
| Orca |
| Speedo |
| ROKA |
| 2XU |
| Arena |
| Sporti |
| Blue Seventy |
| TYR |
| Others |
Value Network & Pricing Analysis
Undercapacity in Guangdong Province silicone molding facilities is compressing supplier lead times while elevating pricing power for medical-grade elastomer shells serving institutional procurement channels.
Pricing Analysis
CE marking under the EU Medical Device Regulation dictates the pricing tier structure across European markets, separating diagnostic-grade heart rate monitoring variants from consumer motion-sensor tiers. FDA 510(k) clearance timelines add certification premiums to US-bound inventory. Three-tier pricing structure across premium, standard, and economy levels reflects waterproofing depth, biometric accuracy, and algorithmic performance guarantees. Cost compression in standard-tier Bluetooth modules is intensifying because Shenzhen foundry capacity expansion outpaces demand absorption. Amateur swimmers exhibit highest price sensitivity, while professional athlete federations accept premium positioning for algorithmic transparency.
Supply Chain Analysis
Extended payment terms from municipal aquatic center procurement departments in Shanghai and Beijing are forcing working-capital restructuring among component suppliers. Guangdong Province, Taiwan, and South Korea anchor semiconductor and silicone supply. Medical-grade platinum-cured elastomer, Bluetooth Low Energy die, and photoplethysmography optical arrays constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundry capacity for waterproofed accelerometer modules. Distribution runs through direct institutional contracting channels that displace traditional retail intermediaries for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between cap-embedded sensor arrays and poolside analytics platforms is creating platform-economics dynamics where ecosystem lock-in supersedes standalone product differentiation.
For Market Incumbents: Pre-empt algorithmic commoditization by deepening sensor fusion R&D investments and securing exclusive data-sharing agreements with European national swimming federations. Speedo and Arena must defend against sports technology specialists by controlling captive silicone molding capacity in Guangdong. CE marking precedence and EU AI Act compliance documentation serve as regulatory moats against fast-follower entrants.
For New Entrants and Emerging Players: Establish a beachhead in collegiate athletic program direct contracting, where procurement autonomy exceeds centralized purchasing constraints and incumbent brand loyalty remains penetrable. The open-water triathlon GPS-enabled segment offers lowest competitive density and highest margin absorption for specialized entrants. Sensor-as-a-service subscription models bypass capital-intensive retail channel buildout.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heart rate monitoring variants as FDA 510(k) clearance timelines extend and photoplethysmography optical array costs compress below consumer thresholds. Acquisition targets should display vertical integration into medical-grade silicone compounding or algorithmic stroke recognition capabilities. Watch for NMPA electromagnetic compatibility testing completion as inflection signal for China market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion R&D Investment | Multi-biometric integration within IPX8 power budgets differentiates institutional-tier offerings from consumer alternatives. |
| Direct Institutional Contracting | Multi-year sensor-as-a-service agreements with Shanghai municipal aquatic centers bypass retail margin extraction. |
| EU AI Act Compliance Documentation | Algorithmic transparency disclosures satisfy European national swimming federation procurement preconditions. |
| Guangdong Silicone Molding Integration | Captive medical-grade elastomer capacity insulates against petrochemical feedstock price volatility. |
| Photoplethysmography Cost Compression | LED and photodiode pricing below consumer thresholds enables mass-market heart rate monitoring deployment. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, NMPA electromagnetic compatibility test reports, and customs trade data preceded structured interviews with biomedical engineers at municipal aquatic centers, procurement managers at collegiate athletic programs, silicone molding facility operators in Guangdong Province, and regulatory affairs leads at wearable health device manufacturers. Bottom-up shipment estimates triangulated against top-down addressable pool calculations across technology type, end user, and regional regulatory clusters.
Assumptions held fixed include IPX8 waterproofing standards, Bluetooth Low Energy module cost trajectories, and EU AI Act risk classification frameworks; variables stress-tested included medical-grade silicone price volatility, FDA clearance timeline extensions, and municipal procurement budget cycles. The analytical framework modeled technology type segmentation across motion sensors, heart rate monitoring, and GPS variants; end user segmentation across professional athletes, coaches, and recreational swimmers; and regional regulatory pathway differentiation. CAGRs derived from logistic adoption curves fitted to institutional procurement pipeline visibility.
Stress conditions across FDA 510(k) backlog severity, NMPA testing queue duration, and EU AI Act enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sensor miniaturization cost curves and institutional procurement formalization rates. Macroeconomic contraction in municipal aquatic center capital expenditure, regulatory deviation in biometric data privacy enforcement, or technological disruption in underwater communication protocols would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Padel Court Operator Market