
 Sports Team and Clubs Market | 2026-2036
Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Team and Clubs Market Insights
Corporate buyer concentration is hardening as multinational sponsors and media conglomerates consolidate their spending power across premier franchises. Manchester United FC leverages its global brand architecture to command premium partnership tiers across Asian markets. Real Madrid CF sustains competitive intensity through its in-house content production and direct-to-consumer streaming infrastructure.
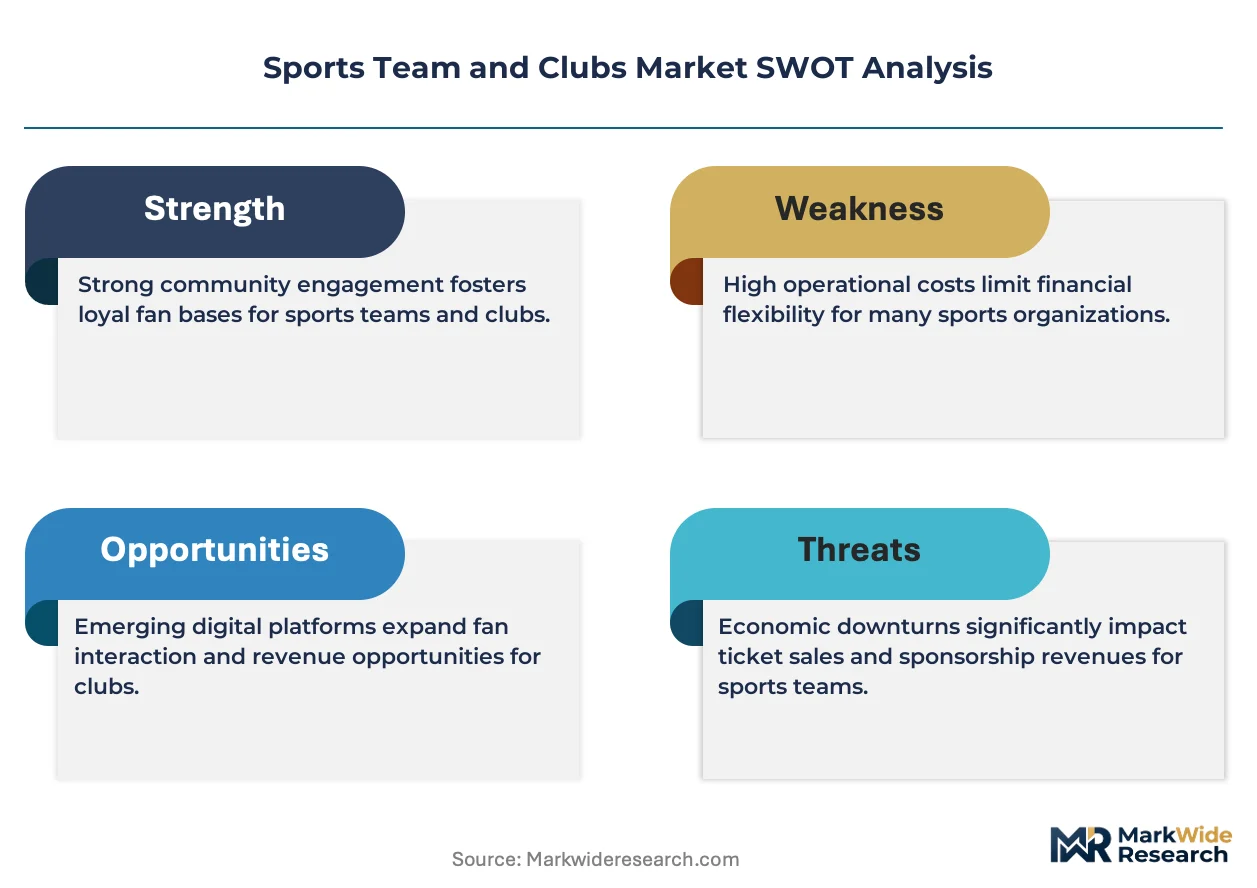
Sports teams and clubs constitute organized competitive athletic enterprises operating across professional leagues, amateur associations, and recreational membership bodies, generating commercial value through live event production, athlete performance, and audience engagement platforms with standardized governance structures. The revenue stream dimension anchors value capture, with broadcasting and sponsorship categories commanding disproportionate margin pools relative to ticket sales. Membership model segmentation differentiates access tiers, where VIP packages extract premium yields from high-net-worth patrons while family plans broaden demographic reach.
The US Federal Communications Commission shapes media rights allocation through broadcast licensing frameworks, while the European Union's Audio-Visual Media Services Directive governs cross-border content distribution standards. National tax authorities in France and Spain apply distinct athlete compensation regulations that alter club payroll structures. Stakeholders must monitor regulatory divergence across jurisdictions as digital platform expansion reconfigures traditional territorial exclusivity models.
Market Dynamics
Digital streaming infrastructure is fragmenting territorial media rights, forcing clubs to rebuild revenue architecture around direct-to-consumer platforms while legacy broadcast contracts erode. This technological displacement concentrates negotiating leverage among tech-enabled franchises with proprietary content pipelines.
Growth Catalysts
- 5G Broadcast Infrastructure:Low-latency mobile delivery enables real-time wagering integration and immersive second-screen experiences. Stadium operators in South Korea and Japan deploy these networks to capture incremental per-fan revenue.
- EU Audio-Visual Media Services Directive:Cross-border content portability rules expand addressable audience pools for clubs with established international fanbases. Spanish and Italian franchises leverage this regulatory framework to monetize diaspora communities.
- Biometric Performance Analytics:Wearable sensor arrays generate proprietary athlete data streams. Clubs commercialize these insights through fantasy sports partnerships and betting operator licensing.
Market Restraints
- Player Transfer Fee Inflation:Saudi Pro League recruitment drives wage and fee escalation across European leagues. Mid-tier clubs face margin compression as talent acquisition costs outpace broadcast revenue growth.
- Carbon Footprint Regulations:The EU Green Deal mandates emission disclosures for event travel and facility operations. Clubs with aging stadium infrastructure face accelerated depreciation and retrofit capital requirements.
- Esports Substitution:Competitive gaming captures younger demographic engagement hours. Traditional sports franchises compete for attention against lower-cost, digitally native entertainment alternatives.
Strategic Opportunities
- Indian Subcontinent Penetration:Cricket league monetization models demonstrate appetite for premium sports content. European football clubs establish localized academy networks and regional streaming partnerships.
- Blockchain Ticketing and Collectibles:Non-fungible token implementations create secondary market royalty streams. Clubs deploy these mechanisms to capture value from scalping and memorabilia trading.
- US Infrastructure Investment and Jobs Act:Facility modernization grants support stadium technology upgrades. Franchises integrate these funds with private capital to deploy cashless commerce and enhanced security systems.
Industry Challenges
- Data Science Talent Scarcity:Clubs compete with technology firms for analytics professionals capable of extracting actionable insights from proprietary performance databases.
- Multi-Jurisdiction Tax Compliance:Athlete compensation structures span national tax regimes with conflicting residency and image rights treatments. Payroll administration complexity escalates with international roster composition.
- Legacy Stadium System Integration:Older venues require costly retrofitting to support modern broadcast, connectivity, and fan experience technologies. Capital allocation trade-offs emerge between competitive squad investment and infrastructure modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Team and Clubs Market |
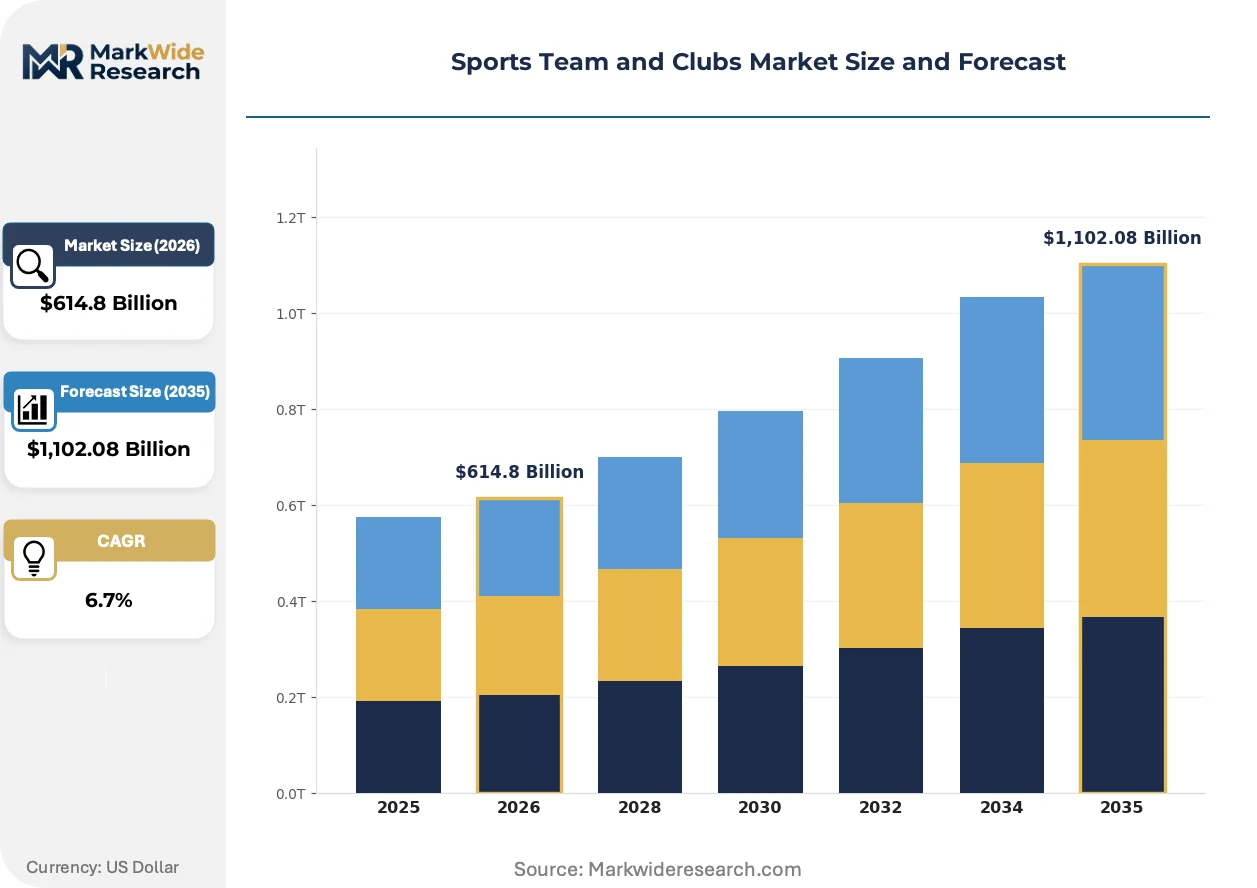
| Market Size in 2026 | $614.8 Billion |
| Market Size in 2035 | $1,102.08 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Fans, Sponsors, Members, Participants Revenue Stream: Tickets, Merchandise, Sponsorships, Broadcasting Service Type: Events, Training, Coaching, Community Programs Membership Model: Annual Passes, Seasonal Memberships, VIP Packages, Family Plans |
| Companies Covered | Manchester United FC, Real Madrid CF, FC Barcelona, New York Yankees, Los Angeles Lakers, Dallas Cowboys, Golden State Warriors, Paris Saint-Germain FC, Bayern Munich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Team and Clubs Market Trends and Innovations
Artificial intelligence applications are penetrating athlete development, fan engagement, and commercial operations simultaneously. Clubs that integrate these capabilities across functional boundaries capture compounding efficiency gains.
Computer vision and machine learning analytics are overtaking traditional scouting and performance evaluation methods. Premier League and Bundesliga clubs deploy these systems to quantify tactical patterns and injury risk indicators. The technology compresses decision cycles in transfer negotiations and enables predictive roster construction.
The EU's Corporate Sustainability Reporting Directive imposes granular disclosure requirements on large clubs operating as publicly accountable enterprises. Spanish and German franchises must now report environmental and social governance metrics with audit-grade rigor. This regulatory pressure is accelerating the appointment of dedicated sustainability officers and third-party certification of supply chain practices.
Subscription fatigue is compressing willingness to pay for multiple standalone streaming services. Younger demographics in Brazil and Mexico demonstrate preference for aggregated sports packages bundled with broadband and mobile contracts. Clubs respond by negotiating carriage through telecommunications platforms rather than direct-to-consumer exclusivity.
Sports Team and Clubs Market Segmentation
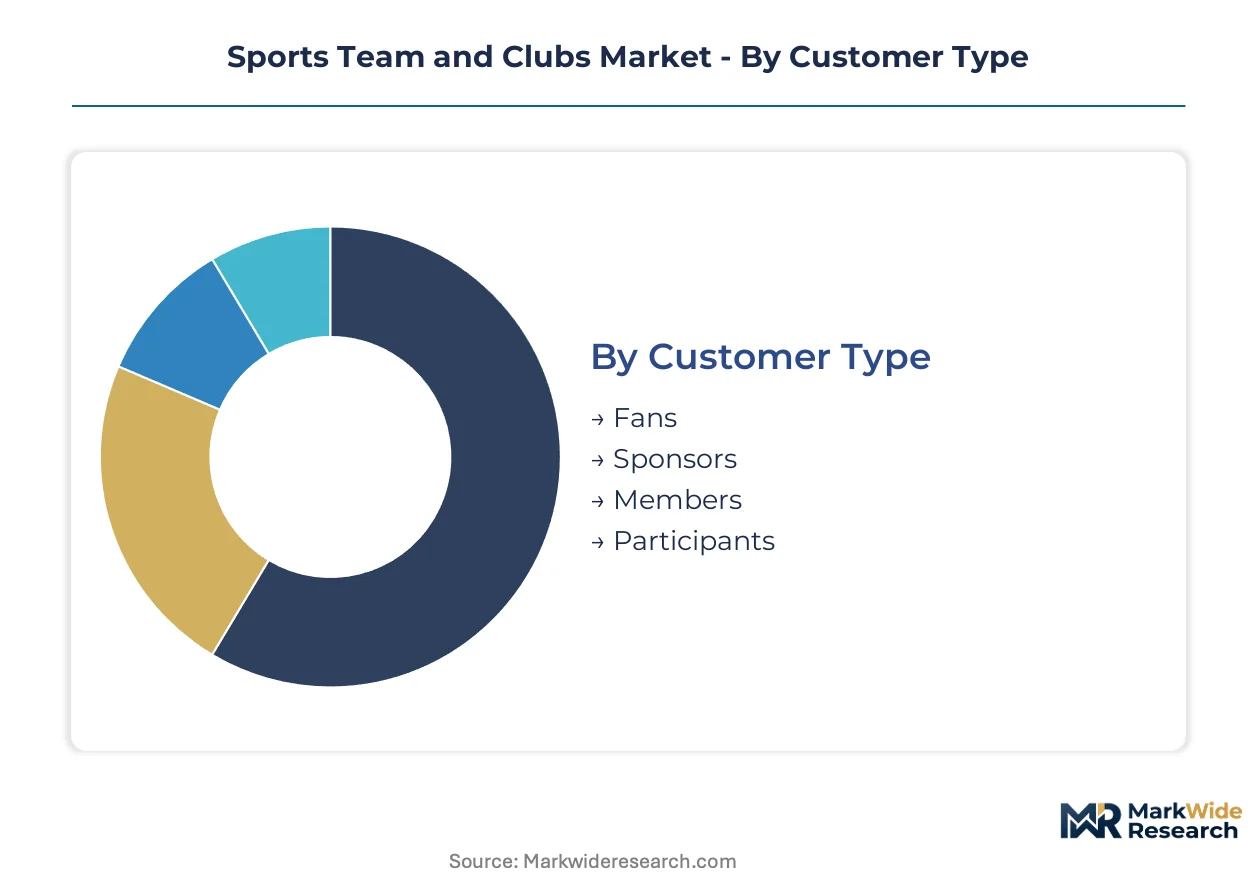
Revenue architecture in sports teams and clubs varies dramatically by how value is captured and from whom. Segmentation reveals where margin pools concentrate and where franchise investments yield differential returns.
Customer Type:
Standardized mass-market relationships contrast with bespoke corporate partnerships across this spectrum.
- Fans:Individual ticket purchasers and media consumers form the volume base. Demand concentrates in metropolitan markets with strong franchise heritage, where digital engagement platforms now supplement traditional attendance.
- Sponsors:Corporate hospitality buyers negotiate multi-year partnership tiers with category exclusivity. Multinational conglomerates consolidate spending across premier leagues, commanding premium asset placement and data access rights.
- Members:Recurring subscription relationships provide predictable revenue streams. English football clubs and Australian rugby franchises leverage these models to reduce matchday dependency.
- Participants:Amateur athletes and recreational league members access training infrastructure and competitive pathways. Community-based demand in Germany and Japan supports club academy networks.
Leading the category by volume: Fans. Growing fastest: Sponsors.
Revenue Stream:
Margin concentration shifts toward intangible assets as physical distribution erodes.
- Tickets:Matchday admissions and venue access generate per-event cash flows. Stadium operators in Spain and Italy face capacity constraints that limit growth, driving investment in dynamic pricing algorithms.
- Merchandise:Branded apparel and licensed products extend fan relationships beyond matchdays. Asian manufacturing partnerships and direct-to-consumer e-commerce reshape traditional retail distribution.
- Sponsorships:Naming rights, kit partnerships, and hospitality packages command the highest margin multiples. Saudi sovereign wealth vehicles and Asian consumer electronics brands now compete for premium placement against established European automotive and financial services sponsors.
- Broadcasting:Territorial media rights and streaming carriage fees anchor long-term valuation. The FCC's licensing frameworks in the United States and the EU's Audio-Visual Media Services Directive reshape how clubs monetize cross-border content portability.
Broadcasting delivers the highest margin capture. Sponsorships are climbing the fastest as new capital sources enter the market.
Service Type:
Core competitive product differentiation separates from ancillary community programming.
- Events:Live match production and stadium experiences constitute the primary value proposition. Brazilian and Mexican clubs invest in immersive technology to combat broadcast substitution effects.
- Training:Professional athlete development and facility access represent high-fixed-cost infrastructure. Biometric performance analytics from wearable sensors now differentiate elite academy offerings.
- Coaching:Individual instruction and skill development programs serve participant segments. German and Dutch club systems integrate coaching certification with membership retention.
- Community Programs:Social outreach and grassroots engagement build long-term fan pipelines. Regulatory pressure from the EU Corporate Sustainability Reporting Directive elevates these programs from marketing expense to disclosed social impact asset.
Events dominate revenue contribution. Training programs show steepest expansion trajectory as data monetization opportunities emerge.
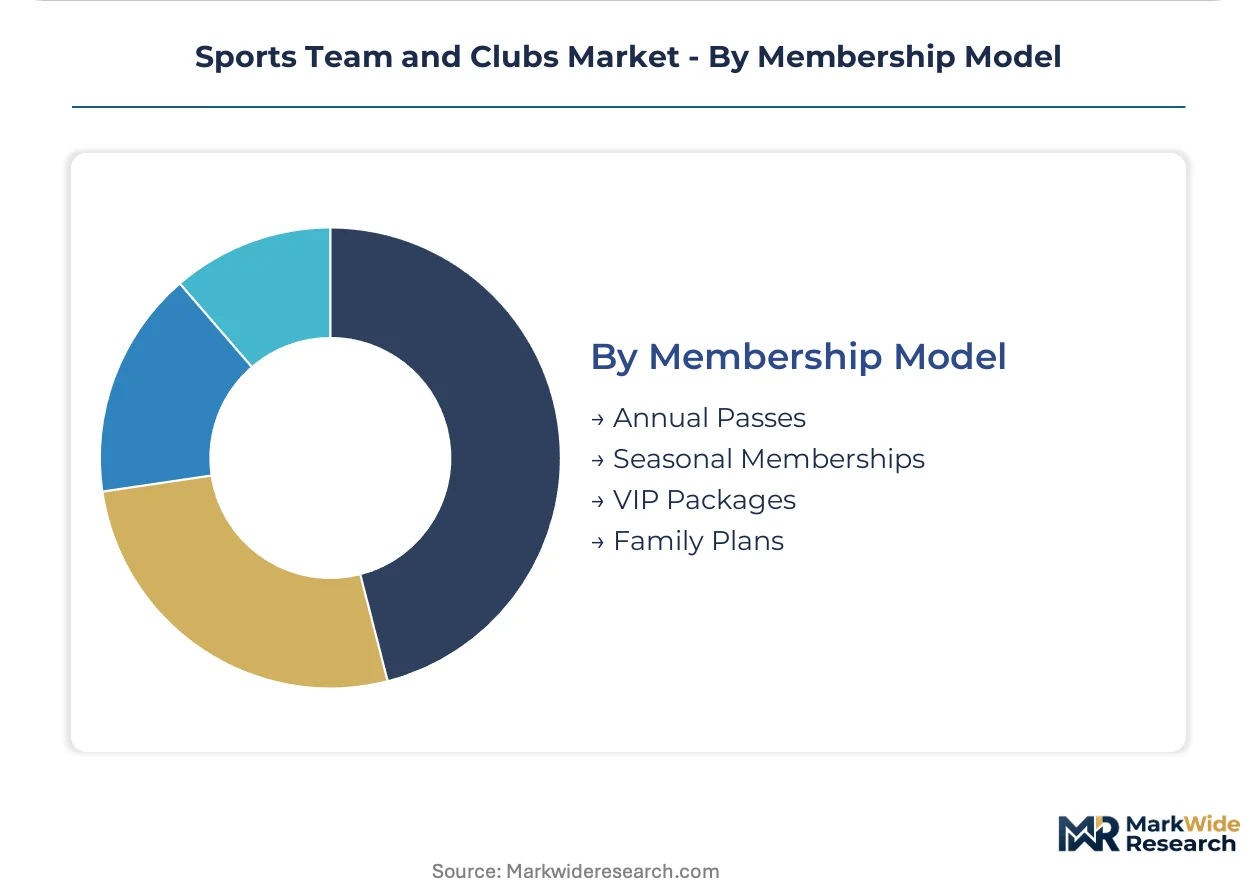
Membership Model:
Access tiering extracts differential willingness-to-pay across household types.
- Annual Passes:Year-round venue and content access for committed supporters. French and Spanish clubs use these to secure baseline revenue before seasonal performance uncertainty resolves.
- Seasonal Memberships:Fixed-term packages aligned with competitive calendars. Australian and Japanese leagues structure these around shorter season formats than European football.
- VIP Packages:Premium hospitality with dedicated concierges and exclusive experiences. High-net-worth patrons in the United States and Gulf markets sustain pricing power despite broader economic sensitivity.
- Family Plans:Multi-person pricing broadens demographic reach and cultivates intergenerational loyalty. Brazilian and Indian market penetration strategies prioritize these formats for middle-class expansion.
VIP Packages command highest per-capita yield. Family Plans are gaining share fastest as clubs pursue audience base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where franchise valuations and media rights command premium positioning. European football clubs leverage cross-border content portability to monetize diaspora communities. Asian markets demonstrate appetite for premium sports content through cricket league monetization models.
United States
Corporate hospitality buyers consolidate purchasing power across major leagues, driving sponsorship revenue concentration. The FCC shapes media rights allocation through broadcast licensing frameworks. Stadium operators in Texas and California deploy cashless commerce and enhanced security systems using Infrastructure Investment and Jobs Act funds.
Spain
Franchises sustain competitive intensity through in-house content production and direct-to-consumer streaming infrastructure. The EU Audio-Visual Media Services Directive governs cross-border content distribution standards for diaspora outreach. Madrid and Barcelona clubs leverage biometric performance analytics from wearable sensors to commercialize athlete data streams.
Germany
Community-based demand supports club academy networks with integrated coaching certification. The EU Green Deal mandates emission disclosures for event travel and facility operations. Bavarian franchises face accelerated depreciation and retrofit capital requirements for aging stadium infrastructure.
United Kingdom
English football clubs leverage membership models to reduce matchday dependency and secure baseline revenue. The EU Corporate Sustainability Reporting Directive elevates community programs from marketing expense to disclosed social impact asset. Manchester-based franchises command premium partnership tiers across Asian markets through global brand architecture.
India
European football clubs establish localized academy networks and regional streaming partnerships to penetrate the subcontinent. The country's national sports regulator oversees league formation and foreign investment frameworks. Mumbai and Delhi clusters demonstrate appetite for premium sports content through cricket league monetization models.
Sports Team and Clubs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue esports substitution and digital-native entertainment alternatives. The vendor base concentrates around premier franchises with proprietary content pipelines and global brand architecture. Three archetypes dominate: tech-enabled franchises with direct-to-consumer platforms, heritage clubs with diaspora monetization capabilities, and conglomerate-backed teams with sovereign wealth sponsorship. Competitive moves center on strategic partnerships for streaming carriage and portfolio diversification into training program monetization.
Within the heritage club tier, Manchester United FC and Real Madrid CF exemplify franchises that have built global brand architecture to command premium partnership tiers. FC Barcelona occupies a position representing the in-house content production archetype with direct-to-consumer streaming infrastructure. Among US-based franchises, the New York Yankees and Los Angeles Lakers anchor the corporate hospitality concentration model, while the Dallas Cowboys and Golden State Warriors sit within the tech-enabled stadium experience segment.
| Leading Market Players |
|---|
| Manchester United FC |
| Real Madrid CF |
| FC Barcelona |
| New York Yankees |
| Los Angeles Lakers |
| Dallas Cowboys |
| Golden State Warriors |
| Paris Saint-Germain FC |
| Bayern Munich |
| Others |
Pricing and Supply Chain Analysis
Elite data science talent concentration in the United States and United Kingdom widens pricing-tier spreads between tech-enabled franchises and legacy operators, as labor-cost differentials in analytics capabilities force mid-tier clubs toward standard membership pricing while premium franchises extract VIP yields from proprietary performance insights.
Pricing Analysis
Volume concentrates in mass-market ticketing and family memberships while margin pools accumulate in sponsorships and broadcasting rights. Three-tier pricing structure across premium hospitality, standard season access, and economy single-match tiers differentiates by venue location and digital content bundling. Cost compression in mid-tier broadcast packages is intensifying because subscription fatigue compresses willingness to pay for multiple standalone streaming services. Price sensitivity runs highest among younger demographics in Brazil and Mexico, while Gulf market high-net-worth patrons sustain VIP pricing power despite broader economic sensitivity.
Supply Chain Analysis
Reverse-logistics flows for merchandise returns and memorabilia authentication reshape inventory management as blockchain-verified collectibles create secondary market royalty capture. Manufacturing concentrates in Bangladesh, Vietnam, and China for branded apparel, while content production infrastructure clusters in Spain, the United States, and South Korea for streaming delivery. Raw material dependencies span polyester textiles, semiconductor components for stadium connectivity, and rare earth elements for broadcast transmission equipment. Single-source vulnerability in Asian manufacturing partnerships elevates tariff exposure for European and North American clubs. Distribution runs through telecommunications platforms rather than direct-to-consumer exclusivity as carriers bundle sports content with broadband and mobile contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Corporate Sustainability Reporting Directive imposes audit-grade disclosure requirements that create a compliance moat for clubs with dedicated sustainability infrastructure, raising capital barriers for entrants lacking ESG certification capabilities.
For Market Incumbents: Extend proprietary content pipeline investments to defend against esports substitution effects capturing younger demographic engagement hours. Deepen biometric performance analytics capabilities to commercialize athlete data streams through fantasy sports partnerships and betting operator licensing. Fortify diaspora monetization infrastructure in the Indian subcontinent before European competitors establish localized academy networks. For New Entrants and Emerging Players: Enter via training program monetization in Germany and Japan, where community-based demand supports club academy networks with integrated coaching certification. Target family plan penetration in Brazilian and Indian middle-class segments as the most penetrable access tier. Pursue regional streaming partnerships rather than direct-to-consumer platform builds to minimize upfront capital requirements. For Investors and Strategic Acquirers: The window for entry favors tech-enabled franchises with direct-to-consumer infrastructure and established international fanbases before legacy broadcast contracts fully erode. Long-term viability hinges on proprietary content pipelines and data monetization capabilities rather than stadium asset ownership. Monitor Saudi sovereign wealth sponsorship flows as an inflection indicator for sponsorship revenue concentration and talent acquisition cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Captures margin erosion from legacy broadcast contract displacement through proprietary streaming infrastructure. |
| Biometric Data Partnership | Commercializes wearable sensor insights through fantasy sports operators and wagering platforms. |
| Sustainability Certification Investment | Secures EU Green Deal compliance advantage and elevates community programs to disclosed social impact assets. |
| Regional Academy Network Expansion | Establishes localized talent pipelines and streaming partnerships in Indian subcontinent growth markets. |
| Blockchain Ticketing Implementation | Captures secondary market value from scalping and memorabilia trading through non-fungible token mechanisms. |
Research Methodology
Multi-period observation of franchise valuation trajectories, media rights contract structures, and sponsorship concentration patterns anchored the trend analysis, supplemented by interviews with club commercial directors, stadium operations executives, broadcast licensing specialists, and fantasy sports platform managers. Secondary validation drew from FCC broadcast licensing databases, EU Audio-Visual Media Services Directive implementation records, SEC filings for publicly traded franchises, and customs data on merchandise trade flows. Bottom-up revenue modeling across ticketing, sponsorship, broadcasting, and merchandise categories triangulated against top-down league financial aggregates.
Input-output matrices mapped demand drivers across customer type, revenue stream, and membership model dimensions throughout the forecast period. Segmentation modeling captured variation by fan versus sponsor versus participant relationships, events versus training versus community programming service types, and VIP versus family plan access tiers. CAGRs derived from trend extrapolation of digital streaming penetration rates, sovereign wealth sponsorship inflows, and 5G broadcast infrastructure deployment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios or accelerated esports substitution. Practitioners should monitor Saudi Pro League recruitment intensity, EU emission disclosure enforcement rigor, and telecommunications platform carriage negotiation dynamics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
India Sports Team and Clubs Market