
 UK Spectator Sports Market | 2026-2036
UK Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
UK Spectator Sports Market Insights
The UK government's net-zero stadium targets is decoupling legacy venue economics from carbon-intensive operations, compelling operators to retrofit or rebuild. Tottenham Hotspur leverages its sustainable stadium design to command premium pricing and non-matchday revenue. Manchester United anchors its commercial strategy through global brand licensing and controlled hospitality tiers. Formula 1 competes for domestic broadcast attention against football's seasonal dominance.
UK spectator sports encompass live attendance, broadcast consumption, and associated commercial engagement across professional and semi-professional competitions, where digital streaming infrastructure and real-time data overlays now constitute baseline technical requirements for rights holders. The primary purpose is to aggregate audience attention for monetization through ticketing, media distribution, and brand association. Football within sport type captures the dominant share of revenue and infrastructure investment, while media rights as a revenue source generates the highest margin pools due to multi-year exclusivity contracts. Sponsorship segments face pressure as brands demand measurable digital engagement metrics alongside traditional pitchside visibility.
The Sports Grounds Safety Authority and the UK Gambling Commission shape operational standards and advertising boundaries respectively, with the former dictating crowd capacity limits and the latter restricting betting sponsorship prominence on matchday assets. The Competition and Markets Authority scrutinizes collective selling arrangements for media rights, influencing how leagues package and distribute content. Stakeholders must monitor evolving gambling advertising restrictions and their cascading impact on club sponsorship pipelines.
Market Dynamics
The Sports Grounds Safety Authority's infrastructure mandates are forcing simultaneous stadium retrofit investments across multiple tiers of English football, compressing capital deployment timelines and reshaping venue economics.
Growth Catalysts
- Premier League hospitality tiering:Corporate buyers are purchasing experiential packages at London and North West venues, converting matchday attendance into multi-year commercial relationships.
- Net-zero stadium retrofit mandates:UK government carbon targets are compelling operators to replace legacy systems with low-carbon alternatives, unlocking green financing instruments for venue upgrades.
- Digital overlay infrastructure:Real-time data and streaming capabilities are becoming baseline technical requirements for rights holders, driving technology procurement across EFL and non-league grounds.
Market Restraints
- Construction cost volatility:Steel and concrete input price fluctuations are inflating stadium development budgets, particularly affecting Championship clubs pursuing Premier League promotion.
- Broadcast rights concentration:Collective selling arrangements face Competition and Markets Authority scrutiny, limiting league flexibility in packaging media rights for emerging platforms.
- Gambling sponsorship substitution:UK Gambling Commission advertising restrictions are forcing clubs to replace betting brands with lower-yield alternatives, compressing commercial revenue pools.
Strategic Opportunities
- Non-matchday venue activation:Tottenham Hotspur's stadium design demonstrates revenue diversification through conference and concert programming, a model replicable at underutilized grounds.
- North West transport corridor expansion:Manchester and Liverpool's improved rail connectivity supports higher away-fan attendance and midweek fixture viability.
- Carbon accounting integration:CSRD-aligned disclosure requirements are creating first-mover advantages for venues with verified emissions data, attracting ESG-mandated institutional capital.
Industry Challenges
- Specialized retrofit engineering scarcity:Stadium carbon retrofit projects require building physics expertise that outstrips current UK contractor capacity, extending project timelines.
- Legacy ticketing system integration:New digital engagement platforms must interface with decades-old access control infrastructure, creating data synchronization failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Spectator Sports Market |
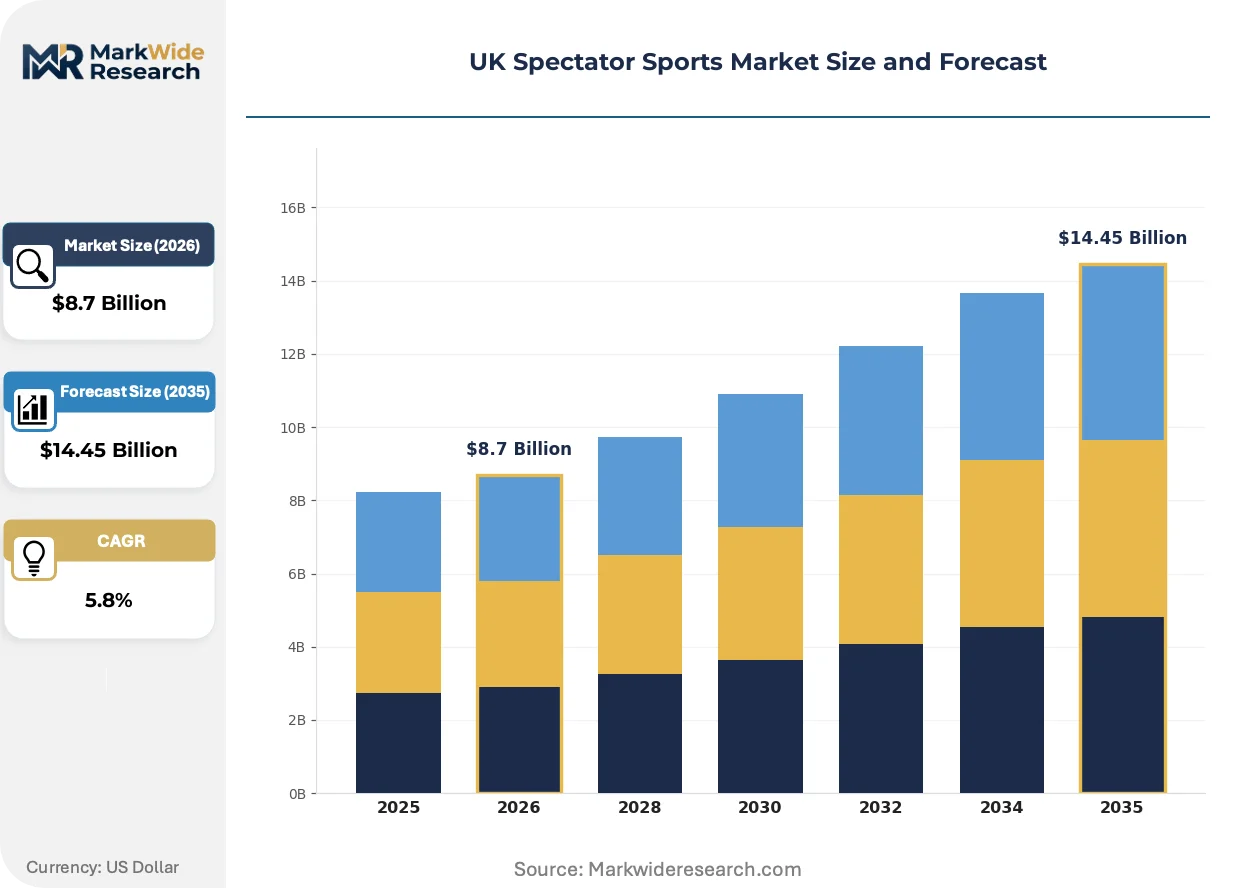
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Football, Rugby, Cricket, Tennis Event Size: Local, Regional, National, International Revenue Source: Ticket Sales, Sponsorship, Media Rights, Merchandise Audience Demographic: Families, Young Adults, Seniors, Students |
| Companies Covered | Tottenham Hotspur, IMG Media Limited, Formula 1, The Premier League, Football Association Limited, Manchester United, Arsenal Football Club, EFL (English Football League), Chelsea FC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Spectator Sports Market Trends and Innovations
Digital infrastructure deployment is overtaking physical capacity expansion as the primary investment priority for UK venue operators, with streaming capabilities and real-time fan engagement tools commanding capital allocation previously reserved for seating increases.
Immersive augmented reality overlays are overtaking static scoreboard displays as the dominant matchday information delivery mechanism. Mid-tier clubs in the Championship and League One are deploying smartphone-integrated AR to compensate for smaller video screen footprints. This compression of hardware requirements is enabling smaller venues to deliver Premier League-equivalent fan experiences without comparable capital expenditure.
The UK Gambling Commission's 2023 shirt sponsorship restrictions are forcing commercial strategy recalibration across the EFL. Clubs must now secure replacement partners from sectors with lower marketing budgets, narrowing the sponsorship pipeline. London-based Premier League clubs with established global brand licensing operations are absorbing this friction more readily than regional counterparts dependent on single-source commercial income.
Younger demographics are abandoning season-ticket commitments in favor of flexible membership schemes with digital-only benefits. Streaming platforms and last-minute resale marketplaces are displacing traditional box office relationships as the primary purchase channel. This behavioral pivot is most pronounced in Greater Manchester and the West Midlands, where transport infrastructure supports spontaneous attendance decisions without advance planning.
UK Spectator Sports Market Segmentation
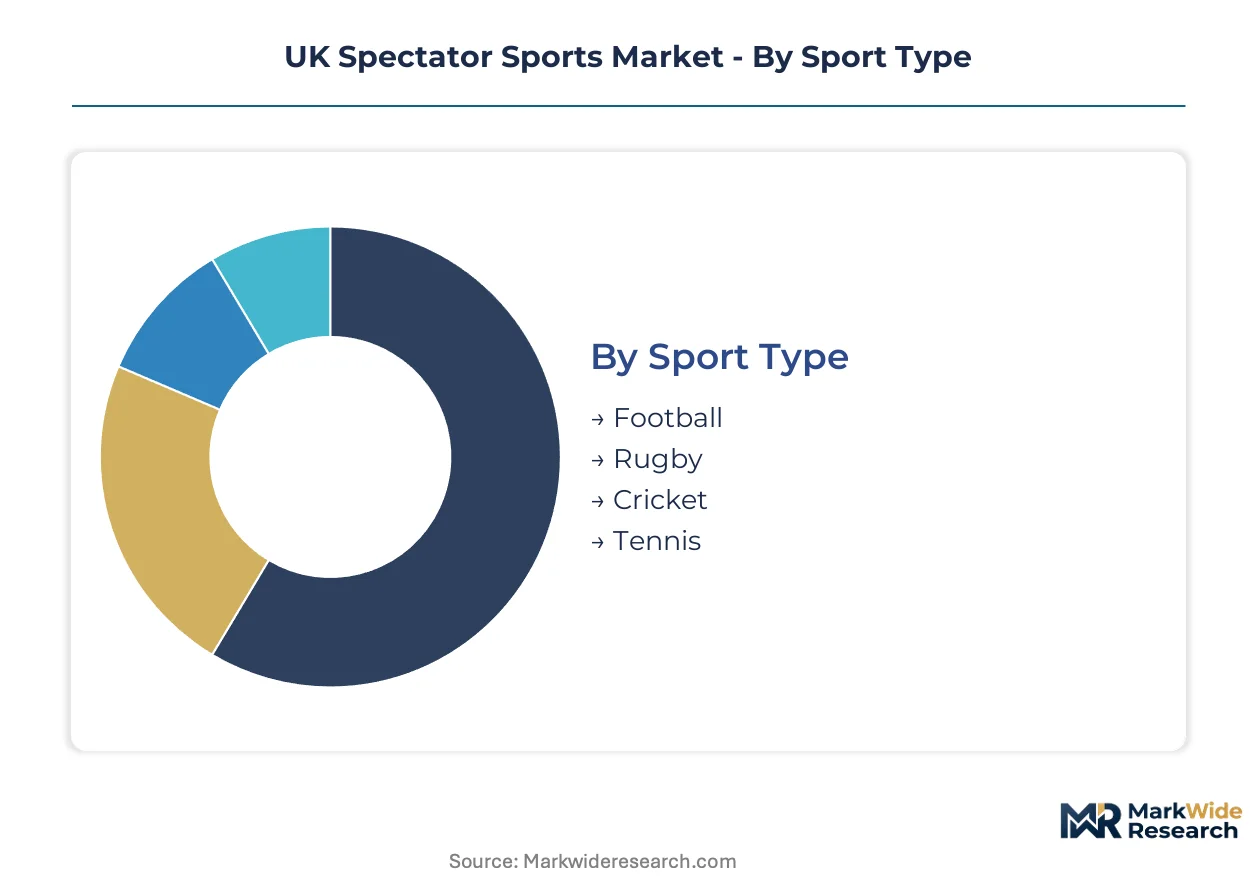
Segmentation in UK spectator sports reveals how distinct buyer motivations and consumption contexts create parallel revenue streams. Each dimension—sport type, event scale, revenue channel, and audience cohort—commands differentiated commercial strategies and infrastructure investments.
Sport Type:
Club allegiance and seasonal rhythm drive purchasing behavior across disciplines, with football's weekly fixture density creating fundamentally different engagement economics than intermittent national events.
- Football:Premier League and EFL fixtures generate sustained weekly demand through tribal supporter identities. London and North West club density concentrates matchday revenue, where transport infrastructure sustains highest attendances.
- Rugby:Premiership and Six Nations tournaments operate on compressed seasonal windows with premium hospitality positioning. Twickenham and regional club grounds capture corporate entertainment budgets through bundled experiential packages.
- Cricket:County Championship and The Hundred format innovations target family attendance with shorter session lengths.
- Tennis:Wimbledon fortnight creates concentrated international attention with limited domestic venue replication.
Volume sits with Football; growth tilts toward Rugby's hospitality tier expansion.
Event Size:
Venue capital requirements and regulatory oversight intensity scale directly with crowd capacity, compressing viable operator profiles at each tier.
- National:Wembley, Twickenham, and Old Trafford host FA Cup finals, rugby internationals, and music concerts requiring Sports Grounds Safety Authority certification at highest tier. These venues amortize infrastructure across multiple event types.
- International:Olympic stadium legacy conversions and Commonwealth Games host cities attract transient global audiences with government-backed security and transport coordination.
- Regional:Championship football grounds and county cricket venues serve catchment populations within two-hour travel radii.
- Local:Non-league football and semi-professional rugby operate with volunteer stewarding and minimal permanent infrastructure.
Revenue concentrates at National tier; venue utilization rates climb fastest at Regional level through multi-purpose programming.
Revenue Source:
Margin structure and cash flow predictability vary dramatically across monetization mechanisms, with exclusivity duration determining capital allocation priority.
- Media Rights:Premier League collective selling generates multi-year contracted income pools with highest margin profiles. Competition and Markets Authority scrutiny limits packaging flexibility for emerging streaming platforms.
- Ticket Sales:Dynamic pricing algorithms now displace fixed season-ticket structures, with younger demographics favoring last-minute digital purchase over advance commitment.
- Sponsorship:UK Gambling Commission advertising restrictions force betting brand substitution with lower-yield alternatives, compressing commercial pipelines at EFL clubs.
- Merchandise:Global brand licensing operations at Manchester United and Liverpool FC demonstrate scalable revenue beyond matchday capture.
Margin leadership belongs to Media Rights; sponsorship faces steepest repricing pressure from regulatory intervention.
Audience Demographic:
Life stage and disposable income segmentation determines pricing tolerance, digital engagement depth, and ancillary spend propensity.
- Young Adults:Smartphone-native consumption patterns favor streaming subscriptions and resale marketplace spontaneity over traditional box office relationships. Greater Manchester and West Midlands transport density supports this behavioral pivot.
- Families:Midweek evening and weekend afternoon scheduling preferences drive cricket's The Hundred format design and football's category pricing structures.
- Students:Discounted membership schemes and flexible entry tiers sustain pipeline development for future full-price conversion.
- Seniors:Season-ticket retention rates remain highest in this cohort, though physical accessibility retrofit requirements add venue compliance cost.
Young Adults deliver fastest behavioral shift; Families anchor volume through predictable repeat attendance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London dominates UK spectator sports revenue concentration through Premier League club density and transport infrastructure density. The capital's stadium network generates the highest matchday attendances and hospitality yields.
North West England
Manchester and Liverpool sustain the second-highest revenue cluster through historic football rivalries and improved rail connectivity. The Sports Grounds Safety Authority mandates stadium infrastructure investments across both cities. Old Trafford and Anfield anchor regional commercial activity while smaller Championship grounds pursue promotion-driven venue upgrades.
West Midlands
Birmingham and surrounding metropolitan areas demonstrate fastest behavioral shift toward flexible ticketing among young adult demographics. Transport density supports spontaneous attendance decisions without advance season-ticket commitment. Villa Park and regional rugby venues capture family-oriented programming with shorter session formats.
Yorkshire and the Humber
Leeds and Sheffield concentrate football and rugby league attendance in legacy industrial cities with strong club identities. The UK government's net-zero stadium targets are compelling operators to retrofit aging grounds with low-carbon systems. Elland Road and regional cricket grounds face compressed capital deployment timelines for compliance.
Scotland
Glasgow and Edinburgh sustain distinct footballing cultures through Celtic-Rangers rivalry and smaller professional clubs. The Scottish Government's climate targets parallel UK-wide stadium retrofit mandates. Hampden Park and regional rugby venues attract limited international fixture allocation against English competition for broadcast attention.
UK Spectator Sports Market Competitive Landscape
The competitive structure tilts toward vertically integrated football clubs with controlled hospitality tiers and global brand licensing operations. Market concentration sits at the Premier League apex where five to six clubs capture disproportionate commercial revenue pools. Three archetypes dominate: legacy heritage clubs with international fanbases, purpose-built stadium operators maximizing non-matchday utilization, and media rights aggregators controlling distribution exclusivity. Dominant competitive moves include stadium redevelopment for revenue diversification and direct-to-consumer streaming platform launches bypassing traditional broadcast intermediaries.
Within the heritage club tier, Manchester United and Tottenham Hotspur exemplify divergent strategies for commercial extraction. Manchester United occupies a position anchored in global brand licensing scalability. Tottenham Hotspur represents the purpose-built stadium archetype with integrated conference and concert programming. Arsenal Football Club sits within the same London corridor, competing for corporate hospitality budgets through tiered experiential packages. These three clubs illustrate how geographic proximity within the capital intensifies competitive positioning for premium revenue streams.
| Leading Market Players |
|---|
| Tottenham Hotspur |
| IMG Media Limited |
| Formula 1 |
| The Premier League |
| Football Association Limited |
| Manchester United |
| Arsenal Football Club |
| EFL (English Football League) |
| Chelsea FC |
| Others |
Pricing and Supply Chain Analysis
Backward integration into controlled hospitality tiers anchors both supply positioning and pricing power for Premier League clubs, enabling Manchester United and Tottenham Hotspur to capture margin pools unavailable to EFL counterparts dependent on third-party commercial operators.
Pricing Analysis
Throughput-based pricing anchors hospitality revenue at major venues, where per-seat yield scales with fixture prestige and corporate package bundling. Price differentiation separates Champions League fixtures from midweek EFL cup ties, with transport accessibility and opponent draw driving tier adjustments. Cost compression in standard ticketing is intensifying because younger demographics favor last-minute resale platforms over advance commitment. Students and young adults in Greater Manchester demonstrate highest price sensitivity; corporate buyers at London venues show lowest.
Supply Chain Analysis
Sports Grounds Safety Authority certification gates stadium infrastructure procurement, with only qualified contractors permitted for capacity-critical retrofit work. Manufacturing concentrates in Germany, China, and the UK for steel seating systems, video display technology, and access control hardware. Raw material dependencies include structural steel, LED display components, and low-carbon concrete alternatives. Single-source vulnerability sits with specialized stadium engineering firms capable of carbon retrofit design. Distribution runs through league-affiliated procurement consortia and direct club vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated operators with controlled revenue tiers, as Sports Grounds Safety Authority retrofit mandates force smaller venues into capital partnerships or asset sales.
For Market Incumbents: Anticipate regulatory compliance costs accelerating venue consolidation by securing specialized retrofit engineering capacity before contractor scarcity extends project timelines. Prioritize non-matchday revenue diversification through conference and concert programming to amortize infrastructure investments across event types. Channel control over hospitality tiering represents the critical defensive lever against EFL clubs pursuing promotion-driven venue upgrades.
For New Entrants and Emerging Players: Direct-to-consumer streaming platforms offer the most penetrable entry route, bypassing traditional broadcast intermediaries with niche sports content packages. White-space targets include mid-tier rugby and cricket venues lacking digital overlay infrastructure, where smartphone-integrated AR can deliver Premier League-equivalent fan experiences without comparable capital expenditure. A subscription-based membership model with flexible entry tiers addresses the behavioral shift away from season-ticket commitment among young adult demographics.
For Investors and Strategic Acquirers: Exit pathways concentrate in heritage clubs with global brand licensing scalability and purpose-built stadium operators with demonstrated non-matchday utilization rates. Long-term viability favors assets with verified carbon accounting data attracting ESG-mandated institutional capital. The signal to watch is UK Gambling Commission advertising restriction expansion, which would force additional commercial revenue model recalibration across the EFL.
| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Carbon Retrofit Program | Sports Grounds Safety Authority compliance unlocks green financing instruments for venue upgrades. |
| Direct-to-Consumer Streaming Launch | Bypassing traditional broadcast intermediaries captures younger demographics abandoning linear television. |
| Hospitality Tier Expansion | Corporate experiential packages convert matchday attendance into multi-year commercial relationships. |
| Non-Matchday Venue Activation | Conference and concert programming amortizes infrastructure across event types at underutilized grounds. |
| Digital Overlay Infrastructure Deployment | Real-time data and streaming capabilities satisfy baseline technical requirements for rights holders. |
Research Methodology
Independent corroboration across stadium operations directors, commercial revenue managers, and Sports Grounds Safety Authority compliance officers underwrites the qualitative findings, combined with secondary validation from Premier League financial disclosures, EFL governance reports, and UK government carbon target documentation. Bottom-up venue revenue modeling triangulates against top-down league media rights valuations.
Rate-of-change decomposition separates volume growth from yield improvement across the projection horizon, with segmentation dimensions including sport type, event scale, revenue channel, and audience demographic. CAGRs derive from fixture density projections, hospitality yield trajectories, and media rights contract renewal patterns. Industry-specific forecast inputs incorporate transport infrastructure expansion timelines and regulatory compliance cost curves.
The model holds under stable regulatory enforcement and continued corporate hospitality demand; deviation in UK Gambling Commission advertising restrictions or construction cost volatility would shift venue economics and consolidation timelines. A model refresh is warranted upon material change in net-zero stadium retrofit mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Sports App Market