
 Smart Bike Trainers Market | 2026-2036
Smart Bike Trainers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bike Trainers Market Insights
CE marking for electromagnetic compatibility is consolidating the cost-of-entry calculus for smart bike trainer manufacturers seeking European market access. Wahoo Fitness leverages in-house power measurement calibration to sustain premium positioning across direct-drive systems. Tacx anchors its competitive stance through proprietary app ecosystem control, while Elite specializes in ergometer-grade precision for rehabilitation and clinical applications.
Smart bike trainers are electromechanical devices that apply variable resistance to a bicycle's drivetrain or rear wheel, typically achieving accuracy within one to two percent of measured power output through integrated strain gauges and eddy-current or electromagnetic braking systems. Their primary commercial purpose is to simulate real-world cycling conditions indoors for structured training, fitness maintenance, and performance testing. Direct-drive trainers command the dominant margin pool due to superior stability and power accuracy, while Bluetooth connectivity functions as the baseline expectation rather than a differentiator across price tiers. Wheel-on configurations retain volume leadership among casual cyclists and entry-level buyers where storage flexibility and lower price points outweigh precision demands.
FCC certification governs radio frequency emissions for trainers sold in the United States, while EU REACH and RoHS frameworks restrict hazardous substances in electronic subassemblies and cabling. Japan's METI energy efficiency guidelines further shape product design requirements for brands targeting East Asian distribution. Stakeholders must monitor how evolving interoperability standards between training platforms and hardware protocols will determine which manufacturers retain platform-agnostic access versus facing ecosystem lockout.
Market Dynamics
Structured indoor training protocols are compressing the competitive cyclist and triathlete segment toward direct-drive systems with sub-one-percent power accuracy, while electromagnetic braking architectures displace fluid resistance mechanisms across premium tiers.
Growth Catalysts
- EU REACH compliance:Hazardous substance restrictions in electronic subassemblies are accelerating material sourcing upgrades across the supply chain, forcing component vendors toward certified suppliers.
- Competitive cyclists and triathletes:This buyer segment is expanding fastest as power-based training methodology migrates from outdoor to indoor protocols.
- Germany:Dense cycling infrastructure investment and pro-team sponsorships have created an early adopter ecosystem that validates premium trainer specifications for export markets.
Market Restraints
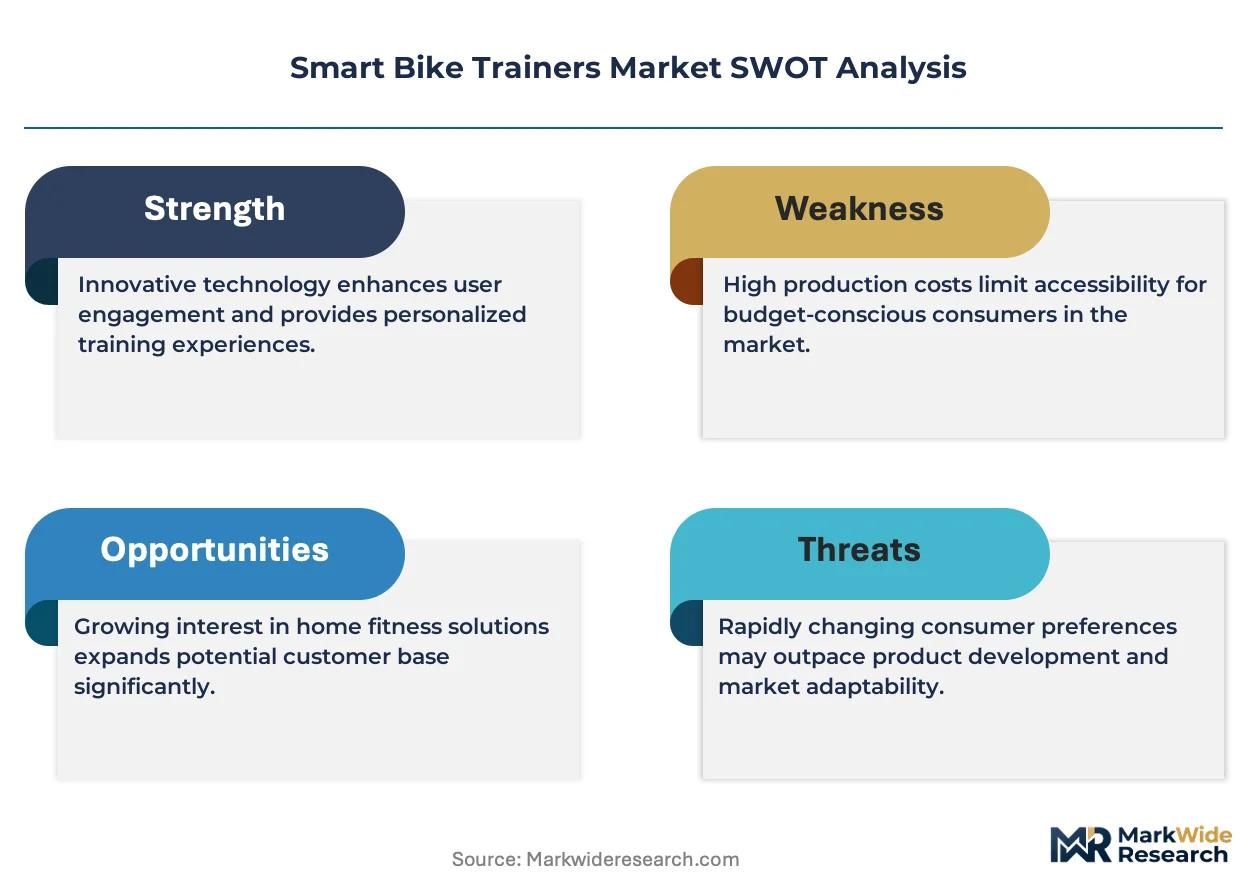
- Rare earth magnet supply:Neodymium price volatility constrains electromagnetic braking system margins, with China controlling upstream processing capacity.
- CE marking cost:Electromagnetic compatibility certification for European market entry adds fixed compliance overhead that disadvantages smaller manufacturers.
- Wheel-on substitution:Entry-level buyers retain volume preference for wheel-on configurations where storage flexibility outweighs direct-drive precision advantages.
Strategic Opportunities
- Rehabilitation and clinical ergometry:Elite's existing precision positioning demonstrates white space for medical-grade certification expansion beyond fitness applications.
- Japan METI energy efficiency guidelines:Compliance with East Asian efficiency standards opens distribution channels where domestic brands lack smart trainer specialization.
- Bluetooth and ANT+ convergence:Protocol standardization is collapsing ecosystem fragmentation, enabling hardware-agnostic platform access for new entrants.
Industry Challenges
- Strain gauge calibration expertise:Power measurement accuracy within one percent requires specialized electromechanical engineering talent that concentrates in German and Dutch manufacturing clusters.
- FCC certification timeline:Radio frequency emissions testing for US market entry extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bike Trainers Market |
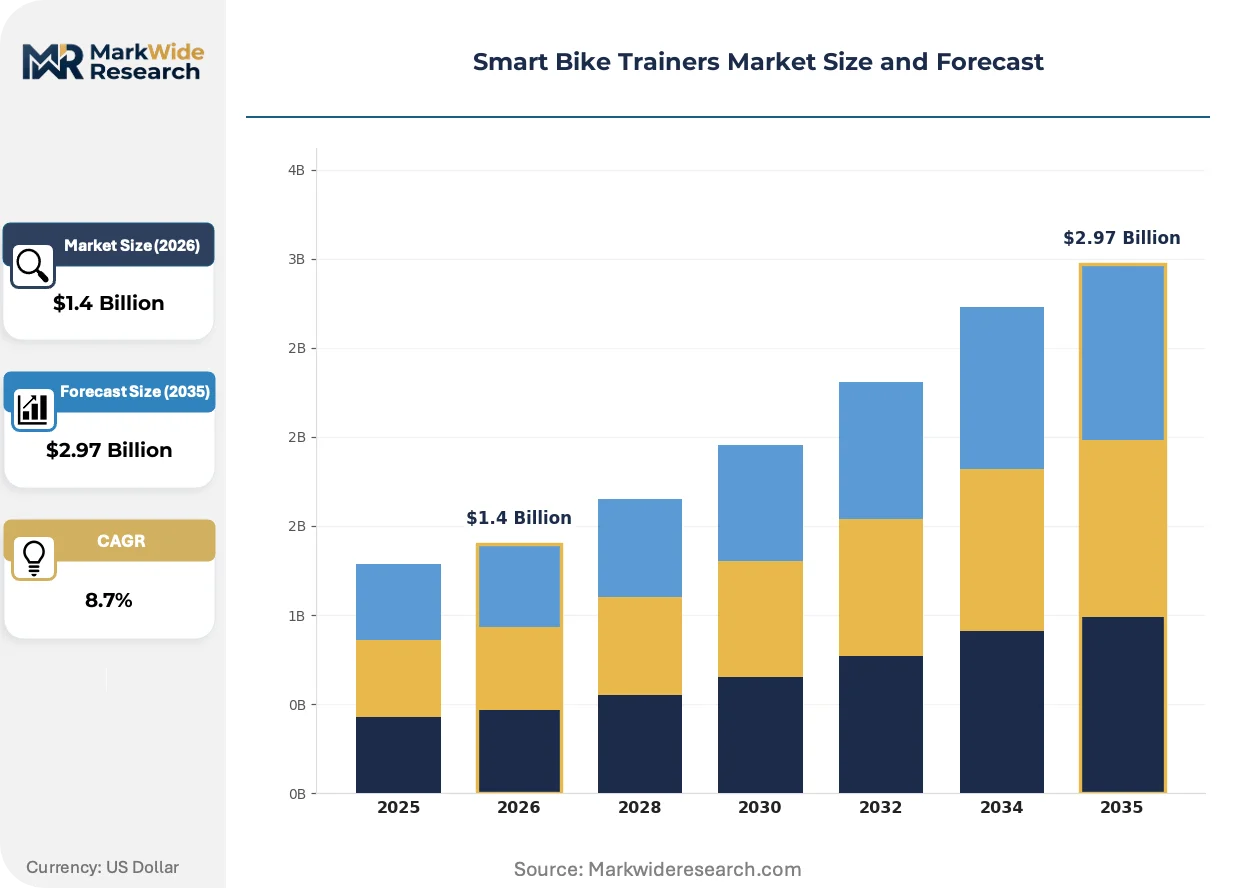
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Drive, Wheel-On, Smart Rollers, Hybrid Connectivity: Bluetooth, ANT+, Wi-Fi, USB End User: Athletes, Casual Cyclists, Fitness Enthusiasts, Rehabilitation Patients Feature: Power Measurement, Ergometer, Interactive Training, App Integration |
| Companies Covered | Wahoo Fitness, Tacx, Elite, Minoura, BKOOL, Stages Cycling, Kurt Kinetic, JetBlack Cycling, Saris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bike Trainers Market Trends and Innovations
Power accuracy certification and electromagnetic braking architectures are compressing technical differentiation windows, while training platform interoperability determines which hardware retains access to structured workout libraries.
Electromagnetic braking systems are consolidating market preference across direct-drive configurations. Competitive cyclists and triathletes are adopting these architectures fastest, migrating from fluid and fan-based resistance. This technology is consolidating the premium tier around sub-one-percent accuracy specifications that wheel-on designs cannot match.
EU REACH and RoHS frameworks are restricting hazardous substances in electronic subassemblies and cabling across European distribution. Manufacturers must reformulate solder compositions and cable sheathing to maintain market access. German and Dutch production facilities are responding fastest, leveraging proximity to ECHA regulatory intelligence.
Platform-agnostic hardware demand is fragmenting proprietary ecosystem control. Buyers now expect seamless connectivity across Zwift, TrainerRoad, and Wahoo SYSTM without vendor lock-in. This behavioral shift is most visible in North American and German markets where subscription service switching costs remain low.
Smart Bike Trainers Market Segmentation
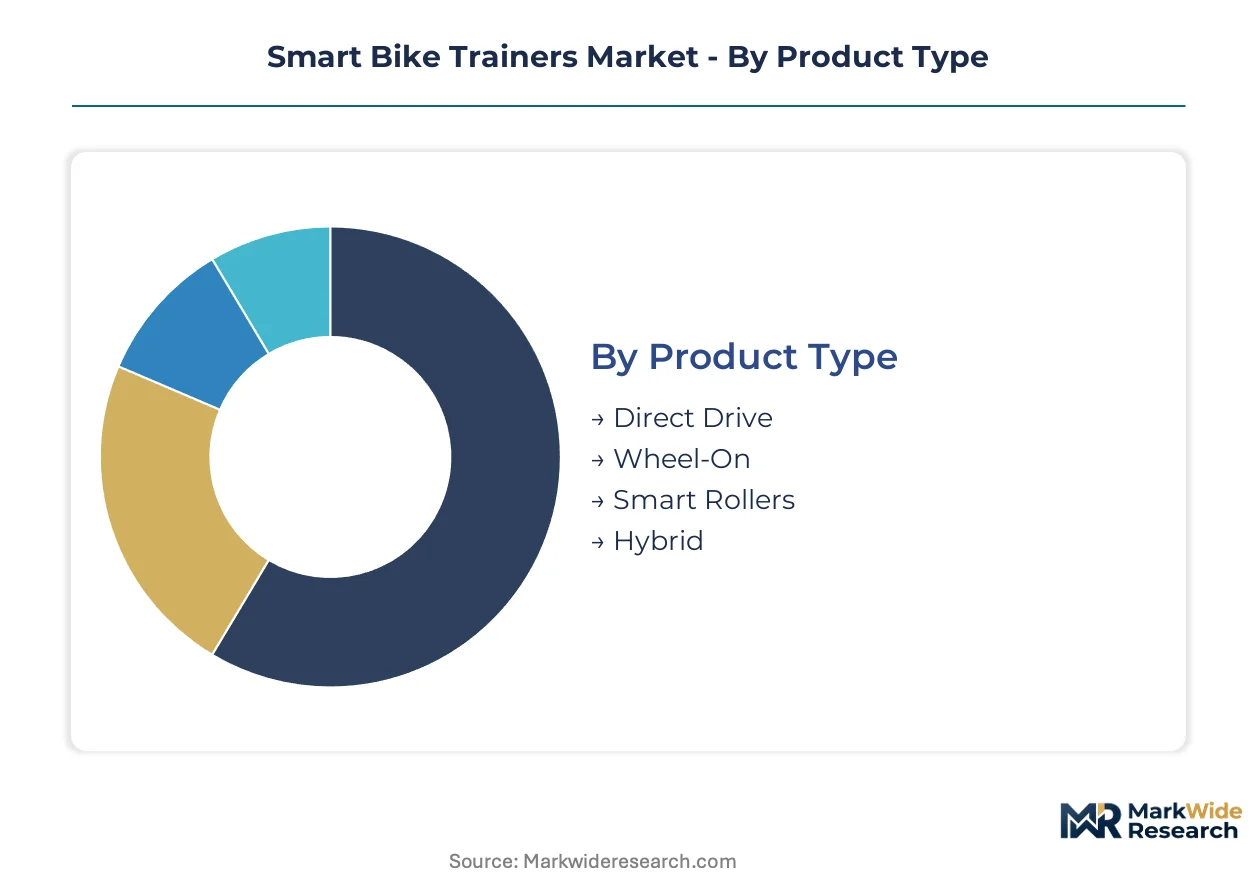
Smart bike trainer segmentation reveals how certification burdens, accuracy requirements, and connectivity protocols fragment purchasing decisions across athlete tiers and clinical applications. Manufacturers must align product architectures with distinct regulatory pathways and end-user precision demands.
Product Type:
CE marking for electromagnetic compatibility and FCC radio frequency certification apply differentially across resistance mechanisms and drivetrain interfaces.
- Direct Drive:Rear wheel removal enables direct cassette engagement with electromagnetic braking systems achieving sub-one-percent power accuracy. Competitive cyclists and triathletes in Germany concentrate demand here as structured training protocols mandate precision validation.
- Wheel-On:Tire-to-roller contact maintains storage flexibility and lower price points through fluid or magnetic resistance mechanisms. Casual cyclists across entry-level markets retain volume preference where portability outweighs accuracy requirements.
- Smart Rollers:Free-standing drum configuration demands minimal setup while sacrificing peak resistance output.
- Hybrid:Convertible architecture spans direct-drive and wheel-on modes for multi-user households.
Leading the category by volume: Wheel-On. Growing fastest: Direct Drive.
Connectivity:
Protocol standardization is collapsing ecosystem fragmentation, with hardware-agnostic expectations reshaping which interfaces command premium positioning versus baseline inclusion.
- Bluetooth:Universal smartphone pairing functionality now serves as table-stakes across all price tiers rather than a differentiator. German and Dutch buyers expect seamless Zwift and TrainerRoad compatibility without proprietary lock-in.
- ANT+:Dedicated fitness protocol maintains dominance among competitive cyclists running multi-sensor setups. Athletes in structured training environments demand this for simultaneous heart rate, cadence, and power meter integration.
- Wi-Fi:Direct router connectivity eliminates smartphone bridging for firmware updates and ride uploads.
- USB:Wired power and data connection serves clinical ergometry applications requiring interference immunity.
Bluetooth anchors volume leadership through smartphone ubiquity. ANT+ retains the steepest expansion trajectory among performance-focused segments.
End User:
Precision requirements and reimbursement pathways separate clinical certification demands from consumer fitness applications.
- Athletes:Power-based periodization and race simulation drive specification intensity toward electromagnetic braking and sub-one-percent accuracy. This segment concentrates in Germany, Belgium, and the Netherlands where pro-team sponsorships validate premium hardware.
- Casual Cyclists:Weather contingency and convenience motivation sustain wheel-on volume through lower price points and storage flexibility. Entry-level buyers prioritize setup simplicity over calibration complexity.
- Fitness Enthusiasts:Gamified training platforms convert indoor exercise adherence through interactive environment immersion.
- Rehabilitation Patients:Medical-grade ergometry demands strain gauge calibration traceability and ISO 13485-adjacent quality systems for clinical reimbursement eligibility.
Athletes command the dominant margin pool. Rehabilitation Patients represent the fastest-expanding trajectory as precision cycling enters physical therapy protocols.
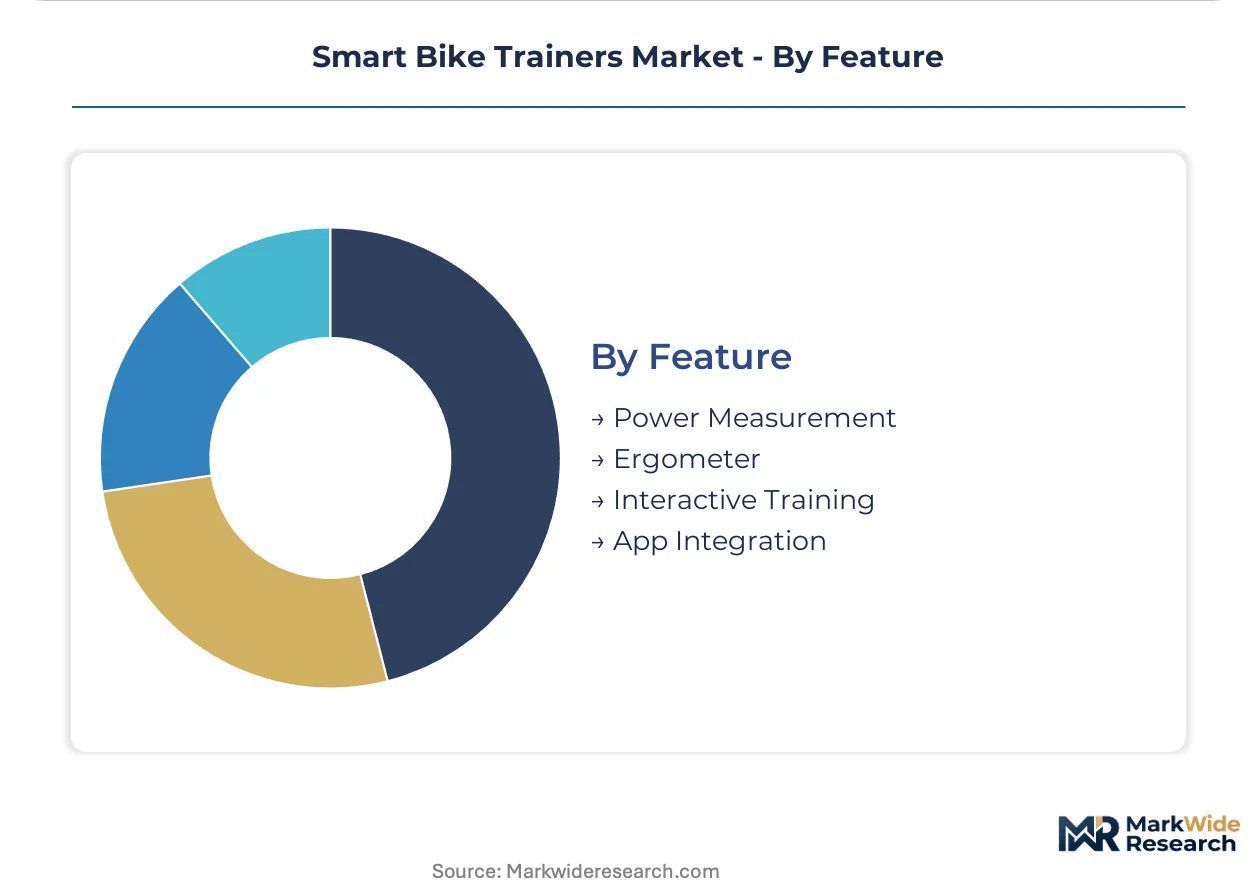
Feature:
Functional differentiation clusters around measurement certification, therapeutic application, and software ecosystem integration.
- Power Measurement:Strain gauge integration with temperature compensation algorithms defines competitive viability. German manufacturing clusters concentrate specialized electromechanical calibration expertise required for one-percent accuracy claims.
- Ergometer:Constant wattage mode enables clinical prescription of precise metabolic workloads. Rehabilitation facilities in Japan and Germany drive adoption where METI energy efficiency guidelines and EU MDR-adjacent quality standards overlap.
- Interactive Training:Resistance modulation synchronized to virtual terrain gradients requires low-latency protocol implementation.
- App Integration:Platform-agnostic API access determines hardware longevity as subscription services consolidate.
Power Measurement leads feature prioritization across premium tiers. Ergometer functionality is gaining share fastest as clinical applications expand beyond fitness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate electromagnetic component sourcing for trainer manufacturers serving export markets. These manufacturing clusters leverage proximity to rare earth processing facilities and bonded logistics corridors.
Germany
Pro-team sponsorships from Bayern Munich and Bora-Hansgrohe validate premium hardware specifications for competitive cyclists. ECHA REACH compliance mandates reformulated solder compositions in electronic subassemblies. Stuttgart and Friedrichshafen host specialized strain gauge calibration facilities serving direct-drive system manufacturers.
United States
FCC certification timelines extend product launch cycles by four to six months for electromagnetic braking architectures. Indoor cycling studios in Colorado and California drive fleet procurement of platform-agnostic hardware. Denver and Boulder clusters concentrate software engineering talent for training platform interoperability.
Japan
METI energy efficiency guidelines shape product design requirements for rehabilitation-focused ergometer applications. Precision cycling enters physical therapy protocols at Tokyo and Osaka medical centers. Nagoya manufacturing corridors adapt automotive sensor expertise to strain gauge production for clinical-grade trainers.
Netherlands
Amsterdam and Eindhoven cycling infrastructure investment creates dense early adopter ecosystems for smart trainer validation. ECHA regulatory intelligence proximity accelerates RoHS compliance for cable sheathing reformulation. Rotterdam logistics hubs facilitate component distribution across EU distribution networks.
United Kingdom
London and Manchester indoor training studios compress adoption timelines for structured workout protocols. CE marking requirements for electromagnetic compatibility add fixed compliance overhead for market entry. Cambridge engineering clusters develop temperature compensation algorithms for power measurement accuracy.
Smart Bike Trainers Market Competitive Landscape
German producers anchor the premium tier through precision calibration expertise; Taiwanese and Chinese fabricators hold volume positions in electromagnetic component supply. The vendor base splits between consolidated direct-drive specialists and fragmented wheel-on assemblers. Three archetypes dominate: ecosystem-locked platform controllers, component-agnostic hardware suppliers, and clinical-precision ergometer specialists. Capacity expansion and backward integration into strain gauge sourcing represent the dominant competitive vectors.
Within the ecosystem-control archetype, Wahoo Fitness and Tacx occupy positions defined by proprietary software integration versus platform-agnostic hardware access. Elite exemplifies the clinical-precision specialist archetype, anchoring rehabilitation and medical-grade applications where ISO 13485-adjacent quality systems determine reimbursement eligibility. These three companies represent distinct strategic postures rather than overlapping market coverage.
| Leading Market Players |
|---|
| Wahoo Fitness |
| Tacx |
| Elite |
| Minoura |
| BKOOL |
| Stages Cycling |
| Kurt Kinetic |
| JetBlack Cycling |
| Saris |
| Others |
Pricing and Supply Chain Analysis
Direct-drive precision tiers and wheel-on convenience segments diverge sharply in both margin structure and component sourcing geography. Electromagnetic braking architectures command premium positioning through German and Dutch calibration expertise, while fluid-resistance wheel-on units source from Taiwanese fabricators serving price-sensitive entry buyers.
Pricing Analysis
Lead-time-driven pricing compression favors manufacturers with bonded inventory in Rotterdam and Shenzhen logistics hubs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with CE-marked electromagnetic systems capturing margin premiums over uncertified alternatives. Cost compression in wheel-on tiers is intensifying because Chinese component oversupply has collapsed spot pricing for magnetic resistance units. Casual cyclists exhibit highest price sensitivity, while competitive athletes prioritize accuracy validation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processing for neodymium-dependent electromagnetic braking systems. Component sourcing concentrates in China, Taiwan, and Germany, drawing from strain gauge sensors, eddy-current brake assemblies, and precision-machined flywheels. Supply chain risk centers on tariff exposure for US-bound finished goods containing Chinese-origin magnets. Distribution runs through specialist cycling retailers in Europe, direct-to-consumer channels in North America, and medical equipment distributors for clinical ergometer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart bike trainers are undergoing a technology-transition phase as electromagnetic braking displaces fluid and fan-based resistance mechanisms across premium tiers. This substitution is reshaping competitive positioning around calibration expertise rather than mechanical manufacturing scale.
For Market Incumbents: Deploy proprietary app ecosystem control as the primary defensive lever against platform-agnostic hardware commoditization. Incumbents should deepen backward integration into strain gauge sourcing to protect one-percent accuracy claims from supply disruption. Tacx and Wahoo Fitness have demonstrated that software lock-in retains subscriber lifetime value even as hardware margins compress. For New Entrants and Emerging Players: Capture rehabilitation and clinical ergometry white space where ISO 13485-adjacent quality systems create certification barriers for fitness-focused incumbents. Japan and Germany present the most penetrable geographies given METI efficiency guidelines and EU MDR-adjacent standards overlap. A go-to-market angle anchored to hospital procurement channels bypasses saturated consumer retail. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-agnostic hardware suppliers with medical-grade certification optionality. Long-term viability in this market hinges on sustaining accuracy leadership through electromagnetic architecture transitions. The signal to watch is training platform API access revocation, which would strand ecosystem-dependent hardware without software revenue offsets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Gauge Sourcing | German calibration expertise protects one-percent accuracy claims from magnet supply volatility. |
| Clinical Ergometer Certification Pathway | ISO 13485-adjacent quality systems unlock reimbursement eligibility in Japanese rehabilitation protocols. |
| Platform-Agnostic API Development | Seamless Zwift and TrainerRoad compatibility prevents ecosystem lockout as subscription services consolidate. |
| Rotterdam Bonded Inventory Expansion | Proximity to ECHA regulatory intelligence accelerates REACH compliance for European market access. |
| Medical Equipment Distribution Partnership | Hospital procurement channels bypass saturated cycling retail for rehabilitation-focused ergometer sales. |
Research Methodology
Trade publications, customs databases, and ECHA regulatory filings formed the secondary backbone of this analysis. Primary interviews with smart trainer product managers, cycling team performance directors, hospital rehabilitation procurement officers, and electromagnetic component sourcing leads validated secondary findings. Bottom-up shipment data from German and Dutch manufacturing clusters was triangulated against top-down consumer spending estimates across the analysis window.
Historical trendline analysis of direct-drive versus wheel-on volume shifts informed the projection framework. Segmentation dimensions modeled include resistance mechanism type, connectivity protocol, end-user precision requirements, and regional regulatory cluster. CAGRs were derived from curve-fitting observed adoption rates of electromagnetic architectures against fluid-resistance legacy stock. Forecast inputs incorporated pro-team sponsorship validation cycles and clinical ergometer reimbursement pathway maturation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet price volatility and training platform consolidation dynamics. Forecasts reflect documented assumptions regarding interoperability standard stability and REACH compliance cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market