
 Smart Fitness Trainer Market | 2026-2036
Smart Fitness Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Trainer Market Insights
Market Context
Buyer concentration among corporate wellness programs is expanding as Fortune 500 employers consolidate vendor relationships for connected fitness benefits. Apple Inc. leverages its HealthKit ecosystem to anchor enterprise contracts with self-insured employers seeking biometric integration. Peloton Interactive, Inc. competes through commercial-grade hardware deployments that sustain recurring subscription revenue from B2B channels. Garmin Ltd. specializes in precision sensor arrays that differentiate its offerings for insurance-backed wellness incentive programs.
Technical Definition and Segment Structure
A smart fitness trainer is an AI-enabled system that combines biomechanical sensors, real-time performance analytics, and adaptive coaching algorithms to deliver personalized exercise programming through wearable devices, connected equipment, or software interfaces. These systems process heart rate variability, motion capture data, and user feedback to dynamically adjust workout intensity and form correction. Wearable Devices and Smart Equipment dominate current revenue pools, while AI Integration within the Technology segment captures expanding margin as proprietary algorithm development creates defensible product differentiation. Fitness Apps operating on Freemium pricing models show structural growth velocity as user acquisition costs decline through social distribution channels.
Regulatory Frame and Outlook
The FDA exercises oversight of smart fitness trainers making specific diagnostic or therapeutic claims, while the EU AI Act imposes risk-classification requirements on algorithmic coaching systems deployed in European markets. FCC regulations govern wireless connectivity standards for Bluetooth-enabled equipment sold in the United States. Stakeholders must monitor evolving liability frameworks as AI-generated training recommendations face scrutiny from health regulators and consumer protection agencies across multiple jurisdictions.
Market Dynamics
Corporate wellness procurement consolidation is compressing vendor margins while accelerating platform standardization across Fortune 500 self-insured employers seeking biometric-integrated fitness ecosystems.
Growth Catalysts
- EU AI Act compliance mandates:European algorithmic transparency requirements are forcing coaching platforms to upgrade explainable AI capabilities, creating replacement demand for legacy black-box systems.
- Heart rate variability monitoring:Precision biometric tracking is expanding from elite athletics into mainstream corporate wellness programs as insurance-backed incentive structures mature.
- Motion capture miniaturization:Advancements in MEMS sensor arrays are enabling form-correction features on sub-premium hardware tiers previously limited to commercial-grade equipment.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints for specialized biometric sensor chips create input volatility for wearable device manufacturers.
- FDA diagnostic claim friction:Regulatory scrutiny of AI-generated health recommendations limits marketing language and extends compliance review timelines for therapeutic-adjacent features.
- Freemium app substitution:Zero-cost fitness applications with adequate baseline functionality capture price-sensitive consumer segments before paid conversion.
Strategic Opportunities
- Medicare Advantage integration:US value-based care contracts create reimbursement pathways for clinically validated fitness interventions in aging populations.
- India PLI scheme leverage:Domestic manufacturing incentives for electronics assembly attract hardware OEMs seeking cost-competitive export capacity.
- Computer vision convergence:Integration of depth-sensing cameras with existing smartphone ecosystems enables software-only coaching without dedicated hardware purchase.
Industry Challenges
- Biomechanical data science talent scarcity:Shortage of specialists combining exercise physiology expertise with machine learning engineering limits algorithm development velocity.
- Legacy gym management system integration:API fragmentation across established club software platforms complicates enterprise deployment of connected equipment networks.
- CE marking timeline variability:Inconsistent EU notified body review speeds for wireless medical-adjacent devices delay European market entry schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Trainer Market |
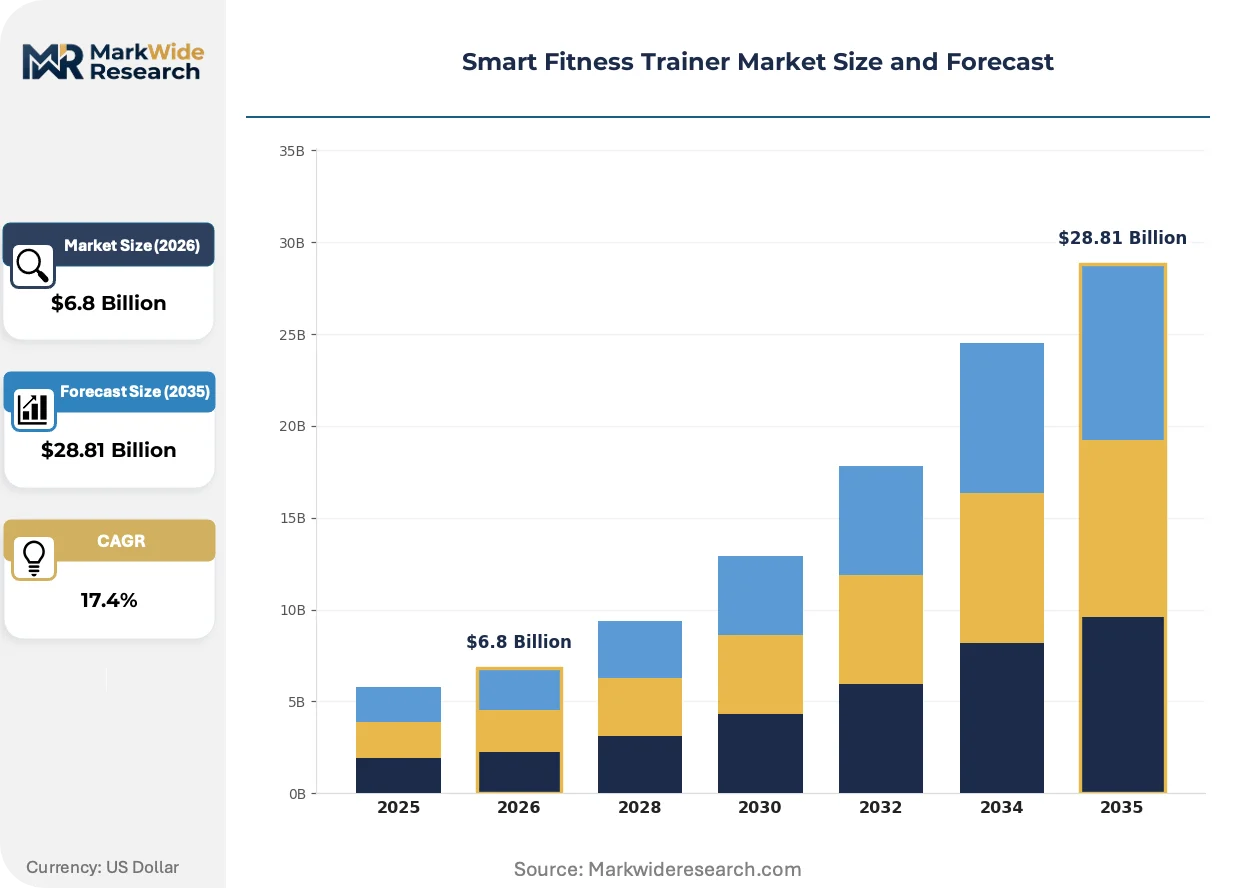
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Equipment, Fitness Apps, Interactive Platforms Technology: AI Integration, Bluetooth Connectivity, Cloud-Based Solutions, Mobile Applications End User: Fitness Enthusiasts, Personal Trainers, Gyms, Health Clubs Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Tiered Pricing |
| Companies Covered | Apple Inc., Samsung Electronics, Fitbit, Garmin Ltd., Xiaomi Inc., Huawei Technologies, Polar Electro, Peloton Interactive, Inc., Tonal System, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Trainer Market Trends and Innovations
Algorithmic personalization is displacing static programming across all price tiers, compressing the competitive advantage window for content libraries while elevating real-time adaptive coaching as the primary differentiation vector.
Edge AI inference engines are unifying biometric processing with on-device recommendation generation, eliminating cloud latency for form-correction feedback. Boutique studio chains in tech-forward US metropolitan markets are deploying these systems to justify premium membership pricing. The technology is unifying hardware and software margins into single-platform economics that favor vertically integrated vendors over component assemblers.
The EU AI Act risk-classification framework is imposing documentation burdens on algorithmic coaching systems marketed in European markets. High-risk categorization for systems processing health data triggers conformity assessment requirements that extend time-to-market by six to eighteen months. German and French health regulators are coordinating implementation guidance that will determine whether adaptive workout algorithms qualify as medical device software.
Employer procurement committees are consolidating vendor relationships from point solutions to integrated wellness platforms. Self-insured US corporations are displacing standalone fitness benefits with biometric-integrated ecosystems that tie premium discounts to verified activity data. This concentration is most visible among Fortune 500 headquarters clusters in Texas and California, where benefits administrators prioritize single-contract simplicity over best-of-breed feature depth.
Smart Fitness Trainer Market Segmentation
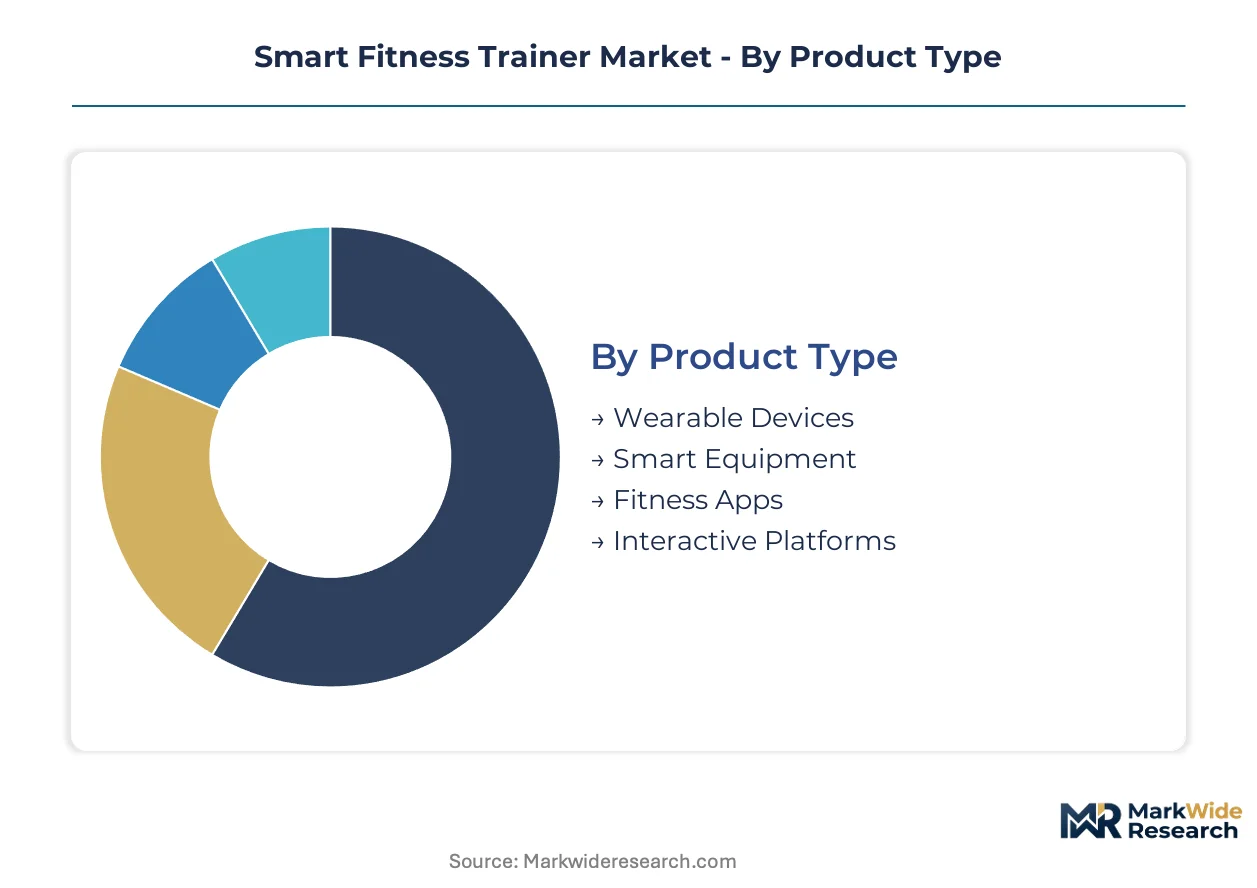
Segmentation in smart fitness trainers reveals divergent margin structures across hardware and software delivery modes. Product architecture determines whether vendors capture recurring revenue streams or one-time equipment sales. Technology integration depth separates defensible platform economics from commodity component assembly.
Product Type:
Wearable Devices dominate unit volume while Smart Equipment commands premium pricing through commercial-grade durability specifications.
- Wearable Devices:Wrist-worn and chest-strap sensors processing heart rate variability and motion data through MEMS accelerometers. Demand concentrates among corporate wellness programs at Fortune 500 employers in Texas and California seeking biometric verification for insurance premium discounts. Supply constraints from Taiwan-based foundry capacity create input volatility for specialized sensor chips.
- Smart Equipment:Connected treadmills, stationary cycles, and strength training rigs with embedded screens and real-time form correction. Boutique studio chains in Manhattan and San Francisco deploy these systems to justify premium membership tiers. Hardware margins compress as component standardization accelerates across commercial-grade tiers.
- Fitness Apps:Software-only coaching platforms delivering adaptive programming through smartphone interfaces. Social distribution channels reduce user acquisition costs for freemium models.
- Interactive Platforms:Integrated ecosystems combining live classes, community features, and performance analytics. Enterprise contracts with self-insured employers drive B2B revenue concentration.
Mature deployment sits with Smart Equipment in commercial health clubs. Newer deployment is concentrated in Wearable Devices as MEMS miniaturization enables sub-premium form correction.
Technology:
Proprietary algorithm development creates defensible differentiation while connectivity standards commoditize hardware integration layers.
- AI Integration:Machine learning models processing biomechanical data to generate personalized workout adjustments and real-time coaching cues. EU AI Act risk-classification requirements extend conformity assessment timelines for systems deployed in Germany and France. Explainable AI capabilities separate compliant platforms from legacy black-box architectures facing replacement demand.
- Bluetooth Connectivity:Wireless protocols enabling sensor-to-device data transmission for heart rate and motion capture. FCC regulations govern spectrum allocation for equipment sold in the United States.
- Cloud-Based Solutions:Remote processing infrastructure for performance analytics and program storage. Latency sensitivity limits deployment for real-time form correction applications.
- Mobile Applications:Smartphone-native software leveraging onboard sensors without dedicated hardware purchase. Computer vision convergence through depth-sensing cameras expands addressable market to price-sensitive segments.
Margin concentration aligns with AI Integration as algorithmic personalization displaces static content libraries. Bluetooth Connectivity exhibits steepest commoditization pressure from standardization.
End User:
Procurement authority separates enterprise buyers with consolidated vendor relationships from fragmented individual purchase decisions.
- Fitness Enthusiasts:Individual consumers purchasing devices and subscriptions for home-based training. Price sensitivity drives freemium app substitution before paid conversion.
- Personal Trainers:Independent professionals deploying client management and remote coaching tools. Platform fees compress margins for solo practitioners.
- Gyms:Mid-size facilities upgrading equipment fleets to compete with boutique alternatives. API fragmentation across legacy management systems complicates connected equipment deployment.
- Health Clubs:Large-format operators negotiating enterprise pricing for integrated wellness ecosystems. Self-insured employers in the United States consolidate contracts with biometric-integrated platform vendors.
Enterprise procurement sits with Health Clubs. Individual adoption is expanding fastest among Fitness Enthusiasts as smartphone-native coaching reduces hardware barriers.
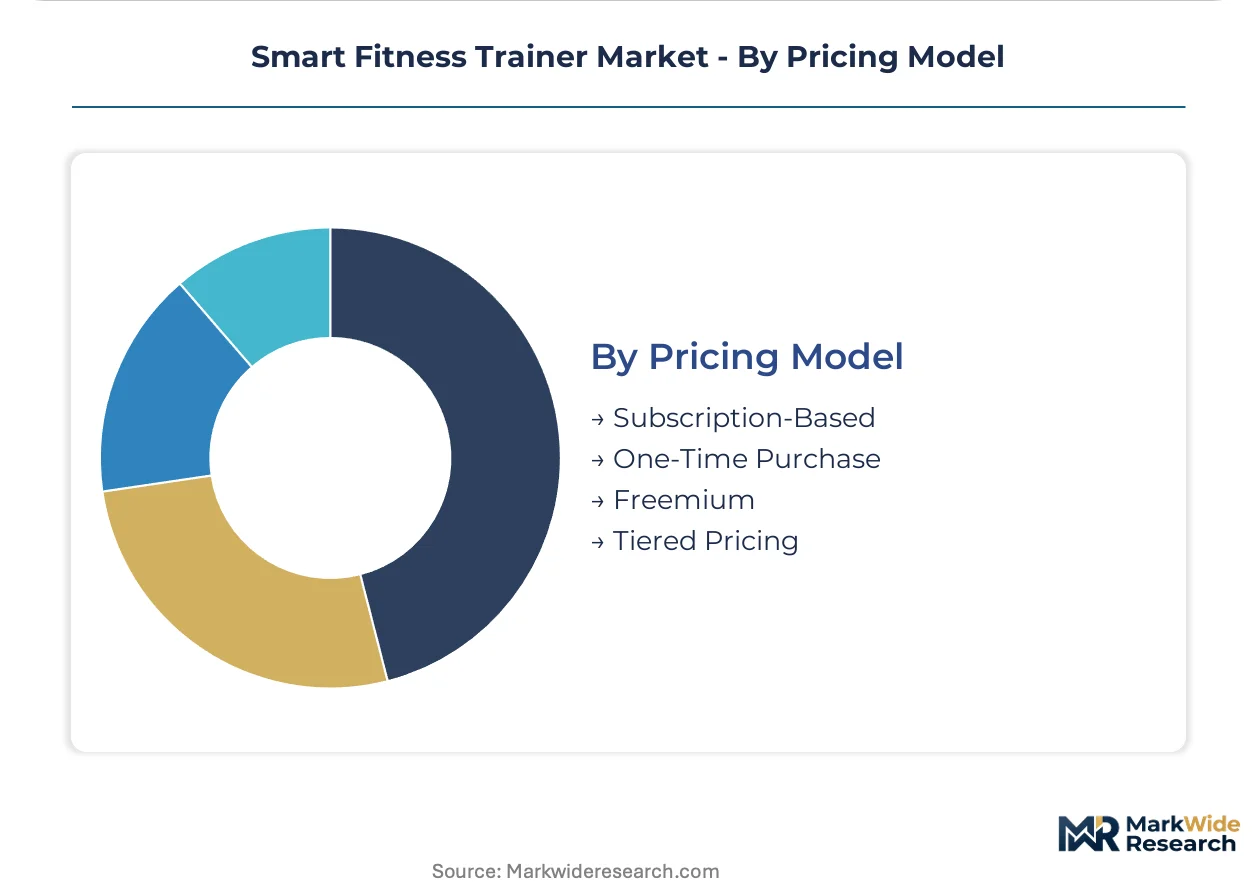
Pricing Model:
Revenue predictability separates recurring subscription economics from transactional hardware sales vulnerable to replacement cycles.
- Subscription-Based:Monthly or annual fees for software access, content libraries, and coaching services. Corporate wellness contracts favor this structure for budget forecasting.
- One-Time Purchase:Upfront equipment payments without ongoing service obligations. Commercial-grade Smart Equipment in health clubs typically follows this model.
- Freemium:Baseline functionality at zero cost with premium features behind paywalls. User acquisition through social distribution channels reduces marketing spend for Fitness Apps.
- Tiered Pricing:Three-level structures separating premium, standard, and economy feature sets. Corporate procurement committees negotiate volume discounts at the premium tier.
Established revenue sits with One-Time Purchase for Smart Equipment. Structural expansion is concentrated in Subscription-Based models as employers seek integrated wellness platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan-based foundry capacity for MEMS biometric sensors anchors hardware supply chains, while algorithm development clusters concentrate in coastal metropolitan zones with dense employer wellness program procurement.
United States
Fortune 500 self-insured employers in Texas and California consolidate vendor contracts for biometric-integrated wellness platforms. FDA scrutiny of AI-generated health recommendations extends compliance timelines for therapeutic-adjacent coaching features. Manhattan and San Francisco boutique studio chains deploy premium connected equipment to justify membership pricing tiers.
Germany
EU AI Act risk-classification requirements trigger conformity assessment delays for algorithmic coaching systems entering European markets. BfArM coordination with French regulators determines whether adaptive workout algorithms qualify as medical device software. Munich and Berlin health tech clusters attract explainable AI engineering talent for compliance-ready platform development.
China
Domestic manufacturing scale for MEMS accelerometers and heart rate sensors supplies cost-competitive wearable device assembly. MIIT standards for wireless medical-adjacent equipment create certification pathways for export-oriented OEMs. Shenzhen electronics corridors integrate sensor fabrication with finished goods assembly for price-sensitive consumer segments.
India
PLI scheme incentives for electronics manufacturing attract hardware OEMs seeking export-competitive assembly capacity. CDSCO oversight of software-as-medical-device claims shapes marketing language for coaching platforms targeting clinical validation. Bangalore and Hyderabad technology corridors host machine learning engineering talent for adaptive algorithm development.
United Kingdom
Corporate wellness procurement committees at London-headquartered multinationals prioritize single-contract platform simplicity over best-of-breed feature depth. MHRA alignment with EU AI Act risk frameworks influences algorithmic transparency requirements for coaching systems. Cambridge and Oxford research clusters feed biomechanical data science expertise into commercial platform development.
Smart Fitness Trainer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-native coaching without dedicated hardware purchase. The vendor base stratifies across vertically integrated ecosystem architects, precision sensor specialists, and freemium platform operators. Three archetypes dominate: consumer electronics conglomerates leveraging health data ecosystems, dedicated fitness hardware manufacturers defending equipment margins, and software-first challengers exploiting smartphone-native distribution. Competitive moves concentrate on enterprise contract consolidation and algorithmic personalization capabilities.
Among consumer electronics conglomerates, Apple Inc. and Samsung Electronics exemplify ecosystem-centric positioning that binds hardware sales to recurring service revenue. Garmin Ltd. represents the precision sensor specialist archetype, anchoring insurance-backed wellness incentive program supply chains. Peloton Interactive, Inc. occupies a position within the connected equipment tier that commercial health club procurement committees evaluate against integrated platform alternatives.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Fitbit |
| Garmin Ltd. |
| Xiaomi Inc. |
| Huawei Technologies |
| Polar Electro |
| Peloton Interactive, Inc. |
| Tonal System, Inc. |
| Others |
Pricing and Supply Chain Analysis
MEMS sensor miniaturization is collapsing the cost floor for biometric hardware while concentrating production expertise in Taiwan-based foundries, creating divergent margin trajectories between component suppliers and finished goods assemblers. This technological shift simultaneously enables sub-premium pricing tiers for wearable devices and amplifies pricing power for precision sensor specialists serving insurance-backed wellness programs.
Pricing Analysis
Service bundling separates premium connected equipment contracts from unbundled hardware transactions in commercial health club procurement. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by algorithm personalization depth and FDA-adjacent certification status. Cost compression in the wearable tier intensifies because freemium app substitution erodes paid conversion rates. Individual fitness enthusiasts exhibit highest price sensitivity, while Fortune 500 benefits administrators prioritize single-contract simplicity over unit cost optimization.
Supply Chain Analysis
Biometric sensor chip supply rests on Taiwan-based foundry capacity, with secondary sourcing from South Korean semiconductor fabricators and select US-based specialty producers. Critical inputs include MEMS accelerometers, heart rate photoplethysmography modules, and Bluetooth Low Energy transceivers. Single-source vulnerability concentrates in Taiwan Strait logistics corridors, where geopolitical friction threatens just-in-time delivery schedules for wearable device OEMs. Distribution runs through enterprise procurement committees at self-insured employers, direct-to-consumer e-commerce channels, and boutique studio chain equipment leasing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where algorithm development velocity and captive sensor supply determine platform economics. Players are pursuing upstream control over MEMS fabrication to secure cost-competitive hardware margins against software-native challengers.
For Market Incumbents: Anticipate freemium platform substitution by deepening explainable AI capabilities ahead of EU AI Act enforcement timelines. Consolidate enterprise wellness contracts through biometric data ecosystem lock-in, while defending equipment margins via commercial-grade durability specifications that software-only competitors cannot replicate. Backward integration into MEMS sensor design protects against Taiwan foundry capacity volatility. For New Entrants and Emerging Players: Corporate wellness procurement committees represent the most penetrable channel, as Fortune 500 employers displace point solutions for integrated platforms. Medicare Advantage reimbursement pathways for clinically validated fitness interventions offer white-space expansion in aging population segments. A smartphone-native coaching deployment leveraging depth-sensing computer vision bypasses dedicated hardware capital requirements entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical platform acquisitions by consumer electronics conglomerates seeking health data ecosystem expansion. Long-term viability hinges on algorithmic personalization moats that survive regulatory transparency requirements and commoditization pressure from open-source fitness models. Watch FDA diagnostic claim enforcement intensity as the inflection signal distinguishing wellness-adjacent platforms from regulated medical device software.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Explainability Investment | EU AI Act compliance separates compliant platforms from black-box replacement demand in Germany and France. |
| MEMS Sensor Backward Integration | In-house production of biometric chips reduces Taiwan foundry dependency for wearable device manufacturers. |
| Enterprise Wellness Platform Consolidation | Single-contract biometric ecosystems capture Fortune 500 procurement committees in Texas and California. |
| Computer Vision Coaching Development | Depth-sensing smartphone integration expands addressable market without dedicated hardware purchase barriers. |
| Medicare Advantage Reimbursement Strategy | Clinical validation pathways unlock value-based care contracts for aging population fitness interventions. |
Research Methodology
Independent corroboration across connected fitness platform executives, corporate benefits administrators, MEMS sensor procurement leads, and boutique studio operations directors underwrites the qualitative findings. Primary interviews with biomechanical data scientists and regulatory affairs specialists at FDA-cleared device manufacturers combined with secondary validation from SEC filings, EU AI Act implementation guidance, and hospital procurement database extracts. Bottom-up unit economics modeling triangulates against top-down employer wellness spending estimates.
Comparable historical reference periods anchored the projection horizon to pre-pandemic corporate wellness procurement baselines and post-acceleration connected equipment adoption curves. The analytical framework segments by product architecture, technology integration depth, end-user procurement authority, and pricing model recurrence structure across the modeling period. CAGRs derive from biometric sensor cost curve trajectories, employer benefits budget elasticity estimates, and algorithmic personalization adoption velocity assumptions.
Caveats apply where FDA diagnostic claim enforcement intensity, Taiwan foundry capacity disruptions, or EU AI Act risk-classification reinterpretation could materially shift the outlook. Forecasts reflect assumptions about employer wellness program consolidation continuity and freemium-to-paid conversion rate stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
France Sports Teams and Clubs Market