
 North America Sports Promoter Market | 2026-2036
North America Sports Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Promoter Market Insights
Esports and mixed martial arts viewership is recalibrating how traditional sports promoters allocate talent and venue resources. Wasserman leverages its athlete representation strength to cross-sell event management services to corporate clients. Creative Artists Agency anchors premium pricing in talent management through exclusive roster control across multiple leagues. Nike competes by integrating footwear licensing directly into promoter-led sponsorship packages, bypassing conventional agency markups.
A sports promoter is an entity that organizes, finances, and markets live athletic competitions, typically securing venue contracts, broadcast rights, and corporate sponsorships to generate spectator revenue and media licensing fees. The role demands coordination of ticketing infrastructure, security protocols, and broadcast production standards to deliver commercially viable events. Sponsorship sales commands the largest margin pool among service types, as multi-year corporate partnerships lock in predictable revenue streams ahead of event execution cycles. Event management retains structural importance due to its capital-intensive nature and direct control over fan experience quality. Talent management represents the fastest-growing segment as athlete personal brands increasingly transcend team affiliations and drive independent monetization opportunities.
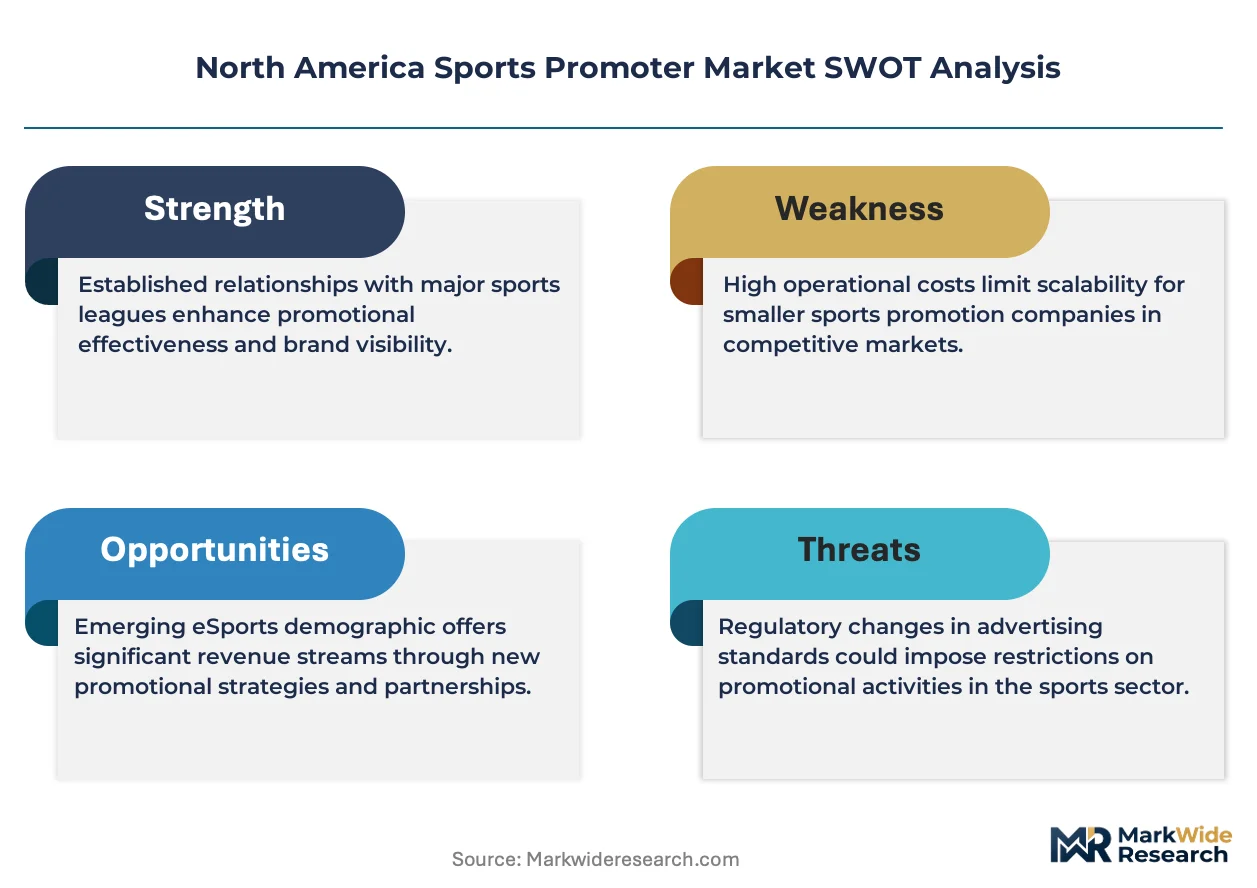
The FTC monitors advertising disclosure requirements for influencer-driven sports promotions, while state gaming commissions in New Jersey and Nevada enforce integrity standards around betting-affiliated events. OSHA guidelines shape venue staffing and crowd safety protocols that directly impact promoter operational costs. Stakeholders must track how emerging state-level sports betting regulations will redistribute sponsorship value between promoters, leagues, and digital platforms.
Market Dynamics
Corporate sponsorship budgets are pivoting from static media buys to experiential activations at live events, forcing promoters to reconfigure venue infrastructure and talent contracts around immersive fan engagement rather than traditional broadcast metrics.
Growth Catalysts
- State Sports Betting Expansion:The FCC's evolving advertising guidelines are unlocking new revenue streams as promoters integrate betting partnerships into event sponsorship packages across Nevada and New Jersey venues.
- Texas Stadium Infrastructure:Concentrated investment in Dallas and Houston arena developments is creating premium inventory for large-scale combat sports and esports tournaments that command higher per-seat yields.
- Athlete Personal Brand Monetization:Social media platform tools are enabling direct-to-fan commerce that promoters can license, reducing dependency on traditional broadcast rights splits.
Market Restraints
- Venue Construction Cost Inflation:Steel and specialized audio-visual equipment price volatility is compressing margins on multi-year venue lease commitments in California and Florida markets.
- Broadcast Rights Concentration:Three national networks control premium live sports distribution, extracting terms that limit promoter flexibility in secondary market exploitation.
- OSHA Crowd Safety Compliance:Evolving federal staffing and emergency response mandates are adding operational overhead to events exceeding 10,000 capacity thresholds.
Strategic Opportunities
- Underpenetrated Canadian Markets:Toronto and Vancouver lack dedicated mid-size venues (5,000-15,000 capacity) for emerging combat sports leagues, creating first-mover positioning for infrastructure investors.
- Mobile Ticketing and Wallet Integration:Smartphone-native access control is enabling dynamic pricing and real-time inventory management that increases yield per event.
- FTC Influencer Disclosure Framework:Clearer guidelines on athlete-endorsed promotions are legitimizing micro-influencer campaigns that promoters can package to regional sponsors at lower entry costs.
Industry Challenges
- Esports Production Talent Scarcity:Broadcast technicians skilled in simultaneous multi-platform streaming and in-arena screen synchronization command premium wages that strain event budgets.
- Legacy Ticketing System Integration:Migrating from established primary-market platforms to blockchain-verified resale controls requires capital expenditure without immediate revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Promoter Market |
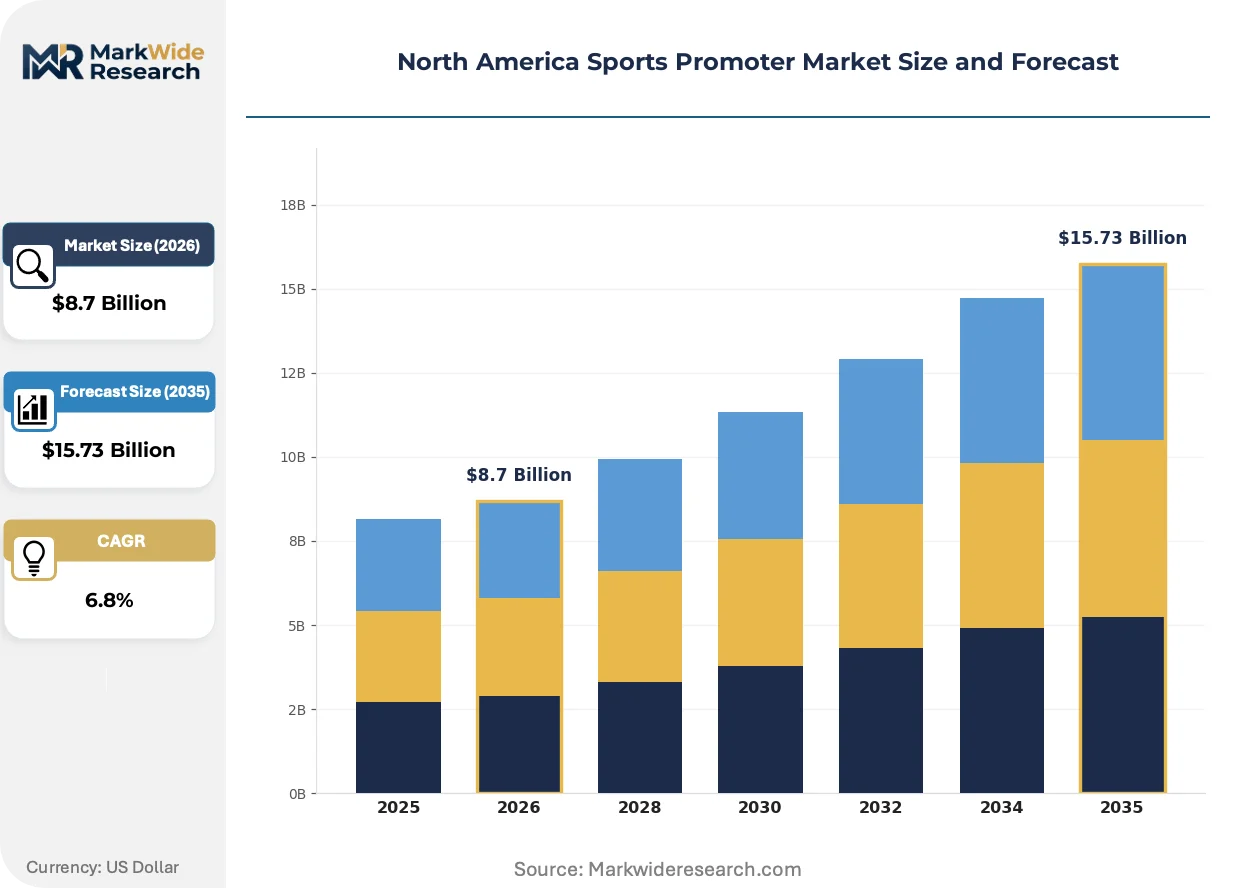
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Corporations, Agencies, Federations, Teams Service Type: Event Management, Sponsorship Sales, Marketing Strategy, Talent Management Sport: Football, Basketball, Baseball, Ice Hockey Partnership Type: Exclusive, Non-exclusive, Sponsorship, Media Rights |
| Companies Covered | USA Football, Major League Baseball, National Basketball Association, Wasserman, Creative Artists Agency, ESPN, Nike, Adidas, Fanatics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Promoter Market Trends and Innovations
Live event production is converging with gaming technology and real-time betting infrastructure, creating hybrid experiences that demand new technical capabilities from venue operators and promoter technical staff.
Computer vision and AI-driven camera systems are automating broadcast production workflows for mid-tier events that previously required manual director oversight. Regional mixed martial arts promoters in Texas and Arizona are adopting these tools to produce streaming-quality feeds at one-third of traditional crew costs. This compression is automating the democratization of content distribution, allowing smaller promoters to retain media rights rather than surrendering them to established networks.
The FTC's updated endorsement disclosure requirements are tightening enforcement around athlete-influencer partnerships that blur organic content and paid promotion. Promoters must now implement standardized contract language and monitoring protocols to avoid liability in campaigns featuring contracted talent. California and New York-based agencies are responding by building in-house compliance review functions that add 8-12% to campaign management overhead.
Fan acquisition patterns are fragmenting across platform-specific communities rather than consolidating around traditional league broadcast schedules. Younger demographics in urban Texas and California markets discover events through TikTok and Discord channels, displacing email marketing and sports radio as primary awareness drivers. This rotation is forcing promoters to maintain platform-native content teams and abandon centralized campaign management approaches.
North America Sports Promoter Market Segmentation
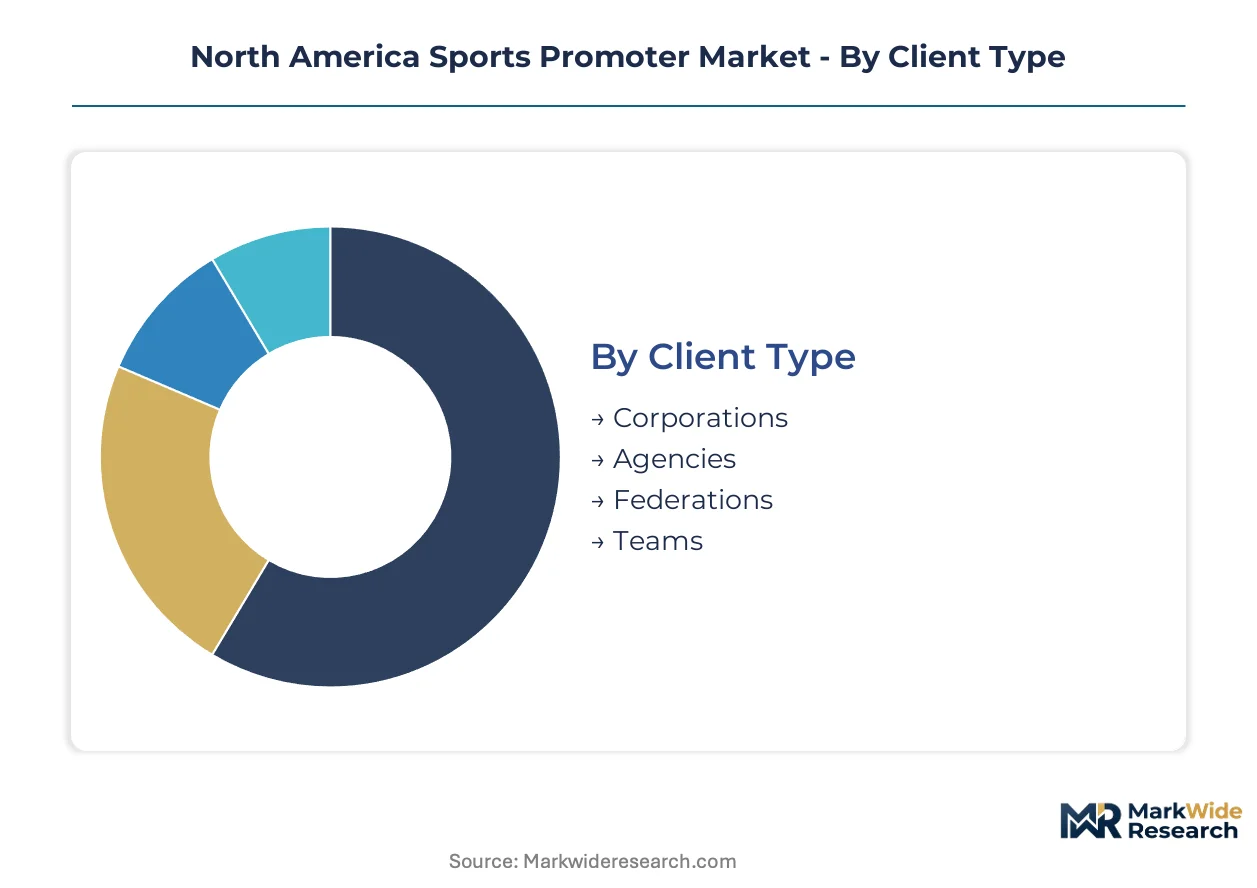
Promoter business models fragment sharply across client relationships and revenue mechanics. Each segmentation axis reveals distinct margin profiles, capital intensity requirements, and regulatory exposure that reshape competitive positioning.
Client Type:
Corporate buyers prioritize measurable ROI on experiential spend; federation clients demand governance compliance layered into contract structures.
- Corporations:Direct event ownership for brand activation and employee engagement programs. Demand concentrates in Texas and California where stadium infrastructure supports immersive fan experiences at scale. Procurement teams now mandate real-time attendance analytics and social media amplification metrics as standard contract terms.
- Agencies:Intermediary procurement of promoter services on behalf of brand clients. Growth tilts toward media agencies bundling talent representation with event production to capture margin pools previously split between separate vendors.
- Federations:Governing bodies outsourcing championship logistics and commercial rights management. NCAA and US Soccer Federation contracts in the US drive volume through multi-year tournament schedules.
- Teams:Franchise-level outsourcing of non-core event operations. NHL and NBA clubs in Canadian markets increasingly contract venue management to specialist promoters.
Volume sits with Corporations; growth tilts toward Agencies.
Service Type:
Margin capture varies dramatically by service layer, with front-loaded sponsorship sales yielding predictability and back-end talent management offering expansion optionality.
- Sponsorship Sales:Multi-year corporate partnership origination and renewal management. Multi-year corporate partnerships lock predictable revenue ahead of event execution cycles, with NFL and NBA properties commanding premium placement fees in US venues.
- Talent Management:Athlete representation, contract negotiation, and personal brand commercialization. Social media platform tools enable direct-to-fan commerce that promoters license, reducing dependency on traditional broadcast rights splits.
- Event Management:Venue contracting, security coordination, and broadcast production execution. Capital-intensive infrastructure control demands heavy upfront commitment in Texas and California stadium markets.
- Marketing Strategy:Audience development, ticketing optimization, and sponsor activation design. Regional promoters deploy platform-native content teams to capture fragmented fan acquisition across TikTok and Discord channels.
Revenue weight rests with Sponsorship Sales; Talent Management climbs fastest as athlete personal brands transcend team affiliations.
Sport:
Broadcast economics and venue specifications create divergent promoter engagement models across major league properties.
- Football:NFL and collegiate American football properties with stadium-scale production requirements. Dominates Texas and California infrastructure investment, where 60,000-plus capacity venues command premium per-seat yields for playoff and championship events.
- Basketball:NBA, WNBA, and collegiate basketball with arena-configurable formats. Mid-size venue flexibility supports touring exhibition models and international preseason schedules originating from US markets.
- Baseball:MLB properties with seasonal scheduling density and regional travel patterns. Ballpark-specific production standards limit promoter portability across venue types.
- Ice Hockey:NHL and minor league operations with specialized rink infrastructure requirements. Canadian market concentration creates distinct procurement patterns versus US-based promoter economics.
Football anchors absolute revenue; Basketball offers format adaptability for emerging experiential formats.
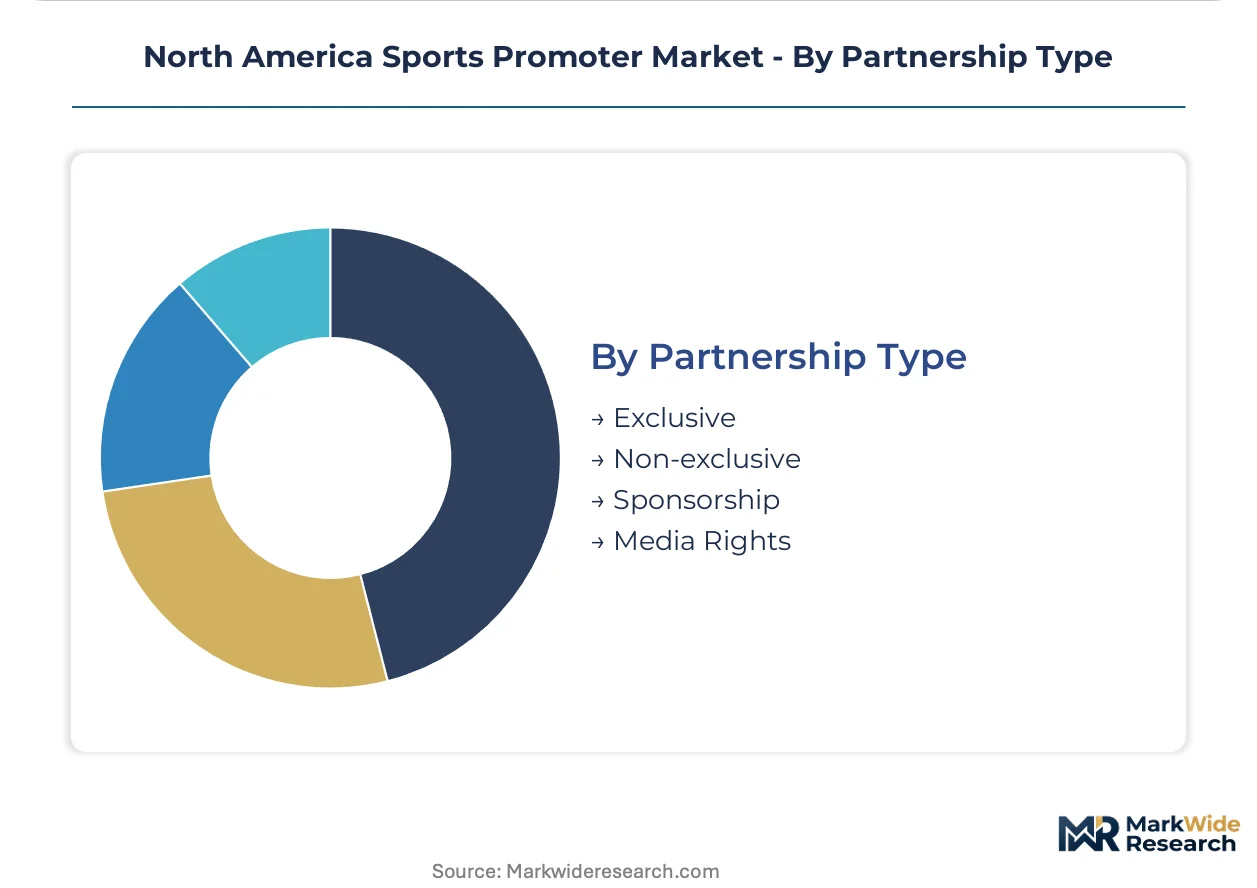
Partnership Type:
Contract exclusivity determines competitive moat depth and revenue stability across promoter portfolios.
- Exclusive:Sole promoter rights for defined territories, properties, or time periods. UFC and WWE maintain exclusive promoter relationships with Nevada and Texas venues that block competitor access to premium dates.
- Sponsorship:Brand-funded event activation without full property control. Corporate partners in California demand standardized FTC disclosure compliance across athlete-influencer campaigns.
- Media Rights:Licensed broadcast and streaming distribution arrangements. Three national network concentration limits promoter flexibility in secondary market exploitation.
- Non-exclusive:Shared promoter access with competitive scheduling risk. Emerging combat sports leagues accept non-exclusive terms to secure venue access in underpenetrated Canadian markets.
Exclusive partnerships concentrate margin; Non-exclusive structures expand addressable inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Opportunity Zones and California enterprise districts are concentrating sports promoter infrastructure investment through accelerated depreciation incentives and venue development bonds. These tax-advantaged structures are redirecting capital toward experiential event facilities in Dallas-Fort Worth and Los Angeles corridors.
United States
NFL and NBA properties drive promoter revenue concentration in Texas and California markets. OSHA crowd safety mandates for events exceeding 10,000 capacity are adding operational overhead to stadium operations. Dallas and Houston anchor the largest venue development pipeline, with 60,000-plus capacity facilities commanding premium per-seat yields for combat sports and esports tournaments.
Canada
Toronto and Vancouver exhibit underpenetrated mid-size venue capacity for emerging combat sports leagues. Health Canada advertising standards for athlete endorsements are tightening disclosure requirements for cross-border promotional campaigns. Ontario's Greater Toronto Area is attracting first-mover infrastructure investors targeting the 5,000-15,000 capacity gap in dedicated event facilities.
Mexico
Mexico City metropolitan demand for international exhibition matches is expanding promoter addressable inventory. The country's national consumer protection regulator is enforcing transparency standards for ticket resale platforms operating across border markets. Nuevo León's Monterrey corridor is developing arena infrastructure to capture touring revenue from US-based combat sports properties.
North America Sports Promoter Market Competitive Landscape
Top-tier vendors anchor exclusive league partnerships and talent representation rosters, while mid-tier promoters compete on regional venue access and non-exclusive event packaging. The vendor base stratifies across three tiers: integrated agencies controlling athlete representation and event production, specialized venue operators with broadcast production capabilities, and regional promoters focused on single-sport or single-market concentration. Dominant competitive moves include exclusive venue lease negotiations locking competitor access to premium dates, and backward integration into talent representation to capture margin pools previously split between separate service providers.
Within the integrated agency tier, Wasserman and Creative Artists Agency exemplify the cross-selling model combining athlete representation with corporate event management. Wasserman leverages its athlete roster strength to bundle talent procurement with venue logistics for brand clients. Creative Artists Agency occupies a position defined by exclusive roster control across multiple leagues, enabling premium pricing in talent management services. ESPN represents the broadcast-anchored archetype, competing through media rights concentration that limits promoter flexibility in secondary market exploitation.
| Leading Market Players |
|---|
| USA Football |
| Major League Baseball |
| National Basketball Association |
| Wasserman |
| Creative Artists Agency |
| ESPN |
| Nike |
| Adidas |
| Fanatics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up venue operators in Texas and California anchor supply concentration while enforcing pricing discipline through multi-year lease commitments and exclusive date holds. Their capital structure demands yield optimization that feeds back into sponsor package pricing and talent contract structures.
Pricing Analysis
Lead-time-driven pricing stratification separates premium placements for short-fuse activations from discounted inventory for annual commitments booked 12-18 months ahead. Three-tier pricing structure across premium, standard, and economy levels reflects venue tier, broadcast integration depth, and athlete roster exclusivity. Cost compression in mid-tier sponsorship packages is intensifying because corporate procurement teams now mandate real-time analytics as standard contract terms. Regional promoters in underpenetrated Canadian markets exhibit highest price sensitivity; integrated agencies with exclusive league partnerships command least.
Supply Chain Analysis
OSHA certification and state gaming commission licensing gate supplier participation in premium venue tiers, filtering out unqualified operators. Supply concentrates in the United States, Canada, and Mexico, with specialized audio-visual equipment and broadcast production talent drawing from California and Texas labor pools. Single-source vulnerability runs through esports production technician pools, where simultaneous multi-platform streaming skills command premium wages. Distribution runs through primary-market ticketing platforms, venue-direct corporate sales teams, and agency intermediary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venue construction cost inflation and specialized production talent scarcity prop pricing power for incumbent operators with locked-in infrastructure. Supply constraints favor capital-heavy players with existing lease portfolios.
For Market Incumbents: Extend exclusive venue date holds in Dallas-Fort Worth and Los Angeles corridors to block competitor access to premium inventory. Deepen backward integration into talent representation to capture margin pools previously split between separate service providers, defending against media agency bundling threats. For New Entrants and Emerging Players: Launch via non-exclusive venue arrangements in Toronto and Vancouver's 5,000-15,000 capacity gap, targeting emerging combat sports leagues with mobile ticketing and wallet integration as the go-to-market wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional promoters with locked venue leases in Texas Opportunity Zones, where accelerated depreciation incentives enhance cash flow profiles. Long-term viability hinges on exclusive league relationship durability; watch for FCC sports betting advertising rule finalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Venue Lease Negotiation | Blocks competitor access to premium dates in Dallas and Houston arena developments. |
| Backward Integration into Talent Representation | Captures athlete personal brand monetization margin previously surrendered to separate agencies. |
| Mobile Ticketing and Wallet Integration | Enables dynamic pricing and real-time inventory management for yield optimization. |
| Esports Production Capability Buildout | Addresses broadcast technician scarcity through in-house multi-platform streaming expertise. |
| FTC Compliance Function Development | Mitigates liability exposure in athlete-influencer campaigns through standardized contract protocols. |
Research Methodology
Multi-period observation of venue development pipelines, sponsorship contract structures, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with event operations directors, corporate sponsorship procurement leads, state gaming commission officials, and broadcast production managers. Secondary validation drew from FCC rulemaking dockets, OSHA enforcement records, SEC filings of publicly traded venue operators, and municipal bond disclosures for stadium infrastructure projects. Bottom-up event volume modeling and top-down market sizing triangulated value estimates.
Segment-weighting across client type, service type, sport category, and partnership exclusivity tiers structured the analytical framework. CAGRs were derived from trend extrapolation of historical venue revenue per seat, sponsorship renewal rates, and talent management commission growth across the projection horizon. Industry-specific inputs included state-level sports betting legalization timelines and stadium construction cost indices.
Regulatory reversal on sports betting advertising, venue construction cost spikes beyond historical volatility bands, and esports viewership fragmentation are the dominant revision risks to modeled forecasts. A model refresh is warranted upon material change in FCC guidance or Texas stadium development bond issuance patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Smart Swimming Caps Market