
 Smart SIM Market | 2026-2036
Smart SIM Market Size, Share, and Industry Trends Forecast 2026-2036
Smart SIM Market Analytics
GDPR is repositioning data residency requirements for subscriber identity modules across European deployments. Thales Group leverages its aerospace-grade security heritage to anchor high-assurance Smart SIM contracts with tier-one automotive OEMs. Giesecke+Devrient sustains manufacturing scale through backward integration into secure microcontroller fabrication. Infineon Technologies specializes in tamper-resistant hardware architectures that dominate industrial IoT authentication use cases.
A Smart SIM is a reprogrammable integrated circuit that stores international mobile subscriber identity numbers and network authentication keys, typically manufactured on Common Criteria EAL4+ certified silicon with embedded secure elements and Java Card operating systems. Its primary purpose is to enable remote provisioning of cellular subscriptions without physical card replacement, supporting machine-to-machine and consumer device connectivity at scale. eSIM technology leads the technology segment due to its GSMA-standardized remote provisioning architecture and established carrier certification pathways, while iSIM is expanding fastest as system-on-chip integration eliminates discrete component costs in space-constrained wearables. Automotive connectivity commands the deepest margin pools within the application segment because long vehicle lifecycles demand decade-long security update commitments and multi-network roaming contracts.
FCC equipment authorization rules in the United States mandate cybersecurity labeling for IoT devices, directly elevating hardware-based identity standards for cellular modules. ETSI standards in Europe enforce interoperability testing that filters non-compliant virtual SIM implementations from carrier networks. BIS certification requirements in India restrict import of uncertified cryptographic modules, creating localized compliance barriers for foreign Smart SIM suppliers. Stakeholders must monitor whether emerging national digital sovereignty frameworks fragment remote provisioning standards into incompatible regional regimes.
Market Dynamics
GSMA Remote SIM Provisioning specifications are compressing carrier certification timelines and forcing hardware suppliers to embed security at the silicon design stage rather than module assembly.
Growth Catalysts
- Automotive OEM mandates:Connected vehicle platforms require decade-long secure update capabilities that only embedded Smart SIM architectures deliver.
- ETSI interoperability testing:European carrier networks filter non-compliant virtual SIM implementations, creating hardware pull-through for certified modules.
- Machine-to-machine scale:Industrial IoT deployments demand zero-touch provisioning across distributed asset bases without physical technician visits.
Market Restraints
- Secure element cost concentration:Common Criteria EAL4+ certified silicon fabrication concentrates among three foundry sources in Taiwan and South Korea.
- BIS import barriers:India's cryptographic module certification requirements delay foreign Smart SIM market entry by 18-24 months.
- iSIM thermal limitations:Integrated SIM architectures face reliability constraints above 85°C operating temperatures in automotive engine compartments.
Strategic Opportunities
- Wearable form factors:System-on-chip integration eliminates discrete component footprint constraints in medical monitoring devices.
- FCC cybersecurity labeling:United States IoT device authorization rules elevate hardware-based identity to a procurement differentiator.
- German automotive ecosystem:Early eSIM mandate alignment creates reference architecture advantages for suppliers qualifying with Munich and Stuttgart OEMs.
Industry Challenges
- Secure microcontroller talent scarcity:Java Card operating system expertise concentrates among aging specialist engineering pools in France and Germany.
- Carrier certification timeline compression:GSMA specification updates require simultaneous requalification across 40+ operator test labs.
- Legacy fleet integration:Removable SIM infrastructure in installed industrial equipment blocks seamless remote provisioning migration paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart SIM Market |
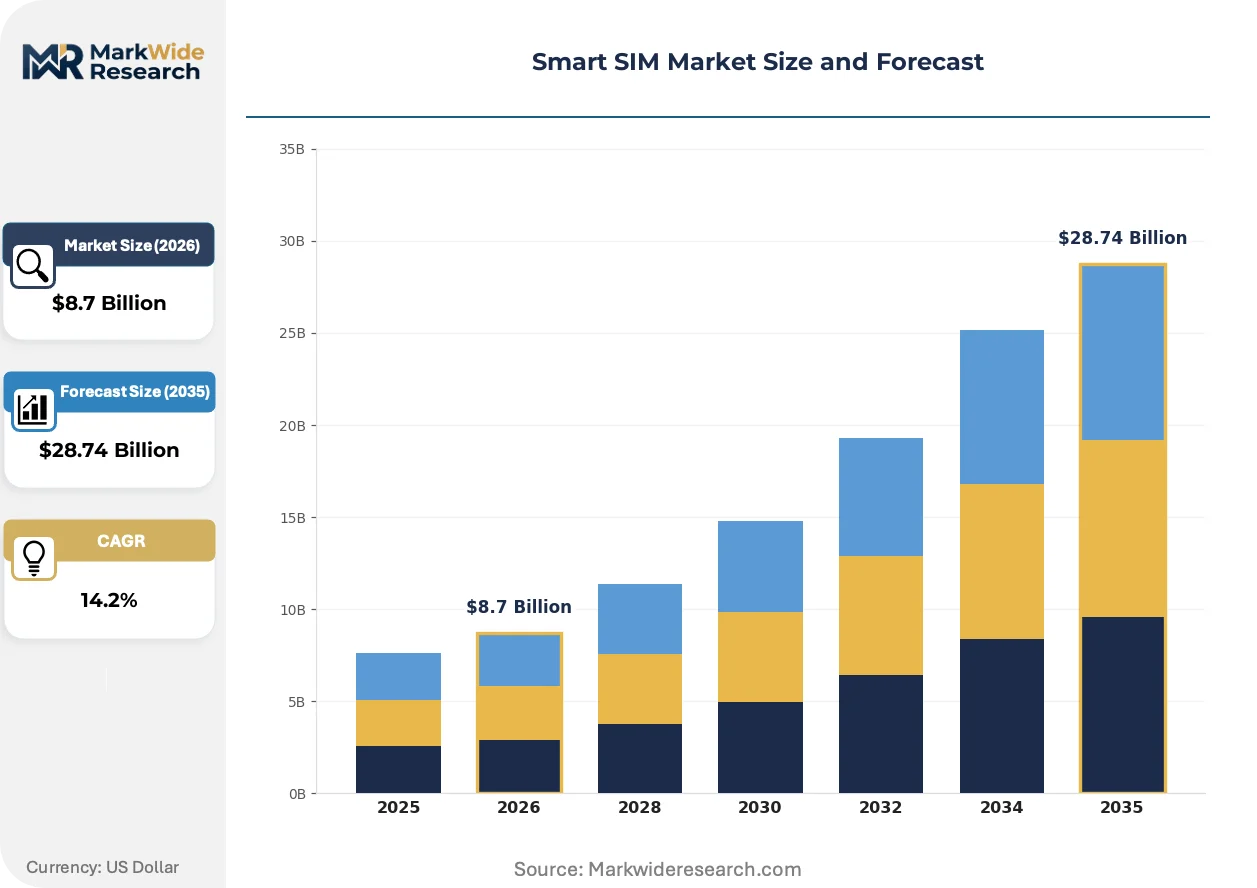
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: eSIM, iSIM, Soft SIM, Virtual SIM Application: Consumer Electronics, M2M Communication, Automotive Connectivity, Wearable Devices End User: Telecom Operators, OEMs, Enterprises, Government Distribution Channel: Online Sales, Retail Stores, Distributors, Wholesalers |
| Companies Covered | Giesecke+Devrient, Thales Group, STMicroelectronics, Infineon Technologies, NXP Semiconductors, Samsung Electronics, AT&T, Deutsche Telekom, Idemia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart SIM Market Evolving Landscape
Remote provisioning architectures are collapsing the traditional SIM distribution chain from physical logistics to digital entitlement delivery, compressing working capital requirements and reordering value capture.
Embedded Universal Integrated Circuit Card (eUICC) technology is automating subscription profile management across carrier boundaries without physical card replacement. Automotive OEMs in Germany and Japan are adopting eUICC as standard for connected vehicle telematics units. This is automating the previously manual process of negotiating roaming agreements and provisioning credentials across multi-national vehicle fleets.
GDPR data residency requirements are mandating localized subscriber identity storage for European deployments. The regulation forces Smart SIM vendors to architect regional credential vaults rather than centralized cloud provisioning. Industrial IoT buyers in Germany and France now specify EU-sovereign infrastructure as a contractual precondition.
After-sales service unbundling is separating connectivity management from hardware supply in enterprise procurement. Fleet operators and industrial asset managers now contract directly with mobile virtual network enablers rather than purchasing bundled modules from system integrators. This pattern is most visible in United States logistics and German manufacturing verticals where total cost of ownership transparency drives sourcing decisions.
Smart SIM Market Segmentation
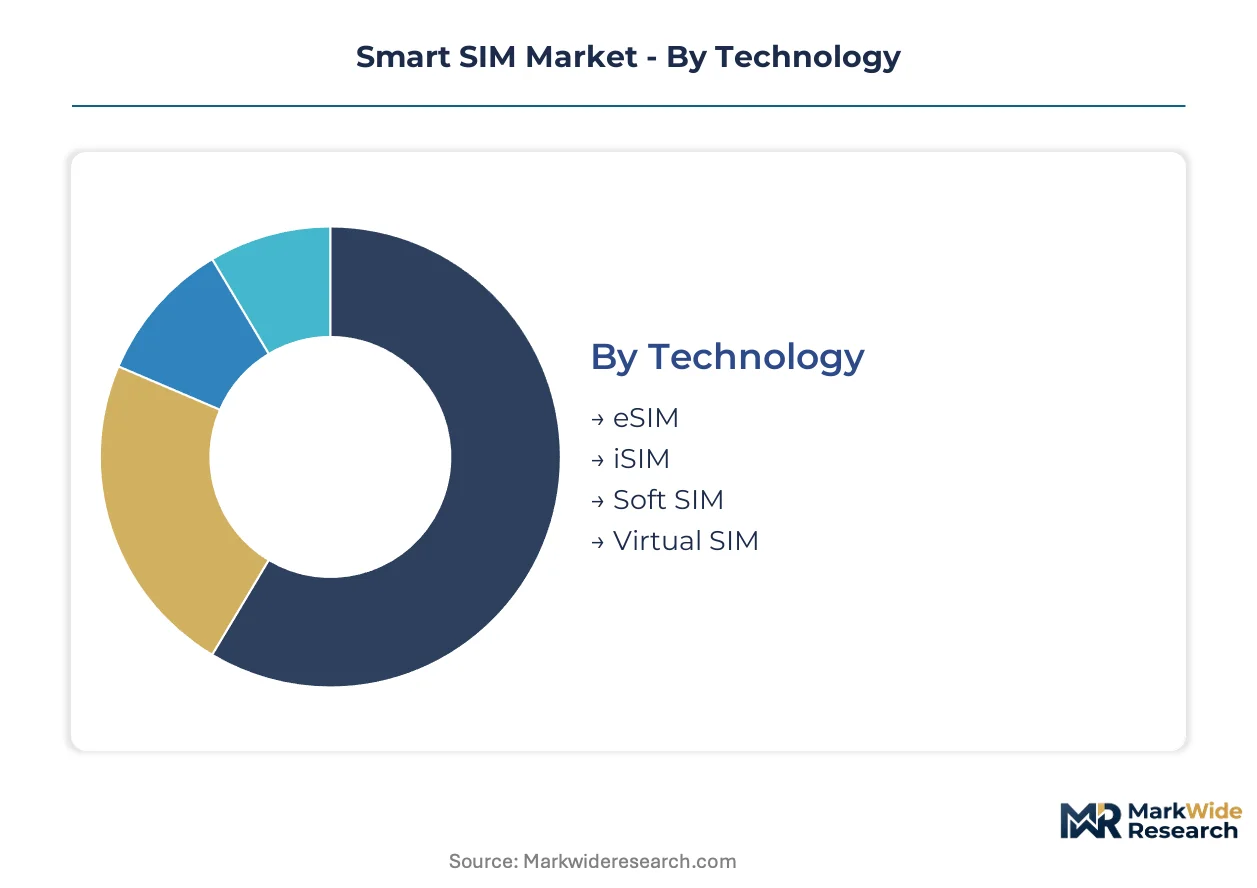
Smart SIM segmentation reveals how provisioning architecture, application security requirements, and procurement authority reshape supplier economics. Each dimension exposes different margin pools and certification barriers.
Technology:
Buyers differentiate by integration depth versus certification burden, trading component elimination against thermal and security validation costs.
- eSIM:Embedded Universal Integrated Circuit Card technology stores multiple operator profiles on GSMA-standardized secure elements. Automotive OEMs in Germany specify eSIM for connected vehicle telematics requiring decade-long security update commitments and multi-network roaming contracts.
- iSIM:Integrated SIM architectures embed subscription management directly into system-on-chip designs, eliminating discrete component footprint and bill-of-materials cost. Wearable manufacturers in South Korea and Japan prioritize iSIM for medical monitoring devices where space constraints dominate design decisions, though thermal limitations above 85°C restrict automotive engine compartment deployment.
- Soft SIM:Software-based credential storage runs on host processor secure enclaves without dedicated hardware elements. IoT module vendors targeting cost-sensitive logistics trackers in United States freight markets favor Soft SIM for rapid carrier switching.
- Virtual SIM:Cloud-hosted subscriber identity abstracts physical hardware entirely through network-based authentication. Enterprise mobility platforms in France deploy Virtual SIM for temporary workforce connectivity without device provisioning overhead.
eSIM leads volumes today; iSIM is gaining share fastest.
Application:
Security lifecycle requirements stretch from consumer replacement cycles to industrial decades, fragmenting supplier qualification paths.
- Automotive Connectivity:Connected vehicle platforms demand tamper-resistant hardware architectures with Common Criteria EAL4+ certification and over-the-air provisioning capabilities spanning fifteen-year vehicle lifecycles. German and Japanese OEMs mandate embedded Smart SIM as standard for telematics units, automating roaming agreement negotiation across multinational fleets.
- M2M Communication:Industrial IoT deployments require zero-touch provisioning across distributed asset bases without physical technician visits. Manufacturing facilities in Germany specify remote provisioning for predictive maintenance sensors where downtime costs exceed connectivity premiums.
- Consumer Electronics:Smartphones and tablets leverage eSIM for dual-SIM functionality and simplified carrier switching. Premium device manufacturers in South Korea integrate embedded provisioning to differentiate flagship models.
- Wearable Devices:Medical monitoring and fitness trackers prioritize iSIM integration for minimal power draw and waterproof sealing. Health technology developers in Switzerland specify system-on-chip solutions for continuous glucose monitors.
Automotive Connectivity commands the steepest expansion trajectory; Wearable Devices show the fastest volume acceleration.
End User:
Procurement authority concentrates with entities controlling subscription revenue streams versus hardware integration decisions.
- Telecom Operators:Mobile network operators provision subscriber identities at scale, capturing recurring revenue from connectivity services. European carriers enforce ETSI interoperability testing that filters non-compliant implementations from certified networks.
- OEMs:Original equipment manufacturers embed Smart SIM during device assembly, controlling hardware-software integration. Automotive OEMs in Stuttgart and Munich anchor qualification requirements that cascade through supplier ecosystems.
- Enterprises:Fleet operators and industrial asset managers contract directly with mobile virtual network enablers rather than purchasing bundled modules. United States logistics verticals drive after-sales service unbundling for total cost of ownership transparency.
- Government:Public sector deployments emphasize sovereign credential storage and domestic certification compliance. India's BIS cryptographic module requirements delay foreign supplier market entry by 18-24 months.
Telecom Operators anchor current procurement volumes; Enterprises are expanding most quickly.
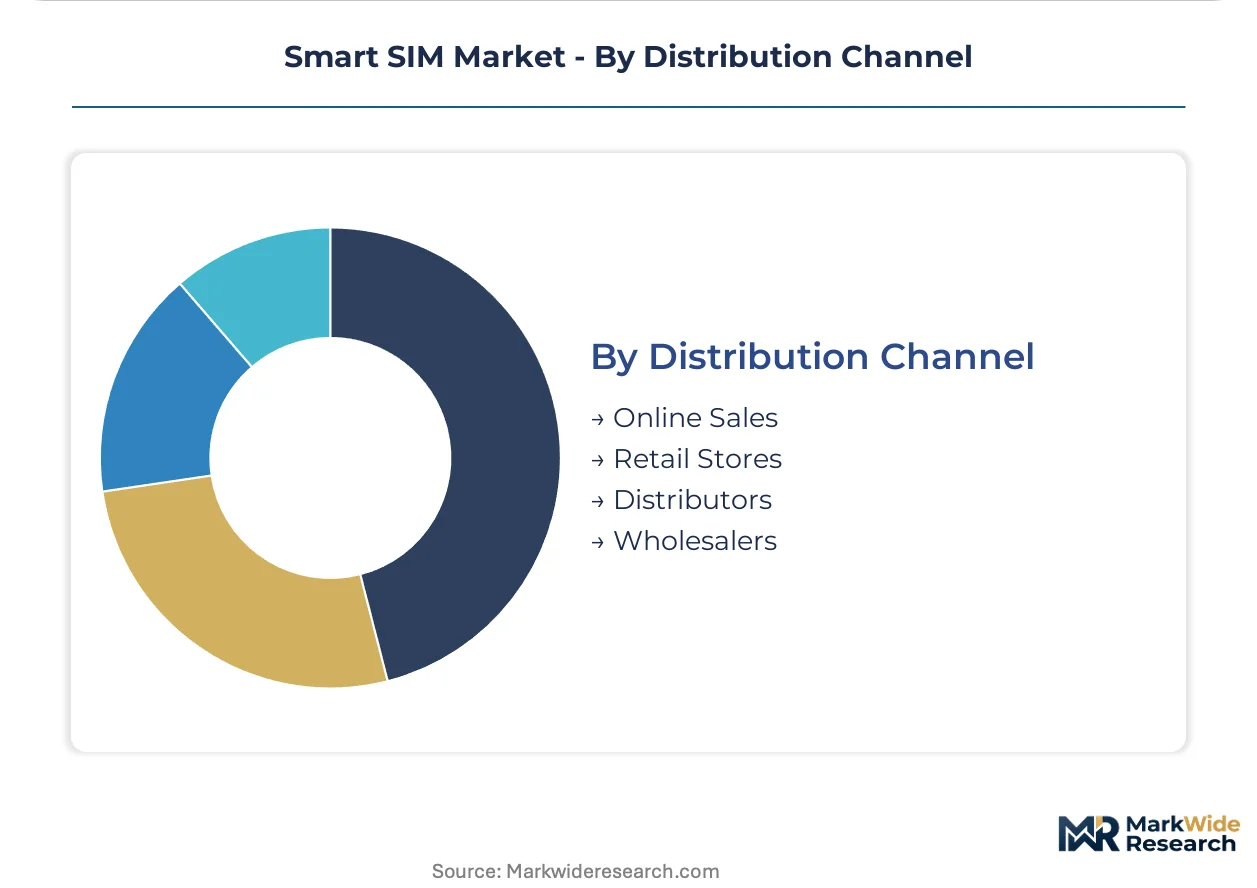
Distribution Channel:
Channel selection reflects buyer technical sophistication and volume scale, with direct digital routes displacing physical logistics for provisioned credentials.
- Online Sales:Digital entitlement delivery compresses working capital requirements and accelerates procurement cycles for technically sophisticated enterprise buyers. Industrial IoT platforms in United States logistics verticals favor direct online procurement for transparency.
- Distributors:Value-added distributors provide technical integration support and regional compliance navigation for mid-scale deployments. European industrial automation suppliers route through distributors for GDPR-aligned data residency architecture.
- Retail Stores:Consumer-facing electronics retailers handle physical device sales with embedded eSIM activation. Premium smartphone channels in South Korea emphasize in-store provisioning experience.
- Wholesalers:Volume resellers aggregate demand from smaller IoT device manufacturers without direct carrier relationships. Regional wholesalers in India navigate BIS import barriers for uncertified module suppliers.
Distributors dominate transaction volumes today; Online Sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist engineering pools in France and Germany anchor secure microcontroller design capabilities, while foundry concentration in Taiwan and South Korea shapes silicon fabrication geography. Regulatory fragmentation across major economies is forcing credential localization and compliance diversification.
Germany
Automotive OEM mandates from Stuttgart and Munich OEMs drive embedded Smart SIM qualification at scale. KBA vehicle type approval processes enforce cybersecurity standards for connected vehicle telematics. The Baden-Württemberg automotive cluster hosts supplier ecosystems qualifying decade-long security update architectures for multinational fleets.
United States
Fleet operators in logistics verticals contract directly with mobile virtual network enablers for total cost transparency. FCC cybersecurity labeling rules for IoT devices elevate hardware-based identity procurement standards. The Midwest industrial corridor automates predictive maintenance sensor deployment through zero-touch provisioning across distributed manufacturing assets.
India
Domestic manufacturing incentives accelerate local secure element assembly for cost-sensitive IoT modules. BIS cryptographic module certification delays foreign supplier market entry by 18-24 months. The Maharashtra-Gujarat electronics manufacturing belt concentrates module integration facilities serving regional industrial automation demand.
South Korea
Wearable manufacturers prioritize system-on-chip integration for medical monitoring devices with severe space constraints. MFDS medical device regulations intersect with telecom certification for health technology deployments. The Seoul capital area cluster drives iSIM volume for premium consumer electronics and continuous glucose monitor specifications.
Japan
Connected vehicle platforms from Nagoya and Tokyo OEMs standardize eUICC for telematics units automating roaming negotiation. METI industrial policy supports secure element supply chain resilience for critical infrastructure. The Chubu automotive corridor anchors qualification requirements cascading through tier-one supplier networks.
Smart SIM Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across secure element fabrication and remote provisioning services. Three foundry sources in Taiwan and South Korea concentrate Common Criteria EAL4+ certified silicon supply, creating tiered access structures. Strategic archetypes include aerospace-grade security heritage players, backward-integrated secure microcontroller fabricators, and tamper-resistant hardware specialists. Competitive moves center on carrier certification timeline compression and geographic qualification diversification to navigate BIS import barriers.
Within the security heritage tier, Thales Group exemplifies aerospace-grade credential anchoring with tier-one automotive OEMs. Giesecke+Devrient occupies a position as a backward-integrated fabricator controlling secure microcontroller production. Infineon Technologies represents the tamper-resistant hardware archetype dominating industrial IoT authentication specifications. These three entities collectively illustrate how certification depth and manufacturing control separate premium-tier positioning from module-assembly competitors.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| Thales Group |
| STMicroelectronics |
| Infineon Technologies |
| NXP Semiconductors |
| Samsung Electronics |
| AT&T |
| Deutsche Telekom |
| Idemia |
| Others |
Value Network & Pricing Analysis
GDPR data residency mandates gate qualified supply for European deployments and anchor premium-tier pricing for EU-sovereign credential vaults. German automotive OEMs and French industrial buyers now specify localized subscriber identity storage as a contractual precondition, compressing hardware margins for non-compliant foreign suppliers while elevating certified domestic providers.
Pricing Analysis
Bundled hardware-connectivity packages from system integrators command 15-25% premiums over unbundled module procurement by fleet operators contracting directly with mobile virtual network enablers. Price differentiation hinges on Common Criteria EAL4+ certification grade and decade-long security update commitments demanded by automotive OEMs. Cost compression in standard-grade IoT modules intensifies as South Korean and Chinese suppliers scale iSIM integration, while premium-tier automotive connectivity maintains pricing power through qualification barriers. Enterprise logistics buyers in the United States exhibit highest price sensitivity, whereas German OEMs prioritize certification depth over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand from Stuttgart and Munich manufacturers, while value-added distributors serve mid-scale European industrial automation buyers navigating GDPR-aligned data residency architectures. Secure element fabrication concentrates in Taiwan and South Korea, with Common Criteria EAL4+ certified silicon drawing from three dominant foundry sources. Raw material dependencies span silicon wafers, secure microcontroller cores, and Java Card operating system licenses. Single-source vulnerability in secure element supply creates structural risk, as BIS import barriers in India and emerging digital sovereignty frameworks threaten to fragment remote provisioning standards into incompatible regional regimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart SIM margin expansion rests on system-on-chip integration eliminating discrete component costs in wearables and medical devices, while premium-tier automotive connectivity commands decade-long security update premiums.
For Market Incumbents: Deepen carrier certification pre-qualification across 40+ operator test labs to compress requalification timelines when GSMA specifications update. Anchor backward integration into secure microcontroller fabrication to defend against emerging iSIM specialists threatening component elimination. Infineon Technologies and Giesecke+Devrient demonstrate how captive silicon supply insulates margin pools from foundry concentration risk in Taiwan and South Korea. For New Entrants and Emerging Players: Launch via direct online sales channels targeting United States logistics verticals where after-sales service unbundling has already separated connectivity procurement from hardware bundling. Exploit BIS certification delays blocking foreign suppliers in India by partnering with domestic Maharashtra-Gujarat electronics manufacturing belt assemblers. White-space opportunity concentrates in cost-sensitive Soft SIM implementations for freight trackers where rapid carrier switching outweighs hardware security depth. For Investors and Strategic Acquirers: Roll-up economics work for secure microcontroller specialists because Java Card operating system expertise concentrates among aging engineering pools in France and Germany with limited talent replenishment. Target acquisition archetypes include tier-two module assemblers lacking carrier certification depth but holding automotive OEM relationships in Nagoya and Tokyo corridors. Watch for inflection when national digital sovereignty frameworks fragment remote provisioning standards, creating localized compliance premiums for regionally qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Certification Pre-Qualification | GSMA specification updates require simultaneous requalification across 40+ operator test labs. |
| System-on-Chip Integration | iSIM eliminates discrete component footprint in South Korean wearable medical monitors. |
| EU-Sovereign Infrastructure Deployment | GDPR mandates localized credential vaults rather than centralized cloud provisioning. |
| Automotive OEM Qualification | Stuttgart and Munich OEMs anchor decade-long security update architecture requirements. |
| Direct-to-Enterprise Channel Development | United States logistics verticals contract directly with mobile virtual network enablers. |
Research Methodology
Coverage spans Germany, United States, India, South Korea, and Japan, with primary inputs from each market cluster. The analysis combines structured interviews with automotive OEM platform engineers, mobile network operator certification leads, secure microcontroller R&D directors, industrial IoT procurement managers, and semiconductor foundry planning officers. Secondary validation draws from GSMA specification documents, ETSI interoperability testing protocols, FCC equipment authorization filings, BIS cryptographic module certification records, and automotive telematics supplier disclosures. Bottom-up module shipment analysis triangulates against top-down connectivity service revenue estimates.
Segmentation granularity extends to technology architecture (eSIM, iSIM, Soft SIM, Virtual SIM), application security lifecycle (automotive, M2M, consumer, wearable), end-user procurement authority (operators, OEMs, enterprises, government), and distribution channel structure (online, distributors, retail, wholesale). CAGRs derive from installed base penetration curves, vehicle production forecasts, and industrial IoT sensor deployment trajectories across the projection horizon. Industry-specific inputs include KBA vehicle type approval timelines, MFDS medical device certification intersects, and METI supply chain resilience policy frameworks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated national digital sovereignty fragmentation or sustained secure element foundry concentration. The analysis reflects assumptions regarding GSMA specification adoption rates, automotive OEM mandate alignment timelines, and regulatory certification pathway stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Diameter Signaling Control Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
5G Transport Networks Market
Telecommunications
Global Telecommunication Market
Telecommunications
Indonesia Volte Market
Telecommunications
South Africa Telecom Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Cloud RAN Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Global 4G LTE Market