
 Cloud RAN Market | 2026-2036
Cloud RAN Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud RAN Market Analysis
Modular hardware-software separation is restructuring procurement patterns across telecom infrastructure. Ericsson AB leverages its integrated portfolio to anchor large-scale brownfield deployments with incumbent carriers. Nokia Corporation competes through cloud-native software layers that extend across multi-vendor radio environments. Samsung Electronics Co., Ltd. specializes in mmWave-optimized vDU solutions that dominate greenfield 5G buildouts in North American and Asian markets.
Cloud RAN disaggregates baseband processing from proprietary radio hardware through virtualized distributed units and centralized units running on commercial off-the-shelf servers. The architecture employs x86 or ARM-based edge servers with FPGA acceleration, fronthaul interfaces compliant with eCPRI or IEEE 1914.3, and containerized network functions orchestrated via Kubernetes. Open RAN deployments are gaining structural momentum as interoperability testing matures and operator consortiums enforce vendor diversity mandates. Private RAN installations for manufacturing campuses and mining operations represent the fastest-expanding margin pool, while V-RAN retains volume leadership through tier-one operator core networks. Multicloud deployment models are emerging as the preferred architecture for operators seeking workload portability between hyperscaler edge zones and on-premise data centers.
The Federal Communications Commission in the United States, the Ministry of Industry and Information Technology in China, and the European Telecommunications Standards Institute collectively shape equipment certification timelines, spectrum allocation rules, and open interface mandates that determine market access conditions. The O-RAN Alliance security specifications and national critical infrastructure protection frameworks are tightening compliance requirements for software supply chain transparency. Stakeholders must monitor spectrum refarming decisions and open RAN interoperability certification progress to calibrate capital allocation between proprietary and disaggregated technology paths.
Market Dynamics
The O-RAN Alliance's open interface specifications and 3GPP Release 17 standards are dismantling decades of vendor lock-in, forcing infrastructure providers to compete on software differentiation rather than proprietary hardware integration. This structural disaggregation is redrawing procurement power toward mobile network operators.
Growth Catalysts
- Network slicing demand:Enterprise verticals require dedicated virtual networks for manufacturing automation and remote surgery applications. Mobile operators deploy Cloud RAN to instantiate isolated network slices on shared infrastructure.
- Spectrum refarming mandates:The FCC's mid-band auction rules and Germany's 5G coverage obligations are accelerating infrastructure replacement cycles. Operators must modernize baseband architectures to support new frequency allocations.
- Edge computing convergence:Kubernetes-orchestrated containerized network functions enable co-location of RAN processing with enterprise workloads. Hyperscaler edge zones in Dallas, Frankfurt, and Seoul are absorbing distributed unit deployments.
Market Restraints
- FPGA supply concentration:Xilinx and Intel dominate programmable logic acceleration for massive MIMO signal processing. Foundry capacity constraints at TSMC extend lead times for virtualized distributed unit hardware.
- Fronthaul fiber dependency:Dark fiber availability limits centralized unit placement in suburban and rural geographies. Trenching costs per kilometer exceed equipment expenditure in markets with sparse fiber infrastructure.
- Interoperability certification gaps:O-RAN Alliance plugfests have validated only subset combinations of radio units and distributed units. Incomplete testing matrices delay multi-vendor deployment confidence.
Strategic Opportunities
- Private RAN campus networks:Mining operations in Western Australia and automotive facilities in South Carolina are procuring standalone 5G infrastructure. These installations bypass traditional operator channels entirely.
- AI-driven RAN optimization:Machine learning inference at the distributed unit enables real-time beamforming adaptation. Convergence of NVIDIA GPU platforms with Ericsson software stacks is creating new solution bundles.
- Open RAN software services:Systems integrators are capturing margin pools previously retained by equipment vendors. Accenture and Tech Mahindra are building practices around multi-vendor integration and lifecycle management.
Industry Challenges
- vDU engineering scarcity:Expertise in real-time kernel optimization and FPGA bitstream development concentrates at Qualcomm and Marvell. Operators struggle to hire engineers capable of troubleshooting latency violations in containerized baseband.
- Brownfield integration complexity:Legacy Ericsson and Nokia macro sites use proprietary CPRI interfaces incompatible with open fronthaul specifications. Retrofit projects require parallel overlay networks or expensive gateway translation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud RAN Market |
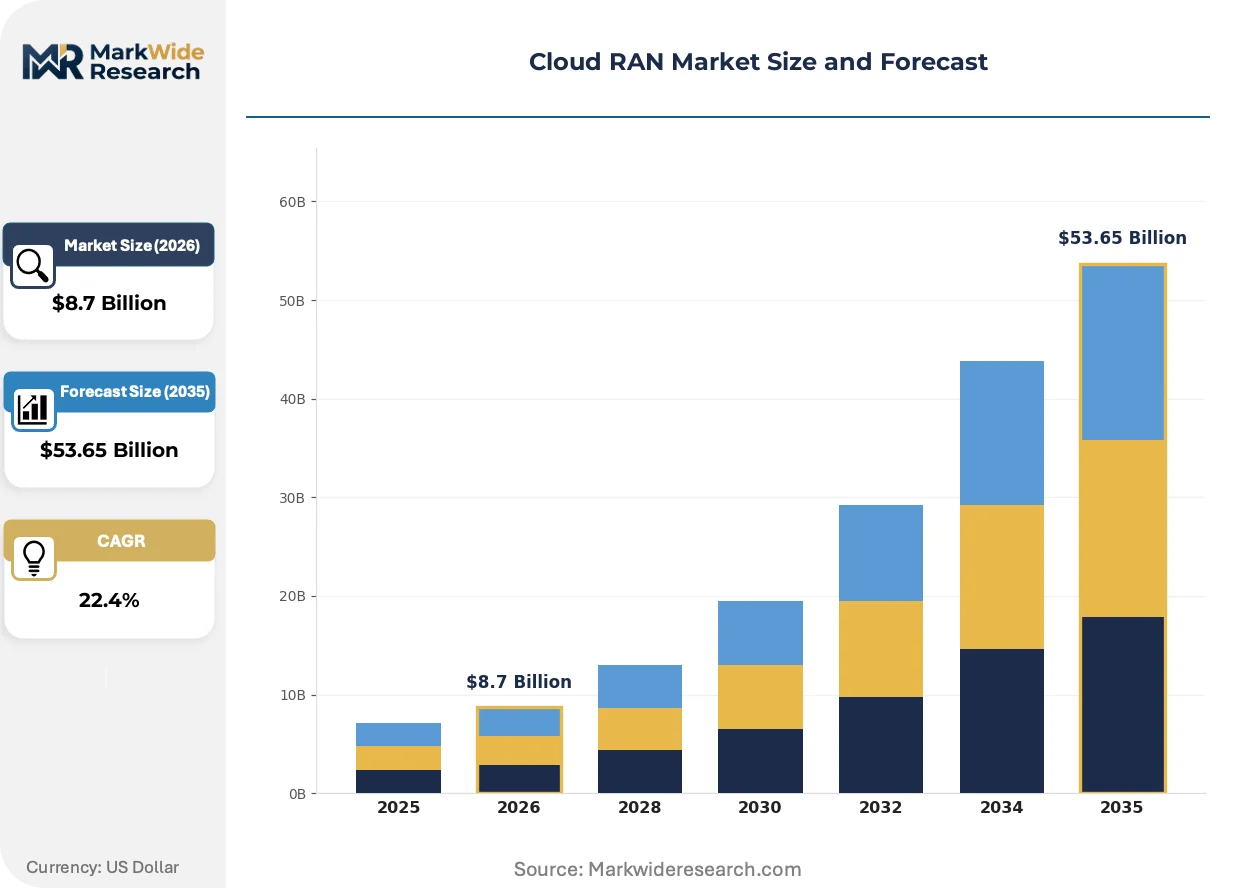
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: V-RAN, Open RAN, Private RAN, Virtualized RAN Technology: 5G, LTE, Wi-Fi, Fiber Optics Deployment Model: On-Premise, Hybrid Cloud, Public Cloud, Multicloud End User: Telecommunications, Enterprises, Government, Managed Service Providers |
| Companies Covered | Ericsson AB, Huawei Technologies Co., Ltd., Nokia Corporation, Samsung Electronics Co., Ltd., ZTE Corporation, NEC Corporation, Intel Corporation, Mavenir Systems, Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud RAN Market Emerging Trajectories
Intelligent automation is penetrating radio access networks at every layer, from self-optimizing beam management to zero-touch provisioning workflows. These capabilities are compressing operational headcount requirements while raising the bar for software-centric competitive differentiation.
Containerized baseband software running on commercial x86 servers is decentralizing processing intelligence toward network edges. Tier-one operators in South Korea are deploying distributed units within 10 kilometers of cell sites to reduce fronthaul latency. This architecture is decentralizing the historical monopoly of centralized baseband hotels in urban cores.
The European Telecommunications Standards Institute's security certification framework for open RAN components is mandating software bill of materials disclosure and vulnerability scanning. Equipment vendors must restructure development pipelines to demonstrate supply chain integrity. German operators are delaying vendor selection decisions pending ETSI certification completion.
Enterprise procurement teams are bypassing traditional systems integrators to contract directly with cloud-native RAN software specialists. Manufacturing conglomerates in Michigan and Texas are issuing requests for proposal that specify Kubernetes-based deployment models. This pattern is most visible in North American private network deployments where IT departments retain capital authority over connectivity infrastructure.
Cloud RAN Market Segmentation
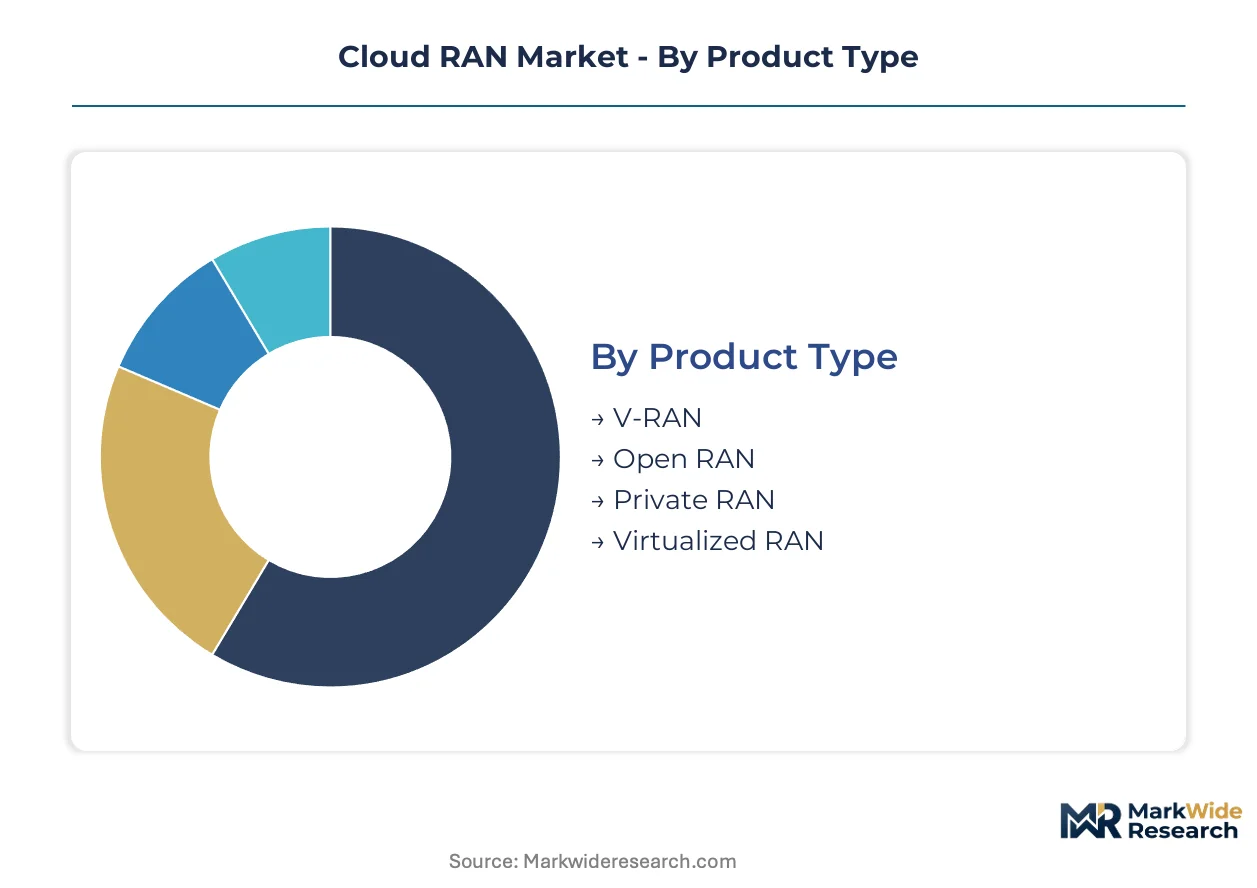
Cloud RAN segmentation reveals distinct procurement patterns across disaggregation levels. Product architecture determines whether operators pursue incremental virtualization or full-stack replacement. Technology choices lock in spectrum strategy for the next decade.
Product Type:
Integration depth varies sharply — standalone deployments run parallel to legacy infrastructure while embedded systems demand full-stack replacement.
- V-RAN:Virtualized RAN employs commercial servers with proprietary software layers from incumbent vendors. Tier-one operators in Germany and South Korea deploy V-RAN within existing Ericsson and Nokia footprints to preserve operational workflows while reducing hardware dependency.
- Open RAN:Disaggregated architecture separates radio units, distributed units, and centralized units through O-RAN Alliance interfaces. The United States leads deployment velocity as Dish Network and Verizon enforce multi-vendor mandates to diversify supplier bases.
- Private RAN:Standalone 5G infrastructure for isolated enterprise campuses bypasses operator core networks entirely. Mining operations in Western Australia and automotive plants in South Carolina procure direct from vendors.
- Virtualized RAN:Containerized baseband functions orchestrated via Kubernetes enable workload portability across edge locations. Hyperscaler partnerships in Dallas and Frankfurt absorb these deployments.
V-RAN leads volumes today; Open RAN is gaining share fastest.
Technology:
Cost tier separation dominates — premium 5G infrastructure commands three to four times the unit economics of mature LTE overlays.
- 5G:New radio specifications with massive MIMO and millimeter-wave capabilities drive baseband processing requirements. South Korean operators deploy 5G Cloud RAN in dense urban corridors to support network slicing for enterprise automation.
- LTE:Legacy 4G virtualization extends equipment lifecycles through software-defined baseband upgrades. Rural operators in the United States prioritize LTE Cloud RAN to meet coverage obligations without full 5G capital commitment.
- Wi-Fi:Unlicensed spectrum integration enables converged access architectures for indoor enterprise environments. Manufacturing campuses in Michigan deploy Wi-Fi-Cloud RAN hybrids for cost-sensitive IoT backhaul.
- Fiber Optics:Fronthaul transport infrastructure using eCPRI and IEEE 1914.3 protocols connects distributed units to centralized processing. Dark fiber availability in Frankfurt and Seoul determines deployment feasibility.
5G commands premium pricing; LTE retains volume leadership in cost-constrained segments.
Deployment Model:
Customer type dictates control boundaries — enterprises demand sovereignty while operators pursue operational flexibility.
- On-Premise:Dedicated infrastructure within operator-owned data centers maintains full control over latency and security. German operators favor on-premise Cloud RAN to satisfy national critical infrastructure protection frameworks.
- Hybrid Cloud:Split processing between private edge and hyperscaler zones balances control with scalability. U.S. operators deploy hybrid models to burst compute loads during peak traffic events.
- Public Cloud:Fully outsourced baseband processing on hyperscaler infrastructure. Early trials concentrate in North American markets with mature edge zone availability.
- Multicloud:Workload portability across multiple cloud providers prevents vendor lock-in. South Korean operators architect multicloud Cloud RAN to arbitrage compute pricing between AWS, Microsoft Azure, and domestic cloud zones.
On-premise dominates current installed base; multicloud exhibits steepest expansion trajectory.
End User:
Application urgency varies — telecommunications infrastructure serves mass connectivity while enterprise and government deployments prioritize isolation.
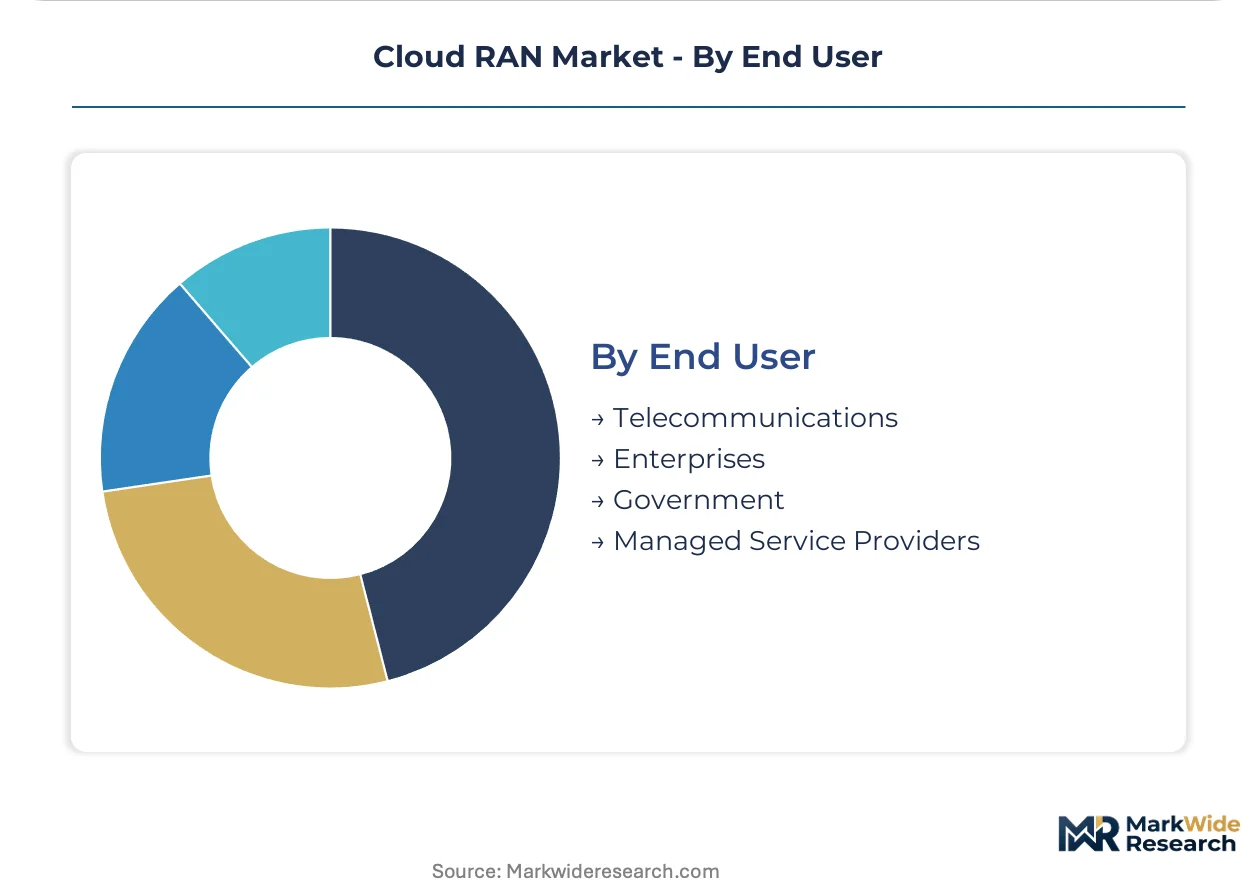
- Telecommunications:Mobile network operators modernize macro networks to reduce opex and enable new revenue streams. Verizon, Deutsche Telekom, and SK Telecom drive procurement volumes through multi-year infrastructure refresh cycles.
- Enterprises:Manufacturing, logistics, and energy firms procure standalone 5G for deterministic connectivity. Automotive facilities in Texas and South Carolina issue RFPs specifying Kubernetes-based deployment models.
- Government:Defense and public safety agencies require sovereign infrastructure with supply chain attestation. U.S. federal mandates for trusted vendor lists reshape procurement eligibility.
- Managed Service Providers:Systems integrators bundle Cloud RAN deployment with ongoing operations. Accenture and Tech Mahindra build practices around multi-vendor integration and lifecycle management.
Telecommunications absorbs majority volumes; enterprise verticals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud RAN infrastructure first achieved commercial scale in South Korea during 2019, where SK Telecom and KT Corporation deployed virtualized baseband processing for nationwide 5G coverage. The architecture has since diffused through spectrum auctions and national broadband strategies across three continents.
United States
Verizon and Dish Network enforce multi-vendor procurement mandates that diversify supplier bases away from single-source dependencies. The FCC's mid-band spectrum auctions and coverage obligations accelerate infrastructure replacement cycles. Dallas-Fort Worth and Phoenix edge zones absorb distributed unit deployments from hyperscaler partnerships.
South Korea
SK Telecom and KT Corporation operate the world's most densely virtualized RAN infrastructure with sub-10-kilometer distributed unit placement. The Ministry of Science and ICT coordinates national 5G strategy with equipment certification timelines. Seoul Capital Area deployments concentrate network slicing capabilities for enterprise automation.
Germany
Deutsche Telekom and Vodafone Germany modernize macro networks under national coverage obligations tied to 3.5 GHz spectrum licenses. ETSI security certification frameworks mandate software bill of materials disclosure from equipment vendors. Bavaria and North Rhine-Westphalia industrial corridors host private RAN installations for automotive manufacturing.
China
China Mobile and China Telecom deploy massive MIMO Cloud RAN across urban corridors with MIIT-coordinated spectrum allocation. The ministry's equipment certification timelines shape vendor market access conditions. Yangtze River Delta manufacturing clusters integrate private 5G for deterministic factory connectivity.
Japan
NTT DOCOMO and KDDI pursue multi-vendor Open RAN architectures with METI-supported interoperability testing programs. The ministry's R&D subsidies accelerate containerized baseband development. Kanto and Kansai metropolitan areas concentrate edge computing convergence with enterprise workload co-location.
Cloud RAN Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software differentiation and integration depth. The vendor base stratifies between integrated incumbents with brownfield anchoring capabilities, cloud-native specialists with multi-vendor orchestration software, and semiconductor firms with programmable logic acceleration. Three archetypes dominate: full-stack integrators, disaggregated software vendors, and silicon acceleration providers. Competitive moves concentrate on strategic partnerships for interoperability certification and vertical integration into FPGA bitstream development.
Among Nordic integrated vendors, Ericsson AB and Nokia Corporation exemplify contrasting approaches to hardware-software separation. Ericsson anchors brownfield deployments with incumbent carriers through operational workflow preservation. Nokia competes via cloud-native software layers extending across multi-vendor radio environments. Samsung Electronics Co., Ltd. occupies a distinct position with mmWave-optimized solutions for greenfield buildouts.
| Leading Market Players |
|---|
| Ericsson AB |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| NEC Corporation |
| Intel Corporation |
| Mavenir Systems |
| Qualcomm Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive FPGA bitstream development within Qualcomm and Marvell anchors supply positions for virtualized distributed units while simultaneously commanding premium pricing power for accelerated baseband processing. Ericsson and Nokia preserve margin structures through proprietary software layers that resist commoditization even as x86 server hardware costs compress.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-stack integrated solutions from disaggregated multi-vendor deployments and bare-metal server configurations. Premium tiers attach to ETSI-certified security compliance and O-RAN Alliance interoperability validation, while economy segments serve rural LTE virtualization projects with minimal customization. Price differentiation stems from certification grade and vertical integration depth. Cost compression in standard-tier vDU hardware is intensifying because foundry capacity constraints at TSMC extend Xilinx and Intel FPGA lead times. Enterprise procurement teams in manufacturing verticals exhibit highest price sensitivity, whereas defense and public safety agencies accept substantial premiums for sovereign supply chain attestation.
Supply Chain Analysis
Multi-supplier qualification mandates from Dish Network and Verizon force diversification across Xilinx, Intel, and emerging Marvell programmable logic alternatives for massive MIMO signal processing. Component sourcing concentrates in Taiwan, the United States, and South Korea for FPGA fabrication, x86 server manufacturing, and mmWave radio unit production respectively. Raw material dependencies span silicon wafers, high-purity copper for fronthaul cabling, and rare earth elements for radio frequency components. Single-source vulnerability persists in 7nm and 5nm foundry capacity. Distribution runs through direct vendor-operator contracts for tier-one deployments and systems integrator channels for private RAN campus installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Cloud RAN infrastructure rests on software-defined value capture displacing hardware-centric procurement patterns. Containerized baseband orchestration enables recurring revenue streams that compound across multi-year operator refresh cycles.
For Market Incumbents: Anticipate displacement pressure from cloud-native specialists by accelerating Kubernetes-native software layer development and securing O-RAN Alliance interoperability certification ahead of competitor plugfest completions. Anchor brownfield relationships through operational workflow preservation while building captive FPGA bitstream capabilities to reduce Xilinx and Intel dependency. Prioritize ETSI security framework pre-certification to capture German operator procurement timelines.
For New Entrants and Emerging Players: Systems integrator partnerships offer the most penetrable channel for bypassing incumbent vendor lock-in at tier-one operators. Target private RAN campus deployments in Western Australian mining and South Carolina automotive facilities where IT departments retain direct capital authority over connectivity infrastructure. Lead with Kubernetes-based deployment models specified in enterprise RFPs to differentiate from legacy vendor architectures.
For Investors and Strategic Acquirers: Roll-up economics work for cloud-native RAN software specialists because operator multi-vendor mandates fragment procurement across dozens of sub-scale vendors lacking lifecycle management capabilities. Viability over the extended horizon hinges on recurring software maintenance revenue displacing upfront equipment margins. Monitor O-RAN Alliance plugfest completion matrices as the inflection signal for multi-vendor deployment confidence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Bitstream Development | Captive acceleration logic reduces dependency on Xilinx and Intel programmable logic supply constraints. |
| O-RAN Alliance Certification | Interoperability validation unlocks Verizon and Dish Network multi-vendor procurement mandates. |
| Private RAN Campus Deployment | Direct enterprise contracts bypass traditional operator channels in Western Australia and South Carolina. |
| Kubernetes Orchestration Integration | Containerized baseband enables workload portability across AWS, Azure, and domestic cloud edge zones. |
| ETSI Security Framework Pre-Certification | Software bill of materials disclosure satisfies German critical infrastructure protection requirements. |
Methodological Framework
Bottom-up mobile network operator deployment modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with RAN engineering directors, hyperscaler edge platform managers, enterprise IT procurement leads, and systems integrator practice heads combined with secondary validation from 3GPP release documentation, O-RAN Alliance specifications, FCC spectrum auction records, and ETSI certification timelines. Triangulation across operator capex disclosures and vendor order intake patterns ensures demand-side and supply-side estimates converge.
Input-output matrices map virtualized distributed unit shipments to centralized unit software licensing values across the projection horizon. Segmentation dimensions modeled include product architecture disaggregation level, radio access technology generation, deployment model sovereignty tier, and end-user vertical. CAGRs derive from logistic diffusion curves fitted to infrastructure replacement cycles and spectrum refarming schedules. Forecast inputs incorporate FPGA foundry capacity utilization, fronthaul fiber availability indices, and enterprise private network RFP flow data.
Revisions become necessary when O-RAN Alliance plugfest completion rates diverge from interoperability certification timelines, or when TSMC foundry allocation shifts disrupt Xilinx and Intel supply commitments. Forecasts reflect documented assumptions regarding operator multi-vendor mandate enforcement and hyperscaler edge zone expansion cadence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
LTE Base Station System Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Managed M2M Services Market
Telecommunications
Iran Telecom Market
Telecommunications
GPON Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Germany Critical Communication Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Singapore MVNO Market