
 Cash Register Machines Market | 2026-2036
Cash Register Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Register Machines Market Analytics
East Asian electronics manufacturing is recalibrating output schedules for point-of-sale hardware. NCR Corporation leverages its North American service network to sustain enterprise retail relationships. Toshiba TEC anchors Japan's domestic hospitality segment with specialized thermal printing systems. Posiflex Technology competes on cost-efficient chassis designs for emerging market small-format stores.
Cash register machines encompass electromechanical and digital transaction recording devices, typically integrating thermal printers, cash drawers, barcode scanners, and payment card readers with processor speeds ranging from 1.2 to 2.4 GHz for real-time sales processing. These systems serve as the central revenue capture node in brick-and-mortar commerce, synchronizing inventory databases with financial ledgers. POS terminals dominate value pools in mature economies where software subscription layers compound hardware margins. Mobile POS captures velocity in street commerce and pop-up retail where legacy countertop units prove impractical. Self-service kiosks concentrate investment from quick-service restaurant chains seeking labor cost containment.
The US FCC governs wireless communication modules embedded in modern terminals, while EU REACH restricts hazardous substances in printed circuit board assemblies. India's BIS certification mandates electrical safety testing for imported POS hardware, creating compliance gates for foreign suppliers. Stakeholders must monitor how central bank digital currency pilots across multiple jurisdictions reshape terminal encryption requirements and payment protocol standards.
Market Dynamics
Quick-service restaurant chains are accelerating self-checkout kiosk deployments to compress labor costs, while central bank digital currency pilots across multiple jurisdictions force terminal manufacturers to redesign encryption architectures before protocol standards stabilize.
Growth Catalysts
- India's Tier-2 Retail Corridors:Small-format stores in secondary Indian cities are replacing mechanical registers with entry-level POS terminals to comply with GST invoice mandates and access formal credit channels.
- EU Payment Services Directive:Terminal security certification requirements under PSD2 are compelling merchant acquirers to refresh hardware estates, creating replacement demand for PCI-compliant devices.
- Thermal Printing Efficiency:Advances in low-power thermal printheads are extending battery life in mobile POS units, enabling street vendors and pop-up retailers to process transactions beyond fixed power infrastructure.
Market Restraints
- Semiconductor Supply Concentration:Processor and wireless module fabrication concentrates in Taiwan and South Korea, exposing terminal manufacturers to geopolitical disruption in advanced node availability.
- Smartphone Substitution:Soft POS applications running on consumer smartphones are capturing micro-merchant transaction volume that previously required dedicated hardware.
- Extended Certification Timelines:India's BIS electrical safety testing adds 4-6 months to import clearance, delaying product launches for foreign suppliers.
Strategic Opportunities
- Central Bank Digital Currency Integration:Pilot programs in China, India, and the European Union are creating first-mover advantage for terminal vendors that embed CBDC-compatible encryption modules ahead of mandate finalization.
- Quick-Service Restaurant Automation:Labor cost pressures are driving franchise operators to deploy self-service kiosks with integrated kitchen display systems, expanding addressable hardware spend per location.
- Subscription Software Layers:Cloud-based inventory and analytics platforms are attaching recurring revenue to hardware deployments in mature economies, compounding lifetime customer value.
Industry Challenges
- Legacy System Integration:Enterprise retailers operate heterogeneous estates of Windows Embedded, Android, and proprietary OS terminals, complicating unified security patch deployment.
- Encryption Architecture Redesign:Anticipated protocol shifts for contactless and CBDC transactions require R&D investment before standards finalize, straining engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Register Machines Market |
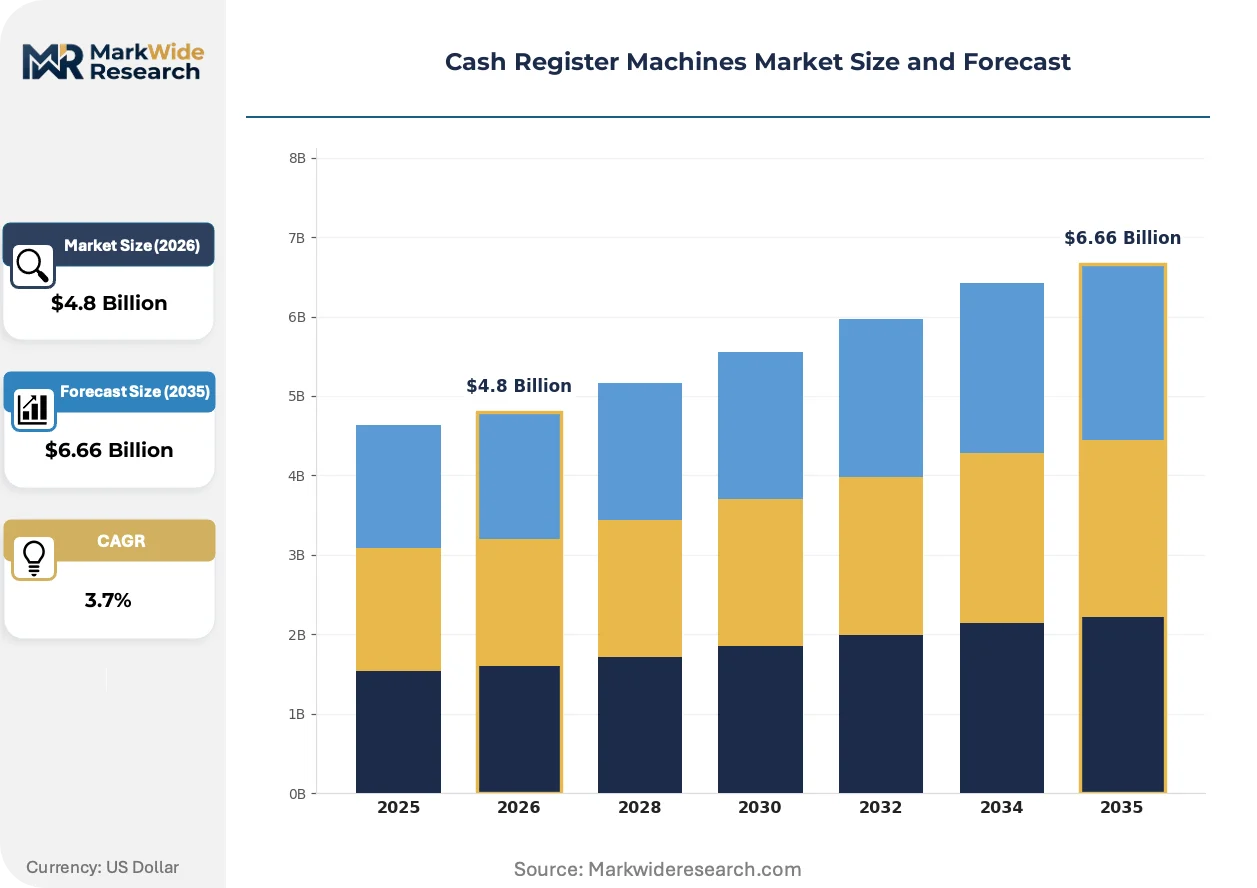
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Cash Registers, POS Terminals, Mobile POS, Self-Service Kiosks Installation: On-Premise, Cloud-Based, Hybrid, Portable End User: Retail Stores, Restaurants, Entertainment Venues, Service Providers Feature: Contactless Payment, Inventory Management, Customer Loyalty Programs, Integration Capabilities |
| Companies Covered | NCR Corporation, Toshiba TEC, Diebold Nixdorf, Casio Computer, Sharp Corporation, Seiko Epson, Fujitsu, Posiflex Technology, SUNMI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Register Machines Market Evolving Landscape
Payment terminal architecture is bifurcating between cloud-native Android platforms and locked-down proprietary systems, with vendor strategy increasingly determined by whether they prioritize developer ecosystem openness or security certification speed.
Edge AI processors are integrating into countertop terminals to enable real-time fraud detection and personalized promotional targeting at the point of transaction. Large-format retailers in the United States are piloting these units to reduce reliance on cloud latency for payment authorization. The technology is integrating payment acceptance with customer analytics, compressing the distinction between transaction hardware and marketing infrastructure.
EU REACH restrictions on hazardous substances in printed circuit board assemblies are forcing manufacturers to reformulate solder compositions and substrate materials. Assembly partners in East Asia are qualifying new supply chains for halogen-free laminates to maintain European market access. Component suppliers serving the medical device sector are extending their REACH-compliant material libraries to capture POS terminal demand.
Merchant acquiring banks are unbundling hardware provisioning from payment processing contracts, shifting procurement decision rights from financial institutions to end retailers. Small-format grocers in India and Southeast Asia are now sourcing terminals directly from distributors rather than through bank-led leasing programs. This channel disintermediation is compressing hardware margins while expanding vendor access to previously captive customer relationships.
Cash Register Machines Market Segmentation
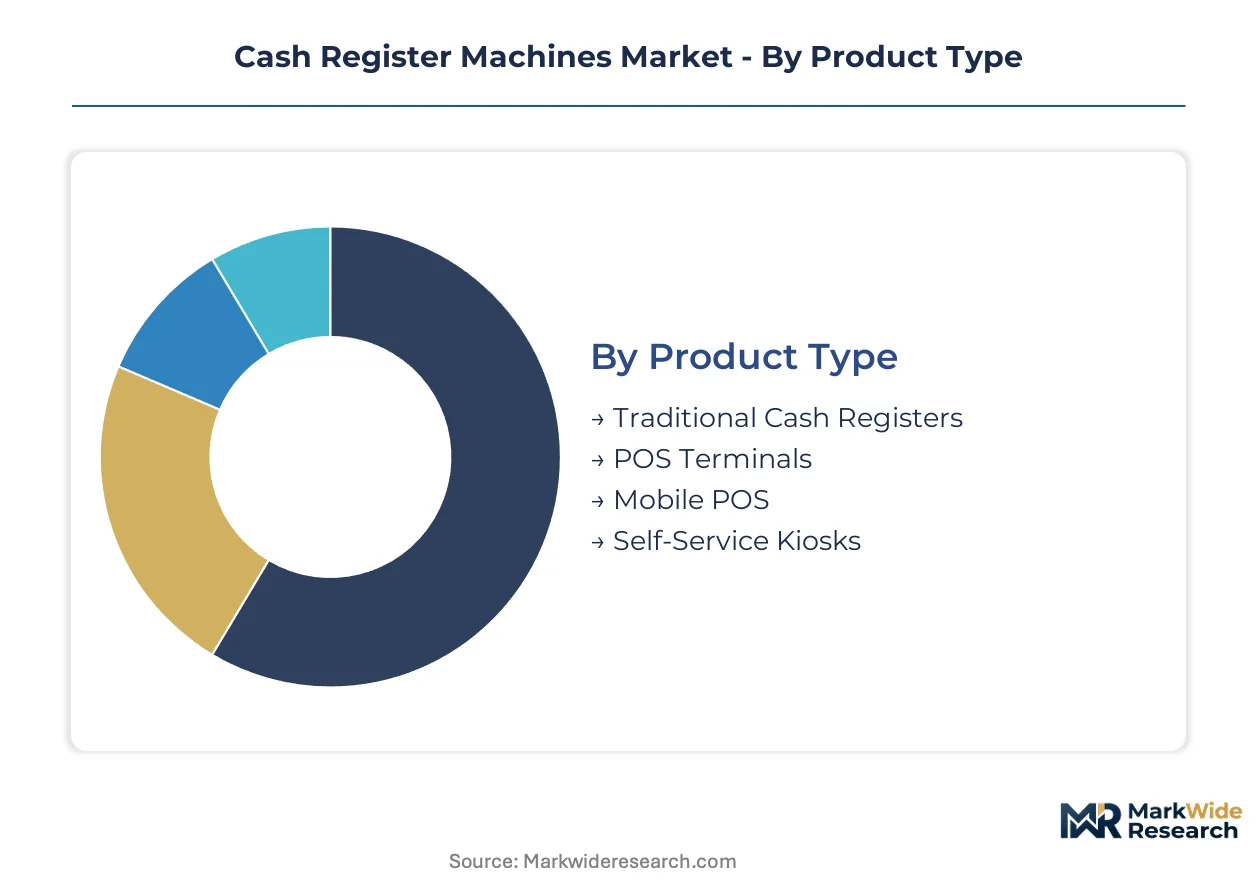
Cash register machine purchasing patterns diverge sharply between cost-sensitive small-format retailers seeking basic compliance functionality and enterprise chains prioritizing software ecosystem integration. Hardware specifications, deployment architectures, and feature bundles must align with distinct operational workflows across food service, retail, and hospitality verticals.
Product Type:
Buyers in this category separate by transaction volume thresholds and countertop space constraints rather than industry vertical alone.
- Traditional Cash Registers:Electromechanical units with basic thermal printing and cash drawer functionality serve India's Tier-2 retail corridors where GST invoice mandates drive replacement of mechanical record-keeping. These devices lack payment card integration, constraining their addressable market to cash-dominant micro-merchants and legacy hospitality operators.
- POS Terminals:Countertop units running Android or proprietary operating systems dominate value pools in mature economies where merchant acquirers bundle hardware with payment processing contracts. PCI-DSS compliance certification requirements under EU PSD2 are accelerating hardware refresh cycles among European retailers.
- Mobile POS:Battery-powered terminals with integrated thermal printers capture street commerce and pop-up retail where fixed infrastructure proves impractical.
- Self-Service Kiosks:Large-format touchscreen units with integrated kitchen display systems concentrate investment from quick-service restaurant chains seeking labor cost containment.
POS Terminals lead volumes today; Self-Service Kiosks are gaining share fastest.
Installation:
Deployment architecture selection tracks buyer IT staffing levels and real-time inventory synchronization requirements.
- On-Premise:Local server-dependent installations persist among enterprise retailers with legacy Windows Embedded terminal estates requiring unified security patch management across heterogeneous OS environments.
- Cloud-Based:Fully managed SaaS deployments attach recurring software subscription revenue to hardware sales, compounding lifetime customer value for vendors serving mature economies. Real-time synchronization with distributed inventory databases drives adoption among multi-location retail chains.
- Hybrid:Edge-processing configurations with cloud backup balance latency-sensitive payment authorization against analytics accessibility.
- Portable:Battery-dependent deployments serve outdoor markets and event commerce where grid connectivity remains intermittent.
On-Premise retains the largest installed base; Cloud-Based deployments are expanding most quickly.
End User:
Vertical-specific workflow patterns dictate hardware form factor and software integration depth.
- Retail Stores:Small-format grocers in India and Southeast Asia are sourcing terminals directly from distributors rather than through bank-led leasing programs, compressing hardware margins while expanding vendor access.
- Restaurants:Quick-service chains are accelerating self-checkout kiosk deployments to compress labor costs, with integrated kitchen display systems expanding addressable hardware spend per location.
- Entertainment Venues:High-throughput environments prioritize contactless payment speed and queue reduction over inventory management functionality.
- Service Providers:Appointment-based businesses emphasize customer loyalty program integration and recurring billing synchronization.
Retail Stores anchor current demand; Restaurants are climbing the fastest.
Feature:
Feature bundling strategies reflect whether buyers prioritize transaction security, operational efficiency, or customer engagement analytics.
- Contactless Payment:NFC and QR code acceptance capabilities are becoming baseline requirements as central bank digital currency pilots across multiple jurisdictions force terminal manufacturers to redesign encryption architectures.
- Inventory Management:Real-time stock synchronization with procurement systems drives adoption among grocery and convenience store operators managing perishable goods.
- Customer Loyalty Programs:Points accumulation and promotional targeting integration appeals to hospitality and service sector operators seeking repeat visit frequency.
- Integration Capabilities:Open API architectures attract developer ecosystems for custom workflow automation, though locked-down proprietary systems retain certification speed advantages.
Contactless Payment features dominate current procurement specifications; Integration Capabilities are showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Tier-2 retail corridors are replacing mechanical registers faster than Germany's merchant acquirers are refreshing PCI-compliant estates, revealing how regulatory mandates and labor cost pressures create divergent replacement cycles across markets.
United States
Quick-service restaurant chains are deploying self-service kiosks with integrated kitchen display systems to compress labor costs. The FCC governs wireless communication modules embedded in modern terminals, creating compliance gates for hardware imports. Large-format retailers in the Pacific Northwest are piloting edge AI processors for real-time fraud detection.
Germany
Merchant acquirers are refreshing hardware estates to meet PCI-DSS compliance certification requirements under EU PSD2. REACH restrictions on hazardous substances in printed circuit board assemblies are forcing manufacturers to reformulate solder compositions. Industrial clusters in Bavaria are qualifying new supply chains for halogen-free laminates.
India
Small-format stores in secondary cities are adopting entry-level POS terminals to comply with GST invoice mandates and access formal credit channels. BIS certification mandates electrical safety testing for imported POS hardware, adding 4-6 months to import clearance. The Delhi-NCR corridor is seeing direct terminal procurement from distributors rather than bank-led leasing.
China
Central bank digital currency pilots are forcing terminal manufacturers to redesign encryption architectures before protocol standards stabilize. MIIT oversees wireless module certification for domestic deployment. Manufacturing clusters in the Pearl River Delta are recalibrating output schedules for point-of-sale hardware exports.
Japan
Toshiba TEC anchors the domestic hospitality segment with specialized thermal printing systems. METI guides industrial standards for payment terminal interoperability. The Kansai region around Osaka maintains concentration in thermal printhead component fabrication for regional supply.
Cash Register Machines Market Competitive Landscape
East Asian producers anchor the hardware fabrication tier; North American service specialists hold enterprise retail relationships through installed base maintenance. The vendor base separates into three strategic archetypes: diversified electronics conglomerates with captive component supply, pure-play POS specialists competing on chassis cost efficiency, and fintech-originated hardware entrants leveraging software subscription attachment. Dominant competitive moves include cloud-native platform migration and direct distribution channel establishment in emerging markets.
Among diversified electronics manufacturers, Toshiba TEC and Fujitsu represent the conglomerate archetype with integrated thermal printing capabilities. NCR Corporation exemplifies the service-network-dependent model for sustaining enterprise relationships. Posiflex Technology occupies a position within the cost-efficient chassis design segment targeting small-format store deployment.
| Leading Market Players |
|---|
| NCR Corporation |
| Toshiba TEC |
| Diebold Nixdorf |
| Casio Computer |
| Sharp Corporation |
| Seiko Epson |
| Fujitsu |
| Posiflex Technology |
| SUNMI |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between PCI-DSS compliant terminals and entry-level GST-mandated devices splits both pricing power and component sourcing strategies across the cash register machines landscape. Premium-tier vendors command hardware-plus-software bundles in European and North American markets while commodity assemblers compete on chassis cost for India's Tier-2 retail corridors.
Pricing Analysis
Distributor margin compression in India's direct-procurement channels is intensifying price competition among entry-level POS terminal suppliers. Three-tier pricing structure across enterprise, mid-market, and micro-merchant levels reflects certification depth and after-sales service bundling rather than raw hardware specifications. Pricing pressure stems from smartphone-based soft POS applications capturing micro-merchant volume previously requiring dedicated terminals. Small-format grocers in Southeast Asia exhibit highest price sensitivity; enterprise quick-service restaurant chains prioritize kitchen display system integration over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing hubs to European and North American markets is amplifying landed cost differentials for thermal printhead components and wireless communication modules. Processor and wireless module fabrication concentrates in Taiwan and South Korea, with halogen-free laminate qualification spreading across Pearl River Delta assembly partners. Raw material dependencies span copper-clad substrates, thermal paper coatings, and lithium-ion battery cells. Single-source vulnerability in advanced semiconductor node availability threatens production continuity. Distribution runs through merchant acquirer-led leasing programs in mature economies and direct distributor relationships in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's GST compliance-driven replacement cycle, where hardware costs sit below European PCI-certification tiers by a factor reflecting regulatory stringency differentials.
For Market Incumbents: Anchor enterprise retail relationships through cloud-native platform migration and predictive maintenance service contracts. Defensive consolidation moves include captive thermal printhead production and direct distribution channel establishment in Delhi-NCR corridors. Threat from fintech-originated hardware entrants with software-first attachment models demands R&D investment in edge AI fraud detection capabilities. For New Entrants and Emerging Players: EU PSD2 terminal security mandates in Germany and France open a window for PCI-compliant device specialists to capture merchant acquirer refresh demand. White-space targets include India's Tier-2 retail corridors bypassing bank-led leasing and quick-service restaurant automation in Southeast Asia. Go-to-market angle emphasizes subscription software layers compounding lifetime customer value beyond hardware margins. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor bases fragment across Android-platform specialists and locked-down proprietary system providers. Long-term viability favors diversified electronics conglomerates with captive component supply and recurring software revenue attachment. Acquisition target archetype: pure-play POS specialists with established BIS certification pathways and distributor relationships in Indian secondary cities. Signal to watch: central bank digital currency protocol finalization triggering encryption architecture redesign investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Android-based open API architectures attract developer ecosystems for custom workflow automation in retail chains. |
| Direct Distribution Channel Establishment | Bypassing merchant acquirer intermediation captures margin compression in India's Tier-2 retail corridors. |
| Edge AI Processor Integration | Real-time fraud detection capabilities reduce cloud latency dependency for large-format United States retailers. |
| REACH-Compliant Material Reformulation | Halogen-free laminate qualification maintains European market access under hazardous substance restrictions. |
| CBDC-Compatible Encryption Module Development | First-mover positioning in China, India, and European Union pilot programs ahead of mandate finalization. |
Research Methodology
Multiple input streams — executive interviews with POS terminal manufacturers, procurement managers at quick-service restaurant chains, distributor principals in Indian Tier-2 cities, and regulatory affairs specialists at merchant acquirers — were reconciled against secondary validation from FCC equipment authorization filings, EU REACH substance restriction updates, BIS certification registries, and customs trade data. Bottom-up unit shipment estimates by product type and installation architecture were cross-referenced with top-down value projections from payment processing contract disclosures.
Historical shipment trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and feature bundling strategy alongside regional regulatory cluster differentiation. CAGRs were derived from slope analysis of replacement cycle timing and technology transition inflection points. Forecast inputs encompass GST compliance mandate enforcement intensity in India, PSD2 hardware refresh timelines in Europe, and central bank digital currency pilot expansion patterns.
Revisions become necessary when semiconductor supply concentration disruptions, smartphone substitution acceleration, or encryption protocol standard shifts materialize outside modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Customer-Facing Technology Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
Self-Checkout System Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Ticket Machine Market
Retail Technology
Global Smart Retail Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Global Kiosk Market
Retail Technology
Digital Kiosk Market
Retail Technology
AR in Retail Market
Retail Technology
Connected Retail Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Retail Sourcing and Procurement Market